Category: malaysia

  • Hot Topics in Malaysia’s 2025 Property Market: What You Need to Know

    Hot Topics in Malaysia’s 2025 Property Market: What You Need to Know

    The Malaysian property market is buzzing with conversations in 2025 as investors, developers, and buyers respond to new trends, policy shifts, and emerging opportunities. From cooling measures to infrastructure-driven growth corridors, the landscape is evolving rapidly. Rising construction costs, industrial and logistics demand, and the spotlight on data centres are just some of the themes shaping discussions today.

    The following are the current hot topics in Malaysia’s property market that every buyer and investor should be aware of:

    1. Residential Market Performance & Price Dynamics

    • House Price Growth Moderating
      Malaysia’s housing price index has been rising, but growth is slowing. For Q4 2024, the national average house price was ~ MYR 483,879, with year-on-year (YoY) growth modest. Global Property Guide
      There were quarter-on-quarter declines in Q4 2024 in many property types (terraced, high-rise, detached, semi-detached) — showing possible short-term corrections or softening. Global Property Guide
    • Regional Price Variations
      • In Penang, average house price remains well above MYR 400,000: about MYR 475,037 in Q4 2024. Global Property Guide
      • Kuala Lumpur is the most expensive, with average ~ MYR 794,467 in Q4 2024. Global Property Guide
      • Other states (e.g. Johor, Selangor) are in between; more affordable housing tends to be further out or in less central locations. Global Property Guide+1
    • Transaction Volume & Supply
      Residential transaction count rose ~4% in 2024 to about 260,516 units; transaction value grew ~5.9 % to ~MYR 106.92 billion. Global Property Guide
      The number of new housing starts rose ~20.6 % in 2024 (for both landed + high-rise) to ~106,236 units; completions rose ~9.7% to ~82,135 units. Global Property Guide
      Also, new planned supply was rising— ~100,461 units in 2024, up ~24.1%. Global Property Guide
    • Overhang / Unsold Stock
      Overhang remains a concern, especially in less premium or lower-value housing. The number of unsold affordable homes has increased. According to Rehda, in 1Q 2025 affordable homes accounted for ~20.7% of unsold residential units. EdgeProp.my
      In Penang, overhang has been showing improvement (decrease in unsold stock) but still persists, especially in certain price bands. Scoop

    2. Developer Sentiment & New Launches

    • Reduced Developer Confidence
      The Rehda survey (1H 2025) shows confidence among developers fell sharply. Only ~19% were optimistic about market prospects mid-2025, down from ~51% six months earlier. EdgeProp.my
      Many developers are being more cautious: ~41% plan new launches in 2H 2025, versus higher rates earlier. Some are not looking to acquire new land because of cost and risk. EdgeProp.my
    • Mismatch of Supply vs Demand (especially “affordable” units)
      A big issue flagged by developers is that many affordable units are being built in locations or at price levels that are not aligned with what local buyers can afford / prefer. Even though lower-priced units tend to have higher demand, their take-up depends heavily on location, amenities, connectivity. EdgeProp.my+1
    • Prime / High-end / Branded Projects Doing Better
      In KL, new launches in “prime” segments are seeing 30-50% take-up rates. Buyers of premium / branded residences (or units in strong locations) are more willing to pay for quality, service, amenities. JLL
      Branded residences are more visible in Penang too (e.g. Marriott Residences at Gurney Drive) reflecting demand (or at least supply) for high-end product. Wikipedia

    3. Commercial, Industrial & Office Sectors

    • Office Vacancy / Demand
      Kuala Lumpur’s office market is recovering: vacancy falling, net absorption positive. For example, KL City saw ~231,392 sq ft net absorption in Q2 2025. Vacancy in KL fell from ~23.6% (Q2 2024) to ~19.2% (Q2 2025). JLL
      Grade A office spaces (those with superior amenities, good location) are better placed; tenants are shifting to better quality buildings. JLL+1
    • Industrial / Logistics / Data Centres Growing Strong
      Demand for industrial space is strong — especially in prime logistics, e-commerce, and supply chain related sectors. In KL / Klang Valley, new supply is being absorbed, and vacancy rates are very low for good quality assets. JLL+1
      The data centre pipeline is large: Malaysia has about 638 MW of capacity completed, ~1,300 MW under construction, and an even larger future pipeline. Investment in this space is seen as strategic. JLL

    4. Government Policy, Taxation & Regulation

    • Budget 2025 Measures
      Budget 2025 includes support for infrastructure, sustainable development, and trying to attract investment in high-value sectors. Real estate/spatial planning tied to ESG / green building is emphasized. JLL
      There’s also focus on more efficient use of land, perhaps more mixed-use zoning or strategic zones. JLL
    • Tax / Fees / Local Levies
      In Penang, for instance, there is proposed quit rent increase (2026) — between ~29% to 200% increase for various land categories. For residential urban land, a hike is less steep; commercial / industrial parcels are more affected. Strata properties may face increases later (from 2027). The Vibes
    • Affordable Housing Policy Pressures
      Developers are required to allocate certain proportions of new developments to affordable housing, but this has led to some unintended consequences: in some cases, these units are in less attractive locations or are priced above what locals can realistically afford. This mismatch leads to slower sales/unsold inventory. EdgeProp.my
    5. Regional Focus: Penang (and Selected States)

    • Overhang Glut Gradually Easing in Penang
      Penang had been among the states with large unsold property inventory. In recent years, unsold units in Penang have reduced (e.g. from ~5,493 in 2021 to ~2,796 in 2024). Scoop
      However, there are still mismatches: properties priced between RM 300,000–500,000 and below are struggling more; high-end (>RM1 million) do better. Location, amenities, connectivity remain critical. Scoop
    • Infrastructure & Transport Matters More
      Projects like the Penang Transport Master Plan (including the Mutiara LRT) are expected to impact property values / demand in areas served. Wikipedia
      Also, improvements like Gurney Bay / Gurney Bay waterfront park are enhancing appeal of coastal / beachfront / high-view precincts in George Town. Wikipedia
    • Local Revenue / Cost Pressures
      The quit rent hike in Penang is being discussed: residents are reacting, especially for commercial / industrial land. This adds to holding costs and might shift developers’ cost calculations. The Vibes
    • High-end / Branded Residences Becoming More Common
      Examples in Penang: Marriott Residences Penang is a new branded residential tower at Gurney Drive. Wikipedia
      The Muze @ PICC is also a large mixed residential project in Bayan Baru with tall towers. Wikipedia

    6. Risks, Headwinds & Constraints

    • Cost Inflation, Construction / Input Costs
      Rising costs for materials, labour shortfalls, logistical challenges (supply chain) are squeezing margins. Developers have less flexibility on pricing vs cost. This trend is being widely reported. EdgeProp.my
    • Financing / Interest Rates
      Borrowing costs, stricter lending criteria, risk of loan rejection are issues especially for buyers of affordable homes. Developer access to finance is also more cautious. EdgeProp.my
    • Unsold Affordable Units Risk
      If many affordable units stay unsold, there is risk of overhang, lower returns for developers, possible depreciation in certain segments. Also risk of price stagnation in non-prime locations. EdgeProp.my+1
    • Regulatory Uncertainty / Local Policy Changes
      Increases in quit rent, possible changes in tax / service tax / sales tax, land use zoning, requirements for affordable housing quotas, etc., create uncertainty. Developers and investors are watching local councils, state governments.
    • Macro / External Risks
      Global supply chain disruptions (especially for industrial / data centre / electronics sectors), geopolitical tensions, input cost volatility, and currency / inflation risk. Also, any downturn in global trade could affect Malaysia’s manufacturing / export sectors (with knock-on effects on property demand, especially for worker housing, industrial real estate).

    7. Opportunities & What to Watch

    • Strategically Located High-Quality / Branded Projects
      Projects with strong amenities, good connectivity (esp. to transit / highways / LRT etc.), high build quality, smart / green features, branded residences — these are likely to command premium pricing and maintain demand.
    • Industrial, Logistics & Data Centres
      Given the global trends (e-commerce, supply chain reshoring, semiconductor investment), Malaysia (especially Penang, Johor, Klang Valley) is seeing growing investor interest in industrial / logistics parks, warehouses, data centre space. These are viewed as relatively defensive assets.
    • Mixed-Use Development & Transit-Oriented Development (TOD)
      Areas around transport infrastructure (LRT, MRT, light rail, major highway nodes) are likely to benefit. Mixed-use developments (residential + retail + office or amenity) that offer a lifestyle component will be attractive.
    • Green / ESG / Sustainability Features
      Buyers / tenants increasingly consider energy efficiency, green certifications, smart home features, environmental impact. Developers incorporating these will have competitive advantage.
    • Government Incentives & Zone Designations
      Investment zones, special economic zones, incentives in Budget 2025, tax breaks (where available), and government infrastructure spending (transport, utilities) are going to influence property hot spots.
    • Price Correction / Buyer Power
      For savvy buyers, there might be opportunities: slower demand in non-prime sectors, more incentive packages by developers, better negotiations (price, furnishing, perks) especially in properties that are not moving quickly.

    Conclusion

    Malaysia’s property market in 2025 is at a turning point, balancing between growth opportunities and structural challenges. While affordability and regulatory changes continue to test both developers and buyers, new catalysts such as data centres, logistics demand, and large-scale infrastructure projects are reshaping the landscape.

    For investors, the key lies in identifying which segments offer long-term resilience and value. For homeowners, understanding how policies, costs, and location trends play out will make all the difference. Ultimately, the hot topics of today are shaping the strategies, risks, and rewards of tomorrow’s property market.

    From the Desk of

    Miichael Yeoh
  • Living in Malaysia: New MM2H Guidelines

    Living in Malaysia: New MM2H Guidelines

    Have you ever thought about living in Malaysia? Imagine waking up to sunshine almost every day, enjoying affordable meals at your favorite kopitiam (coffee shop), and traveling easily around Southeast Asia.

    The Malaysia My Second Home (MM2H) programme makes this dream a reality for many expats, retirees, and families. In 2025, Malaysia has refreshed the programme with clearer rules, especially around property ownership. Let’s dive in and see what this means if you’re planning your new life here.


    🌏 What Makes MM2H Attractive?

    Before looking at property rules, here are the general lifestyle features of the new MM2H:

    ✅ Age requirement: Minimum age lowered to 25 years (previously higher)
    ✅ Bring your family: Spouse, children (up to age 34), and even parents/parents-in-law can join
    ✅ Flexible stay rule: Only 90 days per year in Malaysia (can be split among family members)
    ✅ Visa length: 5, 15, or 20 years depending on tier
    ✅ Healthcare & lifestyle: World-class hospitals, affordable cost of living, English widely spoken

    In short, MM2H is not just about residency — it’s about creating a lifestyle.


    🏡 Property Purchase Rules (The Heart of MM2H 2025)

    Under the new rules, every applicant must purchase a property in Malaysia. Think of it as your anchor — a home that ties you to your new life here.

    By When?

    • You must buy your property within 12 months of receiving your MM2H visa.
    • In Special Economic Zones (like Forest City Johor), the purchase must be completed before visa approval.

    How Long Must You Keep It?

    • A minimum of 10 years (unless upgrading to a higher-value property).
    • This ensures you’re here for the long haul — not just a quick investment flip.

    📊 MM2H Tiers at a Glance

    Here’s a friendly comparison of the three main MM2H tiers:


    🌴 Lifestyle Benefits by Tier

    Silver Tier – Your Starter Lifestyle

    Great for those dipping their toes in Malaysia. Think:

    • A comfortable condo in Penang with sea views 🌊
    • A modern serviced apartment in Kuala Lumpur with pool & gym 🏙️
    • A peaceful home in Ipoh or Melaka for retirement vibes 🕊️

    Gold Tier – Settle & Stay

    For those who want more stability:

    • Long-term residency (15 years) 🗓️
    • Bigger choice of homes in gated communities, townships, or landed properties 🏡
    • Ideal if you want your children to study in Malaysia’s international schools 🎓

    Platinum Tier – The Full Experience

    If you want Malaysia to truly be your second home:

    • 20-year visa security 🔒
    • Right to run businesses or take up employment 💼
    • Luxurious homes in KL’s city center, Penang’s waterfront, or resort-style villas 🌟

    🗺️ Top Lifestyle Spots to Live Under MM2H

    Choosing the right property is also about lifestyle. Here are popular MM2H-friendly locations:

    1. Penang – Food heaven, island lifestyle, thriving expat scene.
    2. Kuala Lumpur – Urban living, international schools, modern healthcare.
    3. Johor Bahru (Forest City & nearby) – Close to Singapore, good for SEZ MM2H.
    4. Langkawi – Duty-free island paradise, perfect for retirees.
    5. Ipoh – Slower pace, heritage charm, lower cost of living.

    💡 Why the Property Requirement Is a Plus

    Some see it as a “rule,” but really, it’s an opportunity:

    • You’re securing a home base in Malaysia.
    • Property values in Malaysia are still affordable compared to neighbors like Singapore.
    • It turns your dream of living here into a tangible commitment.

    Instead of renting endlessly, you’re investing in a lifestyle that grows with you.


    ✨ Final Thoughts

    The updated MM2H is about more than paperwork — it’s about building a life in Malaysia. The property requirement ensures you’re not just passing through, but truly part of the community.

    So if Malaysia has been calling your name, the question is: what kind of life do you want to build here?

    Your condo by the beach, your city apartment, or your family villa could be waiting.

    For enquiries email us at info@miichaelyeoh.com or whatsapp +6012 476 0519.

    From the Desk of Miichael Yeoh
  • 💰 Household Debt in Malaysia – Should We Be Worried?

    💰 Household Debt in Malaysia – Should We Be Worried?

    If you’ve been hearing about household debt in the news and wondering what it means for us Malaysians, here’s the lowdown—without the boring jargon.

    Historical Context

    • 2008 marked a low point in household debt relative to GDP, at 60.4%, showing moderate borrowing during that period. CEIC Data
    • In 2020, debt peaked during the pandemic, reaching a record 93.1% of GDP. CEIC Data
    • As of 2023, debt remained elevated at 84.2% of GDP, up from 80.9% in 2022. CEIC Data

    These figures indicate that while debt declined from its 2020 high, it remains higher than pre-pandemic levels—an ongoing concern.

    The Latest Numbers (2024–2025)

    • In June 2024, household debt stood at around RM1.57 trillion, accounting for 83.8% of GDP. Housing loans comprised 61%, followed by vehicle loans (13.5%) and personal financing (12.4%).
    • By March 2025, debt rose to RM1.65 trillion, or 84.3% of GDP.

    Interestingly, household financial assets were reported to exceed debt by a factor of 2.1, suggesting Malaysians as a whole still have a substantial financial cushion. Additionally, prudent lending practices are maintained, with median debt service ratios (DSR) remaining at 34% for existing loans and 41% for newly approved loans (2024).


    What This Means for Malaysians

    Risks

    1. Sustained High Debt Load
      With debt hovering around 84% of GDP, many households must allocate a significant portion of income toward repayments—possibly limiting spending on essentials.
    2. Rising Youth Bankruptcy
      Between 2020 and early 2025, over 5,272 youths under 34 were declared bankrupt, with nearly 877 cases in 2024 alone. Personal loans accounted for 46.4% of these filings.
    3. Potential for Over-Leveraging via BNPL
      Growing use of “Buy Now, Pay Later” (BNPL) services (e.g., Atome, Grab PayLater) raises concerns, as they operate outside traditional credit tracking like CCRIS and may enable unmonitored debt accumulation.
    4. Lenient Lending to Young Graduates
      Experts warn that easy credit access for fresh graduates—especially via credit cards—could foster poor financial habits without proper income checks or financial literacy.

    Positive Offsets

    1. Healthy Asset Buffer
      Households’ financial assets outpacing their debts by over double implies a buffer that could cushion against economic shocks.
    2. Responsible Lending Frameworks
      With the Responsible Financing guidelines and relatively moderate DSRs, household borrowing still aligns with regulatory safety standards.
    3. Support Services Available
      Agencies like AKPK have helped over 64,000 borrowers settle loans, while nearly 270,000 others continue to receive support through debt management programs.

    Balancing Act: Looking Forward

    • Economic Growth vs. Debt Sustainability
      While household debt has eased somewhat from its pandemic-era peak, it remains elevated, and spikes in personal or BNPL borrowing could strain households—especially lower-income groups.
    • Youth Financial Health
      The rising bankruptcy trend among the young underscores the necessity of stronger financial education and tighter lending criteria for vulnerable demographics.
    • Policy Opportunities
      Strengthening regulation around new lending platforms like BNPL, embedding financial literacy into early education, and enforcing responsible credit access remain vital steps to prevent systemic vulnerabilities.

    In Summary

    Household debt in Malaysia has declined from its 2020 highs but remains elevated, hovering around 84% of GDP in 2024–2025. While household financial assets provide a buffer and regulatory frameworks offer some protection, rising personal debt—especially among youths and via emerging platforms like BNPL—pose risks. Continued focus on financial education, responsible lending policies, and inclusive support systems will be key to ensuring long-term household resilience.

  • Inheritance Law and Joint Ownership Explained

    Inheritance Law and Joint Ownership Explained

    Written by Jocelline Chee from Rightwill | Edited by Miichael Yeoh

    When it comes to inheritance, things can get complicated—and emotional—especially when property is involved. In Malaysia, many people assume that putting property under joint names (like with a spouse or child) will make things smoother when someone passes away. Unfortunately, it’s not always that simple.

    If you’re planning to leave a property behind for your loved ones, it’s important to understand how inheritance laws work in Malaysia and the potential problems that can pop up with joint ownership.


    🏛️ How Inheritance Works in Malaysia

    Inheritance laws in Malaysia depend on your religion:

    • For Muslims, faraid (Islamic inheritance law) applies. It has fixed rules on how the estate is divided among family members.
    • For non-Muslims, the Distribution Act 1958 (amended in 1997) applies. This Act lays out who gets what—based on whether the deceased leaves behind a spouse, children, or parents.

    If someone dies without a will, the law decides how the assets are shared. That’s why it’s so important to have a valid will—it ensures your wishes are followed.

    Example under the Distribution Act:

    If the deceased leaves behind…Parent(s) getSpouse getsChildren get
    Parents, spouse & children1/41/41/2

    🏠 Joint Name Properties – Not As Simple As You Think

    Many Malaysians put properties under joint names thinking it will automatically go to the other person when they pass away. But that’s not always true.

    There are two main types of joint ownership in property law:

    1. Joint Tenancy
      • Comes with the right of survivorship.
      • If one owner dies, the property automatically goes to the surviving owner.
      • This is common among married couples.
    2. Tenancy in Common
      • Each person owns a specific share.
      • When one dies, their share becomes part of their estate and is distributed according to their will or the law.
      • This is more common in Malaysia, even when it’s between family members.

    Here’s the catch: Most joint name properties in Malaysia are actually treated as tenancy in common, unless stated otherwise. That means—even if your name is on the title—the other person’s share doesn’t automatically go to you. It becomes part of their estate and is shared out according to their will or inheritance laws.


    ⚠️ Common Pitfalls to Watch Out For

    1. Unclear Ownership Type
      If it’s not clearly stated whether it’s joint tenancy or tenancy in common, it can lead to confusion—and disputes.
    2. Unequal Contributions
      One person may have paid more, but the property is split 50-50 on paper. This often leads to disagreements among family members.
    3. Family Conflicts
      Things can get messy with children from previous marriages, siblings, or estranged family members. Without clear planning, emotions can take over.
    4. Outdated or No Will
      A will that hasn’t been updated—or worse, no will at all—can cause contradictions and legal battles during probate.

    ✅ What You Should Do

    To protect your assets and your loved ones from future disputes:

    • ✅ Talk to a professional estate planner or lawyer
    • ✅ Make sure your will is valid, updated, and matches your current ownership structure
    • ✅ Clearly state the type of joint ownership on your property documents
    • ✅ Keep your family informed, so there are no surprises later

    Joint ownership may seem like the easy way, but without proper planning, it can create unnecessary complications. A little preparation now can give your family peace of mind in the future.

    From the desk Of

    Miichael Yeoh

    Property Strategist

    Thank you for subscribing!

    Please check your email to confirming your subscription.

  • Malaysia’s Economic Growth and Direct Aid: PM Anwar’s Latest Announcements

    Malaysia’s Economic Growth and Direct Aid: PM Anwar’s Latest Announcements

    Date: July 23, 2025

    By Miichael Yeoh

    Prime Minister Dato’ Seri Anwar Ibrahim delivered a heartfelt address on July 23, 2025, highlighting the nation’s recent economic achievements under the Ekonomi MADANI framework, and more importantly, unveiling new measures aimed at improving the lives of ordinary Malaysians.


    🌍 Key Economic Achievements

    1. Steady GDP Growth:
      • Q1 2025 GDP grew by 4.4%, with Q2 expected to reach 4.5%.
      • Malaysia ranked 23rd globally in the World Competitiveness Index (up 11 spots).
    2. Historic Investments:
      • RM384 billion in approved investments in 2024 – the highest ever.
    3. Stronger Ringgit:
      • The Ringgit has appreciated over 5% against the USD (now at RM4.23), ranking it among Asia’s top five performing currencies.

    💼 Positive Impact on Malaysians

    1. Improved Job Market & Wages

    • Unemployment dropped to 3.0% (lowest in over a decade).
    • RM1,700 minimum wage introduced in Feb 2025.
    • Over 250,000 jobs created between 2023–2024.
    • 153,000 GLC/GLIC employees now earn a living wage of RM3,100/month.

    2. Healthcare & Poverty Eradication

    • More than 4,000 new medical positions to be filled.
    • Nearly 150,000 hardcore poor households lifted out of poverty since 2023.
    • Launch of Sejahtera MADANI, a joint initiative with the corporate sector to continue this effort.

    3. Direct Aid & Support for Cost of Living

    • STR & SARA cash assistance increased to RM13 billion.
    • Additional RM2.9 billion in welfare aid for senior citizens and children in poor families.
    • Paddy farmers and rubber tappers benefit from price floor hikes and higher subsidies.

    🛍️ NEW Immediate Measures for the People

    ✅ 1. RM100 Cash via MyKad for All Adults

    • Effective Aug 31 – Dec 31, 2025, every Malaysian aged 18+ will receive RM100.
    • Usable at over 4,100 stores including Mydin, Lotus, Econsave, and 99Speedmart.
    • Estimated 22 million Malaysians to benefit.
    • Total allocation: RM2 billion (STR & SARA now RM15 billion combined).
    • Households with multiple adults will receive multiple payouts (e.g., 4 adults = RM400 total).

    ✅ 2. Extra Public Holiday

    • Monday, Sept 15, 2025, declared a public holiday to celebrate Malaysia Day and promote family bonding and domestic tourism.

    ✅ 3. Expansion of Jualan Rahmah MADANI

    • Allocation doubled from RM300M to RM600M.
    • More locations and product options across all 600 state constituencies.

    ✅ 4. No Toll Hike for 2025

    • 10 expressways due for toll hikes will remain unchanged.
    • The government will absorb RM500M in compensation to operators.

    ✅ 5. Petrol Subsidy Revamp

    • RON95 petrol price to drop to RM1.99/litre.
    • Subsidy targeting to prevent abuse by foreigners and wealthy individuals.
    • Those who qualify (ordinary Malaysians) will continue to enjoy subsidies, while others will pay market rates.
    • Reflects similar approach to electricity subsidy restructuring, where 85% of users saw lower bills.

    📚 What It Means for Malaysians

    These initiatives signify a direct redistribution of national economic gains back to the people. The government’s approach combines responsible fiscal management, targeted assistance, and long-term poverty alleviation, while avoiding blanket subsidies that benefit the wealthy or foreigners.

    The additional cash support, subsidized essentials, education aid, and income initiatives aim to tackle both immediate cost of living concerns and long-term structural challenges—especially for vulnerable groups.


    🧭 Looking Ahead

    Prime Minister Anwar reaffirmed that the focus remains on rakyat-centric policies, promising further efforts in the upcoming MADANI Budget 2026 to sustainably address the cost of living and economic equality.


    🇲🇾 Bottom Line

    The speech underscores a Malaysia that’s not only recovering economically but also intentionally channelling its growth into meaningful, targeted support for all citizens—especially the B40 and M40 groups. The result is a more inclusive, resilient, and fairer society moving forward.

  • Should You Buy Property in Malaysia Now? Insights 2025

    Should You Buy Property in Malaysia Now? Insights 2025

    Published: July 17, 2025
    By: Miichael Yeoh


    After a strong run in 2023 and 2024, Malaysia’s residential property market is finally taking a breather. While some see this as a red flag, the data paints a more balanced picture—one of resilience and recalibration, not recession.

    So, what exactly is happening in 2025? And should you be worried or ready to buy?

    Let’s break it down.


    📉 Q1 2025: Slower But Still Solid

    Malaysia’s residential property transactions dropped 6.2% in Q1 2025 compared to Q4 2024. That’s the first notable slowdown after nearly two years of consistent growth.

    But here’s the catch: activity levels are still higher than in 2022, which means we’re not seeing a crash—just a cooling-off.

    “The slowdown is expected. It’s the market stabilizing after a hot streak,” said a property analyst from KL.


    📈 Prices Are Still Moving Up

    The national average house price reached RM483,879 in Q1, reflecting a +1.4% year-on-year increase. Areas like Klang Valley, Penang Island, and Johor Bahru continue to dominate in both value and volume.

    Here’s a quick snapshot:

    AreaAvg. Price (Q1 2025)YoY Price Growth
    Klang ValleyRM 550,000+2.1%
    Penang IslandRM 620,000+1.8%
    Johor BahruRM 460,000+1.2%

    🏗️ Developers Stay Selective with New Launches

    With rising construction costs and cautious sentiment, developers are choosing quality over quantity. Most new launches are in well-connected, lifestyle-oriented locations—think smart townships, mixed developments, and green-certified homes.

    Hot-selling projects like Elmina Ridge 2 and Avalon Cybersouth saw near 90% take-up rates, showing buyers are still ready to act—when the product is right.


    🔍 What’s Supporting the Market?

    Despite the slowdown in transactions, several key factors are helping the market stay afloat:

    • Stable interest rates (BNM kept the OPR steady).
    • Low unemployment rate (around 3.3%).
    • Young home-buying population (millennials & Gen Z entering the market).
    • MM2H visa tweaks requiring foreigners to purchase property.

    These are long-term positives that signal stability in the residential segment.


    ⚠️ What Buyers & Investors Should Watch

    While the fundamentals are strong, here are a few caution signs to keep in mind:

    1. Affordability gaps in cities like KL and Penang may limit demand in certain price segments.
    2. Oversupply risks in high-rise areas still exist, especially where demand isn’t organic.
    3. Policy changes—any adjustments to RPGT, stamp duties, or loan rules could shift the playing field fast.

    💡 Final Thoughts

    If you’re a buyer or investor waiting for a market crash—you might be waiting for a while. What we’re seeing now is not the end of growth, but a healthier, more stable market emerging after years of turbulence.

    This could actually be the perfect window to enter—especially if you’re eyeing the right locations, products, and long-term value.

    🗣 “The best time to buy property is when others hesitate—because real opportunity hides in uncertainty.”


    Need help identifying the right property in 2025?
    Join the Property EDU Club — get expert guidance, real-life case studies, and insider access to property deals most investors never see.

    👉 Click here to learn more and join now

  • Exemption and Timeline Changes for E-Invoicing in Malaysia

    Exemption and Timeline Changes for E-Invoicing in Malaysia

    Subscribe to continue reading

    Subscribe to get access to the rest of this post and other subscriber-only content.

  • Revisiting Malaysia’s Home Ownership Campaign: Mid-2025 Update

    Revisiting Malaysia’s Home Ownership Campaign: Mid-2025 Update

    As we come toward the mid of 2025, it’s timely to take a fresh look at the national Home Ownership Campaign (HOC) and related government initiatives aimed at making property ownership more accessible—especially for first-time buyers and middle-income earners.

    Launched originally as a short-term measure, the Home Ownership Campaign 2.0 has been extended until December 31, 2025, in recognition of ongoing housing affordability challenges faced by Malaysians. Alongside this, the Budget 2025 unveiled a series of new incentives designed to further ease the journey to homeownership.


    💡 What’s New in Mid-2025?

    1. Stamp Duty Exemption for First-Time Buyers

    One of the most attractive features of the HOC 2.0 is the 100% stamp duty exemption on properties priced at RM500,000 and below, specifically for first-time homeowners. This incentive significantly reduces the upfront cost of purchasing a home and encourages more young Malaysians to step into the property market.

    2. Housing Credit Guarantee Scheme (SJKP)

    To support those without fixed income documentation—such as gig workers, freelancers, or small business owners—the government continues to offer loan guarantees through SJKP. This allows banks to approve housing loans of up to RM500,000 even for applicants with non-traditional income streams.

    3. Step-Up Financing Scheme

    Also introduced under Budget 2025 is a new Step-Up Financing Scheme, which eases the repayment burden in the early years of a home loan. With government backing of RM5 billion, this scheme helps first-time buyers manage their finances while adjusting to homeownership.


    🧾 Tax Relief for First-Time Buyers

    From January 1, 2025, to December 31, 2027, buyers who sign a Sale and Purchase Agreement (SPA) can claim the following tax reliefs:

    • 🏠 Up to RM7,000/year for properties priced RM500,000 and below
    • 🏠 Up to RM5,000/year for properties priced between RM500,001 and RM750,000

    These tax incentives are designed to provide further savings for eligible homeowners over a 3-year period.


    🏗️ Affordable Housing Developments

    Budget 2025 also channels RM900 million toward affordable housing projects under the People’s Residency Program (PRR) and Rumah Mesra Rakyat (RMR). These programs aim to bridge the housing gap, particularly for B40 and M40 income groups, with strategic developments nationwide.

    In addition, special financial aid—up to RM90,000—is available for those building homes under schemes such as PPRT, including communities in Chinese new villages and fishing settlements.


    🔄 Rent-to-Own Scheme

    For those not ready to buy immediately, the Rent-to-Own (RTO) scheme allows applicants to rent a property for five years with the option to purchase it later. This offers a transitional pathway to homeownership while giving individuals time to strengthen their financial footing.


    ✅ Who’s Eligible?

    To enjoy the full benefits of these initiatives, applicants must typically meet the following conditions:

    • Must be Malaysian citizens aged 18 and above
    • Must be first-time homebuyers
    • Must purchase residential property priced within program thresholds
    • Some schemes may include income eligibility limits

    📊 Summary of Home Ownership Incentives (2025)

    IncentiveDetailsEligibility
    Stamp Duty Exemption100% exemption for properties ≤ RM500,000First-time buyers only
    Tax ReliefRM7,000/year (≤ RM500,000); RM5,000/year (RM500k–RM750k) for 3 yearsSPA signed between 2025–2027
    Housing Credit Guarantee (SJKP)Loan guarantee for properties ≤ RM500,000Buyers with irregular income
    Step-Up Financing SchemeReduced repayments for first 5 yearsFirst-time buyers
    Affordable Housing (PRR/RMR)RM900M allocated for low-income housing projectsB40 & M40 income groups
    Rent-to-Own (RTO) Scheme5-year rental with option to buyMiddle-income buyers

    📈 Potential Savings for a First-Time Homebuyer (Example Scenario)

    ComponentProperty Price: RM480,000Savings
    Stamp Duty (100% Exemption)Normally ~RM9,600RM9,600
    Tax Relief (RM7k/year x3)For 3 yearsRM21,000
    Lower Initial Loan Repaymentvia Step-Up Financing~RM15,000 over 5 years (est.)
    Total Potential Savings~RM45,600

    Note: Values are estimates and may vary by loan package and location.

    🏡 Final Thoughts

    Midway through 2025, Malaysia’s homeownership landscape remains favorable for aspiring buyers, thanks to proactive government support and long-term housing policies. Whether you’re looking to buy your first home, secure financing with flexible terms, or benefit from tax relief, now is an excellent time to take action.

    If you’re considering a property purchase this year, consult with certified property consultants or financial planners to understand how these incentives apply to your personal situation. With the right guidance, 2025 could be the year you unlock the door to your own home.

    From the Desk of

    Miichael Yeoh

  • Discover Malaysia’s RM13.3 Billion in Unclaimed Money

    Discover Malaysia’s RM13.3 Billion in Unclaimed Money

    As of April 2025, the Accountant General’s Department of Malaysia (JANM) has recorded a staggering RM13.3 billion in Unclaimed Money (Wang Tak Dituntut – WTD). However, despite decades of awareness campaigns, only about RM4 billion has been successfully claimed since the initiative began in 1977.

    According to Accountant General Nor Yati Ahmad, many Malaysians are still unaware that they might be entitled to unclaimed funds — or have never checked.

    To improve public awareness, JANM is actively reaching out through community programs and mobile campaigns, especially in rural areas. But the process remains simple for anyone, anywhere, with internet access.


    💡 What Is Unclaimed Money (WTD)?

    Unclaimed Money refers to funds that legally belong to an individual but remain unpaid for over one year. These include:

    • Dormant bank account balances
    • Unclaimed insurance benefits
    • Refunds or overpayments
    • Dividends from investments
    • Uncollected salaries or bonuses

    ✅ How to Check If You Have Unclaimed Money

    Option 1: Online via eGUMIS

    1. Visit https://egumis.anm.gov.my
    2. Register with your NRIC, email, and a password
    3. Log in and enter your IC number to search
    4. If money is found under your name:
      • Upload necessary documents
      • Submit your claim and wait for verification

    Option 2: Visit a JANM Office

    1. Bring required documents (see below)
    2. Complete the WTD Claim Form
    3. Submit in person at any JANM branch

    📄 Documents Required for Claims

    For Personal Claims:

    • Copy of NRIC (front & back)
    • Bank account details (if requesting transfer)
    • Completed claim form (manual method)

    For Claims on Behalf of a Deceased Family Member:

    • Death certificate
    • Proof of relationship (e.g., birth/marriage certificate)
    • Letter of Administration or Grant of Probate
    • Copy of claimant’s NRIC

    Important:
    ✔️ Claims are free of charge
    ✔️ There is no time limit to submit your claim


    📢 Don’t Let Your Money Go Unclaimed

    If you’ve ever opened a bank account, had an insurance policy, received dividends, or worked in Malaysia, there’s a chance you may have unclaimed money waiting. Take just 5 minutes to check — and share this with your family and friends. It could make a real difference!

    From the desk of

    Miichael Yeoh

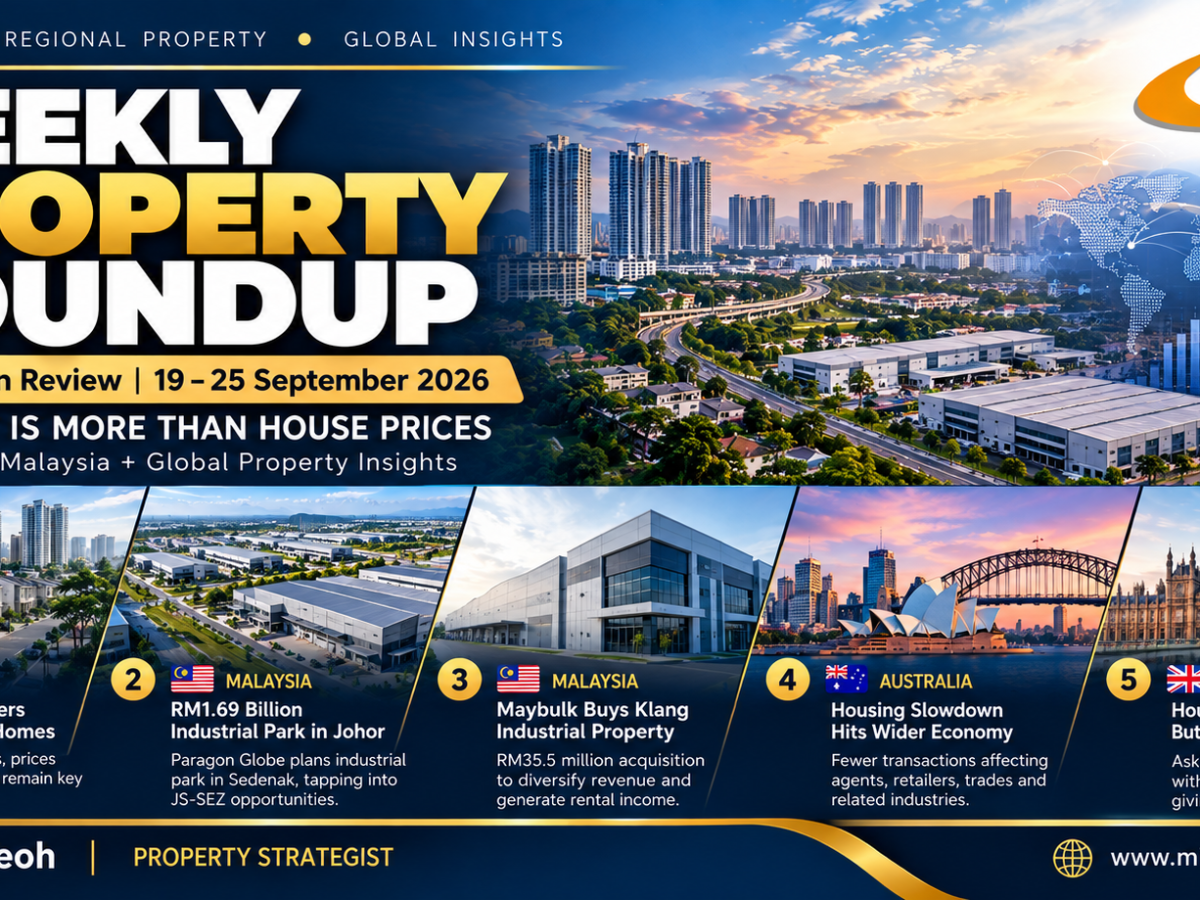
    WEEKLY PROPERTY ROUNDUP

    What really matters in property goes beyond the headline price. This week, Miichael Yeoh looks at five meaningful developments across Malaysia and global markets — and what they could mean for buyers, investors and the wider property market.

    Malaysia Property Market 2026: 33,094 Unsold Homes — Are They Really “For Sale” to Everyone?

    Malaysia’s property market has 33,094 completed residential units worth RM17.78 billion still unsold. But “unsold” does not necessarily mean the same thing for every property. From affordability and financing to Bumiputera quota restrictions and product-market fit, the real story may be more complex. Here’s the Property Discovery System™ perspective.

    WEEKLY PROPERTY ROUNDUP

    Week in Review | 19–25 September 2026 Malaysia • Regional Property • Global Insights The property market is not one market. Different assets, locations and economic forces are moving in very different directions. 🇲🇾 1. Almost 60% of Developers Report Unsold Completed Homes What Happened A new REHDA Property Industry Survey found that 59% of…

  • Malaysia Property Market Sees 8.9% Decline in 1Q2025

    Malaysia Property Market Sees 8.9% Decline in 1Q2025

    Malaysia’s property market experienced a decline in transaction value in the first quarter of 2025 (1Q2025), with a drop of 8.9% to RM51.42 billion, compared to RM56.47 billion in the same period last year, according to the latest report from the National Property Information Centre (Napic).

    Transaction volume also decreased by 6.2% year-on-year, recording 97,772 transactions in 1Q2025, down from 104,194 transactions in 1Q2024, Napic stated in its Friday report.

    Despite the downturn, Valuation and Property Services Department director general Abdul Razak Yusak noted that the property market is expected to remain resilient, buoyed by growth in the construction sector and a rise in newly launched residential units.

    “Industry players and property developers should stay vigilant given the current market dynamics, global economic uncertainties, and evolving external factors,” he said.

    Residential Overhang and New Launches

    Napic reported a significant increase in new residential launches, with 12,498 units introduced in 1Q2025, more than double the 5,585 units launched in 1Q2024. However, the sales performance remained moderate, with a sales rate of 10.8%.

    The residential overhang rose slightly by 1.6% to 23,515 units valued at RM15 billion, a 7.7% increase in value compared to the same quarter last year. Nevertheless, on a quarterly basis, the overhang showed improvement, with volume and value declining by 2.9% and 9.0%, respectively.

    The serviced apartment sector recorded a 6.7% year-on-year reduction in overhang volume, totaling 18,246 units, while the value declined by 6.9% to RM14.61 billion. Abdul Razak noted that Johor Bahru’s serviced apartment market showed signs of recovery, with overhang units reducing by 5.6% in 1Q2025 compared to 4Q2024.

    Shopping complexes also saw a slight improvement in occupancy rates, rising to 79.0% from 78.8% in the previous quarter.

    Meanwhile, the Malaysian House Price Index (MHPI) for 1Q2025 stood at 225.3 points, with the average house price recorded at RM486,070, reflecting a modest annual growth rate of 0.9%.

    Impact on Property Market

    The decline in transaction value and volume in 1Q2025 may signal a period of caution for property investors. With a higher number of unsold units, developers might consider offering more incentives or adjusting pricing strategies to attract buyers. On the other hand, the rise in new launches indicates continued confidence in the market’s long-term potential. Investors are advised to monitor upcoming economic policies and market trends closely, as these factors could significantly influence buyer sentiment and market dynamics in the coming quarters.

    from the desk of

    Miichael Yeoh

    Latest Articles

    WEEKLY PROPERTY ROUNDUP

    The week of September 12-18, 2026, highlighted various property market dynamics, including retail asset repositioning, affordable housing finance, developer health, overseas acquisitions, and interest rate impacts, emphasizing the market’s diverse and evolving nature.

    WEEKLY PROPERTY ROUNDUP

    The week of September 5-11, 2026, highlighted Malaysia’s thriving property market, ongoing demand for sustainable buildings, and the importance of financial stability amid global interest rate fluctuations for buyers and investors.

  • Bank Negara Reduces SRR from 2% to 1%: What Does It Mean and How Will It Affect Us?

    Bank Negara Reduces SRR from 2% to 1%: What Does It Mean and How Will It Affect Us?

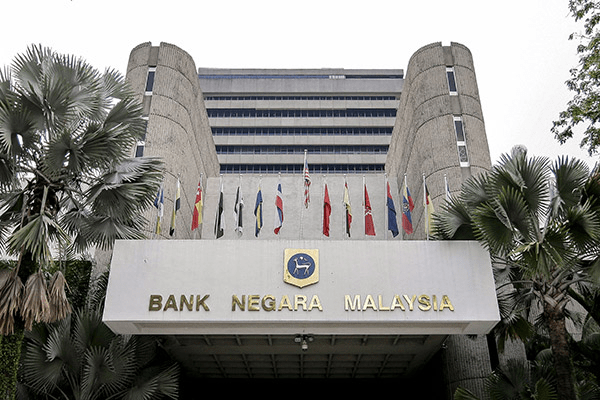
    Bank Negara Malaysia (BNM) has recently announced a reduction in the Statutory Reserve Requirement (SRR) ratio from 2% to 1%. This move is part of a broader strategy to ensure sufficient liquidity in the financial system, supporting economic growth amidst current economic challenges. But what exactly does this mean, and how will it impact individuals and businesses? Let’s break it down.

    Understanding SRR

    The Statutory Reserve Requirement (SRR) is the percentage of a bank’s total deposits that must be kept as reserves with Bank Negara Malaysia. Essentially, it is a tool used by the central bank to control the money supply in the economy. When the SRR is lowered, banks are required to hold less money in reserve, thereby freeing up more funds that can be lent out to businesses and individuals.

    Why Did BNM Reduce the SRR?

    The reduction in the SRR by 1% is expected to release approximately RM19 billion into the banking system, effective from 17 May 2025. This significant injection of liquidity aims to provide banks with more funds for lending and to stimulate economic activities during this period of economic uncertainty.

    The reduction in the SRR from 2% to 1% is aimed at increasing liquidity in the banking system. By allowing banks to keep less money in reserve, more funds become available for lending purposes. This is particularly crucial during periods of economic uncertainty when businesses and individuals may require more financial support. It also helps to reduce the cost of funds for banks, potentially leading to lower interest rates.

    How Does This Impact Us?

    1. More Accessible Loans: With more liquidity in the banking system, banks are more likely to offer loans to businesses and individuals. This can facilitate personal loans, home loans, and business financing, making it easier for borrowers to access funds.
    2. Lower Interest Rates: When banks have more funds to lend, competition among banks may increase, potentially leading to a reduction in lending rates. This is beneficial for borrowers seeking to refinance existing loans or take new loans.
    3. Impact on Savings and Fixed Deposits: On the flip side, while borrowers may benefit from lower interest rates, depositors may see a decrease in interest rates on their savings accounts and fixed deposits as banks adjust their rates to manage the increased liquidity.
    4. Business Expansion and Investment: With more funds available for lending, businesses may find it easier to obtain financing for expansion, investments, or operational costs. This can stimulate economic activity and potentially lead to job creation.

    Potential Risks and Considerations

    While the reduction in SRR can stimulate lending and economic growth, it is essential to consider potential risks. Increased lending could lead to higher household debt if borrowers overextend themselves. Additionally, excessive liquidity could contribute to asset bubbles if funds are channeled into speculative investments.

    Conclusion

    The reduction in SRR from 2% to 1% by Bank Negara Malaysia is a strategic move to increase liquidity and stimulate economic activity. While this creates more lending opportunities and potentially lower interest rates, it is crucial for borrowers to exercise caution and assess their financial capacity before taking on additional debt. Similarly, depositors should monitor interest rate trends to make informed decisions regarding their savings and investments.

    From The Desk of

    Miichael Yeoh

  • EPF Malaysia : Everything You Need to Know

    EPF Malaysia : Everything You Need to Know

    The Employees Provident Fund (EPF), or Kumpulan Wang Simpanan Pekerja (KWSP), plays a crucial role in retirement planning for millions of Malaysians. Whether you’re just starting your career or planning to retire soon, understanding how EPF works is essential to building a secure financial future.

    This updated 2025 guide covers everything you need to know about EPF — from contributions and dividends to withdrawals and the latest changes.


    🔎 What is EPF?

    EPF is a government-managed retirement savings scheme designed to help Malaysian workers in the private and non-pensionable public sectors save consistently during their working years.

    Think of it as a mandatory savings plan, where both the employer and employee contribute a fixed percentage of the employee’s monthly salary. These contributions are then invested in a diversified portfolio — including property, equities, and bonds — to generate long-term returns.

    Members can withdraw their savings upon retirement or under special conditions such as:

    • Buying a home
    • Paying for education
    • Medical emergencies
    • Leaving Malaysia permanently
    • Disability or death

    👥 Who Needs to Contribute to EPF?

    EPF contributions are mandatory for:

    • Private sector employees
    • Non-pensionable government employees
    • Domestic workers (if both parties agree)

    Foreign workers and expatriates can opt out, unless otherwise required by their contract. Meanwhile, self-employed individuals and freelancers can contribute voluntarily to build their own retirement savings.


    💰 2025 EPF Contribution Rates

    Here are the official EPF contribution rates for 2025:

    For Malaysian Employees

    Age GroupEmployerEmployee
    Below 60 (Salary ≤ RM5,000)13%11%
    Below 60 (Salary > RM5,000)12%11%
    60 and above4%0% (optional)

    ➡️ Employees may voluntarily increase their personal contributions above 11%.

    For Foreign Workers (Starting Q4 2025)

    EmployerEmployee
    2%2%

    This new mandate is part of the Employees Provident Fund (Amendment) Bill 2025.


    📈 How EPF Dividends Work

    EPF savings grow over time through annual dividends, typically announced in the first quarter each year. These dividends are based on returns from EPF’s investment activities.

    📊 Recent Dividend Rates:

    • 2023:
      • 5.25% (Conventional)
      • 4.75% (Shariah-compliant)
    • 2024 (Announced March 2025):
      • 6.30% for both Conventional and Shariah accounts

    Dividends are compounded, meaning you earn returns on your contributions and on past years’ dividends.


    🔧 2025 Updates You Should Know

    ✅ Voluntary Contribution Limit Increased

    The annual cap for voluntary contributors is now RM100,000 — great news for freelancers and business owners.

    ✅ i-Akaun App Revamp

    The all-new KWSP i-Akaun app offers powerful features, including:

    • Instant account activation
    • Voluntary contribution options
    • Nominee management
    • Downloadable account statements
    • Retirement calculator
    • i-Sayang (transfer savings to family)
    • Cancel pending withdrawals
    • Access to healthcare/takaful info
    • Tips and official updates from EPF

    🏦 EPF Withdrawal Options

    While EPF is designed for retirement, members may withdraw savings under specific conditions:

    ✅ Withdrawal Categories:

    • Age 50, 55, or 60 (partial/full)
    • Housing (purchase, loan repayments, or settlement)
    • Education (university or college fees for self or children)
    • Medical expenses (critical illness treatments)
    • Leaving Malaysia permanently
    • Death or total permanent disability

    Each type of withdrawal has its own set of requirements and documentation.


    📲 How to Manage Your EPF Account

    Managing your EPF account is simple and convenient with i-Akaun.

    Steps to Access:

    1. Register via the EPF website or self-service kiosk
    2. Download the i-Akaun app
    3. Log in using your IC number and set a password
    4. Activate via SMS or at any EPF branch

    What You Can Do with i-Akaun:

    • Check balances and contribution history
    • Apply for eligible withdrawals
    • Update personal information
    • Manage nominees
    • Access statements and tools

    EPF self-service kiosks are also available nationwide for walk-in services.


    ❌ Common Myths About EPF – Busted!

    🔸 “I can’t change my EPF nominee.”
    ✅ You can update it anytime via the app or at a branch.

    🔸 “EPF is only useful at retirement.”
    ✅ You can make partial withdrawals for housing, education, or health.

    🔸 “EPF dividends are fixed.”
    ✅ They fluctuate based on EPF’s investment performance.

    🔸 “I don’t need to check my EPF.”
    ✅ Mistakes, outdated information, or missing nominees can cause serious issues later.


    ❓ Frequently Asked Questions (FAQs)

    Q: Can I contribute more than 11%?
    Yes, you can increase your contribution or make additional voluntary payments.

    Q: What happens to my EPF when I die?
    It will go to your nominated beneficiary. If no nominee is listed, the funds will go through estate administration.

    Q: Can I switch to a Shariah-compliant EPF account?
    Yes, but only during specific switching windows announced by EPF.

    Q: Is my EPF money safe?
    Yes. EPF is backed by the Malaysian government and is one of the most secure long-term savings tools available.

    Why EPF Is Important

    ✅ Secure Retirement
    EPF ensures Malaysians have savings to support themselves after leaving the workforce, reducing reliance on family or government aid.

    ✅ Steady Growth Through Dividends
    Your money grows each year via compounding dividends, making it one of the most stable long-term savings tools.

    ✅ Government Protection
    EPF is backed by the Malaysian government, making it a low-risk savings platform.

    ✅ Financial Flexibility
    Members can access their savings before retirement for housing, education, or medical needs — giving them a financial buffer during key life events.

    ✅ Easy Account Management
    With tools like the upgraded i-Akaun app, managing, tracking, and planning for your future has never been easier.


    ✅ Final Thoughts

    EPF is not just a retirement fund — it’s a powerful financial safety net that helps Malaysians prepare for the future. By understanding your contributions, making informed withdrawal decisions, and using the i-Akaun app, you can take control of your financial destiny.

    Plan smart. Save smart. Retire strong.

    From the Desk of

    Miichael Yeoh