Author: miichaelyeoh

  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    10–16 October 2026

    LOOK BEYOND THE PRICE

    Five stories. Three Malaysian developments. Two international markets. One objective: helping buyers and investors make better-informed property decisions.

    🇲🇾 MALAYSIA PROPERTY MARKET

    STORY 1 — Why Are Malaysian Property Developers Becoming More Cautious?
    What Happened?

    A property industry survey reported by The Edge Malaysia on 15 October revealed that 63% of surveyed developers had no plans to launch residential projects in the second half of 2026.

    The survey by the Real Estate and Housing Developers’ Association Malaysia (REHDA) covered 181 respondents in Peninsular Malaysia.

    Key findings included:

    • 114 of 181 respondents had no plans for residential launches in the second half of 2026.
    • The remaining respondents planned to launch 18,696 units.
    • 77% of respondents reported financing difficulties during the first half of 2026.
    • 59% of respondents with relevant data reported unsold completed residential units as at 30 June 2026.
    • Among respondents who reported unsold completed units, 32% said some of their stock had remained unsold for more than three years.

    Developers cited market conditions, approval delays and existing unsold inventory as reasons for their cautious approach. The Edge Malaysia

    Source: The Edge Malaysia — REHDA property industry survey, 15 October 2026

    Why It Matters

    This is an important signal for Malaysia’s property market.

    A high number of new launches does not automatically mean a healthy market. What matters is whether homes are priced appropriately, buyers can obtain financing and completed units find genuine occupants.

    The financing figures are particularly noteworthy. Demand for housing may exist, but prospective buyers still need to qualify for loans and manage their financial commitments.

    Developers must also balance construction costs against what their target customers can realistically afford.

    Miichael’s Review

    I see this as a reminder that property development must follow real demand, not simply market excitement.

    When developers become more cautious, buyers should look beyond promotional campaigns and ask some practical questions:

    1. How many comparable properties are already available?
    2. Are existing developments attracting genuine buyers?
    3. Are asking prices supported by recent transactions?
    4. Can the intended buyers realistically obtain financing?
    5. Is the development designed for actual occupants or mainly for investors hoping to resell?

    The survey also suggests that different property categories are performing differently. Buyers should therefore avoid treating the entire Malaysian market as one uniform market.

    My view: A more selective market can reward careful research. Buyers need to distinguish between a property that is attractively marketed and one that is genuinely well positioned.


    STORY 2 — Malaysia Reports 1,726 Revived Housing Projects: What Does This Mean for Buyers?

    What Happened?

    On 14 October, EdgeProp Malaysia reported on the Housing and Local Government Ministry’s update that 1,726 sick or abandoned private housing projects had been revived since 2023.

    The projects involved approximately:

    • 199,643 housing units
    • RM158 billion in gross development value
    • 1,542 sick projects completed with Certificates of Completion and Compliance
    • 147 projects restored to smooth status
    • 37 abandoned projects resolved through physical completion or arrangements benefiting buyers

    The ministry also reported that, as at 31 August 2026, Kuala Lumpur still had seven projects classified as abandoned and another 12 classified as sick.

    The government has set a target of eliminating sick and abandoned housing projects by 2030. EdgeProp

    Source: EdgeProp Malaysia — Housing project rehabilitation update, 14 October 2026

    Why It Matters

    A stalled housing project can create serious financial and emotional difficulties for buyers.

    They may have paid deposits and progressive payments, committed to housing loans and continued paying rent while waiting for their homes.

    The reported rehabilitation figures are encouraging, but one distinction matters: a project being revived does not necessarily mean every unit has been completed and handed over.

    The different outcomes must be examined individually.

    For prospective buyers, this is also a reminder to assess the delivery record of a developer and the actual status of a project before committing.

    Miichael’s Review

    I welcome efforts to protect homebuyers and resolve problematic developments.

    However, I would assess a project’s progress using evidence rather than announcements alone.

    Before buying into an ongoing development, I would want to understand:

    • The developer’s financial and delivery track record.
    • The project’s construction progress.
    • Whether the required approvals and legal arrangements are in place.
    • Whether there are known disputes or rehabilitation issues.
    • The expected completion date and the evidence supporting it.

    For buyers already affected by a stalled project, the available rehabilitation route and legal position are particularly important.

    My view: The real measure of success is not simply how many projects have been declared revived. It is how many affected buyers ultimately receive the homes or appropriate resolutions they were promised.


    STORY 3 — IOI Properties Advances Its Proposed RM7.66 Billion REIT Listing

    What Happened?

    IOI Properties Group Berhad advanced its proposed Malaysian real estate investment trust (REIT) listing after signing an underwriting agreement with six financial institutions.

    According to EdgeProp Malaysia on 12 October:

    • The proposed REIT has nine initial assets.
    • The portfolio was valued at approximately RM7.66 billion as at 31 May 2026.
    • The proposed offering could involve up to 2.2 billion units.
    • The underwriting agreement covers 165 million offer units, subject to the offering’s allocation provisions.
    • The prospectus was targeted for the fourth quarter of 2026, with listing targeted by year-end.

    The initial portfolio includes IOI City Mall, six hotels and two office properties.

    These are proposed listing arrangements; the announcement did not mean the IPO had already been completed. EdgeProp

    Source: EdgeProp Malaysia — IOI Properties advances proposed REIT IPO, 12 October 2026

    Why It Matters

    A REIT provides a way for investors to gain exposure to income-generating property through a listed investment vehicle rather than purchasing an entire property themselves.

    For the property sector, a listing can provide another route for capital management and potentially broaden investor participation.

    However, a large property portfolio does not automatically make a REIT an attractive investment.

    Investors still need to examine rental income, occupancy, financing costs, debt levels, asset valuations and the proposed distribution policy.

    Miichael’s Review

    This is worth watching because it connects property ownership with capital markets.

    For individual investors, a REIT may offer a different way to participate in commercial property, hotels and retail assets without directly managing a building.

    But the decision should be based on the investment’s fundamentals.

    I would look carefully at:

    1. The quality and location of the underlying assets.
    2. The sustainability of rental income.
    3. Financing costs and gearing.
    4. The proposed distribution yield and how it is calculated.
    5. Whether the offering valuation is reasonable relative to comparable investments.

    My view: The important question is not merely how much the portfolio is worth. It is whether its assets can generate sustainable income at a valuation that makes sense for investors.


    🌏 INTERNATIONAL PROPERTY WATCH

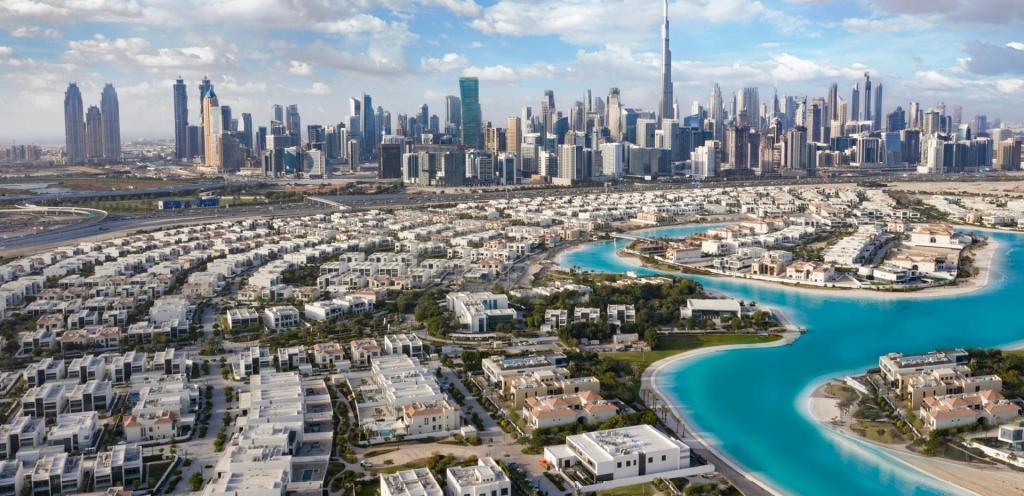
    🇦🇪 STORY 4 — Dubai Buyers Shift Towards Completed Homes as the Market Becomes More Selective
    What Happened?

    A third-quarter 2026 residential market report from betterhomes, reported by Khaleej Times on 15 October, showed a shift towards completed homes in Dubai.

    Key findings included:

    • Sales of ready residential properties rose 16% quarter-on-quarter.
    • Secondary-market transactions reached 10,055, with a total value of Dh27.1 billion.
    • Secondary-market transactions accounted for 29% of total residential sales, up from 24% in the second quarter.
    • Overall residential sales totalled 34,615 transactions during the quarter, broadly unchanged from the previous quarter.
    • Median apartment prices declined 2.4% between June and September, while villa and townhouse prices fell 2.3%.

    Despite the quarterly price declines, prices remained higher than a year earlier. Rental enquiries also rose sharply, although median rents eased in several market segments. Khaleej Times

    Source: Khaleej Times — Dubai ready-home sales jump 16%, 15 October 2026

    Why It Matters

    The figures suggest that buyers are becoming more selective about the type of property they purchase.

    Completed homes offer advantages that off-plan properties cannot immediately provide: buyers can inspect the actual unit, assess the surrounding community and potentially receive rental income sooner.

    However, the reported shift does not mean off-plan properties have become universally unattractive. Different buyers have different financial circumstances, objectives and risk tolerances.

    The decline in quarterly prices also highlights the importance of comparing actual transactions rather than relying exclusively on advertised prices.

    Miichael’s Review

    This is an interesting development for property investors.

    A completed property may provide greater visibility into its condition, rental demand and surrounding environment. An off-plan property may offer different advantages, but it also requires buyers to assess delivery risk and future market conditions.

    I would compare both options using the same criteria:

    • Total acquisition cost.
    • Expected rental income.
    • Maintenance and other holding expenses.
    • Financing commitments.
    • Comparable transaction prices.
    • Exit options if market conditions change.

    My view: A completed property is not automatically a better investment, just as an off-plan property is not automatically a better bargain. The right choice depends on the numbers, the risks and the buyer’s objectives.


    🇨🇦 STORY 5 — Canadian Home Sales Fall Again as Mortgage Rates Weigh on Buyers

    What Happened?

    On 16 October, Reuters reported that Canadian home sales declined again in September as higher mortgage rates and expectations of a possible interest-rate increase weighed on market activity.

    According to the Canadian Real Estate Association (CREA):

    • National home sales fell 2.3% month-on-month in September, following a 0.7% decline in August.
    • Sales were down 7.7% year-on-year on an unadjusted basis.
    • The Home Price Index declined 0.4% month-on-month and 3.4% year-on-year.
    • New property listings fell 1.8% from August.
    • The seasonally adjusted sales-to-new-listings ratio slipped to 48.8%, below its long-term average of 54.7%.

    At the time of the report, financial markets were pricing in the possibility of a 25-basis-point Bank of Canada rate increase in December. This was a market expectation, not a confirmed policy decision. Reuters

    Source: Reuters — Canadian home sales fall in September as mortgage rates increase, 16 October 2026

    Why It Matters

    The Canadian market demonstrates how financing conditions can affect property transactions.

    Even when prospective buyers want to purchase homes, higher mortgage costs can reduce borrowing capacity or make buyers more cautious about committing.

    A slower market may give some buyers more time to negotiate. However, it does not automatically mean that every property is attractively priced.

    Local conditions also matter: national figures can conceal significant differences between cities, neighbourhoods and property types.

    Miichael’s Review

    For me, the main lesson is the relationship between financing and affordability.

    When interest rates rise, a buyer may qualify for a smaller loan or face a higher monthly repayment. That can change which properties are financially sensible.

    Before committing, I would ask:

    1. Can I afford the repayments if borrowing costs increase?
    2. Does the property remain affordable after taxes, insurance and maintenance?
    3. Is the asking price supported by recent comparable transactions?
    4. Can I sustain ownership if resale takes longer than expected?
    5. Am I buying because the property suits my needs, or because I expect prices to rise?

    My view: A property purchase should be financially sustainable even when market conditions become less favourable. Buyers who understand their financing limits are better placed to make measured decisions.


    WORTH WATCHING

    Here are five developments I would monitor over the coming weeks.

    AreaWhat to watchWhy it matters
    MalaysiaDeveloper launch plans and sales performanceShows whether supply is responding to genuine demand.
    MalaysiaRehabilitation of sick and abandoned housing projectsBuyers need evidence of actual progress and resolution.
    MalaysiaIOI Properties’ proposed REIT prospectusProvides details for evaluating the portfolio, pricing and distribution policy.
    UAECompleted-home prices, rents and transaction activityHelps investors assess whether market conditions support their objectives.
    CanadaMortgage rates, sales activity and home-price trendsProvides an indication of how financing conditions affect affordability and demand.

    MY TAKEAWAY THIS WEEK

    This week’s property news reinforces a principle that applies across markets:

    Property decisions should be based on fundamentals, not headlines.

    In Malaysia, developers are becoming more cautious, housing-project rehabilitation remains important, and a proposed REIT listing offers another way to participate in property investment.

    In Dubai, buyers are showing greater interest in completed homes, while prices and rents are becoming more competitive in some segments.

    In Canada, higher borrowing costs are weighing on transactions.

    These markets have different conditions, but the underlying questions are similar.

    • Is the property priced reasonably?
    • Is there genuine demand?
    • Can the buyer afford to own it comfortably?
    • Does the investment generate sustainable income?
    • Are the risks manageable if the market changes?

    A property can look attractive on paper but still be unsuitable for a particular buyer.

    Look beyond the price. Understand the fundamentals before making the decision.

    Miichael Yeoh
    PROPERTY STRATEGIST
    miichaelyeoh.com
  • New Launch vs Subsale: Which Property Should You Buy?

    New Launch vs Subsale: Which Property Should You Buy?

    Written by: Miichael Yeoh

    A new property feels safer. An existing property feels more predictable.

    But neither statement is necessarily true.

    A new launch may offer attractive incentives, modern facilities and a fresh building. A subsale property may allow you to inspect the actual unit, understand the surrounding neighbourhood and investigate existing rental demand.

    So, which should you buy?

    The answer depends on what you’re paying, what you’re getting, what risks you’re taking and what you expect the property to deliver.

    Let’s look beyond the showroom and examine the decision properly.

    1. The Malaysian Property Market Is Giving Buyers a Reason to Be Selective

    Malaysia’s property market remained active in the first half of 2026.

    The first-half property market report recorded 187,320 property transactions worth RM105.12 billion. At the same time, 33,094 completed residential units remained unsold, valued at approximately RM17.78 billion.

    Developers also launched 27,832 residential units during H1 2026, with reported sales performance of 16.6%.

    These figures don’t mean new launches are bad or that subsale properties are automatically better.

    They tell us something more useful.

    Buyers should not assume that a new launch is a good purchase simply because a developer has launched it, or that an existing property is good value simply because someone is reselling it.

    Every property needs to be evaluated on its own merits.

    And that brings us to the first important difference.

    2. New Launch vs Subsale: What Are You Actually Buying?

    Let’s start with the basic distinction.

    A new-launch property is generally purchased directly from a developer, often before construction is completed.

    A subsale property is an existing property purchased from its current owner.

    That difference affects much more than the age of the building.

    Property Condition

    New launch: The property may still be under construction, so the finished quality cannot yet be fully assessed.

    Subsale: You can inspect the actual unit and building before making your decision.

    Pricing

    New launch: The price is set by the developer, with incentives or rebates subject to the terms offered.

    Subsale: The price may be negotiable, depending on the seller and comparable market transactions.

    Rental Income

    New launch: Rental income generally begins only after completion, handover and preparation for tenants.

    Subsale: Rental income may begin sooner if the property is ready and suitable for tenants.

    Construction Risk

    New launch: An uncompleted project carries delivery and construction-related risks.

    Subsale: A completed property avoids the risk of waiting for construction completion, although other risks remain.

    Defects and Renovation

    New launch: You may need to furnish the unit and address defects identified at handover.

    Subsale: You may need to repair existing defects, renovate or replace ageing fittings.

    Facilities and Management

    New launch: The long-term quality of building management has yet to be demonstrated.

    Subsale: You can assess the existing facilities, maintenance and management standards.

    Rental Demand

    New launch: Future rental demand must be estimated using market evidence and competing supply.

    Subsale: Existing rental listings and tenancy evidence may help you assess demand, although future conditions can change.

    Main Uncertainty

    New launch: Completion, final quality, future supply and market conditions.

    Subsale: Hidden defects, maintenance costs, building condition and future resale demand.

    Neither option wins every category.

    The mistake is choosing based on the benefits of one option while ignoring its disadvantages.

    3. Is a New Launch Cheaper Than a Subsale?

    This is where many buyers need to slow down.

    Imagine two condominiums in a similar location.

    Property A: New launch

    • Developer’s selling price: RM600,000
    • Advertised rebate: 8%
    • Indicative price after the rebate: RM552,000

    Property B: Subsale

    • Seller’s asking price: RM530,000
    • Negotiated purchase price: RM515,000

    At first glance, the subsale property appears cheaper.

    But are we comparing the same thing?

    What is the actual transaction price of comparable units?

    Does the new launch include furnishing, parking or other items that would otherwise cost extra?

    Does the subsale unit require RM30,000 in renovation?

    Are the maintenance fees comparable?

    Are both properties equally attractive to future tenants?

    What are the legal, financing and other acquisition costs applicable to each transaction?

    Until you answer these questions, you don’t know which property offers better value.

    Look Beyond the Advertised Price

    Developer incentives can reduce the buyer’s effective cost, but their value depends on the actual terms and what is included.

    Similarly, a subsale seller’s asking price may not reflect the final negotiated price.

    Compare the complete acquisition cost rather than relying on the headline figure.

    And remember:

    A lower purchase price does not automatically mean a better investment.

    4. The Hidden Difference: When Can the Property Start Working for You?

    For investors, this may be one of the most important differences.

    Suppose you purchase a new-launch condominium that will take several years to complete.

    During that period, you may have construction-stage financing payments, depending on the loan structure. You also have to wait until the property is completed, handed over and ready before rental income can begin.

    Now consider a completed subsale condominium.

    If the unit is in good condition and the rental market is established, you may be able to rent it out after completing the purchase and preparing the unit.

    The difference is time.

    Let’s Use a Simple Illustration

    Assume the subsale property can generate RM2,000 per month in rent once it is ready and occupied.

    If the new launch takes three years to complete, the theoretical gross rental income forgone over those 36 months is:

    RM2,000 × 36 months = RM72,000.

    That is a significant amount.

    But don’t misunderstand the calculation.

    RM72,000 is not a guaranteed loss or a complete comparison of the two investments. It is an illustration of potential gross rental income over that period, assuming the subsale could have been rented continuously.

    Actual results would depend on vacancy, expenses, financing, tenant demand and the timing of rental readiness.

    The new launch might also appreciate during construction. The subsale might need substantial renovation or suffer from weak tenant demand.

    The lesson is not that subsale always wins. It’s that time has a financial value, and investors should calculate it.

    5. Can You Trust the Rental Demand for a New Launch?

    This is a question I would ask before purchasing either type of investment property.

    A developer might describe a project as ideal for young professionals, expatriates or students.

    That may be a reasonable target market.

    But a target market is not proof of rental demand.

    Before buying, investigate:

    • Who actually works or studies nearby?
    • What rents are comparable units achieving?
    • How many similar units are already available?
    • How long do comparable properties typically take to find tenants?
    • What facilities and transport options matter to the intended tenants?
    • How many competing developments are expected to be completed?
    • What will make your property more attractive than the alternatives?

    For a completed subsale unit, you may be able to examine existing rental listings, speak to property managers and investigate actual tenancy evidence.

    For an uncompleted new launch, you will have to make more assumptions about future conditions.

    That doesn’t make the new launch a poor investment.

    It simply means the further you are from observable evidence, the more carefully you need to test your assumptions.

    6. What About Building Quality and Defects?

    One advantage of buying a new residential property from a developer is that qualifying purchases under prescribed housing development agreements have statutory protections, including a defect liability period.

    For standard Schedule G and Schedule H agreements, the defect liability period is generally 24 months from vacant possession, subject to the applicable agreement and legal provisions.

    However, a new building is not necessarily a defect-free building.

    You still need to inspect the unit when it is handed over, document defects and follow the proper procedures for reporting them.

    A subsale property presents a different situation.

    You can inspect the actual unit before purchasing, but you may inherit problems such as:

    • Water leakage
    • Damaged flooring
    • Ageing electrical or plumbing systems
    • Poor renovation work
    • Lift or common-area maintenance issues
    • Inadequate sinking-fund reserves
    • Disputes or management problems

    Some problems are visible. Others may require professional inspection or further investigation.

    For a subsale condominium, I would want to understand the condition of both the individual unit and the overall building.

    A brand-new unit can have defects. An older unit can be well maintained. Age alone does not determine quality.

    Note: The applicable legal protections depend on the type of property, transaction and agreement. Buyers should confirm their position with a qualified property lawyer.

    7. Don’t Ignore the Building’s Management

    This is particularly important when comparing condominiums.

    A new launch may offer an impressive swimming pool, gym, landscaped garden and other facilities.

    But who will maintain them?

    Will the maintenance charges be sustainable for residents?

    Will the facilities remain attractive after several years?

    For a completed property, you have something valuable: evidence of how the building is actually being managed.

    Look at:

    • The condition of common areas
    • Lift maintenance
    • Cleanliness and security
    • Maintenance-charge collection
    • Sinking-fund position
    • Major repairs required
    • Management responsiveness
    • The overall resident experience

    A well-maintained older condominium may provide a better ownership experience than a newer building with poor management.

    Equally, an older building with serious maintenance problems may create expenses that a buyer has underestimated.

    Don’t just compare the units. Compare the buildings behind them.

    8. Which Is Better for First-Time Homebuyers?

    There is no universal answer, but the priorities are different from those of an investor.

    A first-time buyer should consider:

    Affordability: Can you comfortably manage the purchase and ongoing costs?

    Move-in timing: Do you need a home soon, or can you wait for construction to finish?

    Location: Does it work for your job, family, transport needs and daily routine?

    Condition: Are you prepared to manage renovation, repairs or defects?

    Certainty: Would you prefer to inspect an existing unit, or are you comfortable committing to a property that has not yet been completed?

    Future flexibility: If your job or family circumstances change, will the property be reasonably easy to rent out or sell?

    A new launch may suit someone who wants a new home and can wait for completion.

    A subsale may suit someone who wants to inspect the actual property and move in sooner.

    But neither option should stretch your finances to the point that a change in income becomes a crisis.

    Your first property should support your life, not make your life revolve around the mortgage.

    9. Which Is Better for Property Investors?

    For investors, I would focus less on whether the property is new or old and more on the investment case.

    Ask five questions.

    A. What Is My Total Investment?

    Include the purchase price, transaction costs, financing costs, renovation, furnishing and other relevant expenses.

    B. When Can I Realistically Earn Rental Income?

    Account for construction, completion, preparation, vacancy and tenant-finding time.

    C. What Is My Expected Net Return?

    Do not confuse gross rental yield with actual cash flow or net return. Include recurring expenses, vacancy, repairs and financing where relevant.

    D. What Competition Am I Facing?

    Consider both existing properties and future supply.

    E. How Will I Exit?

    Think about the future buyer, resale demand, likely competition and the price at which the property might realistically sell.

    A new launch could offer an attractive opportunity if the price, location, product and future demand justify the purchase.

    A subsale could be attractive if its price is supported by evidence, its condition is acceptable and its rental or owner-occupier demand is sustainable.

    Either could be a poor investment if the numbers don’t work.

    10. The PDS New Launch vs Subsale Decision Test

    Before making a decision, I would compare the two properties using the same framework.

    1. What is the true acquisition cost?

    Include the purchase price, incentives, legal costs, financing and necessary improvements.

    2. What evidence supports the price?

    Look at comparable transactions and the property’s actual features.

    3. What demand exists?

    Investigate owner-occupier demand, tenant demand and the reasons people choose the location.

    4. What are the holding costs?

    Calculate the mortgage, maintenance, repairs, insurance and other recurring expenses.

    5. What risks am I accepting?

    Consider construction, defects, renovation, vacancy, management and future supply.

    6. What is the realistic return?

    Assess net rental income, financing impact, potential capital appreciation and costs.

    7. How will I exit?

    Identify the likely future buyer, resale demand and competing properties.

    The most important point is to compare like with like.

    If the two properties are in different locations, serve different tenant markets or offer different layouts, a simple price comparison may be misleading.

    And if you’re comparing a completed property with one that won’t be ready for several years, timing needs to be part of the analysis.

    So, New Launch or Subsale?

    My answer is straightforward.

    Buy a new launch when the product, price, developer, location and future demand justify the commitment.

    Buy a subsale when the actual property, condition, market evidence and total cost make the purchase worthwhile.

    Don’t choose a new launch just because it is new.

    Don’t choose a subsale just because it appears cheaper.

    And don’t assume that developer incentives, a beautiful showroom or an existing tenant automatically make a property a good investment.

    The right decision comes from understanding what you are buying and why it should meet your needs.

    That is the difference between choosing a property and evaluating a property.

    The Final PDS Insight

    When buyers compare new launches and subsale properties, they often begin with the wrong question:

    “Which one is better?”

    I would start somewhere else.

    “Better for whom, at what price, for what purpose and over what period?”

    A property that suits a first-time homeowner may not suit a rental investor.

    A property that works for a ten-year holding period may not work for someone who needs flexibility within three years.

    And a property that looks attractive today may face very different competition tomorrow.

    There is no shortcut around the discovery process.

    There is only a better way to make the decision.

    Don’t just compare the properties. Discover the decision behind them.

    Property Discovery System™

    Discover Better. Decide Smarter.


  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    Week in Review | Saturday, 3 October – Friday, 9 October 2026

    Explore five property updates from Malaysia, Australia and the UK, covering Budget 2027 housing measures, infrastructure delivery and changing market conditions.


    🇲🇾 STORY 1 — Budget 2027: New Stamp Duty Relief for First-Time Homebuyers

    What Happened?

    On 9 October 2026, Prime Minister Anwar Ibrahim tabled Budget 2027, proposing stamp duty exemptions for eligible first-time homebuyers.

    The proposed measures are:

    • Homes priced up to RM500,000: Full stamp duty exemption on the loan agreement and instrument of transfer.
    • Homes priced up to RM750,000: Full exemption on the first RM500,000, with a 50% exemption on the remaining amount.
    • Proposed eligibility period: Sale and purchase agreements executed from 1 January 2027 to 31 December 2030.

    The government also proposed stamp duty relief for transactions involving the rehabilitation of abandoned housing projects. Prime Minister’s Office Malaysia

    Sources: Prime Minister’s Office of Malaysia — Budget 2027 speech · The Star — First-home stamp duty announcement

    Why It Matters

    Stamp duty can be a significant upfront expense for a homebuyer.

    Reducing this cost could make it easier for some first-time buyers to complete a purchase, particularly those already stretching their savings to cover the deposit, legal fees, moving expenses and basic furnishing.

    However, there is an important distinction between making a home cheaper to purchase and making it affordable to own.

    Monthly instalments, maintenance charges, insurance, repairs and emergency savings remain part of the equation.

    Miichael’s Review

    I welcome measures that reduce the barriers to homeownership.

    But I would not advise anyone to rush into buying a property simply because an incentive is available.

    Before making a decision, buyers should ask themselves three questions:

    1. Can I comfortably afford the monthly repayments?
    2. Will I still have sufficient cash reserves after completing the purchase?
    3. Is this the right property for my needs, location and long-term plans?

    The proposed exemption is useful, but the final eligibility rules and implementation details must also be checked.

    My view: A government incentive should improve a sound property decision, not become the reason for making one.


    🇲🇾 STORY 2 — RM20 Billion Housing Guarantee to Support 80,000 First-Time Buyers

    What Happened?

    Budget 2027 provides for housing financing guarantees of up to RM20 billion through the Housing Credit Guarantee Scheme (SJKP), with the aim of assisting 80,000 first-time buyers.

    The scheme particularly targets people who may struggle to obtain conventional housing financing because they are self-employed or do not receive a fixed monthly income.

    The government also announced nearly RM1 billion for housing initiatives, including Rumah Mesra Rakyat and Program Residensi Rakyat. Four new housing projects were announced for Kulai in Johor, Nilai in Negeri Sembilan, Paya Rumput in Melaka and Pertang Valley in Terengganu. Prime Minister’s Office Malaysia

    Sources: Prime Minister’s Office of Malaysia — Budget 2027 housing measures · The Star — RM20 billion SJKP guarantee

    Why It Matters

    This addresses one of the practical challenges facing Malaysian homebuyers: access to financing.

    Some self-employed individuals have sufficient income to meet repayments but find it difficult to satisfy conventional lending requirements because their earnings fluctuate or are documented differently.

    A financing guarantee can help eligible applicants access housing loans. However, it does not mean every applicant will automatically receive loan approval.

    There is also a wider issue to consider.

    Helping more people obtain financing is only part of the solution. The market must also provide homes that buyers can genuinely afford, in locations that suit their work, family needs and daily routines.

    Miichael’s Review

    This measure is particularly relevant to younger buyers, entrepreneurs and people with non-traditional income arrangements.

    However, I would like to see how the scheme works in practice.

    How accessible will it be? What are the eligibility conditions? Will the homes available to these buyers match their budgets?

    Financing access and housing affordability must work together.

    Otherwise, we may help people qualify for loans without necessarily helping them find suitable homes.


    🇲🇾 STORY 3 — Sabah Pan Borneo Highway: Infrastructure Delivery Matters More Than Announcements

    What Happened?

    The Auditor-General’s Report 2/2026, tabled on 5 October, highlighted cost increases and delivery problems affecting Sabah Pan Borneo Highway Phase 1.

    The report stated that contract costs had risen to RM18.96 billion, compared with the original RM17.91 billion.

    As at 31 March 2026, only 4 of the 35 work packages had been completed.

    The report also identified site-readiness and land-acquisition problems, RM513.99 million in variation orders approved beyond authorised limits, and RM41.37 million in delayed utility claims. These are figures reported in the audit, and the completion count relates to the position at the stated date. EdgeProp

    Source: EdgeProp Malaysia — 5 October property and infrastructure digest, reporting on the Auditor-General’s Report 2/2026.

    Why It Matters

    Infrastructure can influence property values by improving access to employment, commercial centres, tourism destinations and essential services.

    But there is a difference between a project being announced, a project being constructed and a project being completed and operational.

    Delays can postpone the economic benefits that were expected to support surrounding areas.

    For buyers and investors, this means that a property’s location should be evaluated against infrastructure that is actually available, as well as projects that remain under construction.

    Miichael’s Review

    When evaluating property near a major infrastructure project, I would not rely on a developer’s location map alone.

    I would examine:

    • Which sections of the road are already operational?
    • How much travel time will actually be saved?
    • Are employment opportunities and commercial activities growing nearby?
    • Will utilities and public services be sufficient for future development?
    • Is the property priced as though future improvements have already been delivered?

    Infrastructure creates potential, but execution determines when—and whether—that potential becomes real.

    This is an important lesson for property buyers in every state, not just Sabah.


    🌏 INTERNATIONAL PROPERTY WATCH

    🇦🇺 STORY 4 — Australia: Housing Prices Fall for a Sixth Consecutive Month

    What Happened?

    National Australia Bank’s October Housing Monitor, published on 7 October, reported that dwelling prices across Australia’s combined capital cities fell 1.2% month-on-month in September 2026.

    This marked the sixth consecutive monthly decline. Prices were 6.4% below their March 2026 peak.

    NAB also revised its forecast to an 8% decline in capital-city dwelling prices over 2026, with a possible peak-to-trough decline of 11%.

    The median time a property spent on the market increased to 41 days, the highest level since late 2020. These figures reflect NAB’s analysis and forecasts, not guaranteed future outcomes. NAB

    Source: National Australia Bank — October 2026 Housing Monitor

    Why It Matters

    The downturn has broadened beyond the markets that initially showed the greatest weakness.

    For buyers, falling prices and longer selling periods may create more room for negotiation. Sellers may need to be more realistic about pricing and the time required to secure a buyer.

    But a declining market does not automatically mean every property is a bargain.

    A property bought at a lower price can still be a poor investment if rental demand is weak, financing costs are high or the local economy deteriorates.

    Miichael’s Review

    I would not look at falling prices in isolation.

    For investors, the more important questions are:

    • Is the purchase price attractive relative to comparable properties?
    • Can rental income reasonably cover the holding costs?
    • Is the local employment base resilient?
    • Can the investment withstand a longer period of weak prices?
    • Would I still want to own this property if the market took several years to recover?

    The best buying opportunity is not necessarily when prices fall the most. It is when the price, risk and long-term fundamentals make sense together.


    🇬🇧 STORY 5 — United Kingdom: Buyer Confidence Weakens While Rental Demand Remains Firm

    What Happened?

    The Royal Institution of Chartered Surveyors (RICS) published its September UK Residential Market Survey on 6 October.

    The survey reported:

    • New buyer enquiries: Net balance of -22%, compared with -18% in August.
    • Agreed sales: Net balance of -18%, compared with -16% in August.
    • House-price sentiment: Net balance of -32%, compared with -28% in August.
    • Tenant demand: Net balance of +23%.
    • Expected rental growth: Net balance of +37% for the following three months.

    The figures suggest weaker buyer sentiment and sales activity alongside continued rental demand. RICS

    Source: RICS — UK Residential Survey, September 2026

    Why It Matters

    The sales and rental markets do not always move in the same direction.

    In the UK, buyers were becoming more cautious while rental demand remained comparatively strong.

    One important clarification: RICS net balances measure the difference between respondents reporting increases and those reporting decreases. A -32% house-price balance does not mean that actual house prices fell by 32%.

    For property investors, rental demand is only one part of the equation. Purchase price, mortgage costs, taxes, maintenance, regulation and net rental yield all matter.

    Miichael’s Review

    This is a good example of why property investors should separate capital-growth expectations from rental fundamentals.

    A market may offer rental opportunities even when transaction activity is weak. But strong rental demand alone does not guarantee a good investment.

    Investors need to understand what remains in their pocket after financing, maintenance, taxes and other expenses.

    Rental demand is a useful signal. Net returns and the ability to sustain ownership are what ultimately matter.


    WORTH WATCHING

    Over the coming weeks, I would pay particular attention to four developments.

    1. Malaysia’s Budget 2027 implementation

    The proposed stamp duty exemptions are encouraging, but the final eligibility conditions and implementation documents will be important. Buyers should not assume that every transaction automatically qualifies.

    2. Financing access for first-time buyers

    The RM20 billion SJKP guarantee is a substantial measure. The next question is how effectively it translates into approved financing and sustainable homeownership.

    3. Infrastructure execution in Malaysia

    The Pan Borneo audit highlights the importance of monitoring actual construction progress, costs and completion dates. Future property decisions should be based on realistic delivery expectations.

    4. International borrowing costs and market conditions

    Australia and the UK show why buyers and investors must continue to monitor financing costs, transaction activity, prices and rental conditions rather than relying on a single market headline.


    MY TAKEAWAY THIS WEEK

    This week reinforces a principle I have always believed in: a property decision should never be based on price alone.

    Malaysia is trying to reduce barriers to homeownership, but buyers still need sustainable financing and suitable homes.

    Australia reminds us that prices can continue falling longer than investors expect.

    The UK shows that sales and rental conditions can move in different directions.

    And the Pan Borneo audit reminds us that infrastructure announcements only create lasting value when projects are delivered.

    For buyers and investors, the questions remain the same:

    • Can I afford it comfortably?
    • Is there genuine demand?
    • Does the location have the infrastructure and economic activity to support it?
    • Do the numbers work under conservative assumptions?
    • Would this still be a sensible decision if the market did not rise as quickly as I hoped?

    Look beyond the price. Understand the fundamentals before making the decision.

    Miichael Yeoh
    PROPERTY STRATEGIST
    www.miichaelyeoh.com
    Thank you for subscribing!

    Please check your email to confirming your subscription.

  • Malaysia Budget 2027: What Property Buyers, Investors and Developers Need to Know

    Malaysia Budget 2027: What Property Buyers, Investors and Developers Need to Know

    By Miichael Yeoh | Property Discovery System(PDS)

    Malaysia’s Budget 2027 has introduced several measures that could influence the country’s property market, from first-home ownership and housing financing to the rehabilitation of abandoned housing projects.

    But what do these announcements actually mean for Malaysians considering a property purchase?

    A stamp duty exemption may reduce the upfront cost of buying a home. A housing loan guarantee may help certain buyers access financing. Public housing and infrastructure investments may create opportunities in selected locations.

    Yet none of these measures automatically makes a property affordable, a development attractive or an investment profitable.

    For homebuyers, investors and developers, the more important question is how these policies affect real property decisions.

    Here is my assessment of the key property-related measures in Malaysia Budget 2027 and what they could mean for the market, including Penang.

    1. First-home buyers: Stamp duty relief expands up to RM750,000

    One of the most significant property announcements in Budget 2027 is the proposed expansion of stamp duty exemptions for first-home purchases.

    According to the Budget speech delivered by Prime Minister and Finance Minister Datuk Seri Anwar Ibrahim on 9 October 2026, the proposed relief will apply to sale and purchase agreements executed from 1 January 2027 to 31 December 2030.

    The proposed structure is:

    • First homes priced up to RM500,000: Full stamp duty exemption on the instrument of transfer and housing loan agreement.
    • First homes priced above RM500,000 and up to RM750,000: Full exemption on the first RM500,000, with a 50% exemption on the remaining amount.

    The proposal is intended to reduce the upfront costs of purchasing a first home.

    Source: Prime Minister’s Office — Budget 2027 speech

    What does this mean for homebuyers?

    For eligible buyers, lower stamp duty can reduce the cash required at the point of purchase.

    The expanded price range is also relevant to buyers who have been looking at homes above RM500,000 but below RM750,000. However, the actual savings will depend on the final implementation rules, the transaction value and the applicable loan terms.

    Buyers should also distinguish between a reduction in transaction costs and an improvement in long-term affordability.

    A home that qualifies for stamp duty relief may still be financially unsuitable if the monthly instalment, maintenance charges, insurance and other commitments stretch the household budget.

    My view: Treat stamp duty relief as a financial advantage, not the main reason to buy a property.

    2. RM20 billion in housing financing guarantees for first-time buyers

    Budget 2027 also provides for up to RM20 billion in housing financing guarantees through the Housing Credit Guarantee Scheme, known as SJKP.

    The scheme is expected to assist approximately 80,000 first-time homebuyers, with particular attention to self-employed individuals and people without fixed monthly incomes.

    This is important because not every prospective buyer has a conventional salary structure.

    Business owners, freelancers and other self-employed individuals may have sufficient earning capacity but face difficulties meeting standard income-documentation requirements.

    SJKP is intended to improve access to housing financing for eligible applicants.

    Source: BERNAMA — Budget 2027 housing financing guarantees

    Does a housing guarantee mean everyone can obtain a loan?

    No. A guarantee does not automatically mean loan approval.

    Applicants must still meet the scheme’s eligibility conditions and the relevant lender’s assessment requirements. Buyers should confirm the applicable financing limits, documentation requirements and repayment obligations before committing to a purchase.

    The key consideration is not simply whether financing is available, but whether the buyer can comfortably sustain the repayments.

    My view: Better financing access is useful when it connects eligible buyers with homes they can genuinely afford. It becomes risky if buyers interpret easier access to financing as a reason to borrow beyond their means.

    3. Can Budget 2027 help revive abandoned housing projects?

    Another significant proposal is the full stamp duty exemption for qualifying transactions involving the rehabilitation of abandoned housing projects.

    The proposed relief covers loan agreements and instruments of transfer executed by contractors or developers rescuing abandoned projects, as well as by the original purchasers involved in those projects.

    The proposed effective period is 1 January 2027 to 31 December 2030.

    The measure forms part of the government’s stated ambition to achieve zero abandoned housing projects by 2030.

    Source: Prime Minister’s Office — Budget 2027 speech

    Will this solve the abandoned housing problem?

    Stamp duty relief can reduce transaction costs, but reviving an abandoned project is more complicated than reducing taxes.

    A successful rescue may depend on:

    • Whether the project is financially viable.
    • Whether a capable rescue developer can be appointed.
    • Whether land, financing and legal issues can be resolved.
    • Whether construction can be completed within a realistic timeframe.
    • Whether original purchasers can ultimately receive their homes.

    For affected buyers, the priority remains understanding the legal and financial status of the project and the conditions under which completion can proceed.

    My view: The incentive is a useful part of the solution, but actual project rehabilitation and delivery will be the real test.

    4. Nearly RM1 billion for housing programmes

    Budget 2027 provides nearly RM1 billion for programmes including Rumah Mesra Rakyat and Program Residensi Rakyat.

    Four new housing projects are identified in Kulai, Johor; Nilai, Negeri Sembilan; Paya Rumput, Melaka; and Pertang Valley, Terengganu.

    The Budget also identifies Bandar MADANI Bukit Jalil as a residential development with supporting amenities, including a vertical school.

    These initiatives reflect the continuing role of government-supported housing in addressing housing needs.

    Source: Prime Minister’s Office — Budget 2027 speech

    For buyers, however, the announcement of a housing programme is only the beginning.

    Eligibility, location, unit pricing, delivery schedules and access to public amenities all affect whether a particular development meets a household’s needs.

    Affordable housing should not be assessed by price alone. Accessibility to employment, transport, schools and essential services also matters.

    5. What could Budget 2027 mean for Penang property?

    Penang’s property market has its own economic drivers. Its manufacturing base, semiconductor ecosystem, employment opportunities, infrastructure and limited availability of certain types of land all influence property demand.

    Budget 2027 includes a RM100 million Strategic Investment Fund involving Khazanah and InvestPenang to support early-stage semiconductor and advanced manufacturing companies.

    The Budget also identifies transport-related infrastructure investment involving roads in port areas and airports, including Penang International Airport.

    These announcements could have indirect implications for property demand if they translate into business expansion, job creation and improved connectivity.

    Source: Prime Minister’s Office — Budget 2027 speech

    Which property segments could benefit?

    Industrial and logistics property

    Business expansion may create demand for suitable industrial facilities, warehouses and supporting commercial space. Actual demand will depend on investment commitments, company requirements and available supply.

    Residential property near employment centres

    If industrial investment generates additional jobs, it could support demand for housing in accessible locations. The effect will vary according to workers’ incomes, commuting patterns, rental budgets and the supply of competing homes.

    Commercial property

    Business growth may create opportunities for offices, retail services and other supporting uses. These opportunities should be assessed against occupancy, tenant demand and operating costs.

    Does this mean Penang property prices will rise?

    Not necessarily.

    Infrastructure and investment announcements are not guarantees of capital appreciation. The impact on individual developments depends on their location, purchase price, accessibility, competing supply, rental demand and the actual delivery of the announced projects.

    For buyers, the right question is not simply whether an area will benefit from economic growth. It is whether a particular property is priced reasonably relative to its likely demand and long-term usefulness.

    6. What should property investors watch?

    Budget 2027 creates several areas worth monitoring, but investors should distinguish between a policy announcement and a measurable investment opportunity.

    Follow employment and business expansion

    Industrial investment may support housing and commercial demand, but the most useful evidence will be actual investment commitments, completed facilities, employment growth and tenant activity.

    Assess rental demand rather than relying on capital appreciation

    A property near an expanding employment centre may attract tenants, but rental demand does not guarantee a satisfactory yield.

    Investors should calculate realistic rental income after vacancies, maintenance, management fees, financing costs and other expenses.

    Check competing supply

    Even a location with strong economic activity can experience weak rental performance if too many similar units compete for tenants.

    Evaluate the purchase price

    Government incentives can influence demand, but buyers still need to assess whether the asking price is supported by comparable transactions, rental evidence and the property’s fundamentals.

    My view: Investors should follow the economic effects of the Budget, not simply the headlines. A good investment still requires a sound entry price and a clear understanding of risk.

    7. What does Budget 2027 mean for property developers?

    The Budget’s housing measures may help reduce some barriers to homeownership. However, developers continue to face the practical challenges of land, construction, financing, regulatory compliance and buyer affordability.

    The Real Estate and Housing Developers’ Association Malaysia (REHDA) welcomed the proposed homeownership measures and housing financing guarantees. It also called for a review of development-related charges and highlighted construction costs and the need to address completed but unsold residential properties.

    Source: EdgeProp — REHDA’s response to Budget 2027

    For developers, three questions deserve attention.

    First, does the product match the buyer’s budget?

    A property may have attractive facilities and branding, but the target buyer must still be able to afford the purchase and ongoing ownership costs.

    Second, does the project offer a clear reason to buy?

    Location, accessibility, layout, price, surrounding amenities and realistic future demand matter more than marketing claims alone.

    Third, is the sales process helping buyers make confident decisions?

    Buyers need clear information about costs, financing, project delivery, ownership obligations and relevant risks.

    The Budget may improve some aspects of the purchasing environment, but it cannot replace sound product positioning, credible communication and responsible sales practices.

    8. Five questions every homebuyer should ask before purchasing

    Regardless of government incentives, I encourage buyers to work through five questions before making a commitment.

    1. Can I afford this property comfortably? Calculate the deposit, transaction costs, monthly instalment, maintenance and a realistic contingency reserve.
    2. Does the location fit my needs? Consider employment, transport, schools, amenities and daily travel requirements.
    3. Is the price supported by evidence? Compare similar properties, recent transactions and realistic rental values where relevant.
    4. What risks am I taking? Understand the developer’s track record, construction status, legal terms, competing supply and likely holding costs.
    5. Does this property fit my long-term plan? A home for own occupation and an investment property may require different priorities.

    These questions are especially important when an incentive makes a purchase appear more attractive. A lower upfront cost does not necessarily make a property the right choice.

    9. My takeaway: Policy support is useful, but property decisions still matter

    Malaysia Budget 2027 proposes meaningful support for first-home buyers through expanded stamp duty relief, housing financing guarantees and measures intended to facilitate the rehabilitation of abandoned projects.

    It also identifies housing programmes and investment initiatives that could influence economic activity in selected locations, including Penang.

    The eventual impact will depend on implementation, financing access, actual investment and the underlying supply and demand for property.

    For homebuyers, the opportunity is to understand the assistance available without losing sight of affordability.

    For investors, it is to identify genuine demand rather than assume every policy announcement will increase property values.

    For developers, it is to understand what buyers need and communicate the value of a project clearly and responsibly.

    At the Property Discovery System™ (PDS), our approach is straightforward: understand the market, evaluate the options, identify the risks and make decisions based on evidence.

    Because buying property should never be about following a headline alone.

    Discover Better. Decide Smarter.

    This article is for general property education and information. Budget 2027 measures described as proposed remain subject to the relevant legislation, implementation guidelines and eligibility requirements. Readers should confirm their individual circumstances with the relevant authorities and professional advisers before making financial or property decisions.

  • Is Now a Good Time to Buy Property in Malaysia ?

    Is Now a Good Time to Buy Property in Malaysia ?

    Everyone wants to know whether property prices will rise or fall.

    But that’s not the question I would ask before buying a property.

    The better question is:

    “Is this the right property, at the right price, with the right financing, for my situation?”

    Because even if the market rises next year, you can still make a bad property decision today.

    And even if prices fall, waiting doesn’t automatically mean you will get a better deal.

    So, is 2026 a good time to buy property in Malaysia?

    My answer: It can be — but only if you stop trying to predict the market and start discovering the numbers behind the decision.


    What Is Actually Happening in the Malaysian Property Market?

    Let’s start with the facts.

    Malaysia’s property market remained resilient in the first half of 2026, recording 187,320 transactions worth RM105.12 billion. The market was supported by relatively stable transaction activity, prices and construction activity.

    At the same time, the market isn’t booming across every segment.

    Residential transactions in H1 2026 were 110,998, accounting for 59.3% of total property transactions. Completed unsold residential units increased to 33,094 units, worth about RM17.78 billion.

    That tells us something important.

    The market isn’t simply “good” or “bad”.

    There are areas of strength.

    There are areas of oversupply.

    There are properties with genuine demand.

    And there are properties that developers are struggling to sell.

    This is exactly why buyers need to become more selective.


    What About Interest Rates?

    This is probably one of the first things buyers look at.

    And understandably so.

    Bank Negara Malaysia has maintained the Overnight Policy Rate (OPR) at 2.75% throughout 2026, including its latest decision on 3 September 2026.

    That provides a relatively stable financing environment compared with periods of rapidly changing interest rates.

    But here’s where I think many buyers make a mistake.

    They see a stable or lower interest-rate environment and immediately think:

    “Good. Time to buy.”

    Not necessarily.

    The interest rate is one variable in your property decision.

    It is not the decision.

    A property that is overpriced by RM100,000 doesn’t suddenly become a good investment because your mortgage rate is slightly lower.


    Should You Wait for Property Prices to Fall?

    This is probably the question I hear most often.

    And it sounds logical.

    “If prices are going to fall, I’ll wait.”

    But there are two problems with this strategy.

    First, nobody knows exactly when prices will fall.

    And more importantly:

    Second, even if prices fall, you may not benefit.

    Why?

    Because the property you want may not fall.

    The bank may tighten lending.

    Your income may change.

    Interest rates may move.

    The developer may remove incentives.

    Another buyer may take the unit you wanted.

    Or the market may simply remain stable for several years.

    Waiting is not a neutral decision.

    Waiting is also a property decision.


    The Bigger Question: What Are You Actually Buying?

    This is where I believe buyers need to change their thinking.

    Don’t ask only:

    “Will property prices go up?”

    Ask:

    “What is creating the demand for this property?”

    Is it:

    • population growth?
    • new jobs?
    • infrastructure?
    • universities?
    • industrial development?
    • tourism?
    • rental demand?
    • limited land supply?
    • better connectivity?
    • genuine owner-occupier demand?

    Or is the main attraction simply:

    “The developer says prices will increase.”

    Those are very different things.


    5 Things I Would Check Before Buying Property

    1. Can You Actually Afford It?

    This sounds obvious.

    But affordability isn’t simply:

    “The bank approved my loan.”

    A bank’s approval tells you what the bank is prepared to lend.

    It doesn’t tell you what you should comfortably borrow.

    Before buying, calculate the full monthly cost:

    • mortgage instalment
    • maintenance fee
    • sinking fund
    • assessment
    • quit rent
    • insurance
    • utilities
    • repairs
    • furnishing
    • parking
    • transportation
    • other existing commitments

    Then ask:

    “If my income stays the same for the next three years, will this property still feel comfortable?”

    That’s a much better question than:

    “How much can the bank approve?”


    2. Is the Price Supported by the Market?

    Don’t fall in love with the launch price.

    Find out what similar properties are actually transacting for.

    NAPIC provides transaction, price, rental and property-market data, including state and district-level information.

    Compare:

    Asking price vs actual transaction price.

    Then compare:

    RM per sq ft vs comparable properties.

    Then ask:

    “What am I paying a premium for?”

    If the answer is simply:

    “Because this is a new launch.”

    That’s not enough.


    3. Is There Real Demand?

    A beautiful building isn’t demand.

    A famous developer isn’t demand.

    A fantastic showroom isn’t demand.

    Demand comes from people who genuinely want to live, work, rent or invest in that location.

    Ask:

    • Who is going to live here?
    • Who is going to rent here?
    • Where do these people work?
    • Why would they choose this location?
    • What alternatives do they have?
    • What competing projects are coming?

    This becomes particularly important when a market has significant unsold stock.

    Malaysia’s completed unsold residential inventory rose to 33,094 units in H1 2026.

    That doesn’t mean all property is bad.

    It means product selection matters.


    4. What Happens When More Supply Arrives?

    This is one of the most overlooked questions in property investing.

    Imagine you buy a condominium because the current rental demand looks excellent.

    But three years later, five more projects are completed nearby.

    Now you have thousands of competing units.

    Your tenant has choices.

    Your rental growth may slow.

    Your vacancy risk may increase.

    And when you eventually want to sell, you’re no longer competing only against today’s properties.

    You’re competing against tomorrow’s properties.

    That’s why I always tell buyers:

    Don’t just study the property. Study what is coming around the property.


    5. What’s Your Exit Strategy?

    This is perhaps the biggest difference between a home purchase and an investment purchase.

    A homeowner may be happy because:

    “I love the location.”

    An investor needs another question:

    “Who will buy this from me later?”

    Think about your exit before your entry.

    If you need to sell in five or ten years:

    • Who is your future buyer?
    • What will they be looking for?
    • What competing supply will exist?
    • Will your property still be relevant?
    • Will your price be affordable to the next buyer?
    • Will the rental market support your valuation?

    You don’t realise your investment return when you buy.

    You realise it when you eventually exit.


    So… Is 2026/2027 a Good Time to Buy Property?

    Here’s my answer.

    Yes — if you’re buying based on fundamentals.

    No — if you’re buying simply because you believe prices must go up.

    The Malaysian property market in 2026 is resilient, but the data also shows why buyers cannot treat the entire market as one big opportunity.

    Transaction activity remains substantial.

    Interest rates are relatively stable.

    But residential demand is uneven, completed unsold stock has increased, and affordability remains an important constraint.

    That creates an interesting environment.

    It may actually be a better time to be a selective buyer than an emotional buyer.

    You don’t necessarily need to wait for a market crash.

    You need to find the property where:

    Price + Location + Demand + Financing + Supply + Exit

    all make sense together.


    The PDS 7-Question Property Test

    Before I buy any property, I would want to answer these seven questions:

    1. Why this property?

    What problem does it solve?

    2. Why this location?

    What is creating sustainable demand?

    3. Why this price?

    What evidence supports the valuation?

    4. Who is the future buyer or tenant?

    Where does the demand come from?

    5. What competition is coming?

    What could affect rental and resale demand?

    6. Can I comfortably hold it?

    Not just today — but through different market conditions.

    7. How do I eventually exit?

    Who will buy it from me?

    If you can’t answer these questions, perhaps you are not ready to buy.

    And that’s okay.

    Not buying is sometimes a better decision than buying the wrong property.


    The Real Question Isn’t “When Should I Buy?”

    After more than two decades around banking, mortgages, property and investment decisions, I’ve learned that buyers often spend too much time trying to predict the market.

    The smarter approach is to understand the decision.

    You don’t need to know exactly where property prices will be five years from now.

    You need to understand why the property you’re considering should still have demand five years from now.

    That’s a very different way of looking at property.

    And it is the philosophy behind the Property Discovery System™.

    Don’t just ask whether now is a good time to buy.

    Discover whether this is the right property for you.

    Discover Better. Decide Smarter.

    Miichael Yeoh

    Property Strategist

  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    26 September – 2 October 2026

    Malaysia + International Property Insights

    This week’s market is interesting for one reason: the headlines are not telling one single story.

    Malaysia has pockets of resilience in retail and construction, but residential developers are still dealing with affordability and unsold stock. Overseas, Australia is going through a much sharper housing correction, while Singapore continues to reposition mature assets through redevelopment.

    For buyers and investors, the lesson is simple: look beneath the headline number.


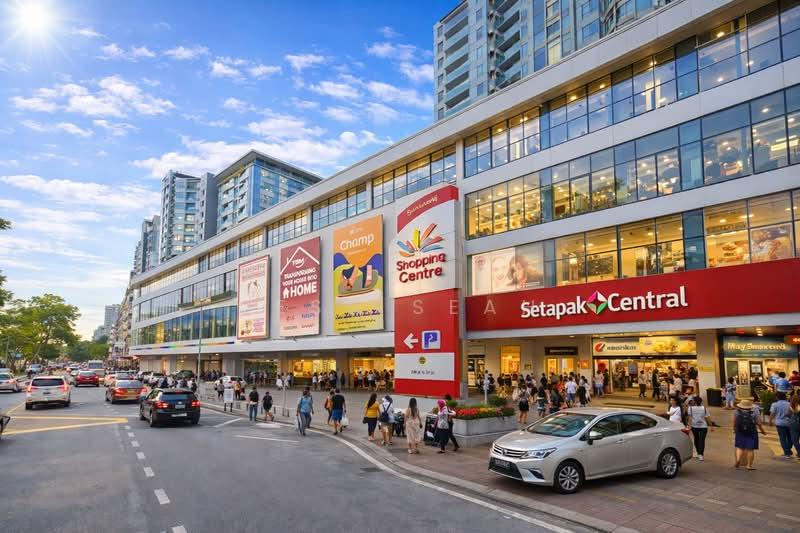
    🇲🇾 1. KIP REIT Completes RM435 Million Setapak Central Mall Acquisition

    What Happened

    KIP REIT completed its RM435 million acquisition of Setapak Central Mall on 30 September.

    The three-storey mall has approximately 514,777 sq ft of net lettable area and 1,090 parking bays. Occupancy had previously been reported at 99.89%.

    The acquisition brings KIP REIT’s portfolio to 20 properties, with the enlarged portfolio previously assessed at around RM2.1 billion. EdgeProp

    Why It Matters

    This isn’t simply about buying another shopping mall.

    A mature, highly occupied retail asset can provide something very different from a new development:

    existing tenants + existing footfall + existing income.

    For investors, that distinction matters.

    The question isn’t simply whether a property is “good”.

    It is:

    How predictable is the income after I buy it?

    Miichael’s Review

    I like looking at transactions like this because they demonstrate another side of property investment.

    A developer creates value through development.

    A REIT investor is often looking for income-producing assets with established operations.

    For individual investors, the same principle applies.

    Before getting excited about a property because of future appreciation, ask:

    What is producing the income today?

    Source: EdgeProp — KIP REIT completes RM435m Setapak Central acquisition


    🇲🇾 2. Gamuda Posts Record Profit — But Property Earnings Fall

    What Happened

    Gamuda reported record FY2026 net profit of RM1.05 billion, up 5%.

    But there is an interesting contrast underneath the headline.

    While the group’s overall performance was supported by stronger construction earnings, property sales fell 22% to RM3.2 billion, while property division net profit declined 18% to RM310.76 million. EdgeProp

    Why It Matters

    This is a useful reminder that a diversified property-related group can perform well overall even when its property division is under pressure.

    It also reinforces an important market principle:

    Construction demand and residential property demand are not necessarily moving together.

    Miichael’s Review

    For me, the interesting part isn’t simply that Gamuda made a record profit.

    It is the divergence between construction and property.

    When analysing a developer, I would not stop at the group’s headline earnings.

    I’d want to know:

    • How much comes from property?
    • What is the sales pipeline?
    • How much unsold inventory exists?
    • Where are the projects located?
    • What is the margin?
    • And how quickly can sales be converted into cash?

    A strong company does not automatically mean every property project is equally attractive.

    Source: EdgeProp — Gamuda posts record FY2026 profit


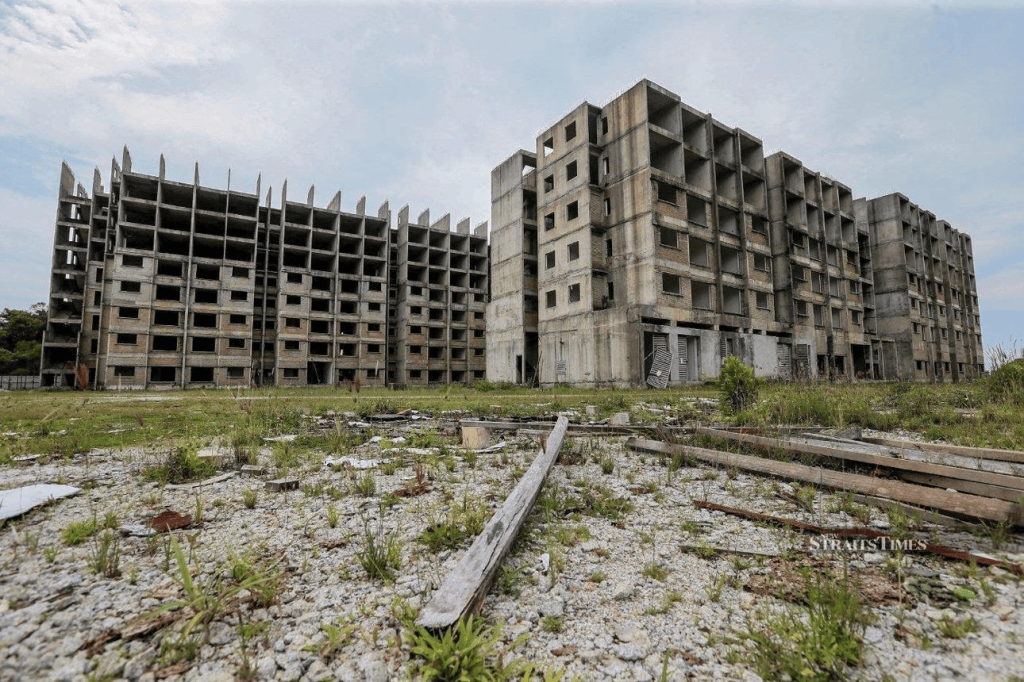
    🇲🇾 3. Government Calls for More “White Knights” to Rescue Abandoned Projects

    What Happened

    Malaysia’s Housing and Local Government Ministry has called on established developers to step in as “white knights” to revive stalled and abandoned housing developments.

    According to the report, the ministry’s task force has helped revive 1,647 distressed projects worth RM153 billion, affecting almost 200,000 homebuyers.

    The government is also pursuing legal reforms involving developer accountability, strata management and residential tenancy. The Star

    Why It Matters

    For a buyer, buying property isn’t simply about:

    location + price + size.

    There is another question that often gets overlooked:

    Who is behind the project — and what happens if things go wrong?

    A delayed or abandoned project can create years of financial and emotional stress for buyers.

    Miichael’s Review

    This is one area where I think buyer education is particularly important.

    Before buying a new development, buyers should investigate the developer’s track record, project delivery history, financial structure, development partners and surrounding ecosystem.

    We often spend hours comparing unit sizes and discounts.

    But sometimes the most important due diligence happens before we even choose the unit.

    Source: The Star — Malaysia needs more white knights


    🌏 4. Australia: Housing Prices Fall for a Sixth Straight Month

    What Happened

    Australia’s housing market continued to weaken in September.

    Cotality’s national Home Value Index fell 1.1% in September, the sixth consecutive monthly decline.

    Values are now 5.2% below the March 2026 peak.

    Sydney fell 1.4% in September and is nearly 9% below its February peak, while Melbourne fell 0.7%.

    Transaction activity has also weakened, with sales over the latest three-month period down around 19% year-on-year, according to Reuters. Reuters

    The Reserve Bank of Australia has also raised its cash rate to 4.6%, a 15-year high, adding further pressure to borrowing capacity. Investing.com

    Why It Matters

    Australia provides an excellent real-world example of the relationship between:

    interest rates → borrowing capacity → buyer demand → transactions → prices.

    And importantly, the impact is not identical across every city.

    Miichael’s Review

    For Malaysian buyers and investors looking overseas, this is a market worth watching carefully.

    A falling market doesn’t automatically mean:

    “Everything is cheap.”

    It means the risk-reward equation is changing.

    For anyone considering an overseas property purchase, I’d be asking:

    Has the price fallen because the market is correcting — or because the fundamentals have deteriorated?

    Those are two very different things.

    Source: Reuters — Australian home prices fall for sixth straight month; Cotality — September Home Value Index


    🌏 5. Singapore: Valley Point to Become a New Mixed-Use Development

    What Happened

    Frasers Property and Mitsubishi Estate announced plans to redevelop Valley Point and Frasers Suites Singapore along River Valley Road.

    The planned mixed-use development will include:

    • 407 luxury residential units and sky villas
    • 184 serviced-residence units
    • dining
    • retail
    • lifestyle components

    The project is planned for launch in 2027, with completion targeted for 2031. The existing properties are expected to cease operations in March 2027. The Business Times

    Why It Matters

    This is a classic example of urban land optimisation.

    Instead of simply maintaining an ageing asset, the owners are looking at the highest and best use of a prime site.

    The redevelopment also combines residential, serviced residences, retail and lifestyle components rather than relying on one single use.

    Miichael’s Review

    This is something developers everywhere can learn from.

    A property isn’t necessarily valuable because of what it is today.

    Sometimes its greatest value comes from what it could become.

    But that requires looking beyond the building itself:

    land value + location + planning potential + demand + surrounding ecosystem.

    For buyers, this also highlights why understanding a property’s future development context can be just as important as studying the existing building.

    Source: The Business Times — Frasers Property and Mitsubishi Estate redevelopment; Frasers Property — official announcement


    👀 WORTH WATCHING

    Malaysia

    1. Residential affordability

    The combination of unsold stock, financing constraints and developer margins remains an important issue.

    2. Retail investment

    The KIP REIT acquisition shows that mature, income-producing retail assets remain relevant when occupancy and cash flow are strong.

    3. Distressed projects

    The government’s push for more private-sector participation could change the landscape for abandoned and stalled developments.

    🌏 International

    4. Australia

    Watch whether the correction continues into 2027 and whether lower transaction volumes eventually create broader economic effects.

    5. Singapore

    Watch how redevelopment and land optimisation reshape mature neighbourhoods.


    💡 MY TAKEAWAY

    This week’s five stories are actually connected by one common theme:

    Property value is about more than price.

    A shopping mall’s value can come from income and occupancy.

    A developer’s value can come from the quality of its pipeline and balance sheet.

    A residential project’s value includes delivery risk.

    A housing market’s direction is influenced by financing and affordability.

    And an older property can sometimes create greater value through redevelopment.

    So when someone asks me:

    “Is this property a good buy?”

    I don’t think the first question should be:

    “How much is it?”

    I’d rather start with:

    Who is buying it?

    Why are they buying it?

    What creates the demand?

    What could go wrong?

    And what happens if the market doesn’t behave as expected?

    That is where proper property due diligence begins.

    From the desk of

    Miichael Yeoh

    Property Strategist

  • Malaysia Property Market 2026: 33,094 Unsold Homes — Are They Really “For Sale” to Everyone?

    Malaysia Property Market 2026: 33,094 Unsold Homes — Are They Really “For Sale” to Everyone?

    33,094

    That is the number currently attracting attention in Malaysia’s property market.

    As at the first half of 2026, 33,094 completed residential units worth RM17.78 billion remained unsold.

    The figure is up from 30,471 units in the previous period.

    Naturally, the immediate question is:

    Why aren’t Malaysians buying these homes?

    The usual answers come quickly.

    Homes are too expensive.

    Buyers cannot afford them.

    Banks are rejecting loans.

    Developers are building too much.

    All of these factors may play a role.

    But I think we need to ask a more fundamental question:

    What does “unsold” actually mean?

    Because an unsold property is not necessarily a property that is simply sitting on the open market waiting for any Malaysian to buy it.

    And that distinction matters.


    The Unsold Property Paradox

    Let’s start with something that may surprise many people.

    Malaysia’s property market is still active.

    In the first half of 2026, the country recorded 187,320 property transactions worth RM105.12 billion.

    Residential property accounted for 110,998 transactions, representing 59.3% of total transactions and RM47.11 billion in transaction value.

    So this isn’t a story about Malaysians suddenly refusing to buy property.

    There are buyers.

    There are transactions.

    There is demand.

    Yet at the same time, tens of thousands of completed homes remain unsold.

    That is the paradox.

    People are buying property — but some completed properties are still not finding buyers.

    This tells us that the problem is more complicated than simply:

    “Malaysians cannot afford houses.”


    Not Every Unsold Unit Has the Same Problem

    This is where I believe we need to look at the property market differently.

    An “unsold” unit could be unsold for very different reasons.

    1. The buyer doesn’t want it.

    The location may not be attractive.

    The layout may not fit the target market.

    The facilities may not justify the price.

    The surrounding environment may not match what buyers want.


    2. The buyer wants it — but cannot get financing.

    This is a very real issue.

    The latest REHDA Property Industry Survey found that 59% of surveyed developers reported unsold completed residential units.

    Among the factors highlighted were end-financing rejection, property prices and unreleased Bumiputera units.

    The survey covered 181 REHDA members in Peninsular Malaysia.

    A buyer can therefore say:

    “I want this property.”

    But the bank may effectively say:

    “You cannot finance it.”

    Those are two completely different problems.


    3. Some units are not immediately available to the entire market

    This is another part of the conversation that deserves more attention.

    Some residential developments contain Bumiputera quota units.

    Where those units remain unsold, developers may need to go through the relevant state process before they can be released to the wider market.

    The rules are not identical across Malaysia.

    In Penang, for example, the state has a formal Bumiputera quota release process, including requirements relating to the physical progress of the development and evidence of marketing efforts to Bumiputera purchasers.

    So an important distinction needs to be made:

    A unit can be recorded as “unsold” without necessarily being immediately available to every buyer in the market.

    And depending on the state and applicable scheme, releasing such units can also involve specific conditions or financial contributions.

    This matters because we should be careful not to treat every unit in the RM17.78 billion figure as if it represents exactly the same market problem.


    4. The product may simply be wrong for today’s buyer

    This is probably one of the most overlooked questions in property development.

    A project may have been conceived several years ago.

    The developer may have studied:

    • population growth,
    • household formation,
    • income levels,
    • infrastructure,
    • competition,
    • buyer profiles,
    • pricing,
    • and future demand.

    Then the project goes through planning, approvals, construction and completion.

    By the time the keys are ready…

    The market may have changed.

    Buyers’ expectations change.

    Household sizes change.

    Working patterns change.

    Transport patterns change.

    Financing conditions change.

    Lifestyle preferences change.

    And competing developments enter the market.

    A product that looked attractive when the development was planned may not necessarily be equally attractive when it is completed.


    And this is where “affordable” becomes an interesting word

    The government has reported that properties priced RM300,000 and below accounted for 51.6% of residential transactions in H1 2026.

    At the same time, the government has acknowledged that completed unsold residential stock is not confined to high-end properties. It is also significant in affordable and mid-priced segments.

    So perhaps we need to distinguish between:

    Affordable by price

    and

    Affordable and desirable to the target buyer.

    They are not necessarily the same thing.

    A RM300,000 property may be affordable on paper.

    But if it is two hours from the buyer’s workplace…

    If public transport is poor…

    If the layout doesn’t suit the family…

    If the maintenance costs are too high…

    If financing is difficult…

    If the buyer doesn’t see future resale demand…

    Then the buyer may still decide:

    “This isn’t for me.”

    And that isn’t necessarily an affordability problem.

    It may be a product-market fit problem.


    This is where the PDS perspective comes in

    For years, much of the property industry has operated around a relatively simple sequence:

    Build → Market → Sell

    But perhaps we need to rethink the sequence.

    The PDS philosophy starts with a different question:

    Discover the buyer before you build for the buyer.

    Who exactly is the intended buyer?

    What problem are they trying to solve?

    Where do they want to live?

    What can they realistically afford?

    Can they obtain financing?

    What type of property fits their lifestyle?

    What compromises are they willing to make?

    What alternatives are available?

    What would make them choose this property over another?

    And perhaps most importantly:

    What evidence would give them confidence to make the decision?


    From “Selling Property” to “Helping Buyers Decide”

    This is a subtle but important shift.

    A traditional sales approach may ask:

    How do we sell this unit?

    A PDS approach asks:

    Why should this buyer choose this unit — and is it actually the right choice for them?

    That changes the conversation.

    Instead of starting with the brochure, we start with the buyer.

    Instead of starting with the promotion, we start with the problem.

    Instead of asking:

    “How much discount do we need to give?”

    we should also be asking:

    “Why isn’t the buyer convinced at the current value proposition?”

    Sometimes the answer may be price.

    Sometimes financing.

    Sometimes location.

    Sometimes product design.

    Sometimes timing.

    Sometimes competition.

    Sometimes eligibility.

    And sometimes the property simply isn’t solving a sufficiently important problem for the intended buyer.


    The Developer’s Question Should Change Too

    Perhaps developers should not only ask:

    “How many units can we sell?”

    They should ask:

    “How many units does this market actually need — and what type?”

    That means looking beyond headline demand.

    It means understanding:

    Demand

    → Who needs the property?

    Ability

    → Who can actually afford it?

    Eligibility

    → Who can legally or practically purchase it?

    Financing

    → Who can obtain the required loan?

    Location

    → Who wants to live there?

    Product

    → What configuration do they want?

    Value

    → Does the property justify the price?

    Confidence

    → What information does the buyer need before deciding?

    This is a much more complete view of property demand.


    The Real Property Overhang May Be an Alignment Problem

    Perhaps Malaysia doesn’t simply have a shortage of buyers.

    Perhaps we have a shortage of alignment.

    Alignment between:

    What developers build

    and

    what buyers actually want.

    Between:

    Price

    and

    purchasing power.

    Between:

    Location

    and

    daily life.

    Between:

    Product

    and

    lifestyle.

    Between:

    Eligibility

    and

    the available buyer pool.

    Between:

    financing

    and

    the buyer’s financial profile.

    And ultimately:

    what is being offered

    and

    what the buyer is prepared to decide on.


    So, What Should We Do About the 33,094?

    I don’t think the answer is simply:

    “Make property cheaper.”

    Nor is it simply:

    “Give buyers more incentives.”

    And it certainly isn’t enough to say:

    “Malaysians aren’t buying.”

    We need to understand why each segment of unsold stock remains unsold.

    Because the solution to a financing problem is different from the solution to a location problem.

    The solution to a Bumiputera quota-release issue is different from the solution to a product-market mismatch.

    And the solution to an overpriced property is different from the solution to a property that is fairly priced but poorly positioned.

    One number can hide many different problems.

    That is why we need to go beyond the headline.


    The PDS Way

    At the Property Discovery System, we believe property decisions should begin with discovery, not selling.

    For buyers:

    Discover the market.
    Understand the property.
    Test the numbers.
    Assess the risks.
    Compare the alternatives.
    Then decide.

    For developers:

    Discover the demand.
    Understand the buyer.
    Design the right product.
    Position it correctly.
    Build trust.
    Then sell.

    Because the objective shouldn’t simply be to sell more properties.

    It should be to create better alignment between property supply and real buyer demand.


    The question we should really be asking

    The headline today is:

    33,094 completed homes remain unsold.

    But perhaps the more important question is:

    Why are these particular homes still unsold?

    Until we answer that question at the unit, project, location, price, financing and buyer level, we risk treating very different problems as if they were the same problem.

    And if we keep treating the symptoms instead of understanding the buyer…

    We may simply build another 33,094 homes to replace them.

    Property is not just about selling a product.

    It is about helping people make better decisions.

    Discover Better. Decide Smarter.

    That is the PDS way.


    Sources &

    • National Property Information Centre (NAPIC), Property Market Report H1 2026. NAPIC — H1 2026 Property Market Report
    • Ministry of Finance Malaysia, launch remarks on the H1 2026 Property Market Report.
    • REHDA Property Industry Survey 1H2026, reported by EdgeProp.
    • Penang State Housing Board, Guidelines for Application for Release of Bumiputera Quota.

  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    Week in Review | 19–25 September 2026

    Malaysia • Regional Property • Global Insights

    The property market is not one market. Different assets, locations and economic forces are moving in very different directions.


    🇲🇾 1. Almost 60% of Developers Report Unsold Completed Homes

    https://images.openai.com/static-rsc-4/uJ1sXQYW8YNgLMcTGhfcD4h9AlGny1gVvYl0-3Z_UUWwYtxe0L-njDRK6hbq_nQHxshYIf8luumPsz7hwaFkeeFnY-h9INrh1M3Wsc166NXJCu6itg6Pu3naU9MIZA6kT81KGWzDrYNL-2laiMsgo-gFVvv0qAxul-Ei9rdVdXRqEG6ZpH0OrMh_BYhREWGV?purpose=fullsize

    What Happened

    A new REHDA Property Industry Survey found that 59% of 181 developers surveyed had unsold completed residential units as at 30 June 2026.

    The three main reasons cited were rejected end-financing applications, property prices and unreleased Bumiputera units.

    During the survey period, 54 respondents launched 15,834 units and sold 5,260 units, giving a take-up rate of 33.2%, only slightly higher than 32.2% previously.

    REHDA also highlighted rising construction costs, financing constraints and regulatory/compliance costs as pressures on housing affordability. An average 13% increase in construction costs was reported between March and June.

    Why It Matters

    This is an important distinction:

    A home can be “affordable” on paper but still unaffordable to the buyer.

    If financing is rejected, margins are lower or credit requirements become more difficult, the advertised selling price isn’t the whole affordability equation.

    For developers, unsold completed stock also ties up capital.

    Miichael’s Review

    This is exactly why I believe buyers should look beyond the headline price.

    Before deciding whether a property is affordable, ask:

    Can I actually obtain the financing?
    What is my monthly commitment?
    What happens if interest rates or my income situation changes?

    For developers, the lesson is equally important:

    Product pricing must match real purchasing power — not just construction cost plus desired margin.

    Source: EdgeProp — REHDA survey on unsold homes and EdgeProp — REHDA on housing costs


    🇲🇾 2. Johor: Paragon Globe Plans RM1.69 Billion Industrial Park

    What Happened

    Paragon Globe is pursuing additional land in Sedenak, Johor, for a proposed industrial park with an estimated gross development value of RM1.69 billion.

    The project sits within the Kulai-Sedenak zone of the Johor-Singapore Special Economic Zone (JS-SEZ) and is planned to include industrial factories, commercial components and worker accommodation.

    The group is also taking a more strategic approach to land development, looking at anchor occupiers and the ecosystems that can form around them, rather than simply developing land in isolation.

    Why It Matters

    This is bigger than another industrial-property announcement.

    The interesting part is the “anchor occupier” strategy.

    A major manufacturer can create demand for:

    • suppliers
    • logistics
    • warehouses
    • worker accommodation
    • retail
    • supporting services

    That can turn an industrial site into an economic ecosystem.

    Miichael’s Review

    This is the kind of development strategy I find interesting.

    The best land doesn’t necessarily have the highest GDV.

    Sometimes the real question is:

    “What economic activity will this land create around itself?”

    That is a much more powerful way to assess long-term land value.

    Source: The Star — Paragon Globe eyes RM1.69bil industrial park; EdgeProp — Paragon Globe landbank strategy


    🇲🇾 3. Klang: Maybulk Moves Into Industrial Property

    What Happened

    Maybulk has proposed acquiring an 8,346 sq m freehold industrial property in Bandar Bukit Raja, Klang, for RM35.5 million.

    The property includes an industrial building, warehouse and office facilities.

    Importantly, Maybulk said the move is part of a strategy to diversify its revenue streams and reduce reliance on its existing shipping and storage businesses.

    The acquisition would also immediately provide rental income once completed.

    Why It Matters

    This is a smaller transaction than the headline billion-ringgit deals — but strategically, it is very interesting.

    We’re seeing a company from outside traditional property development use industrial real estate as an income-producing asset.

    That reflects the growing attractiveness of industrial property as an investment class.

    Miichael’s Review

    I always find these transactions worth watching because they show how corporate investors think about property differently from individual buyers.

    For a corporate investor, property can be:

    An operating asset + rental income + capital preservation + diversification.

    That is very different from buying a property simply because “the area is going up.”

    Source: The Star — Maybulk proposes RM35.5mil Klang industrial acquisition


    🌏 4. Australia: The Housing Slowdown Is Hitting More Than Property Agents

    https://images.openai.com/static-rsc-4/Brs6pRtz5kYYyfE4NHjlwNYzDeZsQhdHN8Ay_xpJgbljRtmXqHfXrQ0ZJ7iHrrLLQKWOe0izOsryIQPmdtGfKgsZshly6_Y3bJOYhnrsCRXXrUXpoyniGMpBU6UiTg5U1rpeUgc7Zw_F7zL8TwPXur-FNtdpsHx7XF08Uo8dO-6FZFqw6SGoo2PIJCj64MzF?purpose=fullsize

    What Happened

    Australia’s housing slowdown is now affecting a much wider economic ecosystem.

    Reuters reported that Australian home sales volumes have fallen sharply, with turnover 15% below a year earlier in July/August and 10.5% below the five-year average.

    Reuters estimates that the reduction in housing activity could remove around A$2.8 billion to A$5.6 billion of annual spending from businesses connected to property transactions — including removalists, conveyancers, furniture retailers, tradespeople and renovation businesses.

    The important point is that prices themselves have not collapsed: Reuters reported prices were less than 4% below the March peak and still above year-ago levels. The bigger issue is fewer transactions.

    Why It Matters

    This is a fascinating distinction:

    Property prices can remain relatively resilient while the property economy slows dramatically.

    If fewer people buy and sell, many businesses around the property ecosystem suffer.

    Miichael’s Review

    This is a useful lesson for Malaysia too.

    When we analyse a property market, we shouldn’t look only at:

    “Are prices rising?”

    We should also watch:

    transaction volume, financing, turnover, inventory and buyer confidence.

    A market can look healthy from a price chart while becoming much less active underneath.

    Source: Reuters — Australia’s housing slowdown and wider economic impact


    🌏 5. UK Housing: Prices Bounce, But Buyers Remain Selective

    https://images.openai.com/static-rsc-4/AEe5M10FcR-kJRCayCQU6MvkhNhkoA3_xw2GGp_f6LLLxiydkqrUYPQL63QZdaCxQoINy6jL0mpDitHMoiolKW5iBFZCF_fbHycfkm-eMLNzJIn4oybRTkZ_P3qO1zOmbgx6hiVX8Ce5o71Tg2Q2XS9ZjNv5XPC_Gl731cYvpOuShOgWgt_lYJuEbdKNQVeu?purpose=fullsize

    What Happened

    UK asking prices rose 0.7% in September, equivalent to about £2,441, according to Rightmove data reported by The Times.

    The average asking price reached approximately £367,440.

    But the headline increase needs context: prices remained 0.8% below a year earlier, while housing supply was reported to be at a 12-year high.

    Why It Matters

    More supply gives buyers more choice — and therefore more negotiating power.

    A seller cannot simply assume that a higher asking price will translate into a higher achieved price.

    Miichael’s Review

    This is one of my favourite property lessons:

    The asking price is not necessarily the market value.

    When supply rises and buyers become more selective, pricing strategy becomes increasingly important.

    For investors, this also reinforces the need to distinguish between:

    headline price movement and actual market liquidity.

    Source: The Times — UK house prices rise for first time since May


    📊 PROPERTY NUMBER OF THE WEEK

    59%

    The percentage of surveyed Malaysian developers reporting unsold completed residential units.

    But the more interesting number may be:

    33.2%

    The reported take-up rate during the REHDA survey period.

    The lesson: demand exists — but buyers are becoming increasingly constrained by financing, affordability and product suitability.


    👀 WORTH WATCHING

    🇲🇾 Malaysia

    1. Housing affordability
    Will financing accessibility improve enough to reduce completed unsold stock?

    2. Johor industrial property
    Watch how the JS-SEZ develops around actual occupiers and employment rather than simply land speculation.

    3. Klang industrial assets
    Will more corporates diversify into income-producing industrial property?

    🌏 International

    4. Australia
    Whether weak transaction volumes persist even if prices remain relatively resilient.

    5. UK
    Whether increased housing supply eventually translates into more realistic pricing.


    💡 MIICHAEL’S TAKEAWAY

    This week gives us five very different property stories.

    Housing affordability.
    Industrial land strategy.
    Corporate property investment.
    Australia’s transaction slowdown.
    UK supply and pricing.

    And that’s exactly why I don’t believe we should talk about “the property market” as though it is one single thing.

    Different sectors behave differently.

    Different locations behave differently.

    And most importantly, different buyers have different problems.

    For someone buying a home, financing and affordability may matter most.

    For an investor, rental income and liquidity may matter more.

    For a developer, land cost, product positioning and absorption may determine success.

    And for a corporate investor, property may simply be another asset class for diversification.

    So perhaps the better question isn’t:

    “Is property a good investment?”

    It is:

    “Which property, in which location, for what purpose — and under what market conditions?”

    That is where better property decisions begin.

    Miichael Yeoh

    Property Strategist

  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    Week in Review | 12–18 September 2026

    Malaysia • Regional Property • Global Insights

    The property market is bigger than house prices. Follow the money, the people and the assets.


    🇲🇾 1. KIP REIT: Retail Property Is Being Repositioned, Not Abandoned

    https://images.openai.com/static-rsc-4/FE3MJchSQotX9YuPbZPIptH2f3klwx57hOtiag2TrNWJqNoH_DJyzrHa7K8Vf0R5R59-cWO0p0wq2ag0mRP_tqj2NvEL8yA4sLbNgXWMvdynUaBGhfgMFI9IrOCiEMIe14OC3bExGI0mfAT00kd2GuHIlQ46ZNiGwPp00pgOSI0UV6qfJd8-Vrq6nlCryRjt?purpose=fullsize

    What Happened

    KIP REIT plans asset enhancement initiatives at three malls — KIPMall Masai, KIPMall Kota Warisan and AEON Mall Kinta City.

    The strategy is aimed at improving operational efficiency and supporting longer-term rental growth.

    There is another interesting move: KIP REIT is targeting completion of its RM435 million acquisition of Setapak Central Mall, which would be its largest acquisition to date and take assets under management to about RM2.2 billion.

    Why It Matters

    Retail property is often written off as “old economy”.

    But successful malls are increasingly becoming community infrastructure — food, services, groceries, healthcare, entertainment and daily necessities.

    The question isn’t simply:

    “Is shopping mall demand declining?”

    It should be:

    “Can the asset remain relevant to its surrounding population?”

    Miichael’s Review

    This is something I find particularly interesting.

    Property owners don’t always need to build something new to create value.

    Sometimes, repositioning an existing asset can be the smarter strategy.

    Source: EdgeProp, 18 September 2026.


    🇲🇾 2. RM475 Million Sukuk: Affordable Housing Needs Capital Too

    https://images.openai.com/static-rsc-4/qZnwyXfXtbssVeM0gJ0UyMNoQ_HOxzgGPPQ7VJoTwrJYrEoEtoVE5gdnAwYgBxswD2HlM1X_3PortDlviTMSly0x0BG3yPCgk_eCc2onB607e5S7XRRhYTpPkA6NO631rPH7rlBvpvcO_MY3VPoVQFihdmjB9NJu05BHNuIg-s-3xMn04WrPYYRufXekwqeN?purpose=fullsize

    What Happened

    Lagenda Properties has completed its first RM475 million sukuk issuance under a larger RM1.5 billion Sukuk Wakalah programme.

    The proceeds will be used for acquisitions, working capital and affordable housing developments.

    Why It Matters

    Affordable housing is sometimes discussed only from the buyer affordability perspective.

    But there is another side:

    How do developers finance affordable housing profitably and sustainably?

    If construction costs, land costs and financing costs continue rising, access to capital becomes critical.

    Miichael’s Review

    I like this story because it reminds us that property is not just about selling houses.

    There is an entire financial ecosystem behind every development:

    Land → Financing → Construction → Sales → Delivery → Exit

    Understanding that chain helps us understand why some developers can keep expanding while others struggle.

    Source: EdgeProp, 18 September 2026.


    🇲🇾 3. Glomac Returns to Profit — A Reminder to Watch Developer Health

    https://images.openai.com/static-rsc-4/hnQvi8sM8duuJGU7EE09eEA36eU0yr074Tx8dEJcKR2F7ILr4VKSjElTjjxtlcn3QJQdPXunhBy9_mroevHS0x5o-iUlk9xfvSJUPvTiezwh2azShtwakbqaJPSEYhlQSMnPyHSZwi8jbeYzgtp2Pd2xVk4516ALCQ8bw_BUs3zAVSohSS6Gl3imZ6u4dLlt?purpose=fullsize

    What Happened

    Glomac returned to the black in its first quarter of FY2027.

    Net profit attributable to owners reached RM7.6 million, compared with a RM1.42 million loss a year earlier.

    Revenue jumped 163% to RM68.53 million, with property-development revenue more than tripling to RM61.12 million.

    More encouragingly, borrowings fell from RM237.0 million at end-April to RM224.4 million at end-July, while cash and short-term placements stood at RM249.5 million.

    Why It Matters

    When considering a new development, buyers often focus on:

    • Location
    • Price
    • Facilities
    • Discounts

    But one question is frequently overlooked:

    Who is the developer and how financially healthy are they?

    Miichael’s Review

    A property doesn’t exist in isolation.

    The developer’s financial strength can influence construction progress, delivery, future phases and ultimately buyer confidence.

    For me, developer due diligence should be part of property due diligence.

    Source: EdgeProp, 18 September 2026.

    Click to register for the event : Before You Buy The Next Property

    🌏 4. IOI Properties Completes RM7.95 Billion Singapore Acquisition

    https://images.openai.com/static-rsc-4/7j-qiqH5s-9fqzlWqqPjPu0gubzytRjTSa-z9FzFkzCY4JuXy0-_8k-YRET5NwzKFZN6ihhpa-hFs75TrZ0n0XmFNJRnsbK0aBT9ZmjBooxH-bObKpUK7VBqOT-zLJaczPypqBxU-ZY4TlMgtIESgNalyPHFs6aHOVdFgkBfSYiKWiNQwf0Tt04iqT_ynaPS?purpose=fullsize

    What Happened

    IOI Properties Group has completed its acquisition of the company owning Asia Square Tower 2 in Singapore.

    The total cash outlay was approximately S$2.47 billion — around RM7.95 billion.

    The 46-storey integrated development at Marina View includes Grade A offices, retail space and parking, with approximately 773,000 sq ft of net lettable area.

    Why It Matters

    This is much bigger than a Malaysian developer buying an overseas building.

    It demonstrates how Malaysian property groups are increasingly looking beyond Malaysia for income-producing assets and geographical diversification.

    Miichael’s Review

    I find this particularly relevant to Malaysian investors.

    The property industry is becoming increasingly global.

    A Malaysian developer today may have:

    Residential → Industrial → Retail → Office → REIT → Overseas Assets

    That diversification can create resilience — but only if the company understands the market it is entering.

    And there’s another lesson:

    Sometimes the best property opportunity isn’t a new development. It is an existing income-producing asset.

    Source: EdgeProp, 18 September 2026.


    🌏 5. Australia: Housing Values Fall as Higher Rates Bite

    https://images.openai.com/static-rsc-4/tVw9lLv91mbn3JLpF70gDBGvznn3NWOzDDSpHHWno1XnMJhtSsSSmf-BQol8V87QgZ7WSIZ_8xGAvFRUz-ycM2WgAIL7VSxDWKCgGczsTze7JQUh5mVe392M6oH6yBjG9Xz8_rGoRcdZf95cyiekidEuP5Q0jq0UdUbz2PjmSs0xGj_u8oooZcQj9QSwrd8d?purpose=fullsize

    What Happened

    Australia’s housing market is showing signs of meaningful weakness.

    The latest Australian Bureau of Statistics data showed the total value of residential dwellings fell A$34.1 billion, or 0.3%, in the June quarter to A$12.69 trillion.

    The mean dwelling price fell 0.7% to A$1.10 million.

    New South Wales saw the mean dwelling price fall 2.4%, while Victoria fell 2.1%.

    And this week, the Reserve Bank of Australia’s governor warned that inflation risks are returning, keeping the possibility of further interest-rate tightening alive.

    Why It Matters

    This is a useful reminder for Malaysian property investors who look overseas.

    A country can have:

    Strong population + housing shortage + high property prices

    …and still experience falling values when financing conditions change.

    Miichael’s Review

    This is exactly why I keep saying:

    Property is a long-term financial commitment, not just a location decision.

    Interest rates can change the affordability equation very quickly.

    Source: Australian Bureau of Statistics and Reuters, September 2026.


    📊 PROPERTY NUMBER OF THE WEEK

    RM7.95 BILLION

    The approximate cash outlay by IOI Properties for Asia Square Tower 2 in Singapore.

    That’s not just a property transaction.

    It’s a statement about where Malaysian property companies are looking for growth.


    👀 WORTH WATCHING

    1. Malaysian REITs

    Will more REITs reposition existing retail and commercial assets instead of simply acquiring new properties?

    2. Affordable Housing

    Can developers continue delivering affordable homes while land, construction and financing costs remain elevated?

    3. Johor

    Land banking and development activity around the Johor-Singapore economic corridor remain worth watching.

    4. Interest Rates

    Australia’s renewed inflation concerns show how quickly monetary policy can change property-market sentiment.

    5. Malaysian Developers Going Overseas

    Will more Malaysian developers follow IOI Properties into Singapore and other regional markets?


    💡 MIICHAEL’S TAKEAWAY THIS WEEK

    This week’s five stories are deliberately very different.

    And that’s exactly what makes the property market interesting.

    We have:

    Retail repositioning.
    Affordable housing finance.
    Developer financial health.
    A RM7.95 billion overseas acquisition.
    And a housing market reacting to interest rates.

    Put them together and one thing becomes clear:

    There is no single “property market”.

    Different property sectors behave differently.

    Different states behave differently.

    Different countries behave differently.

    And different investors have different objectives.

    So rather than asking:

    “Is property going up or down?”

    Perhaps the better question is:

    “Which property, in which location, for which purpose, under which economic conditions?”

    That’s where better property decisions begin.

    Miichael Yeoh

    Property Strategist

  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    Week in Review | 5–11 September 2026

    Malaysia Property • Global Insights • Better Decisions

    Hi everyone,

    This week’s stories remind us that property isn’t driven by headlines alone. A stronger market comes from healthy demand, smart capital, sustainable buildings and confidence in the wider economy.

    Here are the 5 developments I believe are most meaningful for buyers, investors and property professionals this week.

    🇲🇾 1. Malaysia’s Property Market Tops RM105 Billion

    Sky Meridien Residence @ Sentul East Renovated Condo For Sale RM950K | Malaysia Property and Real Estate

    What Happened?

    Malaysia recorded 187,320 property transactions worth RM105.12 billion during the first half of 2026.

    However, there is another number worth paying attention to: 33,094 completed residential units remain unsold, an increase of 8.6% from the previous period.

    Why It Matters

    A busy market does not mean every project is successful. The difference between transaction volume and sales absorption tells us buyers are becoming much more selective.

    Miichael’s Review

    When people ask whether the property market is good or bad, my answer is usually:

    “Which market are we talking about?”

    A healthy property decision begins with understanding demand, supply and affordability—not simply following price movements.

    Source: JPPH 1H 2026 Property Market Report.

    🇲🇾 2. A RM331 Million Office Deal Signals Confidence in KL Commercial Property

    Knight Frank

    What Happened?

    AmFIRST REIT is seeking unitholder approval to dispose of Menara AmBank in Kuala Lumpur for RM331 million. The transaction is one of the more significant commercial office deals announced this week.

    Why It Matters

    Commercial property often gives us an early indication of how institutional investors view the market. Capital recycling allows REITs to strengthen balance sheets and reposition their portfolios.

    Miichael’s Review

    Residential property usually receives the attention, but I always watch office and commercial transactions closely.

    Large institutional deals often tell us where long-term confidence is moving before the broader market notices.

    Source: The Star Business

    🇲🇾 3. Green Buildings May Soon Receive New Tax Incentives

    Eco-Friendly Buildings in Malaysia: Worth the Cost? | Rummah.my

    What Happened?

    The Housing Ministry has submitted proposals for new tax incentives to encourage greener building development ahead of Budget 2026. The initiative aims to accelerate sustainable construction and improve environmental performance across future projects

    Why It Matters

    Sustainability is gradually becoming a financial consideration, not just an environmental one. Incentives could influence developer decisions, construction costs and buyer demand over time.

    Miichael’s Review

    I believe future property value will increasingly include another question:

    “Is this building sustainable enough to remain competitive 20 years from now?”

    Green features may become part of long-term asset value—not simply a marketing brochure.

    Source: The Star, 5 September 2026.

    🌏 4. Australia’s Housing Sector Faces a Reality Check

    Housing

    What Happened?

    Australian housing developer Bathla stood down more than 200 employees as financial pressure continues affecting parts of the residential development sector. The story highlights the challenges facing developers despite ongoing housing shortages.

    Why It Matters

    Housing demand alone doesn’t guarantee developer profitability. Rising construction costs, financing pressure and project cash flow remain critical risks.

    Miichael’s Review

    This is an important reminder for investors:

    A strong housing market and a strong development business are not always the same thing.

    Always understand the developer’s financial strength—not just the project.

    Source: The Guardian Australia.

    🌏 5. Global Markets Are Watching Interest Rates Closely

    Benefit Street Partners

    What Happened?

    Global investors are closely watching upcoming US Federal Reserve decisions, while Malaysia has maintained its OPR at 2.75%, providing relative stability for domestic borrowers.

    Why It Matters

    Interest rates influence mortgage affordability, investment returns and foreign capital flows. Even when Bank Negara holds rates steady, global monetary policy still affects market sentiment.

    Miichael’s Review

    Rather than asking whether rates will rise or fall, buyers should ask:

    “Can I comfortably afford this property if rates stay higher for longer?”

    That is a much healthier way to evaluate risk.

    Source: WSJ & Bank Negara Malaysia.

    📊 Property Number of the Week

    Transactions

    187,320

    Properties transacted in 1H 2026

    Market Value

    RM105.1B

    Total transaction value nationwide

    Commercial Deal

    RM331M

    Proposed Menara AmBank disposal

    Policy Focus

    Green Incentives

    Potential boost for sustainable buildings

    👀 Worth Watching

    Over the coming weeks, I’ll be watching:

    • Budget 2026 housing and green-building incentives
    • More institutional commercial property transactions
    • Whether unsold residential stock begins to decline
    • Global interest-rate direction and its impact on mortgages

    💡 My Takeaway This Week

    This week isn’t about one spectacular property launch.

    It’s about confidence.

    Confidence from homebuyers. Confidence from institutional investors. Confidence in sustainable development. And confidence created by stable economic policy.

    As buyers, I believe we should always ask one question before making a decision:

    “Will this property still make sense 10 years from today?”

    That question often matters more than today’s promotional price.

    Miichael Yeoh

    PROPERTY STRATEGIST

    🌐 http://www.miichaelyeoh.com

  • WEEKLY PROPERTY ROUNDUP | Week in Review (29 August – 4 September 2026)

    WEEKLY PROPERTY ROUNDUP | Week in Review (29 August – 4 September 2026)

    Top 3 developments I believe every buyer and investor should know

    Good morning everyone,

    Every week, I try to answer one simple question:

    What really matters in Malaysia’s property market?

    The biggest lesson from the past week is this: property value is increasingly created by infrastructure, employment and the quality of the surrounding ecosystem—not just by the building itself.

    Here are the Top 3 developments I believe every buyer and investor should know.

    1. Malaysia’s Industrial Growth Continues to Drive Property Demand

    Malaysia's semiconductor industry development strategy

    What happened?

    Malaysia’s advanced manufacturing and semiconductor sectors continued attracting new investment, with Penang remaining one of the country’s strongest industrial growth regions. Industry reports show industrial investment remains concentrated in high-value manufacturing, electronics and supply-chain expansion.

    Why it matters

    Industrial growth doesn’t just create factories—it creates jobs, talent, housing demand, logistics, retail and commercial activity. Historically, areas experiencing sustained employment growth tend to enjoy healthier long-term property demand than areas driven purely by speculation.

    Miichael’s Review

    Many buyers ask me:

    “Which project will appreciate the most?”

    I think the better question is:

    “Where will people still be working five to ten years from now?”

    Follow employment before following property prices.

    Source: Industrial investment & manufacturing reports.

    2. Urban Regeneration Is Becoming the New Growth Story

    Malaysia Real Estate & Property in Seremban | Bandar Sri Sendayan

    What happened?

    Developers continue investing in mixed-use regeneration projects within mature townships rather than expanding endlessly into new suburbs. Projects like PJ Quarter demonstrate a growing focus on integrating residential, retail, public spaces and community facilities into established neighbourhoods.

    Source: EdgeProp

    Why it matters

    Today’s buyers increasingly value:

    • Walkability
    • Public transport
    • Healthcare & education
    • Lifestyle convenience
    • Community spaces

    These factors often contribute more to sustainable demand than simply having a prestigious address.

    Miichael’s Review

    A property’s postcode is important.

    But its ecosystem is even more valuable.

    That’s where long-term liveability and resale demand are created.

    Source: Developer announcement & urban regeneration reports.

    3. Digital Infrastructure Is Quietly Changing Land Value

    支持AI算力部署!万国数据马来西亚努沙再也科技园数据中心园区(二期)正式投运 - 万国数据服务有限公司

    What happened?

    Malaysia’s digital infrastructure momentum continues as developers and institutional investors increasingly recognise the strategic value of land supported by power capacity, fibre connectivity and industrial infrastructure. Data centres remain one of the strongest emerging land-demand drivers across several Malaysian states.

    Why it matters

    The next property growth story may not begin with another condominium launch.

    It may begin with:

    • Power infrastructure
    • Data connectivity
    • AI & cloud investment
    • Industrial ecosystem
    • Business expansion

    Miichael’s Review

    The opportunity isn’t owning a data centre.

    The opportunity is identifying the surrounding locations that benefit from the jobs, businesses and services that follow.

    That’s where long-term property value is often created.

    Source: Digital infrastructure & property investment reports.

    📊 Property Snapshot This Week

    Industrial Investment

    Strong

    Advanced manufacturing continues supporting property demand.

    Growth Focus

    Mature Townships

    Urban regeneration is attracting developer investment.

    Emerging Driver

    Data Centres

    Power & connectivity are becoming strategic land assets.

    Buyer Trend

    More Selective

    Buyers are placing greater emphasis on long-term value.

    👀 Worth Watching

    Over the coming weeks, I’ll be watching four areas closely:

    • Expansion of Malaysia’s semiconductor ecosystem
    • New mixed-use regeneration projects
    • Data-centre related land acquisitions
    • Locations where employment growth translates into genuine housing demand

    These will likely become the next wave of meaningful property stories.

    🎯 My Takeaway This Week

    Three different stories.

    Industrial growth. Urban regeneration. Digital infrastructure.

    But they all point to one conclusion:

    Don’t evaluate the property in isolation. Evaluate the ecosystem that supports it.

    Before buying, I would always ask:

    • Where will the jobs come from?
    • Is infrastructure improving?
    • Will people genuinely want to live or work here?
    • What creates demand five years from today?

    That’s where better property decisions begin.

    Miichael Yeoh

    PROPERTY STRATEGIST

    🌐 http://www.miichaelyeoh.com

    Thank you for subscribing!

    Please check your email to confirming your subscription.

  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    Week in Review | 22–28 August 2026

    Hi Everyone.

    This week’s property market highlights show one clear trend: the future value of property is increasingly being shaped by infrastructure, digital investment and the quality of the surrounding ecosystem.

    Here are the Top 5 developments that caught my attention.

    Looking down onto KLCC

    1. Data centres are redefining land value

    Mah Sing agreed to sell 78.8 acres of land at Southville City, Selangor, for approximately RM617.9 million to an international digital infrastructure group for data-centre development.

    Why it matters

    Land is no longer valued only for residential or commercial potential. Power capacity, fibre connectivity and digital infrastructure are becoming major value drivers.

    Miichael’s Review

    The real opportunity isn’t owning a data centre—it’s identifying the surrounding locations that will benefit from the jobs, businesses and ecosystem that follow.

    Aerial and ground view of high-voltage transmission towers in rural Malaysia, showing electricity infrastructure and power distribution network under bright sky.

    2. PJ Quarter brings new life to an established township

    Frasers Property and Tan & Tan announced PJ Quarter, a 5.15-hectare mixed-use redevelopment in Section 13, Petaling Jaya, integrating homes, retail, parks and community spaces.

    Why it matters

    This is a classic example of urban regeneration—creating value by improving the overall neighbourhood rather than simply building another project.

    Miichael’s Review

    A great location is more than an address. Sustainable value comes from the ecosystem around it: transport, education, healthcare, employment and lifestyle.

    Kepong New Condo Property Development | M Nova

    3. Malaysia’s industrial economy continues to support property demand

    Manufacturing and advanced industries continue to strengthen Malaysia’s investment landscape, particularly in Penang and key industrial corridors, reinforcing long-term demand for industrial and supporting residential property.

    Miichael’s Review

    Economic growth creates opportunities—but not every property benefits equally. Follow where employment and business investment are genuinely expanding.

    Johor Manufacturing - BizVantage 360 Malaysia

    4. Buyers are becoming more selective

    Developers and analysts continue to observe that today’s buyers are taking longer to make decisions, comparing projects more carefully and placing greater emphasis on affordability and long-term value.

    Miichael’s Review

    This is a healthy change. Instead of asking “Which project is the hottest?” buyers are beginning to ask “Which property makes the most sense for me?”

    Married couple reading carefully contract terms of conditions.

    5. The definition of property opportunity is changing

    Across this week’s stories, one message stands out: value is increasingly created by connectivity, infrastructure, regulation and economic activity, not simply by location alone.

    Miichael’s Review

    I believe the next successful property investor will not be the one who buys the most properties.

    It will be the one who understands why demand will exist five to ten years from now.

    Exploring the MRT Putrajaya : All you need to know about MRT Putrajaya in 2025! | PropertyGenie

    👀 Worth Watching

    I’ll be watching three areas over the coming weeks:

    • Growth of Malaysia’s digital infrastructure ecosystem
    • New urban regeneration projects in mature townships
    • Industrial investment creating new residential demand

    🎯 My Takeaway This Week

    The biggest lesson from this week is simple:

    Don’t just evaluate the property. Evaluate the ecosystem that supports it.

    Infrastructure, employment, connectivity and community are becoming the real foundations of long-term property value.

    That’s where better property decisions begin.

    Miichael Yeoh

    PROPERTY STRATEGIST