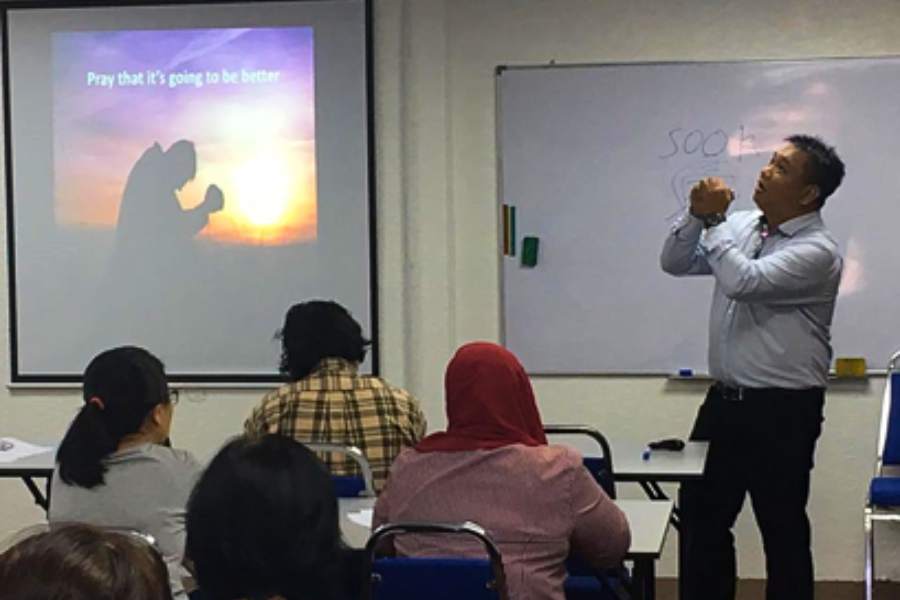
In the picture, what do you think I am doing? Praying for the money to drop
I do not really depend on these. I don’t think money will suddenly drop from the sky or hoping for a miracle to happen. If a car were to break down, you will need a mechanic to fix the problem. He will have to follow a series of steps in doing repair and to make sure your car is running again.
Likewise, in mortgage approval you cannot wait for miracle things to happen. To me, luck have nothing to do on mortgage approval. Many borrowers and agents, prefer to photocopy many stacks of financial documents and give to every bank they know off or can find and submit to them for approval. Is this the right way?
Do you know that every time your documents are submitted, the banks will record and send to Bank Negara which in turn will update the Central Credit Information System (CCRIS) every month? No matter whether your loan is approved or rejected it will be updated on the last page of your record. Let’s say Bank A rejects your loan, Bank B,C and D also rejects but Bank E actually can approve your loan but seeing so many banks rejected your loan the chances are they will also reject your loan.
Never expose yourself. Every bank have different approval criteria. Some banks might not like you but some does. I have a case once, his Debt Service Ratio is very high at 150% in which is higher than the normal 70-85%. Either the banks rejects or do not want to waste time processing his case. I reviewed his documents and to cut things short, I managed to get 70% loan approval. This case is a fine example where the borrower will have to do the following:
Do a Know yourself (KYS) test.
Check your credit status
Check which bank is suitable for you.
You will have to do more work on the last step. You will need to find out each bank approval criteria and also the different types of documents for approval. You are not buying a RM1,000 property but hundreds or even millions worth of property. It is good to do a research first. It is hard to go back when your loan had been rejected. It is easier to diagnose a problem first.
Without a doubt, your mortgage represents one of the most significant financial commitments you’ll undertake. Over its lifespan, the interest paid to the bank alone can skyrocket into tens of thousands. Consider this: by adhering to a 30-year home loan term, you may ultimately shell out twice the original loan amount in total.
Did you know that within the first five years of a 30-year loan, you’re likely to reduce only about 7% of the principal? Even by the 20th year, you might still be grappling with less than half. It’s high time to reclaim control over your loan and expedite its repayment to save substantial sums in interest.
Gone are the days of rigid loan structures prevalent from the 1960s to the 1990s. Today, borrowers have access to a plethora of tools and flexible bank policies, enabling them to slash down loan tenures.
The sooner you bid farewell to your home loan, the sooner you’ll inch closer to retirement and debt-free living. While myriad methods exist to accelerate repayment, not all may be a perfect fit for your situation. It’s imperative to conduct thorough research and select the strategies best aligned with your needs.
Here are some actionable ways to expedite home loan repayment:
Making Extra Payments: Witness the magic unfold by utilizing a mortgage calculator to see how even modest additional monthly payments can drastically reduce interest and hasten home loan repayment. Remember, every dollar directed towards the principal shrinks the interest burden and speeds up loan clearance
Refinance: Take advantage of prevailing lower interest rates by refinancing your loan. Use a mortgage calculator to gauge potential interest savings, but don’t forget to factor in associated costs like penalties and legal fees.
Negotiate Interest Rate Adjustments: Keep a keen eye on interest rate fluctuations and consider negotiating with your bank for a reduction. Maintaining current installment amounts despite rate reductions can substantially reduce repayment years
Utilize Flexi Mortgages: Explore flexible mortgage options like the Flexi Mortgage or Money Merge Account, where daily interest calculations and account consolidation accelerate principal reduction, thus shortening loan tenure.
Interest Rate Adjustments: Strategize responses to fluctuating interest rates by either increasing monthly installments to maintain repayment duration or maintaining installments to reduce repayment years.
EPF Withdrawals: Tap into your EPF Account II to swiftly reduce principal and expedite loan repayment. This can even be arranged on a monthly basis for added convenience. In Malaysia it is called EPF or Employee Provident Fund. Its a retirement saving account.
Continuous Monitoring and Adjustment: Regularly monitor your loan progress and financial situation, adjusting strategies as needed to optimize repayment efficiency.
Bi-Weekly Payments: Divide your monthly installment into bi-weekly payments, effectively making 13 monthly payments annually. This simple adjustment can shave off at least four years from a typical 30-year loan term, although availability may vary by region. Please take note that not every country has this package.
By diligently implementing these strategies, you can significantly alleviate the burden of your home loan and pave the way towards financial freedom.
Financial planning is the cornerstone of a secure and prosperous future. It involves setting realistic goals, creating a roadmap to achieve them, and making informed decisions about your money. Whether you’re just starting your career or nearing retirement, having a solid financial plan in place is essential for building wealth, managing risks, and achieving financial independence. In this article, we’ll explore the key components of financial planning and provide actionable tips to help you navigate your financial journey with confidence.
1. Assess Your Current Financial Situation: The first step in financial planning is to assess your current financial situation. Take stock of your income, expenses, assets, and liabilities. Create a detailed budget to track your spending habits and identify areas where you can save money. Calculate your net worth by subtracting your liabilities from your assets. This snapshot of your finances will help you understand where you stand and identify areas for improvement.
2.Set SMART Financial Goals: Once you have a clear understanding of your financial situation, it’s time to set SMART (Specific, Measurable, Achievable, Relevant, Time-bound) financial goals. Whether it’s buying a home, saving for your children’s education, or planning for retirement, clearly define your goals and prioritize them based on their importance and urgency. Break down each goal into smaller, manageable milestones to track your progress along the way.
3.Create a Budget and Stick to It: A budget is a powerful tool that helps you allocate your income towards your financial goals while ensuring that you live within your means. Start by listing your fixed expenses such as rent/mortgage, utilities, and loan payments, then allocate a portion of your income towards savings and investments. Be mindful of discretionary spending and look for opportunities to cut unnecessary expenses. Regularly review and adjust your budget as your financial situation changes.
4. Build an Emergency Fund: Life is unpredictable, and unexpected expenses can derail your financial plans if you’re not prepared. That’s why it’s crucial to build an emergency fund to cover unforeseen expenses such as medical emergencies, car repairs, or job loss. Aim to save at least three to six months’ worth of living expenses in a liquid, accessible account like a savings account or money market fund. Having an emergency fund provides peace of mind and financial security during challenging times.
5. Manage Debt Wisely: Debt can be a significant obstacle to achieving your financial goals if not managed wisely. Prioritize paying off high-interest debt such as credit cards and personal loans to minimize interest payments and improve your financial health. Consider consolidating debt or negotiating lower interest rates to accelerate your debt repayment journey. Avoid taking on new debt unless absolutely necessary and use credit responsibly to build a positive credit history.
6. Invest for the Future: Investing is a powerful wealth-building tool that allows your money to grow over time through the power of compounding. Determine your risk tolerance and investment objectives, then develop a diversified investment portfolio tailored to your goals and timeline. Consider investing in a mix of stocks, bonds, mutual funds, and other asset classes to spread risk and maximize returns. Regularly review and rebalance your portfolio to ensure it remains aligned with your objectives.
7. Plan for Retirement: Retirement may seem far off, but it’s never too early to start planning for your golden years. Take advantage of employer-sponsored retirement plans such as 401(k)s or IRAs to save for retirement tax-efficiently. Contribute enough to qualify for employer matching contributions and increase your contributions over time as your income grows. Consider working with a financial advisor to develop a personalized retirement plan and explore options such as annuities or pension plans to supplement your retirement income.
8. Protect Yourself and Your Loved Ones: Insurance is an essential component of financial planning that provides protection against unforeseen events such as illness, disability, or death. Review your insurance coverage regularly to ensure it adequately protects you and your loved ones. Consider policies such as health insurance, life insurance, disability insurance, and long-term care insurance based on your needs and circumstances. Don’t overlook estate planning, including drafting a will and establishing powers of attorney to protect your assets and ensure your wishes are carried out.
Financial planning is a lifelong journey that requires diligence, discipline, and adaptability. By following these key principles and incorporating them into your financial strategy, you can take control of your finances, build wealth, and achieve your long-term goals. Remember that financial planning is not a one-time event but a continuous process that evolves with your life circumstances. Stay proactive, stay informed, and stay committed to securing your financial future.