Category: Financial Planning

  • Effects of OPR Changes on Borrowing and Savings

    Effects of OPR Changes on Borrowing and Savings

    As of January 2025, Bank Negara Malaysia (BNM) has maintained the Overnight Policy Rate (OPR) at 3.00%, a position held since May 2023.

    Understanding the Overnight Policy Rate (OPR)

    The OPR is the benchmark interest rate at which banks lend to one another overnight. Set by BNM, it serves as a primary monetary policy tool to regulate liquidity, control inflation, and sustain economic growth.

    Implications of an OPR Increase

    When BNM raises the OPR, it signals an intent to tighten monetary policy. The effects of such an increase include:

    Higher Borrowing Costs: Banks typically respond to an OPR hike by raising their base rates, leading to increased interest rates on loans and mortgages. This results in higher monthly repayments for borrowers.

    Enhanced Savings Returns: Conversely, depositors may benefit from higher interest earnings on savings and fixed deposits, encouraging increased savings.

    Controlled Inflation: Elevated borrowing costs can dampen consumer spending and business investments, helping to moderate demand-pull inflation.

    Currency Appreciation: Higher interest rates can attract foreign investment, potentially strengthening the Malaysian ringgit.

    Impact on Property Market: Increased interest rates may lead to higher mortgage costs, potentially cooling property demand and affecting market dynamics.
    Recent Economic Context

    In the third quarter of 2024, Malaysia’s economic growth slowed to 5.3% from 5.9% in the previous quarter, influenced by reduced oil and gas production. Despite this, robust household spending and increased investments provided support.

    BNM’s Monetary Policy Stance

    BNM has maintained the OPR at 3.00% since May 2023, citing positive economic growth and steady inflation. Economists anticipate that the central bank will keep the OPR unchanged until at least 2026, aligning with current economic assessments.

    Interest Rate Impact Example

    Let’s look at an example of how interest rates affect property loans. Assume you’re borrowing RM500,000 for 30 years:

    • Current Interest Rate (4.5%): Monthly repayment is approximately RM2,533.43.
    • If OPR Increases by 25 Basis Points (4.75%): Monthly repayment rises to around RM2,608.82.
    • Impact: This increase of RM75.39 per month adds up to RM27,140.40 over the loan’s term.

    This illustrates why understanding interest rates and their potential changes is crucial for planning your finances.

    Conclusion

    An increase in Malaysia’s OPR has multifaceted effects, influencing borrowing costs, savings returns, inflation, currency value, and the property market. Understanding these dynamics is crucial for individuals and businesses to make informed financial decisions in response to monetary policy changes.

    From the Desk of

    Miichael Yeoh
  • Avoid Costly Mistakes: 8 Reasons to Learn Before Investing in Real Estate

    Avoid Costly Mistakes: 8 Reasons to Learn Before Investing in Real Estate

    Purchasing or investing in property is one of the most significant financial decisions a person can make. While the prospect of owning a piece of real estate can be exciting, it’s also fraught with risks and complexities. Here are eight compelling reasons why educating yourself before taking the plunge is crucial:

    1. Understanding the Market

    The property market is dynamic, influenced by factors such as economic conditions, interest rates, and government policies. Without proper knowledge, you might buy at the wrong time or in the wrong location, potentially leading to financial losses. Education helps you grasp market cycles and trends, enabling informed decisions.

    2. Avoiding Costly Mistakes

    From overpaying for a property to falling victim to scams, the risks of making costly mistakes are high for uninformed buyers. Learning about property valuation, legal processes, and common pitfalls can save you from financial heartache.

    3. Maximizing Investment Returns

    Investing in property isn’t just about buying a house or apartment; it’s about choosing assets that will appreciate in value or generate steady rental income. Understanding key metrics such as ROI (Return on Investment) and cash flow can help you identify profitable opportunities.

    4. Navigating Legal and Financial Complexities

    Property transactions involve a maze of legal and financial considerations. From understanding loan agreements to navigating tax implications and zoning laws, there’s a lot to learn. A lack of knowledge could lead to delays or even legal troubles.

    5. Building Confidence

    The more you know, the more confident you’ll feel about your decisions. Knowledge reduces fear and uncertainty, empowering you to negotiate effectively, choose wisely, and stick to your long-term goals.

    6. Identifying Red Flags

    Not all properties are created equal. Structural issues, poor location, and hidden costs can turn a dream investment into a nightmare. Learning to conduct due diligence and property inspections ensures you spot potential problems early.

    7. Accessing Better Financing Options

    Understanding how mortgages and loans work can save you thousands of dollars over the life of your investment. Learning about different financing options and how to improve your creditworthiness can lead to better interest rates and loan terms.

    8. Planning for the Future

    Property investment is a long-term commitment. Learning helps you align your investment choices with your financial goals, whether it’s building wealth, securing passive income, or preparing for retirement. Knowledge enables strategic planning that benefits you in the long run.

    Conclusion

    Investing time and effort into learning before buying or investing in property is an investment in itself. It equips you with the tools and insights needed to make smart, informed decisions that align with your financial aspirations. Remember, in the world of property, knowledge isn’t just power; it’s profit.

  • Mike Tyson’s Resilience: Investment Lessons for Every Age

    Mike Tyson’s Resilience: Investment Lessons for Every Age

    Mike Tyson, the legendary former heavyweight boxing champion, shocked the world when he continues to maintain his fighting spirit at 58. His return wasn’t just about showcasing his physical prowess; it symbolized the unyielding human spirit and a refusal to let age define capabilities. Tyson’s story offers an invaluable lesson: it’s never too late to keep striving for your dreams, even after traditional retirement age.

    For property investors, Tyson’s journey serves as a powerful reminder that success often comes to those who refuse to give up, regardless of age or setbacks.

    Age is Just a Number in Life and Property Investment

    Many believe that real estate is a young person’s game. However, the truth is that property investment, much like Tyson’s boxing career, rewards perseverance, learning, and action—qualities that grow stronger with age and experience. Whether you’re in your 30s or your 60s, there’s always an opportunity to start or scale your property portfolio.

    The Beauty of Late Blooming

    Tyson isn’t alone in proving that success can come at any age. Many individuals have achieved extraordinary milestones well past the age society deems “prime.” These stories also align closely with property investment principles.

    1. Donald Trump

    Donald Trump built a significant part of his wealth through real estate. Even at 70, when he became the oldest first-term President of the United States in 2016, he demonstrated that reinvention is possible at any age. His story reminds property investors that it’s never too late to think big and make bold moves.

    2. Colonel Harland Sanders

    The founder of Kentucky Fried Chicken (KFC) started his fried chicken empire at 62 after facing multiple failures. Sanders’s persistence mirrors the journey of seasoned investors who’ve faced setbacks but ultimately built lasting wealth by taking calculated risks.

    3. Ray Kroc

    At 52, Ray Kroc transformed McDonald’s into a global powerhouse. Like in property investment, Kroc’s success required spotting a great opportunity and scaling it—a skill that improves with age and experience.

    4. Diana Nyad

    At 64, Diana Nyad became the first person to swim from Cuba to Florida without a shark cage. Her determination to push limits reflects the same mindset required in property investment: relentless focus and belief in achieving the impossible.

    Why Real Estate Works at Any Age

    1. Compounding Growth: Property investments tend to grow in value over time, making it ideal for those looking to build wealth regardless of when they start.
    2. Leverage Experience: With age comes wisdom—an invaluable asset in understanding market trends and avoiding costly mistakes.
    3. Passive Income: Rental properties offer a consistent income stream, making them perfect for retirement planning or financial independence at any stage of life.
    4. Opportunities for Reinvention: Like Tyson stepping back into the ring, seasoned individuals can pivot into property investment as a second career or passion project.

    Lessons from Tyson for Property Investors

    Tyson’s return to the ring, like the stories of Trump, Sanders, and others, underscores the importance of persistence and seizing opportunities. Property investment is no different. It requires:

    • Resilience: Markets fluctuate, but seasoned investors stay the course.
    • Action: It’s never too late to make that first purchase or expand your portfolio.
    • Vision: Investing in property, like boxing, requires foresight and planning to achieve long-term success.

    Making Your Comeback

    Whether you’re approaching retirement or already there, property investment offers one of the most reliable ways to achieve financial freedom. With proper guidance, anyone—regardless of age—can start building a portfolio that generates wealth for years to come.

    Just like Tyson’s return to the ring, starting or growing a property portfolio later in life is proof that you can achieve greatness in your “second act.” So, lace up your gloves, do your research, and take the first step—your property investment journey starts now!

  • Road to Financial Freedom

    Road to Financial Freedom


    Road to Financial Freedom: Episode 3 Recap

    We’re excited to share that we’ve just wrapped up Episode 3 of our Property Talk series, featuring the insightful CY Goh. In this episode, CY Goh delved into the crucial topic of achieving financial freedom through strategic planning and disciplined execution.

    CY Goh shared a wealth of knowledge, drawing from his personal journey and the strategies that have fueled his success. After years of attending numerous courses and learning from top industry experts, Goh embarked on his property investment journey. Today, he proudly shares the techniques and insights that have helped him attain financial independence.

    For those interested in learning more, we invite you to watch the recorded video of this episode. You might find that one of Goh’s strategies resonates with you and fits your financial goals.

    However, please remember that the strategies shared by CY Goh are based on his personal experiences and perspectives. They may not be suitable for everyone, and we encourage viewers to exercise their own discretion and consider their unique circumstances before applying any of the advice.

    Enjoy the video, and may it inspire your own journey towards financial freedom!

    UPCOMING

  • Unlock Rental Property Success with a Strong DSCR

    Unlock Rental Property Success with a Strong DSCR

    Ever come across the term Debt Service Coverage Ratio (DSCR)? If not, don’t worry—I’m here to simplify it for you. While it might seem complex, DSCR is actually a straightforward concept that plays a crucial role in real estate investing.

    What is Debt Service Coverage Ratio (DSCR)?

    The Debt Service Coverage Ratio (DSCR) is a key metric that assesses whether a property’s income is sufficient to cover its debt obligations. Think of it as a financial report card for real estate investors, showing if a property is financially sustainable. Let’s break it down for easier understanding:

    The DSCR Formula

    DSCR = Net Operating Income (NOI) / Total Debt Service (TDS)

    • Net Operating Income (NOI): The income generated by the property, including rent and other sources, after deducting expenses like maintenance, property management fees, and taxes.
    • Total Debt Service (TDS): The total annual payments required to service the loan, covering both principal and interest.

    How to Interpret DSCR

    • DSCR > 1: The property generates more income than needed to cover its debt—this is a positive sign!
    • DSCR < 1: The property’s income is insufficient to cover the debt—this signals potential risk.

    A higher DSCR indicates a lower risk of default, making the property more attractive to lenders.

    How DSCR Works in Practice

    Let’s see DSCR in action with a practical example:

    1. Net Operating Income (NOI):
      • Peter’s rental property generates RM50,000 annually.
      • Annual expenses total RM20,000.
      • NOI = RM50,000 – RM20,000 = RM30,000.
    1. Total Debt Service (TDS):
      • Peter’s annual mortgage payment is RM24,000.
      • Total Debt Service (TDS) = RM24,000.
    1. DSCR Calculation:
      • DSCR = RM30,000 (NOI) / RM24,000 (TDS) = 1.25.

    With a DSCR of 1.25, Peter’s property generates more income than needed to cover the debt, indicating financial stability and a comfortable margin for loan payments.

    Why DSCR Matters?

    The Debt Service Coverage Ratio (DSCR) is a critical indicator in real estate investing, helping you assess whether a property’s income can cover its debt obligations. Whether you’re looking to own rental properties or simply exploring the real estate market, understanding DSCR is essential for your success. By maintaining a healthy DSCR, you can build a solid foundation for your investments and ensure long-term profitability.

    From The Desk of Miichael Yeoh

    Check out the latest article on how Budget 2025 impacts the property sector

  • EPF Borrowing Scheme: Is This Legal?

    EPF Borrowing Scheme: Is This Legal?

    What can I say? Malaysians are incredibly innovative. We always find all sorts of ways to make money. Recently, I stumbled upon an intriguing article online about a new scheme: borrowing against your EPF. Yes, you heard me right. If you have money in your EPF and you are between the ages of 48 to 55, you are supposedly eligible to borrow. But is this scheme legal? The answer is a resounding “NO.” There is no such scheme approved by KWSP. This is the creation by syndicates.

    I discovered that many people are promoting this scheme. Approval is alarmingly easy; all you need is a copy of your MyKad and your latest EPF statement. As long as there is money in your account, consider your loan approved. Of course, the interest rate is sky-high, but the borrower doesn’t need to repay until EPF withdrawal.

    Picture Credit: Focus Malaysia

    These types of loans pose a significant risk to the financial security of retirees. With the promise of immediate cash, many are tempted to apply, potentially jeopardizing their retirement. EPF contributors are strongly advised to seek advice before considering such schemes.

    From the Desk of Miichael Yeoh
  • Property Investment: Success or Bankrupt?

    Property Investment: Success or Bankrupt?

    Many people are enthusiastic about making money from property investment. After all, who wouldn’t want a reliable safety net for the future? Property can indeed offer financial security, but this is only true if you plan properly and do your due diligence before buying. While it may sound lucrative, without the correct approach, it can quickly turn into a financial disaster.

    I recall an incident that starkly highlights this point. After one of my seminars organized by a property developer, a couple in their 30s approached me. They shared a heartbreaking story: they had declared bankruptcy and had a 6-year-old child to care for. Their downfall began when they followed advice from a so-called property expert and started purchasing properties beyond their financial means. The rental income from these properties was either too low or non-existent, and they couldn’t find tenants. To make matters worse, the so-called expert was nowhere to be found, leaving the couple to face the harsh realities alone.

    What lesson can we draw from this? The pursuit of wealth through property investment can sometimes turn into a nightmare, even if you believe such misfortune won’t happen to you.

    Click Register NOW

    Let’s rewind a bit. Had this couple engaged in proper financial planning, their situation might have been very different. A crucial aspect of financial planning is understanding your monthly income against your expenses. Personally, I wouldn’t consider purchasing a property unless I had at least 12 months of installment payments saved in advance, especially if I had to take a loan from the bank. There is much more to financial planning, but diving into the details would be lengthy. The key takeaway is this: invest within your capacity. Don’t let greed drive your decisions, as it might be too late to turn back once you’re down that road.

    The desire to become a successful property millionaire is understandable, but it’s essential to think carefully before making such a bold step.

    I hope this article opens your eyes to the realities of property investment.

    If you need expert advice on your property investment journey, please email us at info@miichaelyeoh.com.

    From the Desk of Miichael Yeoh

  • Discover The Keys to Successful Property Investment (Live Webinar)

    Discover The Keys to Successful Property Investment (Live Webinar)

    Are these familiar struggles for you?

    🏠 Feeling lost in the world of property investment?

    💰 Watching your investments drain your finances?

    😱 Scared off by terrifying investment horror stories?

    💸 Struggling to secure funds for investment?

    🏦 Facing obstacles getting a loan from the bank?

    🔍 Bought a property but can’t find a tenant?

    You’re not alone. But here’s what awaits you on the other side:

    • Witnessing others prosper through property investment while you sit on the sidelines.
    • Regretting missed opportunities for passive income generation.
    • Reflecting on how better financial planning could have changed your life.

    What’s in store for you at my seminar?

    🔍 Insights to equip yourself for successful property investment.

    ⚠️ Awareness of common pitfalls to avoid in the property market.

    🏡 Understanding the crucial components of property investment.

    📊 Appreciation for the importance of property data analysis.

    🔍 Guidance on conducting thorough due diligence before buying.

    💼 Experience the transformative power of effective financial planning.

    Audiences and events I’ve spoken and organized for property buyers/investors, developers, conventions, and property study trips.

    Don’t let uncertainty or fear hold you back! Join me and unlock the doors to a brighter financial future!

    Register your FREE SEATS Now as seats are limited…..

    See you soon,

    Miichael Yeoh

  • 7 Critical Factors to Consider Before Investing in Property

    7 Critical Factors to Consider Before Investing in Property

    Investing in property can be lucrative, but it requires careful planning and consideration. Based on my experience in the industry, I’ve seen many success stories as well as horror tales of financial loss and even bankruptcy. To avoid pitfalls, you must prepare thoroughly. Here are seven critical factors to consider before investing in property:

    1. Objective

    • Define Your Goals: Have a clear investment objective. Determine whether you’re looking for short-term gains or long-term investments.
    • Rental Strategy: Decide how you plan to rent out the property. Is it for long-term tenants or short-term rentals like Airbnb?
    • Return on Investment (ROI): Set a target ROI that aligns with your risk tolerance. Remember, higher risk typically comes with higher returns. Personally, I prefer calculated risks with an average return.

    2. Financial Planning

    • Affordability: Assess your financial situation meticulously. Don’t overextend yourself by buying properties beyond your affordability level.
    • Savings: My rule of thumb is to have at least 12 months of bank installments saved before purchasing a property. This cushion helps avoid financial stress.
    • Budgeting: Carefully calculate your income and expenses to ensure you can manage the investment without compromising your financial stability.

    3. Bank Loan Eligibility

    • Pre-Approval: Understand how much the bank is willing to lend before committing to a purchase. Getting pre-approved for a loan can prevent future disappointments.
    • Creditworthiness: Ensure your financial records and credit score are in good shape to qualify for better loan terms. Banks favor prudent borrowers.

    4. Demographics

    • Population Density: Choose locations with a high population density to ensure demand for your property.
    • Target Audience: Consider who your potential renters or buyers will be. A property in a well-populated area is more likely to attract tenants and buyers.

    5. Infrastructure

    • Accessibility: Ensure the property has good access to roads, public transport, and essential services. Lack of infrastructure can make it difficult to rent or sell the property later.
    • Local Development Plans: Check with the local council for any planned infrastructure developments that could enhance the property’s value.

    6. Pulling Demand

    • Market Demand: Avoid properties in areas with little to no demand. Research the local market and industries to understand who will be your customers.
    • Economic Activity: Proximity to thriving industries or business hubs can increase rental and resale value.

    7. Future Prospects

    • Growth Potential: Investigate the area’s future growth prospects. Look for upcoming developments, planned amenities, and general economic outlook.
    • Long-Term Viability: Ensure the location has the potential for long-term growth, making it easier to rent or sell the property in the future.

    Investing in property is not just about buying; it’s about making informed decisions based on thorough research and strategic planning. By considering these seven factors, you can mitigate risks and increase your chances of a successful investment.

    From the desk of Miichael Yeoh

  • From Property Millionaire to Property Millionhair

    From Property Millionaire to Property Millionhair

    Many individuals aspire to become property millionaires. They immerse themselves in books, seminars, and courses, each with their own pace – some favoring quick success, while others opt for a slower, steadier approach. What’s your preference?

    But caution is warranted. Sadly, many who aspire to property wealth end up with a different outcome – becoming “property millionhairs” instead. Take Jerry, for example (not his real name). Despite a net income of RM5K, he impulsively purchased five properties at once, enticed by promises of a RM200k cashback per unit. With five units, he envisioned instant wealth. However, blinded by the prospect of millionaire status, he overlooked critical details, such as the absence of the cashback clause in the contract.

    To realize his dream, Jerry enlisted his girlfriend’s help to secure mortgage approval, as his income alone wasn’t sufficient. The terms seemed promising – the cashback would be disbursed upon the bank’s final payment release, just a few months away. Jerry was ecstatic, anticipating wealth raining down on him.

    When the cashback arrived, Jerry felt like royalty. His eyes gleamed with newfound riches, and he indulged in extravagant purchases – a RM300k car, luxury watches, jewelry, and more. He also spent a substantial sum renovating his properties for potential tenants.

    Yet, eight months later, reality set in. Jerry’s million was dwindling rapidly, with vacant units generating no income to offset his hefty RM12k monthly mortgage payments. Facing financial ruin, he discovered his properties were valued 40% below their purchase price, rendering them unsellable without further financial strain.

    Do you want to emulate Jerry’s fate? Consider these warnings:

    Packages like Jerry’s often involve properties with poor marketability.

    Jerry’s scheme of securing multiple loans or called compression method with a single income is fraudulent and can lead to legal consequences.

    Jerry may have salvaged some funds, but others haven’t been as fortunate. I’ve encountered individuals on the brink of bankruptcy, struggling to provide for their families, a heartbreaking reality.

    Banks are now more vigilant, scrutinizing loan applications meticulously to prevent such misfortunes. Yet, at the heart of it lies human greed, fueled by promises of grandeur.

    For me, prudence reigns supreme. I advocate for careful planning, eschewing shortcuts for a methodical approach. If I can’t cover at least 12 months of mortgage payments, I refrain from purchasing, no matter how enticing the property. Financial responsibility dictates my decisions. To everyone out there, heed this advice: stay within your means. When deals seem too good to be true, exercise caution. Protect your financial well-being, for our lives are invaluable.

    From the Desk of Miichael Yeoh

  • Praying For Luck in Mortgage Approval

    Praying For Luck in Mortgage Approval

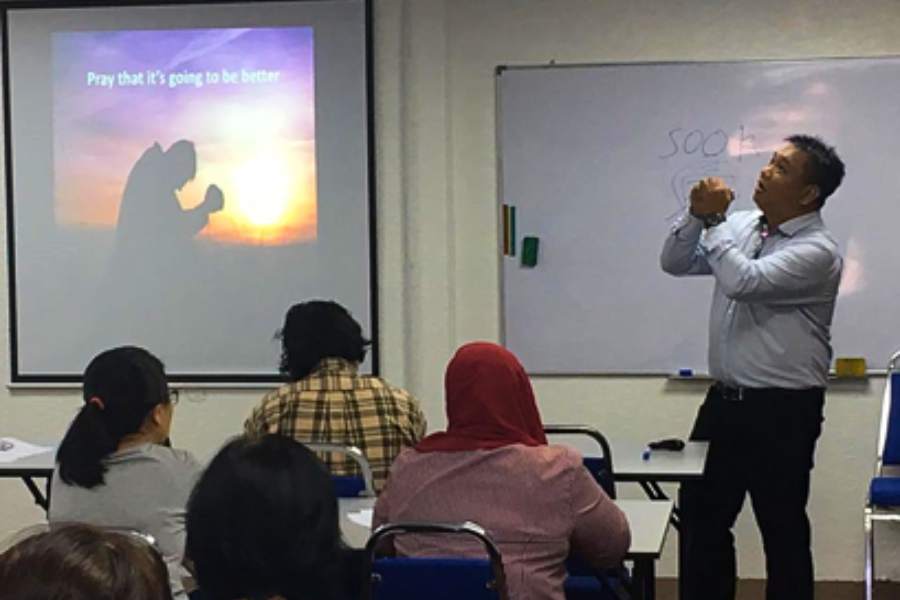
    In the picture, what do you think I am doing? Praying for the money to drop

    I do not really depend on these. I don’t think money will suddenly drop from the sky or hoping for a miracle to happen. If a car were to break down, you will need a mechanic to fix the problem. He will have to follow a series of steps in doing repair and to make sure your car is running again.

    Likewise, in mortgage approval you cannot wait for miracle things to happen. To me, luck have nothing to do on mortgage approval. Many borrowers and agents, prefer to photocopy many stacks of financial documents and give to every bank they know off or can find and submit to them for approval. Is this the right way?

    Do you know that every time your documents are submitted, the banks will record and send to Bank Negara which in turn will update the Central Credit Information System (CCRIS) every month? No matter whether your loan is approved or rejected it will be updated on the last page of your record. Let’s say Bank A rejects your loan, Bank B,C and D also rejects but Bank E actually can approve your loan but seeing so many banks rejected your loan the chances are they will also reject your loan.

    Never expose yourself. Every bank have different approval criteria. Some banks might not like you but some does. I have a case once, his Debt Service Ratio is very high at 150% in which is higher than the normal 70-85%. Either the banks rejects or do not want to waste time processing his case. I reviewed his documents and to cut things short, I managed to get 70% loan approval. This case is a fine example where the borrower will have to do the following:

    • Do a Know yourself (KYS) test.
    • Check your credit status
    • Check which bank is suitable for you.

    You will have to do more work on the last step. You will need to find out each bank approval criteria and also the different types of documents for approval. You are not buying a RM1,000 property but hundreds or even millions worth of property. It is good to do a research first. It is hard to go back when your loan had been rejected. It is easier to diagnose a problem first.

    Related article https://miichaelyeoh.com/2024/04/07/what-you-should-do-before-applying-a-loan/

    From the desk of Miichael Yeoh