Category: Financial Planning

  • Before You Buy Any Property, Run It Through This Simple Checklist

    Before You Buy Any Property, Run It Through This Simple Checklist

    Most property mistakes don’t happen after you buy.
    They happen before you sign.

    Over the years — working in banks, speaking on stages, and educating buyers and investors — I’ve noticed one consistent pattern:

    People buy property based on emotion, marketing, or price,
    instead of structure, numbers, and risk.

    Good property decisions are rarely accidental.
    They are the result of asking the right questions early.

    Let me show you the checklist I personally use — and teach — before anyone commits to a property purchase.


    1. Start With the Right Question (Not “Can I Buy?”)

    The wrong question is:

    “Can I get a loan?”

    The better question is:

    “Is this property right for me?”

    Before you look at projects, promotions, or discounts, be clear on your purpose:

    • Are you buying for own stay, rental income, or long-term growth?
    • Do you want monthly stability, future upside, or both?
    • How long are you prepared to hold this property?

    A good property for someone else can be a bad property for you.

    Clarity always comes before commitment.


    2. Understand Your Financial Comfort Zone

    Many buyers confuse approval with affordability.

    Just because you can commit, doesn’t mean you should.

    Before buying, be honest about:

    • Your monthly commitments after purchase
    • Your buffer if interest rates rise or income changes
    • Whether the property adds pressure or flexibility to your life

    A simple rule I often share:

    If a property causes stress from Day One, it’s already a bad decision.

    Property should support your long-term plan — not trap you in it.

    3. Protect Yourself Before You Celebrate

    Buying property is not just about price and location.
    It’s about rights, responsibilities, and clarity.

    Before you sign anything, make sure you understand:

    • What you truly own
    • Any conditions or restrictions attached to the property
    • Your obligations now and in the future
    • What happens if things don’t go according to plan

    Many buyers only realise what they signed after problems arise.
    By then, it’s often too late.

    Confidence comes from understanding — not assumptions.


    4. Look at the Real Cost, Not Just the Purchase Price

    The purchase price is only the beginning.

    You need to consider:

    • All upfront costs
    • Ongoing holding expenses
    • The impact of rental income on your overall finances
    • What you walk away with — not just what comes in

    A property that looks attractive on paper can disappoint once all costs are considered.

    Smart buyers focus on net outcome, not headline numbers.


    5. Evaluate the Property Like an Investor, Even If You’re Not One

    Even if you’re buying for own stay, think ahead.

    Ask yourself:

    • Who else would want this property in the future?
    • Is supply increasing in this area?
    • Are rental expectations realistic?
    • If you needed to sell, who would be your buyer?

    Hope is not a strategy.
    Every property should have a clear future story.


    6. A Simple Yes / No Filter I Personally Use

    Before I say yes to any property, I run through this:

    • ✅ Does this make sense financially over time?
    • ✅ Do I fully understand what I’m committing to?
    • ✅ Am I comfortable holding this through different market cycles?
    • ✅ Does this fit my life plan — not just today, but later?
    • ✅ Do I have flexibility if things change?

    If any answer is No, I pause.

    Property rewards patience far more than pressure.


    Final Thought: Learn First, Buy Second

    Property is not about buying fast or buying early.
    It’s about buying wisely.

    Too many people buy first — and learn later.
    The cost of that mistake can last decades.

    That’s why I believe education must always come before action.

    When you understand the decision fully, confidence follows naturally.

    And confident buyers make better property decisions — every time.

    From the desk of

    Miichael Yeoh
  • Property Refinancing in Malaysia

    Property Refinancing in Malaysia

    New Rules, Regulations & When Refinancing Actually Makes Sense

    Over the years, refinancing has been one of the most powerful financial tools for Malaysian homeowners and property investors. Used correctly, it can improve cash flow, reduce interest costs, or unlock equity for smarter investments.

    However, recent regulatory changes by Bank Negara Malaysia (BNM) mean refinancing is no longer as straightforward as before — especially when it involves cash-out.

    If you’re considering refinancing your property in 2025 or beyond, here’s what you must understand before making a move.


    What Is Property Refinancing?

    Property refinancing simply means replacing your existing home loan with a new loan, usually with another bank, based on your property’s current market value.

    Homeowners typically refinance to:

    • Get a lower interest rate
    • Reduce monthly instalments
    • Adjust loan tenure
    • Access cash from accumulated property equity
    • Consolidate high-interest debts

    The strategy itself hasn’t changed — the rules have.


    What’s New? Key Refinancing Rules You Must Know

    1. Cash-Out Refinancing Is Now More Restrictive

    One of the biggest changes affects cash-out refinancing.

    If you refinance and take extra cash for personal use (such as lifestyle spending, personal debts, or non-income-generating purposes), that portion may now be treated as personal financing, not a housing loan.

    👉 Key impact:

    • The cash-out portion may be capped at a maximum repayment tenure of 10 years
    • Monthly instalments will be significantly higher compared to spreading it over 30–35 years

    This is a major shift. In the past, many borrowers stretched cash-out amounts across the full home loan tenure, keeping instalments low but debt long.


    2. Stronger Affordability & DSR Checks

    Banks are now applying stricter Debt Service Ratio (DSR) assessments, especially for:

    • Multiple property owners
    • Refinancing with cash-out
    • Borrowers with existing personal loans or credit card balances

    Even if your property value has increased, approval is no longer guaranteed if your cash flow doesn’t support the new repayment structure.


    3. More Transparency on Loan Costs

    BNM has reinforced rules to ensure:

    • Clear disclosure of effective interest rates
    • Transparent breakdown of total repayment costs
    • Fair interest calculations based on reducing balance, not outdated methods

    This protects borrowers — but it also means banks are less flexible with “creative structuring”.


    Why Did Bank Negara Tighten Refinancing Rules?

    The objective is simple: reduce unhealthy household debt behaviour.

    Over the years, many Malaysians:

    • Used refinancing repeatedly for lifestyle spending
    • Rolled short-term debts into long-term housing loans
    • Focused on “low monthly instalment” instead of total debt impact

    The new rules encourage:

    • Responsible borrowing
    • Better financial planning
    • Using refinancing for productive purposes, not emotional decisions

    So… Why Should You Refinance a Property?

    Refinancing still makes sense — if done for the right reasons.

    1. To Lower Your Interest Rate

    If your current loan is:

    • On an old package
    • Above current market rates

    Refinancing can reduce:

    • Monthly instalments
    • Total interest paid over the loan tenure

    This is the cleanest and safest reason to refinance.


    2. To Improve Monthly Cash Flow

    Some homeowners refinance to:

    • Extend tenure
    • Reduce instalments
    • Create breathing space for cash flow

    This can be helpful during:

    • Business expansion
    • Income transition
    • Temporary financial tightening

    However, it must be done strategically, not emotionally.


    3. To Access Equity for Income-Producing Purposes

    This is where refinancing still shines — when the cash is used productively, such as:

    • Renovating a rental property
    • Funding another investment
    • Business expansion with clear returns

    Banks are generally more supportive when refinancing is tied to income generation, not consumption.


    4. Debt Consolidation (With Caution)

    Refinancing to clear:

    • Credit cards
    • Personal loans

    can reduce interest costs if discipline improves after refinancing.

    If spending habits remain unchanged, refinancing only delays the problem.


    5. To Restructure Your Property Portfolio

    For investors, refinancing can be used to:

    • Optimise loan structure across multiple properties
    • Release equity to rebalance portfolio risk
    • Improve overall holding power

    This requires proper planning — not just chasing approval.


    What You Should Consider Before Refinancing

    Before signing anything, ask yourself:

    ✔ Does refinancing truly save money after legal & valuation costs?
    ✔ Can I comfortably afford repayments if cash-out tenure is shorter?
    ✔ Am I refinancing for strategy — or short-term relief?
    ✔ Does this move strengthen my financial position 5–10 years from now?

    Refinancing is a tool. Used correctly, it builds wealth. Used wrongly, it creates silent financial stress.


    Final Thoughts from Miichael

    In today’s environment, refinancing is no longer about “how much cash can I take out”.

    The real question is:

    Does this refinancing decision improve my financial position — or just make today easier at tomorrow’s expense?

    With tighter rules in place, planning matters more than approval.

    If you’re unsure whether refinancing makes sense for your situation, get proper advice before committing. The cost of a wrong decision today can take years to undo.

  • The Property Guru Trap: How to Separate Education from Marketing

    The Property Guru Trap: How to Separate Education from Marketing

    By Miichael Yeoh


    Let’s be honest.

    Today, the property industry is noisier than ever. Everywhere you look — social media, webinars, billboards, YouTube ads — there’s a new “property guru” promising fast riches, zero-risk investments, and financial freedom in record time.

    The problem? Most Malaysians are not confused because property is complicated. They’re confused because they are overloaded with marketing disguised as education.

    And that’s where many fall into what I call The Property Guru Trap.


    When Marketing Pretends to Be Education

    Here’s the uncomfortable truth: not all property educators are educators. Many are simply excellent marketers.

    Their formula is simple:

    • Showcase luxury lifestyle
    • Highlight “student success” without context
    • Push urgency: Buy now or miss out forever
    • Sell emotion, not strategy

    You’re not being taught how to think. You’re being told what to buy.

    Real education gives you clarity. Marketing creates pressure. One empowers. The other manipulates.


    A Real Story I See Too Often

    Just last year, a couple in their early 30s came to me after attending my property seminar. They had purchased three so-called “hot projects” based on hype incentives.

    On paper, it looked attractive. In reality:

    • Both units were negative cashflow
    • Rental demand was weak
    • Their monthly commitments were choking their lifestyle

    They weren’t irresponsible. They were simply following loud voices instead of clear frameworks.

    And sadly, this is becoming the norm — not the exception.


    The Real Cost of Following the Wrong Advice

    I’ve met too many people who:

    • Bought units with negative cashflow
    • Overleveraged based on “hot tips”
    • Ended up with properties that can’t be rented
    • Are stuck servicing loans that don’t perform

    Not because they were careless — but because they trusted confidently delivered advice without understanding the fundamentals.

    A true educator helps you analyze. A salesperson helps you justify.

    There is a difference.


    How to Tell If You’re Learning or Being Sold To

    ✅ Real Education Will:

    • Teach you how to calculate ROI, yield, and risk
    • Help you understand bank approval logic
    • Show both pros AND cons of a deal
    • Focus on your personal financial situation
    • Encourage long-term thinking

    🚩 Pure Marketing Will:

    • Avoid numbers and focus on hype
    • “Guaranteed rental must make sense”
    • Emphasize lifestyle more than strategy
    • Create fear of missing out
    • Push for immediate commitment

    If the main goal is to close you fast — it’s not education. It’s sales.


    Property Success Is Built on Structure, Not Excitement

    Smart investors don’t rely on tips. They rely on process.

    They understand:

    • Why banks approve or reject loans
    • How debt strategy impacts long-term wealth
    • The difference between speculation and investment
    • That timing alone doesn’t beat fundamentals

    This is why structured learning matters. Not a weekend motivation high — but a system that builds independent decision-makers.


    The Role of a Real Property Educator

    A real educator doesn’t create dependency. They create capability.

    You should walk away able to:

    • Analyse any project yourself
    • Question assumptions
    • Say NO to bad deals
    • Build a property plan based on your life goals, not someone else’s wins

    Because the ultimate goal is not to follow a guru. It is to become your own strategist.


    My Commitment to Property Education

    For over a decade, my focus has never been about selling you a project. It has always been about equipping you with a framework:

    • A banker’s mindset to assess risk
    • An investor’s eye to spot opportunity
    • A player’s strategy to move smartly in the real world

    Property is a powerful wealth tool — but only when approached with clarity, structure, and knowledge.

    Not hype. Not shortcuts. Not empty promises.


    Final Thought

    Before you follow any advice, ask yourself:

    “Am I being educated — or am I being persuaded?”

    The moment you learn to differentiate the two, you stop being a follower… And start becoming a true property investor.


    Property Matching: The Missing Link Most Gurus Ignore

    One of the biggest differences between real education and marketing is this:

    Marketing pushes projects. Education focuses on property matching.

    Property matching means selecting a property based on who YOU are — not what the developer wants to sell.

    It considers:

    • Your income structure
    • Your existing commitments
    • Your risk profile
    • Your investment timeline
    • Your cashflow capability
    • Your long-term objectives

    Instead of asking: “Which project is hot now?”

    The right question is: “Which property fits my current financial position and future strategy?”

    This is exactly why many buyers end up stressed. They buy what is popular — not what is suitable.

    A proper property matching process helps you:

    • Avoid overcommitting
    • Prevent loan rejection issues
    • Choose units with realistic rental demand
    • Align property type with your wealth plan

    There is no such thing as a universally good property. Only a property that is good for the RIGHT person.

    And this step is often skipped in high-pressure sales environments — because matching takes time, analysis, and honesty.

    That’s not convenient for fast sales. But it is essential for sustainable investing.


    Ready to Learn Property the Right Way?

    If you’re serious about building wealth through property — not just buying based on emotion — then it’s time to approach it with strategy.

    ✅ Learn how banks really assess your loan ✅ Understand cashflow before committing ✅ Build a property roadmap aligned to your life goals

    Join my upcoming property programme or consultation session and start making decisions with clarity, not pressure.

    Because wealth is not built on motivation. It is built on informed decisions.

  • Boost Your Loan Approval Chances in Malaysia

    Boost Your Loan Approval Chances in Malaysia

    Malaysian bank lending (especially for property purchases) is currently shaped by several key monetary, regulatory, and market-demand factors. Rates have been easing somewhat, but approval conditions remain cautious. Below are the latest numbers and trends.


    Current Figures & Trends

    1. Overnight Policy Rate (OPR) & Reference Rates
      • In July 2025, Bank Negara Malaysia (BNM) cut the OPR from 3.00% to 2.75% – the first cut in five years.
      • Major banks have adjusted their Standardised Base Rate (SBR) to 2.75% per annum following the OPR cut.
      • Base Rate (BR) has also been adjusted (for many banks) in line with this, though BR tends to be higher than SBR. For example, Alliance Bank’s BR is about 3.57%.
    2. Base Lending Rate / Base Financing Rate (BLR/BFR)
      • The BLR or BFR (for Islamic financings) for many banks remains in the ~6.35% to ~6.65% range. For example, Maybank’s BLR is 6.40%, Hong Leong Bank’s is ~6.64%, etc. baserate.my+3Maybank2u+3NewPages+3
    3. Effective Housing Loan Rates
      • While the base/reference rates give a starting point, effective lending rates (what borrowers actually pay) tend to be higher because banks add a margin/spread depending on risk, loan amount, tenure, etc.
      • Recent reports suggest effective rates for housing loans are in many cases 4.15% to 5.7% p.a. depending on bank, borrower profile, loan value, promotion, etc. Property Genie
    4. Loan Approval & Volume
      • There was a 25.7% month-on-month increase in approvals of housing-loan applications in July 2025 after a slump in June. Focus Malaysia – Business & Beyond
      • The approval ratio (i.e. approved vs applied) in July 2025 was about 44.8%, up from ~42.6% in June 2025. Focus Malaysia – Business & Beyond
      • On a year-on-year basis, total approved loan volume declined by ~5.1% for that month; cumulatively over the first 7 months of 2025, approved property loans were ~RM 161.4 billion, about -1.5% relative to same period in previous year. Focus Malaysia – Business & Beyond
    5. Outlook
      • With lower OPR and more competitive base/reference rates, there is optimism that loan approvals (both volume and ratio) may improve in the remaining months of 2025. Government’s likely to include incentives in Budget 2026 to support first-time buyers, low-to-middle income groups. Focus Malaysia – Business & Beyond

    Steps Borrowers Can Take to Increase Chances of Loan Approval

    Given the current environment, borrowers can do several things to strengthen their applications and improve likelihood of approval. Here are practical steps, both before and during application.

    StepWhat to DoWhy It Helps
    1. Check & Clean Up Your Credit HistoryObtain your credit report (e.g. through CTOS, CCRIS, Experian) ahead of time. Ensure there are no outstanding defaults, ensure credit card/HP payments are on time.Banks check creditworthiness; a clean credit history reduces risk and may allow you to access better rates.
    2. Assess Debt Service Ratio (DSR) / Total CommitmentsKnow your monthly obligations: other loans, credit cards, etc. Make sure your net income minus all obligations leaves enough room for loan instalments. Try to reduce existing liabilities if possible.Banks often reject or charge higher margins if your debts relative to income are too high. Lower commitments improves affordability assessment.
    3. Have Stable & Adequate IncomeDemonstrate consistent employment or business income; have documentation (pay slips, tax returns, EPF contributions). If self-employed or commission-based, provide past 2-3 years’ income statements, audited if possible.Stability & predictability of income give banks confidence in your ability to repay.
    4. Make Reasonable Down Payment / EquityThe more you put down (lower loan-to-value ratio), the less risk for the bank. If you’re first-time buyer programs exist (often requiring only 10% payment), check eligibility, but be aware these may still have stricter conditions.Less loan amount relative to property value helps bank exposure and reduces margin required.
    5. Choose Appropriate Loan TenureLonger tenure reduces monthly instalments but increases total interest paid; very long tenure may raise risk from bank’s perspective (future rate changes, income changes). Balance payroll constraints with ability to service.A manageable monthly repayment improves approval chances; less risk of default.
    6. Prepare All Supporting Documents ProperlyHave ready: identity documents, employment letters, income proof, EPF statements, tax returns (if applicable), bank statements, any other asset documentation. Ensure documents are current.It speeds up processing and reduces grounds for rejection due to missing information.
    7. Shop Around & Compare OffersDifferent banks have different margins, promotions, and underwriting criteria. Get multiple quotes. Negotiate (sometimes banks reduce spread or offer incentives).May get better rate, lower fees, more favorable terms.
    8. Provide Clear Purpose & Property DetailsHave the Sale & Purchase Agreement (SPA), valuation report (if needed), title deed, property details, etc. If property is new or under construction, ensure developer’s track record and required approvals are in order.Banks assess property risk as well: location, title, developer credibility affect approval.
    9. Maintain Good Savings / ReservesHaving savings or avoid fully depleting your accounts helps; having reserves gives cushion in case of rate increases or unexpected expenses.Shows financial discipline and lowers risk from bank’s viewpoint.
    10. Understand Bank Fees & RequirementsBe aware of legal fees, valuation fees, stamp duties, insurance (MRTA/MRTT), and any bank-specific requirements (e.g. guarantor, joint-applicant). Make sure to budget for them.Unexpected costs can derail the process; being well-prepared ensures smoother approval.

    Challenges & What Borrowers Should Watch Out For

    • Even with OPR at 2.75% and SBR adjusted, banks’ margins/spreads can still be high depending on borrower risk. So effective rates may still be less favourable for some.
    • Approval ratios (~44-47%) show that over half of applications still get declined. That means it’s not just about rates; credit & affordability are being closely scrutinized. Focus Malaysia – Business & Beyond
    • Rising costs for legal fees, valuation, and sometimes hidden fees can make total cost of financing higher than expected.
    • Inflation, future rate rises, economic uncertainties mean banks may reserve right to tighten conditions suddenly.


    Conclusion

    Bank lending is currently becoming somewhat more favourable in Malaysia thanks to the OPR cut and adjusted reference rates. However, borrowers must still present strong, well-prepared loan applications. Cleaning up credit, reducing existing obligations, having stable income and proper documentation, and choosing appropriate loan terms are all crucial.

  • 💰 Household Debt in Malaysia – Should We Be Worried?

    💰 Household Debt in Malaysia – Should We Be Worried?

    If you’ve been hearing about household debt in the news and wondering what it means for us Malaysians, here’s the lowdown—without the boring jargon.

    Historical Context

    • 2008 marked a low point in household debt relative to GDP, at 60.4%, showing moderate borrowing during that period. CEIC Data
    • In 2020, debt peaked during the pandemic, reaching a record 93.1% of GDP. CEIC Data
    • As of 2023, debt remained elevated at 84.2% of GDP, up from 80.9% in 2022. CEIC Data

    These figures indicate that while debt declined from its 2020 high, it remains higher than pre-pandemic levels—an ongoing concern.

    The Latest Numbers (2024–2025)

    • In June 2024, household debt stood at around RM1.57 trillion, accounting for 83.8% of GDP. Housing loans comprised 61%, followed by vehicle loans (13.5%) and personal financing (12.4%).
    • By March 2025, debt rose to RM1.65 trillion, or 84.3% of GDP.

    Interestingly, household financial assets were reported to exceed debt by a factor of 2.1, suggesting Malaysians as a whole still have a substantial financial cushion. Additionally, prudent lending practices are maintained, with median debt service ratios (DSR) remaining at 34% for existing loans and 41% for newly approved loans (2024).


    What This Means for Malaysians

    Risks

    1. Sustained High Debt Load
      With debt hovering around 84% of GDP, many households must allocate a significant portion of income toward repayments—possibly limiting spending on essentials.
    2. Rising Youth Bankruptcy
      Between 2020 and early 2025, over 5,272 youths under 34 were declared bankrupt, with nearly 877 cases in 2024 alone. Personal loans accounted for 46.4% of these filings.
    3. Potential for Over-Leveraging via BNPL
      Growing use of “Buy Now, Pay Later” (BNPL) services (e.g., Atome, Grab PayLater) raises concerns, as they operate outside traditional credit tracking like CCRIS and may enable unmonitored debt accumulation.
    4. Lenient Lending to Young Graduates
      Experts warn that easy credit access for fresh graduates—especially via credit cards—could foster poor financial habits without proper income checks or financial literacy.

    Positive Offsets

    1. Healthy Asset Buffer
      Households’ financial assets outpacing their debts by over double implies a buffer that could cushion against economic shocks.
    2. Responsible Lending Frameworks
      With the Responsible Financing guidelines and relatively moderate DSRs, household borrowing still aligns with regulatory safety standards.
    3. Support Services Available
      Agencies like AKPK have helped over 64,000 borrowers settle loans, while nearly 270,000 others continue to receive support through debt management programs.

    Balancing Act: Looking Forward

    • Economic Growth vs. Debt Sustainability
      While household debt has eased somewhat from its pandemic-era peak, it remains elevated, and spikes in personal or BNPL borrowing could strain households—especially lower-income groups.
    • Youth Financial Health
      The rising bankruptcy trend among the young underscores the necessity of stronger financial education and tighter lending criteria for vulnerable demographics.
    • Policy Opportunities
      Strengthening regulation around new lending platforms like BNPL, embedding financial literacy into early education, and enforcing responsible credit access remain vital steps to prevent systemic vulnerabilities.

    In Summary

    Household debt in Malaysia has declined from its 2020 highs but remains elevated, hovering around 84% of GDP in 2024–2025. While household financial assets provide a buffer and regulatory frameworks offer some protection, rising personal debt—especially among youths and via emerging platforms like BNPL—pose risks. Continued focus on financial education, responsible lending policies, and inclusive support systems will be key to ensuring long-term household resilience.

  • Inheritance Law and Joint Ownership Explained

    Inheritance Law and Joint Ownership Explained

    Written by Jocelline Chee from Rightwill | Edited by Miichael Yeoh

    When it comes to inheritance, things can get complicated—and emotional—especially when property is involved. In Malaysia, many people assume that putting property under joint names (like with a spouse or child) will make things smoother when someone passes away. Unfortunately, it’s not always that simple.

    If you’re planning to leave a property behind for your loved ones, it’s important to understand how inheritance laws work in Malaysia and the potential problems that can pop up with joint ownership.


    🏛️ How Inheritance Works in Malaysia

    Inheritance laws in Malaysia depend on your religion:

    • For Muslims, faraid (Islamic inheritance law) applies. It has fixed rules on how the estate is divided among family members.
    • For non-Muslims, the Distribution Act 1958 (amended in 1997) applies. This Act lays out who gets what—based on whether the deceased leaves behind a spouse, children, or parents.

    If someone dies without a will, the law decides how the assets are shared. That’s why it’s so important to have a valid will—it ensures your wishes are followed.

    Example under the Distribution Act:

    If the deceased leaves behind…Parent(s) getSpouse getsChildren get
    Parents, spouse & children1/41/41/2

    🏠 Joint Name Properties – Not As Simple As You Think

    Many Malaysians put properties under joint names thinking it will automatically go to the other person when they pass away. But that’s not always true.

    There are two main types of joint ownership in property law:

    1. Joint Tenancy
      • Comes with the right of survivorship.
      • If one owner dies, the property automatically goes to the surviving owner.
      • This is common among married couples.
    2. Tenancy in Common
      • Each person owns a specific share.
      • When one dies, their share becomes part of their estate and is distributed according to their will or the law.
      • This is more common in Malaysia, even when it’s between family members.

    Here’s the catch: Most joint name properties in Malaysia are actually treated as tenancy in common, unless stated otherwise. That means—even if your name is on the title—the other person’s share doesn’t automatically go to you. It becomes part of their estate and is shared out according to their will or inheritance laws.


    ⚠️ Common Pitfalls to Watch Out For

    1. Unclear Ownership Type
      If it’s not clearly stated whether it’s joint tenancy or tenancy in common, it can lead to confusion—and disputes.
    2. Unequal Contributions
      One person may have paid more, but the property is split 50-50 on paper. This often leads to disagreements among family members.
    3. Family Conflicts
      Things can get messy with children from previous marriages, siblings, or estranged family members. Without clear planning, emotions can take over.
    4. Outdated or No Will
      A will that hasn’t been updated—or worse, no will at all—can cause contradictions and legal battles during probate.

    ✅ What You Should Do

    To protect your assets and your loved ones from future disputes:

    • ✅ Talk to a professional estate planner or lawyer
    • ✅ Make sure your will is valid, updated, and matches your current ownership structure
    • ✅ Clearly state the type of joint ownership on your property documents
    • ✅ Keep your family informed, so there are no surprises later

    Joint ownership may seem like the easy way, but without proper planning, it can create unnecessary complications. A little preparation now can give your family peace of mind in the future.

    From the desk Of

    Miichael Yeoh

    Property Strategist

    Thank you for subscribing!

    Please check your email to confirming your subscription.

  • Should You Buy Property in Malaysia Now? Insights 2025

    Should You Buy Property in Malaysia Now? Insights 2025

    Published: July 17, 2025
    By: Miichael Yeoh


    After a strong run in 2023 and 2024, Malaysia’s residential property market is finally taking a breather. While some see this as a red flag, the data paints a more balanced picture—one of resilience and recalibration, not recession.

    So, what exactly is happening in 2025? And should you be worried or ready to buy?

    Let’s break it down.


    📉 Q1 2025: Slower But Still Solid

    Malaysia’s residential property transactions dropped 6.2% in Q1 2025 compared to Q4 2024. That’s the first notable slowdown after nearly two years of consistent growth.

    But here’s the catch: activity levels are still higher than in 2022, which means we’re not seeing a crash—just a cooling-off.

    “The slowdown is expected. It’s the market stabilizing after a hot streak,” said a property analyst from KL.


    📈 Prices Are Still Moving Up

    The national average house price reached RM483,879 in Q1, reflecting a +1.4% year-on-year increase. Areas like Klang Valley, Penang Island, and Johor Bahru continue to dominate in both value and volume.

    Here’s a quick snapshot:

    AreaAvg. Price (Q1 2025)YoY Price Growth
    Klang ValleyRM 550,000+2.1%
    Penang IslandRM 620,000+1.8%
    Johor BahruRM 460,000+1.2%

    🏗️ Developers Stay Selective with New Launches

    With rising construction costs and cautious sentiment, developers are choosing quality over quantity. Most new launches are in well-connected, lifestyle-oriented locations—think smart townships, mixed developments, and green-certified homes.

    Hot-selling projects like Elmina Ridge 2 and Avalon Cybersouth saw near 90% take-up rates, showing buyers are still ready to act—when the product is right.


    🔍 What’s Supporting the Market?

    Despite the slowdown in transactions, several key factors are helping the market stay afloat:

    • Stable interest rates (BNM kept the OPR steady).
    • Low unemployment rate (around 3.3%).
    • Young home-buying population (millennials & Gen Z entering the market).
    • MM2H visa tweaks requiring foreigners to purchase property.

    These are long-term positives that signal stability in the residential segment.


    ⚠️ What Buyers & Investors Should Watch

    While the fundamentals are strong, here are a few caution signs to keep in mind:

    1. Affordability gaps in cities like KL and Penang may limit demand in certain price segments.
    2. Oversupply risks in high-rise areas still exist, especially where demand isn’t organic.
    3. Policy changes—any adjustments to RPGT, stamp duties, or loan rules could shift the playing field fast.

    💡 Final Thoughts

    If you’re a buyer or investor waiting for a market crash—you might be waiting for a while. What we’re seeing now is not the end of growth, but a healthier, more stable market emerging after years of turbulence.

    This could actually be the perfect window to enter—especially if you’re eyeing the right locations, products, and long-term value.

    🗣 “The best time to buy property is when others hesitate—because real opportunity hides in uncertainty.”


    Need help identifying the right property in 2025?
    Join the Property EDU Club — get expert guidance, real-life case studies, and insider access to property deals most investors never see.

    👉 Click here to learn more and join now

  • Discover Malaysia’s RM13.3 Billion in Unclaimed Money

    Discover Malaysia’s RM13.3 Billion in Unclaimed Money

    As of April 2025, the Accountant General’s Department of Malaysia (JANM) has recorded a staggering RM13.3 billion in Unclaimed Money (Wang Tak Dituntut – WTD). However, despite decades of awareness campaigns, only about RM4 billion has been successfully claimed since the initiative began in 1977.

    According to Accountant General Nor Yati Ahmad, many Malaysians are still unaware that they might be entitled to unclaimed funds — or have never checked.

    To improve public awareness, JANM is actively reaching out through community programs and mobile campaigns, especially in rural areas. But the process remains simple for anyone, anywhere, with internet access.


    💡 What Is Unclaimed Money (WTD)?

    Unclaimed Money refers to funds that legally belong to an individual but remain unpaid for over one year. These include:

    • Dormant bank account balances
    • Unclaimed insurance benefits
    • Refunds or overpayments
    • Dividends from investments
    • Uncollected salaries or bonuses

    ✅ How to Check If You Have Unclaimed Money

    Option 1: Online via eGUMIS

    1. Visit https://egumis.anm.gov.my
    2. Register with your NRIC, email, and a password
    3. Log in and enter your IC number to search
    4. If money is found under your name:
      • Upload necessary documents
      • Submit your claim and wait for verification

    Option 2: Visit a JANM Office

    1. Bring required documents (see below)
    2. Complete the WTD Claim Form
    3. Submit in person at any JANM branch

    📄 Documents Required for Claims

    For Personal Claims:

    • Copy of NRIC (front & back)
    • Bank account details (if requesting transfer)
    • Completed claim form (manual method)

    For Claims on Behalf of a Deceased Family Member:

    • Death certificate
    • Proof of relationship (e.g., birth/marriage certificate)
    • Letter of Administration or Grant of Probate
    • Copy of claimant’s NRIC

    Important:
    ✔️ Claims are free of charge
    ✔️ There is no time limit to submit your claim


    📢 Don’t Let Your Money Go Unclaimed

    If you’ve ever opened a bank account, had an insurance policy, received dividends, or worked in Malaysia, there’s a chance you may have unclaimed money waiting. Take just 5 minutes to check — and share this with your family and friends. It could make a real difference!

    From the desk of

    Miichael Yeoh
    WEEKLY PROPERTY ROUNDUP

    Malaysia’s Budget 2027 puts first-home buyer support in focus, while infrastructure delivery in Sabah and fresh data from Australia and the UK offer important lessons for property buyers and investors.

    Is Now a Good Time to Buy Property in Malaysia ?

    This article emphasizes the importance of selecting the right property based on individual circumstances, rather than solely predicting market trends. It highlights Malaysia’s resilient property market , underscored by vital factors affecting demand.

  • EPF Malaysia : Everything You Need to Know

    EPF Malaysia : Everything You Need to Know

    The Employees Provident Fund (EPF), or Kumpulan Wang Simpanan Pekerja (KWSP), plays a crucial role in retirement planning for millions of Malaysians. Whether you’re just starting your career or planning to retire soon, understanding how EPF works is essential to building a secure financial future.

    This updated 2025 guide covers everything you need to know about EPF — from contributions and dividends to withdrawals and the latest changes.


    🔎 What is EPF?

    EPF is a government-managed retirement savings scheme designed to help Malaysian workers in the private and non-pensionable public sectors save consistently during their working years.

    Think of it as a mandatory savings plan, where both the employer and employee contribute a fixed percentage of the employee’s monthly salary. These contributions are then invested in a diversified portfolio — including property, equities, and bonds — to generate long-term returns.

    Members can withdraw their savings upon retirement or under special conditions such as:

    • Buying a home
    • Paying for education
    • Medical emergencies
    • Leaving Malaysia permanently
    • Disability or death

    👥 Who Needs to Contribute to EPF?

    EPF contributions are mandatory for:

    • Private sector employees
    • Non-pensionable government employees
    • Domestic workers (if both parties agree)

    Foreign workers and expatriates can opt out, unless otherwise required by their contract. Meanwhile, self-employed individuals and freelancers can contribute voluntarily to build their own retirement savings.


    💰 2025 EPF Contribution Rates

    Here are the official EPF contribution rates for 2025:

    For Malaysian Employees

    Age GroupEmployerEmployee
    Below 60 (Salary ≤ RM5,000)13%11%
    Below 60 (Salary > RM5,000)12%11%
    60 and above4%0% (optional)

    ➡️ Employees may voluntarily increase their personal contributions above 11%.

    For Foreign Workers (Starting Q4 2025)

    EmployerEmployee
    2%2%

    This new mandate is part of the Employees Provident Fund (Amendment) Bill 2025.


    📈 How EPF Dividends Work

    EPF savings grow over time through annual dividends, typically announced in the first quarter each year. These dividends are based on returns from EPF’s investment activities.

    📊 Recent Dividend Rates:

    • 2023:
      • 5.25% (Conventional)
      • 4.75% (Shariah-compliant)
    • 2024 (Announced March 2025):
      • 6.30% for both Conventional and Shariah accounts

    Dividends are compounded, meaning you earn returns on your contributions and on past years’ dividends.


    🔧 2025 Updates You Should Know

    ✅ Voluntary Contribution Limit Increased

    The annual cap for voluntary contributors is now RM100,000 — great news for freelancers and business owners.

    ✅ i-Akaun App Revamp

    The all-new KWSP i-Akaun app offers powerful features, including:

    • Instant account activation
    • Voluntary contribution options
    • Nominee management
    • Downloadable account statements
    • Retirement calculator
    • i-Sayang (transfer savings to family)
    • Cancel pending withdrawals
    • Access to healthcare/takaful info
    • Tips and official updates from EPF

    🏦 EPF Withdrawal Options

    While EPF is designed for retirement, members may withdraw savings under specific conditions:

    ✅ Withdrawal Categories:

    • Age 50, 55, or 60 (partial/full)
    • Housing (purchase, loan repayments, or settlement)
    • Education (university or college fees for self or children)
    • Medical expenses (critical illness treatments)
    • Leaving Malaysia permanently
    • Death or total permanent disability

    Each type of withdrawal has its own set of requirements and documentation.


    📲 How to Manage Your EPF Account

    Managing your EPF account is simple and convenient with i-Akaun.

    Steps to Access:

    1. Register via the EPF website or self-service kiosk
    2. Download the i-Akaun app
    3. Log in using your IC number and set a password
    4. Activate via SMS or at any EPF branch

    What You Can Do with i-Akaun:

    • Check balances and contribution history
    • Apply for eligible withdrawals
    • Update personal information
    • Manage nominees
    • Access statements and tools

    EPF self-service kiosks are also available nationwide for walk-in services.


    ❌ Common Myths About EPF – Busted!

    🔸 “I can’t change my EPF nominee.”
    ✅ You can update it anytime via the app or at a branch.

    🔸 “EPF is only useful at retirement.”
    ✅ You can make partial withdrawals for housing, education, or health.

    🔸 “EPF dividends are fixed.”
    ✅ They fluctuate based on EPF’s investment performance.

    🔸 “I don’t need to check my EPF.”
    ✅ Mistakes, outdated information, or missing nominees can cause serious issues later.


    ❓ Frequently Asked Questions (FAQs)

    Q: Can I contribute more than 11%?
    Yes, you can increase your contribution or make additional voluntary payments.

    Q: What happens to my EPF when I die?
    It will go to your nominated beneficiary. If no nominee is listed, the funds will go through estate administration.

    Q: Can I switch to a Shariah-compliant EPF account?
    Yes, but only during specific switching windows announced by EPF.

    Q: Is my EPF money safe?
    Yes. EPF is backed by the Malaysian government and is one of the most secure long-term savings tools available.

    Why EPF Is Important

    ✅ Secure Retirement
    EPF ensures Malaysians have savings to support themselves after leaving the workforce, reducing reliance on family or government aid.

    ✅ Steady Growth Through Dividends
    Your money grows each year via compounding dividends, making it one of the most stable long-term savings tools.

    ✅ Government Protection
    EPF is backed by the Malaysian government, making it a low-risk savings platform.

    ✅ Financial Flexibility
    Members can access their savings before retirement for housing, education, or medical needs — giving them a financial buffer during key life events.

    ✅ Easy Account Management
    With tools like the upgraded i-Akaun app, managing, tracking, and planning for your future has never been easier.


    ✅ Final Thoughts

    EPF is not just a retirement fund — it’s a powerful financial safety net that helps Malaysians prepare for the future. By understanding your contributions, making informed withdrawal decisions, and using the i-Akaun app, you can take control of your financial destiny.

    Plan smart. Save smart. Retire strong.

    From the Desk of

    Miichael Yeoh

  • Unlock Wealth with Smart Mortgage Strategies

    Unlock Wealth with Smart Mortgage Strategies

    Did you know that 70% of Malaysians exhaust their EPF savings within just five years of retirement?

    This is a shocking reality, but it doesn’t have to be yours. Without proper financial and mortgage planning, many people find themselves struggling with rising living costs, increasing debt, and an uncertain future.

    Many people believe that simply saving money in a bank or relying on EPF will be enough to sustain them after retirement. However, with inflation, economic uncertainties, and an increasing cost of living, savings alone are not enough. To secure your financial future, you need a smart strategy that builds wealth while you sleep—and that’s where financial and mortgage planning come in.

    If you want to retire rich, not broke, it’s time to take control of your financial future!


    The Importance of Financial & Mortgage Planning

    1️⃣ Your Salary Alone is Not Enough

    Many Malaysians rely solely on their salaries as their primary source of income. However, depending only on salary comes with risks:
    ❌ Job insecurity – What happens if you lose your job or your business slows down?
    ❌ Limited earning potential – Salary increments may not keep up with rising expenses.
    ❌ No long-term wealth creation – Once you stop working, your income stops too.

    By understanding financial planning and leveraging mortgages, you can turn your income into wealth-building assets like property investments that generate passive income.

    ✅ Smart financial planning ensures that your money works for you, not the other way around.

    2️⃣ The Rising Cost of Living & Inflation

    The price of food, petrol, housing, and healthcare has been rising every year. What seems affordable today might be out of reach in the next five or ten years.

    📌 Example: 12 years ago, a property in Kuala Lumpur cost RM300,000. Today, the same property is worth RM600,000. If you had bought it back then, you would have gained RM300,000 in capital appreciation.

    Now imagine if you had invested in properties over the years—how much wealth would you have built?

    This is why financial planning and leveraging mortgages for property investment is crucial. The sooner you start, the better you can protect yourself from inflation and rising costs.

    3️⃣ Using Mortgages as a Wealth-Building Tool

    Many people see mortgages as a burden. But in reality, a mortgage is one of the most powerful financial tools you can use to build wealth.

    Here’s how:
    ✅ Leverage: With a mortgage, you can own high-value properties with only a fraction of the cost upfront.
    ✅ Passive Income: By renting out your properties, you create a steady income stream that covers loan repayments and generates profit.
    ✅ Capital Appreciation: Over time, property values tend to increase, helping you build long-term wealth.

    4️⃣ Securing Your Retirement with Smart Investments

    Many retirees face financial struggles because they failed to plan early. Without a steady stream of passive income, they depend entirely on their savings, which can deplete quickly.

    A well-structured mortgage plan can help you own multiple properties that generate rental income. This means that by the time you retire, you’ll have a steady cash flow to support your lifestyle—without relying on savings alone!


    How to Start Planning Your Financial Future Today

    🔹 Understand how mortgages work – Learn how to maximize loan approvals and use mortgages to grow your wealth.
    🔹 Invest in the right properties – Avoid costly mistakes and find properties that give high returns.
    🔹 Create multiple income streams – Secure your future with passive income from real estate investments.

    Final Thought: The Best Time to Invest is NOW!

    Many people delay financial planning, thinking they have plenty of time. But the truth is, the longer you wait, the harder it becomes to build wealth.

    💡 The best time to invest was yesterday. The second-best time is NOW!

    🚀 Don’t wait until it’s too late. Take charge of your financial future today!

    From the Desk of

    Miichael Yeoh
  • Real Estate Summit 2025: A Resounding Success!

    Real Estate Summit 2025: A Resounding Success!

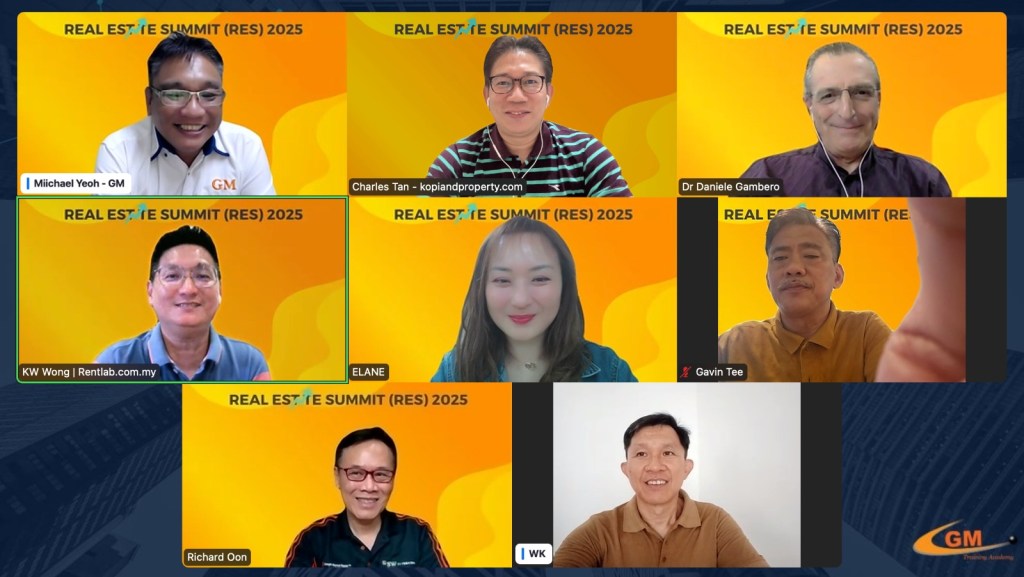
    After two days of insightful discussions, expert sharing, and valuable networking, the Real Estate Summit 2025 (RES2025) has officially concluded! This event brought together some of the most renowned experts in real estate, finance, and investment, providing participants with actionable insights into the property market, financial planning, and smart investment strategies for 2025.

    We were honored to welcome participants from Malaysia, the Philippines, Singapore, the USA, Germany, and many other countries. The diversity of attendees enriched discussions and created a vibrant learning environment.

    A Heartfelt Thank You to Our Participants & Speakers

    First and foremost, we extend our deepest gratitude to all participants for attending RES2025. Your enthusiasm and eagerness to learn made this event truly impactful.

    A special appreciation to our distinguished speakers, whose expertise and insights played a crucial role in the success of RES2025:

    🔹 Dato’ Sri Gavin Tee – A real estate expert who shared his forecast on the 2025 property market and upcoming investment opportunities.
    🔹 Richard Oon – A taxation and financial planning specialist who guided participants on tax-saving strategies and financial management for property investors.
    🔹 Dr. Daniele Gambero – A respected market analyst who discussed real estate trends, mortgage challenges, and investment potential in 2025.
    🔹 Dr. Elane Goh – A finance and investment strategist who shared her insights on wealth creation through property investments and financial planning.
    🔹 WK Ng – A seasoned property investor who transitioned from the corporate world to full-time investing, providing real-life success strategies.
    🔹 KW Wong – A PropTech innovator and Secretary-General of the Malaysia PropTech Association, who spoke about the digital transformation of the rental market.
    🔹 Charles Tan – A leading property market analyst who offered valuable perspectives on Malaysia’s evolving real estate landscape.
    🔹 Miichael Yeoh – A mortgage and financial expert, who emphasized the importance of planning before making any major investment decisions.

    Your dedication and willingness to share your knowledge made RES2025 a game-changing event for all attendees.

    Special thanks to our co-organiser POLA Malaysia and our media partners Property Hunter and kopiandproperty.

    Key Takeaways from RES2025

    Throughout the two-day summit, participants gained powerful insights into the property industry, with topics covering:

    ✔️ Where to Invest in 2025 – Discovering high-potential investment hotspots.
    ✔️ Real Estate Market Trends – Adapting to economic shifts and evolving regulations.
    ✔️ Financial Planning & Taxation – Understanding tax incentives, financial structures, and mortgage strategies.
    ✔️ Mortgage Market 2025 – The latest developments in home financing and lending policies.
    ✔️ PropTech Innovations – The rise of digital property platforms and the impact on buying, selling, and renting.
    ✔️ Investment Strategies – How to build a profitable real estate portfolio.

    As Miichael Yeoh emphasized in his session: “Plan first before making your next move.” Strategic financial and investment planning is essential to achieving long-term success in real estate.
    The Power of Networking & Knowledge Sharing

    Beyond expert talks, RES2025 provided an invaluable opportunity for participants to connect with industry leaders, experienced investors, and like-minded individuals. The event fostered an environment where attendees could exchange ideas, gain exclusive insights, and build meaningful professional relationships.

    Looking Forward: What’s Next?

    The success of RES2025 reaffirms GM Training Academy’s commitment to empowering individuals with property education and financial literacy. We believe that informed decisions lead to successful investments, and we are dedicated to helping investors, homeowners, and professionals navigate the ever-changing real estate market.

    🚀 Upcoming Initiatives:

    ✅ More masterclasses and training workshops
    ✅ Exclusive webinars featuring top industry experts
    ✅ Property investment study tours
    ✅ Advanced financial and mortgage planning courses

    Stay Connected & Keep Learning

    📢 Missed RES2025? No worries! Stay connected with us for upcoming programs that will continue to provide valuable industry insights and expert guidance.

    Once again, THANK YOU to all our participants and speakers for making RES2025 a grand success! We look forward to seeing you at our next event.

  • Effects of OPR Changes on Borrowing and Savings

    Effects of OPR Changes on Borrowing and Savings

    As of January 2025, Bank Negara Malaysia (BNM) has maintained the Overnight Policy Rate (OPR) at 3.00%, a position held since May 2023.

    Understanding the Overnight Policy Rate (OPR)

    The OPR is the benchmark interest rate at which banks lend to one another overnight. Set by BNM, it serves as a primary monetary policy tool to regulate liquidity, control inflation, and sustain economic growth.

    Implications of an OPR Increase

    When BNM raises the OPR, it signals an intent to tighten monetary policy. The effects of such an increase include:

    Higher Borrowing Costs: Banks typically respond to an OPR hike by raising their base rates, leading to increased interest rates on loans and mortgages. This results in higher monthly repayments for borrowers.

    Enhanced Savings Returns: Conversely, depositors may benefit from higher interest earnings on savings and fixed deposits, encouraging increased savings.

    Controlled Inflation: Elevated borrowing costs can dampen consumer spending and business investments, helping to moderate demand-pull inflation.

    Currency Appreciation: Higher interest rates can attract foreign investment, potentially strengthening the Malaysian ringgit.

    Impact on Property Market: Increased interest rates may lead to higher mortgage costs, potentially cooling property demand and affecting market dynamics.

    Recent Economic Context

    In the third quarter of 2024, Malaysia’s economic growth slowed to 5.3% from 5.9% in the previous quarter, influenced by reduced oil and gas production. Despite this, robust household spending and increased investments provided support.

    BNM’s Monetary Policy Stance

    BNM has maintained the OPR at 3.00% since May 2023, citing positive economic growth and steady inflation. Economists anticipate that the central bank will keep the OPR unchanged until at least 2026, aligning with current economic assessments.

    Interest Rate Impact Example

    Let’s look at an example of how interest rates affect property loans. Assume you’re borrowing RM500,000 for 30 years:

    • Current Interest Rate (4.5%): Monthly repayment is approximately RM2,533.43.
    • If OPR Increases by 25 Basis Points (4.75%): Monthly repayment rises to around RM2,608.82.
    • Impact: This increase of RM75.39 per month adds up to RM27,140.40 over the loan’s term.

    This illustrates why understanding interest rates and their potential changes is crucial for planning your finances.

    Conclusion

    An increase in Malaysia’s OPR has multifaceted effects, influencing borrowing costs, savings returns, inflation, currency value, and the property market. Understanding these dynamics is crucial for individuals and businesses to make informed financial decisions in response to monetary policy changes.

    From the Desk of

    Miichael Yeoh