Author: miichaelyeoh

  • From Talk to Ground: Experiencing YBK Industrial Park Firsthand

    From Talk to Ground: Experiencing YBK Industrial Park Firsthand

    A Powerful Sunday at YBK Industrial Park, Rimbayu South
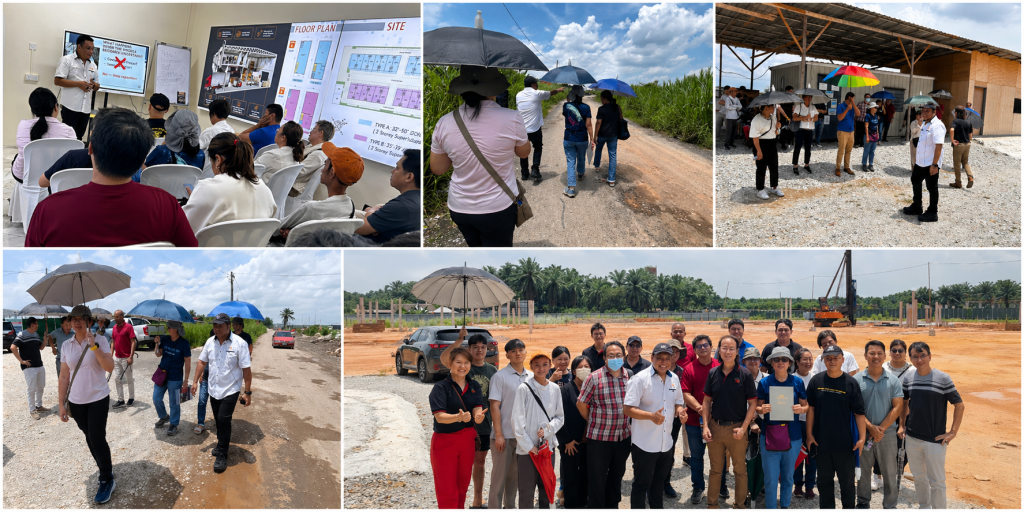
    Last Sunday, we had an absolutely fantastic session at YBK Industrial Park, Rimbayu South. This was a private, invitation-based event—and we had a full house. The room was filled with serious participants who came prepared, not just to listen, but to understand where the next wave of industrial opportunity is heading.

    I started my session at 11:20 AM. As always, my role was to set the stage before the project presentation begins. We walked through the macro environment—global capital movement, supply chain shifts, and why industrial assets are becoming increasingly relevant. From there, I narrowed it down to Malaysia’s positioning, and eventually to why locations like Rimbayu South are quietly gaining traction.

    Because at the end of the day, a good investment is not about chasing trends—it’s about understanding timing and positioning.

    Benjamin from YBK followed up with a solid presentation on the project itself. Straightforward, structured, and backed by fundamentals. No unnecessary noise—just clarity on what the project offers, how it is planned, and where it stands in today’s market.

    At 12:40 PM, we moved into what I always consider the most important part of any session—the site visit.

    The project is located just directly opposite the sales gallery, making it extremely convenient. But more importantly, it allows participants to experience the site physically, not just conceptually.

    It was a hot and humid afternoon—but honestly, that’s part of the process. Property is not meant to be understood in air-conditioned rooms alone.

    Participants were given a choice—to walk with me or take a comfortable MPV arranged by the developer. Some came prepared with umbrellas and caps. Some didn’t—but still came along anyway. That’s the kind of commitment I like to see.

    We started the short walk together, and along the way, I shared additional insights on upcoming developments surrounding YBK Industrial Park. This is where many investors begin to see the bigger picture—because value is not just about what is built, but what is coming next.

    YBK Industrial Park @ Rimbayu South

    Within just 3 minutes, we arrived at the site.

    And this is where the real conversation begins.

    Questions started coming in—sharp, practical, and focused on real investment considerations. From layout and access to tenant demand and future positioning. Both myself and the developer team addressed everything directly, on-site, under the 1 PM sun.

    No slides. No filters. Just real answers on real ground.

    After that, we took a slow walk back, captured a group photo, and wrapped up the session over lunch. It was a simple but highly productive session—exactly how property engagement should be.

    Not just presentation. But experience.


    Missed This Session?

    If you couldn’t make it for this round, here’s your next opportunity.

    Join my upcoming webinar:

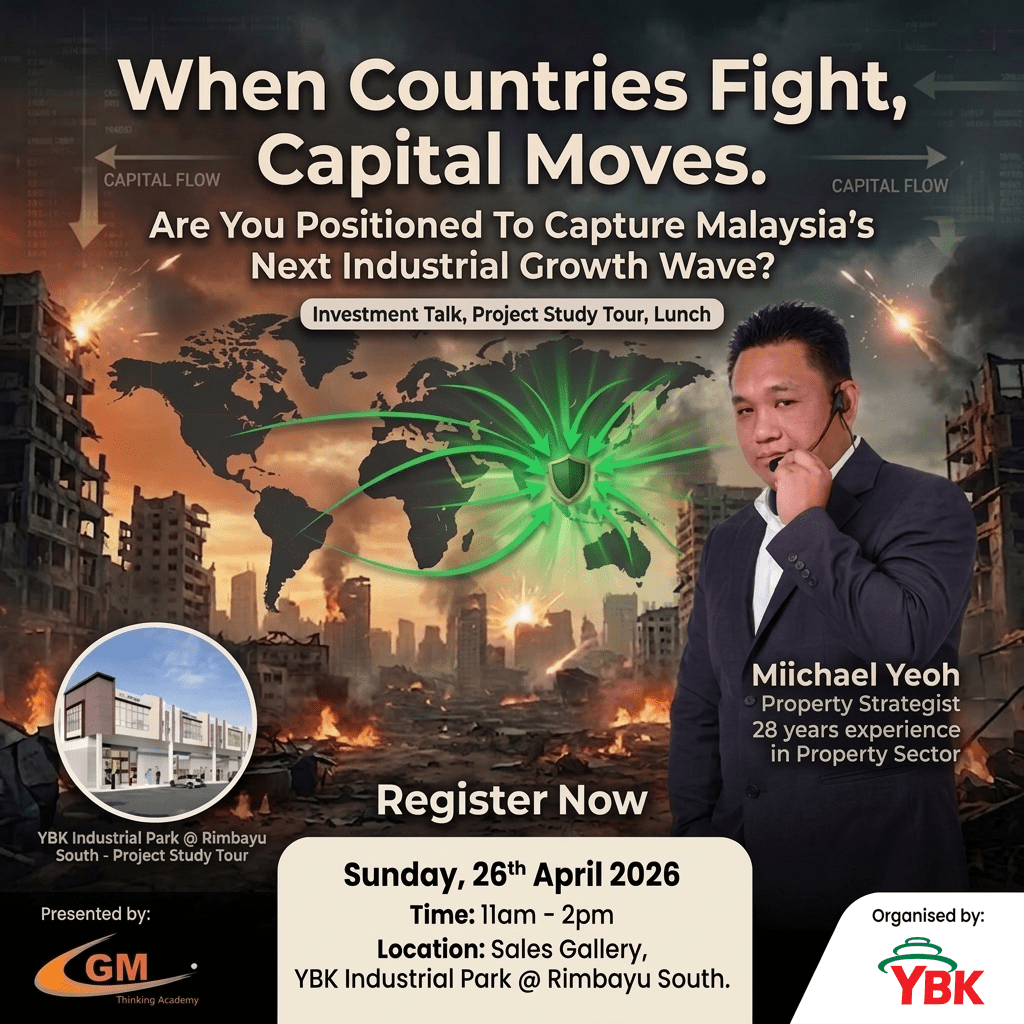
    “When Countries Fight, Capital Moves. Are you positioned to capture Malaysia’s Next Industrial Growth Wave?”

    📅 Date: 7 May 2026 (Thursday)
    ⏰ Time: 8:30 PM
    📍 Location: Zoom

    This session will go deeper into the macro forces shaping capital flow, and more importantly, how to position yourself ahead of the next industrial growth cycle.

    👉 Registration link: https://ybkgm.eventbrite.sg/?aff=ws

    If you are serious about understanding where the market is heading—not just where it has been—this is a session you should not miss.

    Miichael Yeoh

    Property Strategist

    Disclaimer: This reflects the author’s personal views based on market experience and current observations. It is not financial advice. Smart investors do their own research before making any move.
  • Before You Buy Property, Do This First — Or You’re Just Guessing

    Before You Buy Property, Do This First — Or You’re Just Guessing

    Smart Investors Don’t Start With Property — They Start With Demand

    Most people think property investment starts with:

    Location.
    Price.
    Developer.

    It doesn’t.

    It starts with a much more fundamental question:

    Are you buying for own use… or for investment?

    Because if you get this wrong, everything else becomes noise.


    Step 1: Define Your Purpose (No Grey Area)

    I’ve seen buyers say they are investing…

    But make decisions based on:

    • Design
    • Lifestyle
    • Personal preference

    That’s not investing.

    That’s emotion.

    If it’s own stay, you follow your lifestyle.

    If it’s investment, you follow demand and numbers.


    Step 2: Know Your Budget (This Sets Your Playing Field)

    Before anything else:

    • What is your true affordability?
    • What is your financing capacity?
    • What is your holding strength?

    Because in property:

    You don’t lose money when you buy wrong.
    You lose money when you can’t hold.

    Especially for investors—cash flow and holding power are everything.


    Step 3: Real Investors Do One Thing Differently — They RESEARCH

    This is the biggest gap in the market.

    Most buyers rely on:

    • Marketing materials
    • Sales narratives
    • “Good location” claims

    But experienced investors?

    They study the market before they commit.


    What Do You Actually Research?

    1. Demand & Demographics (The Real Starting Point)

    Forget the building first.

    Ask:

    Who is the end user of this property?

    • Young professionals?
    • Families?
    • Tourists?
    • Businesses?

    If you don’t understand demand,
    you’re not investing—you’re guessing.


    And This Is Where Industrial Property Becomes Interesting

    For big-budget investors, the shift is already happening.

    Demand is no longer driven by lifestyle.

    It’s driven by business movement and capital flow.

    Look at what’s happening:

    • Manufacturing relocation into Malaysia
    • Growth in logistics and warehousing
    • E-commerce expansion
    • Supply chain restructuring across ASEAN

    This creates a different type of demand:

    • Larger space requirements
    • Functional layouts over aesthetics
    • Accessibility to ports, highways, and labour
    • Long-term tenancy from businesses (not individuals)

    In other words:

    Industrial demand is economic-driven, not sentiment-driven.

    And that’s exactly what sophisticated investors are looking for.


    2. Price Per Square Foot (Entry Determines Exit)

    You make money when you buy right.

    Compare:

    • Nearby transactions
    • Competing projects
    • Replacement cost

    If you enter too high, your upside is already limited.


    3. Surrounding Supply (The Silent Risk)

    Most investors ignore this.

    But supply determines:

    • Rental pressure
    • Vacancy risk
    • Exit liquidity

    Too much incoming supply?

    Even a “good project” can underperform.


    4. Infrastructure & Connectivity (Follow the Growth)

    No area grows randomly.

    Growth follows:

    • Highways
    • Ports
    • Rail (LRT / MRT / logistics links)
    • Industrial corridors

    If infrastructure is expanding, demand usually follows.


    5. Rental & Yield Reality Check

    At the end of the day:

    Can it generate income?

    • What is the realistic rental?
    • Who is the tenant profile?
    • What is the occupancy expectation?

    If the numbers don’t work on paper,
    don’t rely on hope.


    What I’ve Learned From the Ground

    After evaluating multiple projects and markets, one thing is clear:

    The winners are not those who buy the most.
    The winners are those who understand demand the best.

    Every property I consider goes through:

    • Demand validation
    • Market comparison
    • Supply analysis
    • Financial assessment

    Because once you commit,
    you’re not just buying property…

    You’re locking in a decision for years.


    Final Thought

    Property investment has evolved.

    It’s no longer about chasing what’s popular.

    It’s about understanding why demand exists—and where it’s going next.

    Those who do the work will always have an edge.

    Those who don’t…

    Will always be reacting.


    Disclaimer: This reflects the author’s personal views based on market experience and current observations. It is not financial advice. Smart investors do their own research before making any move.
    From the Desk of

    Miichael Yeoh

  • Property Is Still Alive — But the Game Has Changed

    Property Is Still Alive — But the Game Has Changed

    Buying a property today is very different compared to 10 or 20 years ago.

    Back then, property could sell very easily.
    Developers launched, buyers queued, and decisions were made quickly.

    Today, the world has changed.

    The way people buy property has changed.
    The way markets behave has changed.
    And more importantly, the way buyers think has changed.

    Buyers today are far more informed.

    Before even paying a booking fee, many would have already:

    • Compared multiple projects
    • Studied pricing trends
    • Checked developer track record
    • Analysed location fundamentals
    • Calculated loan eligibility and cash flow

    In other words, today’s buyers are not just buyers — they are researchers.


    At the same time, the global environment is not exactly calm.

    We are seeing ongoing geopolitical tensions — from the US–Iran situation to instability in parts of the Middle East.
    Interest rates, inflation, and currency movements continue to shift.

    All these create one thing: uncertainty.

    And when uncertainty comes in, market behaviour changes.

    From what I observe in today’s property market:

    • Investors are waiting — not exiting
    • Sellers are holding — not reducing
    • Buyers are selective — not absent

    Let that sink in.

    The market is not dead.
    It is simply… more cautious.


    And here is something many people miss:

    👉 When the market is not stable, that is where the opportunity lies.

    Why?

    Because:

    • Less emotional buying
    • More rational pricing
    • More room for negotiation
    • More time to analyse properly

    In a hot market, people chase.
    In a cautious market, people choose.

    And those who choose well, win.


    This is exactly why I started focusing on Property Market Intelligence.

    Not just looking at property as a product,
    but understanding:

    • Market timing
    • Buyer psychology
    • Financing structure
    • Exit strategy
    • Risk positioning

    This approach is built from more than 25 years in the property and banking industry.

    I have gone through multiple market cycles:

    • Asian Financial Crisis
    • Global Financial Crisis
    • Property slowdowns
    • Policy changes
    • And shifting buyer behaviours across decades

    Every cycle teaches one thing:

    👉 The market will always move — but not everyone moves with it.


    Today, success in property is no longer about:
    “Buy and wait.”

    It is about:
    “Buy with clarity.”

    Because in today’s market:

    • Information is everywhere
    • But insight is rare

    If you are buying today, don’t just ask:

    “Is this a good property?”

    Ask instead:

    • Who will buy from me later?
    • What is the demand driver here?
    • How does financing affect my holding power?
    • What happens if the market stays slow for 3–5 years?

    That is how professionals think.


    The market has not disappeared.

    It has simply matured.

    And in a mature market,
    strategy will always beat impulse.


    Miichael Yeoh
    Property Strategist | Author

    Author of:
    Think Like a Banker, Act Like a Player
    Property Investment BLT
    Buying Property Like a Pro (MPH Bestseller)

  • Will the US–Israel–Iran War Affect Property in Malaysia?

    Will the US–Israel–Iran War Affect Property in Malaysia?

    Will the US–Israel–Iran War Affect Property in Malaysia?

    Most people think war is “far away”.

    Middle East… not Malaysia… not our problem.

    But if you’ve been in property long enough, you’ll realise this:

    What happens globally will always find its way into your loan, your instalment, and your tenant’s wallet.

    Let’s break it down — from a real-world property perspective.


    1. The Impact Will Not Be Direct — But It Will Be Real

    Malaysia is not at war.

    Our property market is not suddenly crashing tomorrow.

    In fact, economists say the direct impact on Malaysia is limited — but the indirect effects are where things get interesting.

    And property… is always affected by indirect forces.


    2. The First Domino: Oil Prices

    Right now, oil prices are already spiking above USD100 due to the conflict.

    Why does this matter?

    Because oil affects everything:

    • Construction cost (cement, steel, transport)
    • Developer margins
    • Inflation
    • Interest rates

    When oil goes up → cost of living goes up → buyers become more cautious

    And this is where property sentiment starts to shift.


    3. Rising Cost of Living = Slower Property Decisions

    Experts already warn that prolonged conflict will push up:

    • Food prices
    • Fertiliser costs
    • Transportation costs

    We are already seeing supply chain disruptions globally.

    Simple logic:

    When people feel poorer… they delay big decisions.

    And property is the biggest decision of all.

    From my experience:

    • First-time buyers will hesitate
    • Investors will become more selective
    • Loan approvals may tighten

    4. Interest Rates — The Silent Killer

    War → Inflation → Central banks stay cautious

    Even if Bank Negara doesn’t immediately raise rates, the global environment matters.

    If inflation remains high:

    • Financing cost stays elevated
    • Instalments stay high
    • Yield becomes more important than ever

    This is where many investors get it wrong.

    They buy based on “price appreciation”.

    But in uncertain times:

    Cash flow becomes king.


    5. Currency & Investor Sentiment

    During global conflict:

    • Money flows to “safe havens”
    • Emerging markets (like Malaysia) can see weaker currency

    This affects:

    • Foreign investment
    • High-end property demand
    • Developer confidence

    It doesn’t crash the market…

    But it slows momentum.


    6. The Hidden Opportunity (Most People Miss This)

    Here’s the part many don’t talk about.

    Malaysia is actually in a neutral advantage position:

    • We are politically stable
    • Not directly involved
    • Still attractive compared to more volatile regions

    Historically, during global uncertainty:

    Smart investors don’t exit — they reposition.

    Opportunities may appear in:

    • Undervalued projects
    • Developers needing stronger sales
    • Better packages (rebates, freebies, furnished units)

    Sound familiar?


    7. My Personal Take (From the Ground)

    I’ve gone through multiple cycles — financial crisis, policy changes, Covid.

    War is just another external shock.

    And property always reacts in the same pattern:

    Phase 1: Fear
    Phase 2: Slowdown
    Phase 3: Adjustment
    Phase 4: Opportunity

    Right now, we are somewhere between Phase 1 and 2.


    Final Thought

    Will this war affect Malaysia property?

    Yes — but not in the way most people think.

    It won’t crash the market overnight.

    But it will:

    • Change buyer behaviour
    • Shift investor strategy
    • Reward those who understand fundamentals

    And this is where experience matters.


    My Advice

    If you are buying:

    • Don’t panic
    • Don’t rush
    • Focus on cash flow, not speculation

    If you are investing:

    This is the time to be sharper — not quieter.


    Miichael Yeoh
    Property Strategist | Author

    Author of:
    Think Like a Banker, Act Like a Player
    Property Investment BLT
    Buying Property Like a Pro (MPH Bestseller)

  • How AI Is Reshaping the Way We Buy Property

    How AI Is Reshaping the Way We Buy Property

    In today’s digital world, buying property is no longer just about location, price, and site visits. Artificial Intelligence (AI) is quietly influencing how buyers think, search, and eventually make decisions.

    Whether you realize it or not, AI is already part of your property journey.


    1. How AI Affects Our Buying Decisions

    AI has changed the way we consume information.

    In the past, buyers relied on agents, brochures, and physical visits. Today, what you see online is curated based on your behavior:

    • What you search
    • What you click
    • What you watch

    Over time, AI builds a profile of your preferences and starts feeding you properties that match your interest.

    Many buyers feel like they “found” the property themselves.

    But in reality, AI has already filtered the options for you.


    2. Property Marketing vs Other Products — Same Model, Different Weight

    From my experience, property marketing is not very different from other products.

    It follows a similar digital marketing structure.

    But the difference is this:

    👉 Property is a high-value, long-term commitment

    You are not buying something for RM1. You are committing hundreds of thousands or even millions.

    Because of that, the marketing is designed to:

    • Build trust
    • Educate
    • Reassure
    • Reduce risk

    It is less about pushing a sale, and more about guiding a decision.


    3. The Sales Funnel Is Always There

    Every product follows a sales funnel.

    Some marketers execute it well. Some only do part of it. Some only focus on getting attention.

    In property, you will typically go through stages like:

    • Seeing ads
    • Clicking to learn more
    • Registering interest
    • Communicating with salespeople
    • Visiting or evaluating

    Whether you notice it or not, you are being guided step by step.


    4. “Why Am I Suddenly Seeing Property Ads Everywhere?”

    This is something many people experience.

    You talk to a friend about buying property… You search a few listings…

    Next thing you know, when you open Facebook or Instagram:

    👉 Property ads start appearing everywhere.

    This is how AI and digital tracking work.

    It picks up signals from your behavior and starts showing you more relevant content.

    It is not magic — it is data.


    5. The Moment You Click, Your Journey Changes

    Once you click on an ad, your journey becomes more intentional.

    You may start seeing:

    • More related ads
    • Follow-up messages
    • Invitations to previews
    • Additional information and content

    This is how modern property marketing works today.


    6. Not All Campaigns Are the Same

    The experience you get depends on the developer or salesperson.

    Some are very basic. Some are more structured and consistent.

    But regardless of how advanced the system is, one thing remains the same:

    👉 The final decision is still yours.


    7. My Perspective as a Property Buyer

    From my own experience in property, one thing is very clear:

    👉 We cannot avoid AI.

    It is already part of how information is delivered to us.

    But here is the part many people overlook:

    AI can influence your interest, but it should not replace your judgment.

    At the end of the day:

    • You are not buying a cheap product
    • You are committing significant capital
    • You are making a long-term financial decision

    Because of that, buyers must still:

    ✔ Do proper research ✔ Understand the numbers ✔ Assess their holding power ✔ Evaluate the location and fundamentals

    And most importantly:

    👉 Listen to people who have real experience in property

    Not everything online tells the full story.


    Final Thoughts

    AI is a powerful tool.

    It can help you discover opportunities faster. It can guide you through options you may not have seen before.

    But it should never replace:

    • Due diligence
    • Critical thinking
    • Experience-based advice

    In property, the difference between a good decision and a bad one is not the advertisement you saw…

    It is the quality of the decision you make after that.

    At the end of the day, AI may influence what you see…

    But it should never replace how you think.

    Property is not a small purchase.
    It’s a long-term financial commitment.

    The difference is not in the advertisement you saw —
    It’s in the decision you make after that.

    Make sure it’s a well-informed one

    From the Desk of

    Miichael Yeoh

    Property Strategist | Author

    Author of:

    Think Like a Banker, Act Like a Player

    Property Investment BLT Buying

    Property Like a Pro (MPH Bestseller)

    P.S. Follow for consistent, experience-based property insights — beyond what marketing tells you.

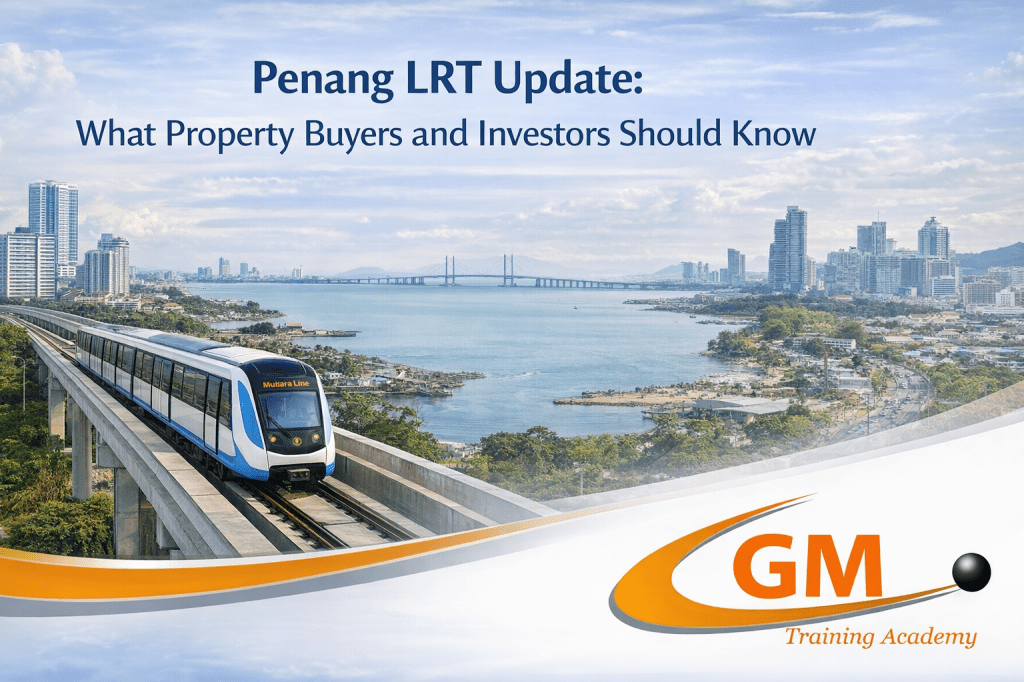
  • Penang LRT Update: What Property Buyers and Investors Should Know

    Penang LRT Update: What Property Buyers and Investors Should Know

    For years, the lack of rail transit has been one of the biggest infrastructure gaps in Penang. While cities like Kuala Lumpur have extensive rail networks, Penang has relied heavily on cars and buses.

    That is now changing.

    The Penang Light Rail Transit (LRT) project — known as the Mutiara Line — is officially underway, marking one of the largest infrastructure developments in northern Malaysia. For property buyers and investors, this project will reshape accessibility, mobility, and potentially property values across key corridors in Penang.

    In this article, we explore the latest updates on the Penang LRT and what it means for the property market.


    1. Overview of the Penang LRT (Mutiara Line)

    The Mutiara Line will be Penang’s first urban rail system and the first LRT outside the Klang Valley. It forms a key component of the Penang Transport Master Plan (PTMP) aimed at improving connectivity across the island and mainland.

    Key facts about the project:

    • Length: approximately 29.5 km
    • Stations: about 21 stations
    • Type: elevated light rail system
    • Estimated cost: about RM16–17 billion
    • Target completion: around 2031

    The line will connect Silicon Island / Penang South Reclamation area to Penang Sentral, passing through major areas such as:

    • Bayan Lepas
    • Sungai Tiram
    • Gelugor
    • Jelutong
    • George Town (Komtar)

    It will also link with Penang Sentral, providing connections to ETS, KTM Komuter and ferry services.

    This integration is designed to create a seamless transport system between Penang Island and Seberang Perai.


    2. Latest Construction Updates (2025–2026)

    Recent developments show that the project has moved from planning into active implementation.

    Penang projects powering ahead

    Important milestones include:

    Construction has begun
    The first phase of works started in 2025, with contractors appointed and preliminary works such as soil investigations and site preparation underway.

    Major works expanding in 2026
    Construction activity is expected to intensify throughout 2026, including elevated track construction and station development.

    Traffic diversions already in place
    Road diversions along areas such as Jalan Sultan Azlan Shah near Bayan Lepas have begun to accommodate construction works that may last up to 38 months.

    Public inspection of revised rail scheme
    Authorities have also opened a public inspection period for revised plans, including a proposed cross-sea link to Penang Sentral, which will strengthen connectivity between the island and mainland.


    3. Why the LRT Matters for the Property Market

    Infrastructure has always played a major role in shaping property values.

    Based on experiences in Kuala Lumpur, rail transit typically creates three types of property impact.

    1️⃣ Transit-Oriented Development (TOD)

    Properties located near LRT stations tend to see increased demand due to convenience and connectivity.

    Areas expected to benefit include:

    • Bayan Lepas
    • Sungai Nibong
    • Gelugor
    • Jelutong
    • Komtar / George Town

    These areas could evolve into future TOD zones, attracting both residential and commercial developments.


    2️⃣ Improved Accessibility

    Currently, travelling from Bayan Lepas to George Town during peak hours can take more than an hour.

    With the LRT:

    • Travel time could be significantly reduced
    • Workers in the Bayan Lepas industrial zone gain easier access to the city
    • Tourism and business mobility improve

    Better connectivity often leads to stronger rental demand.


    3️⃣ Long-Term Economic Growth

    The LRT is not just a transport project. It is also a strategic economic infrastructure designed to support:

    • Silicon Island development
    • the Bayan Lepas industrial hub
    • tourism in George Town
    • cross-strait connectivity with mainland Penang

    Large infrastructure projects tend to stimulate surrounding investments and commercial activity.


    4. A Strategic Perspective for Property Buyers

    However, buying property purely because it is near an LRT station is not enough.

    From an investment perspective, buyers should still analyse:

    • Rental demand around the station
    • Employment nodes nearby
    • Supply of new developments
    • Holding power during construction years

    The Penang LRT is expected to complete around 2031, meaning property investors must adopt a long-term view rather than short-term speculation.


    Final Thoughts

    The Penang LRT has been discussed for more than a decade. Now that construction has begun, the project is moving from concept to reality.

    For Penang, the LRT represents more than just a transport system — it is a structural shift in how the city grows and how people move.

    For property buyers and investors, the key question is no longer whether the LRT will happen.

    The real question is:

    Are you positioning your property decisions ahead of this infrastructure transformation?


    Written by:
    Miichael Yeoh
    Property Strategist | Developer Consultant | Investment & Mortgage


    References

    1. MRT Corp – Mutiara Line Project Information
    2. Bernama – Penang LRT construction update
    3. The Star / Penang infrastructure updates
    4. Malay Mail / Infrastructure reports on LRT cost and timeline
    5. Wikipedia – Mutiara Line LRT project overview
  • Think Like a Banker Before You Buy Property

    Think Like a Banker Before You Buy Property

    One thing I learned from working closely with banks is this:

    Banks are extremely careful before approving a property loan.

    They analyse risks, stress-test your finances, and study whether you can survive difficult situations.

    But here’s the irony.

    Many property buyers don’t analyse their purchase the same way.

    They look at the show unit.
    They listen to marketing promises.
    They follow what others are buying.

    But they rarely ask the same questions a banker would ask.

    If you want to invest in property wisely, start by thinking like a banker.

    Here are three things bankers always analyse.


    1️⃣ Debt Ratio – Are You Stretching Yourself Too Thin?

    Banks look closely at your Debt Service Ratio (DSR).

    This measures how much of your income is used to pay debts.

    Even if a bank approves your loan, you should still ask yourself:

    • What happens if interest rates increase?
    • What if my income drops temporarily?
    • Will I still feel comfortable servicing the loan?

    A property might look affordable today.

    But bankers always plan for tomorrow’s risks.


    2️⃣ Holding Power – Can You Hold Through Market Cycles?

    Property markets don’t always go up.

    There will be slow periods.

    Bankers evaluate whether a borrower has the financial strength to continue paying during tough times.

    Smart investors should ask:

    • Can I hold this property for 5–10 years if needed?
    • Do I have cash reserves?
    • What if the market takes longer to recover?

    Many investors fail not because they bought the wrong property…

    They fail because they cannot hold it long enough.


    3️⃣ Rental Sustainability – Can the Property Support Itself?

    Another banker mindset is income sustainability.

    Before buying, ask:

    • Is there real rental demand here?
    • Who are the potential tenants?
    • Can the rental help support the loan?

    A strong investment property should ideally generate rental income that supports part of the financing.

    This reduces pressure and improves long-term stability.


    Final Thought

    Successful property investors don’t buy emotionally.

    They evaluate property like a banker evaluating risk.

    Before your next purchase, ask yourself:

    Does this property pass the banker’s test?

    When you start thinking like a banker, you don’t just buy property.

    You build a stronger and safer property portfolio.


    Miichael Yeoh
    Property Strategist | Developer Consultant | Investment & Mortgage Expert
    Author of Think Like a Banker, Act Like a Player

  • The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?

    The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?

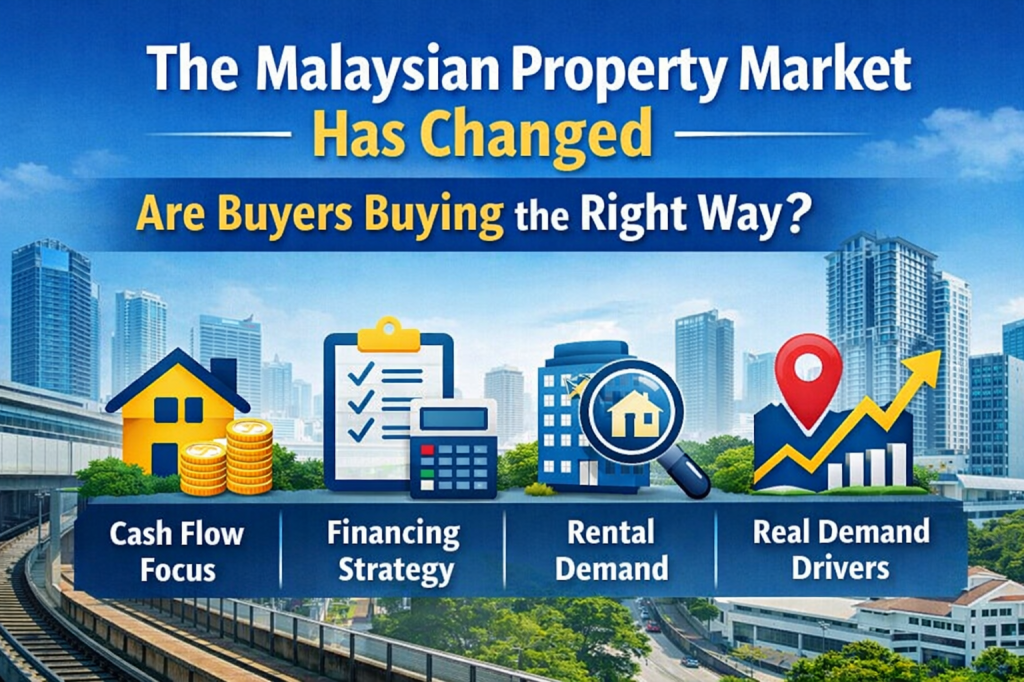
    The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?

    For many years, property investing in Malaysia followed a familiar formula.

    Buy a new launch, wait a few years, and hope the price goes up.

    This strategy worked reasonably well during earlier property cycles when prices were rising quickly, financing was easier, and supply was more limited. Many investors entered the market believing that capital appreciation alone would justify the purchase.

    But today, the Malaysian property market has entered a different phase.

    The question buyers should now ask is no longer “Will the price go up?”
    The more important question is “Can this property sustain itself financially?”


    The Shift From Speculation to Sustainability

    Over the past decade, the mindset of property buyers has gradually evolved.

    Today’s buyers are more cautious, more analytical, and more focused on cash flow and long-term holding power.

    Instead of relying purely on future price appreciation, investors are increasingly asking questions such as:

    • What is the rental demand in this area?
    • Can the rental cover most of the loan instalment?
    • What happens if interest rates increase?
    • Who is the actual tenant profile for this property?

    These questions reflect a more mature approach to property investing.

    The reality is simple: not every property will appreciate significantly in the short term. When appreciation slows, the ability of the property to generate rental income becomes far more important.


    Financing Strategy Now Matters More Than Ever

    Another major shift in the market is the growing importance of financing structure.

    Many buyers focus heavily on the purchase price but pay little attention to how the property is financed. Yet the financing strategy can determine whether an investment becomes manageable or financially stressful.

    Buyers today need to consider:

    • Loan margin and interest rates
    • Monthly instalment affordability
    • Holding power during market slowdowns
    • Overall debt exposure

    A well-structured loan can give investors time and flexibility, while poor financial planning can force them to sell prematurely.

    Thinking about financing before buying is no longer optional — it is essential.


    Rental Demand Is Becoming a Key Decision Factor

    One of the biggest mistakes many investors made in the past was buying properties without considering who would actually rent the unit.

    Today, buyers are beginning to look more closely at demand drivers such as:

    • Proximity to employment hubs
    • Accessibility and transportation infrastructure
    • Nearby universities or hospitals
    • Tourism demand and short-term rental potential

    In markets like Penang, Kuala Lumpur, and Johor Bahru, rental demand is increasingly shaping investment decisions.

    For example, areas with strong tourism activity or major infrastructure developments may offer better rental prospects compared to purely speculative locations.

    The key question investors should ask is:

    “Who is my tenant?”

    If there is no clear answer, the investment may not perform as expected.


    The Role of Infrastructure and Economic Drivers

    Another important factor influencing property performance today is real economic activity.

    Infrastructure projects, transportation connectivity, employment centres, and tourism growth can significantly impact both rental demand and long-term property value.

    For instance, upcoming transportation developments and urban revitalisation projects in cities such as Georgetown could change demand patterns in the coming years.

    However, infrastructure alone does not guarantee success. The surrounding ecosystem — population growth, business activity, and lifestyle demand — must also support the property market.


    Buying Property Today Requires a Different Mindset

    The Malaysian property market has not disappeared. But the way buyers approach property must evolve.

    Successful investors today tend to follow a more balanced approach:

    • Evaluate rental yield and cash flow
    • Structure financing carefully
    • Understand real demand drivers
    • Focus on long-term sustainability

    In other words, the focus has shifted from short-term speculation to long-term investment discipline.


    A Final Thought

    Property has always been a long-term asset class.

    But in today’s market environment, buying property requires more than just optimism about future price growth.

    It requires careful thinking, realistic financial planning, and a clear understanding of market demand.

    The Malaysian property market has changed.

    The real question is — have buyers changed with it?


    Miichael Yeoh
    Property Strategist | Developer Consultant | HRD Corp Trainer

    Miichael Yeoh has more than 28 years of experience spanning banking, mortgage advisory, property investment, and developer consultancy. He is also the author of Think Like a Banker, Act Like a Player, Property Investment BLT, and Buying Property Like A Pro.

  • What Is OPR in Malaysia and How Does It Affect Housing Loan Interest Rates?

    What Is OPR in Malaysia and How Does It Affect Housing Loan Interest Rates?

    By Miichael Yeoh

    As someone who has spent nearly three decades in banking, mortgage advisory and property strategy, one question I get repeatedly from investors and homebuyers is:

    “Why did my bank increase (or educe) my interest rate when I didn’t change anything?”

    The answer almost always traces back to one key number — the Overnight Policy Rate (OPR).

    Let’s break down how OPR is derived, who decides it, and how it directly affects your housing loan, business financing, and even fixed deposits.


    What Is OPR?

    Bank Negara Malaysia (BNM) uses the Overnight Policy Rate (OPR) as its main monetary policy tool.

    The OPR is the interest rate at which banks lend money to one another overnight. It serves as the benchmark rate that influences all other interest rates in the country.

    Think of it as the “master switch” of Malaysia’s financial system.


    How Is OPR Derived?

    OPR is not randomly adjusted. It is decided by BNM’s Monetary Policy Committee (MPC) based on several key economic indicators:

    1️⃣ Inflation (Price Stability)

    If inflation is rising too quickly, BNM may increase OPR to slow down spending and borrowing.
    If inflation is low or the economy is weak, BNM may reduce OPR to stimulate growth.

    2️⃣ Economic Growth (GDP)

    Strong economic growth may lead to higher OPR to prevent overheating.
    Weak GDP growth may lead to lower OPR to encourage borrowing and investment.

    3️⃣ Employment & Consumer Spending

    High unemployment? Lower OPR to boost activity.
    Strong consumer demand? Possibly tighten policy.

    4️⃣ Global Economic Conditions

    US Federal Reserve rates, global trade trends, currency strength, and geopolitical risks all influence Malaysia’s monetary decisions.

    5️⃣ Financial System Stability

    BNM ensures banks remain liquid and stable. OPR adjustments help manage systemic risk.

    In simple terms:

    OPR balances growth and inflation.


    How OPR Affects Banks’ Interest Rates

    When OPR changes, banks adjust their benchmark rates such as:

    • BR (Base Rate)
    • SBR (Standardised Base Rate)

    Most housing loans today are priced as:

    SBR + Spread (e.g., SBR + 1.5%)

    When OPR increases:

    • SBR increases
    • Monthly instalments increase
    • Loan affordability reduces

    When OPR decreases:

    • SBR decreases
    • Monthly instalments reduce
    • Borrowing becomes cheaper

    Example: How It Impacts a Housing Loan

    Let’s say:

    • Loan: RM500,000
    • Tenure: 35 years
    • Rate: SBR 3.00% + 1.50% = 4.50%

    If OPR increases by 0.25%:

    • SBR may rise to 3.25%
    • New rate becomes 4.75%
    • Monthly instalment increases

    Even a 0.25% increase can mean thousands of ringgit extra over the loan tenure.

    This is why property investors must monitor OPR closely.


    Impact on Different Groups

    🏠 Homeowners

    Higher OPR = higher instalments (if on floating rate).

    🏢 Property Investors

    Rental yield may be squeezed if instalments rise but rental cannot increase proportionally.

    💼 Businesses

    Cost of financing increases, affecting expansion decisions.

    💰 Savers

    Good news — Fixed deposit rates usually improve when OPR rises.


    Why OPR Matters in Property Strategy

    As a developer consultant and property strategist, I always advise clients:

    Don’t only calculate today’s instalment. Stress-test at +1% or +2%.

    Markets move in cycles. OPR will not stay low forever.

    Smart investors:

    • Lock in good spreads during low-rate environments
    • Structure debt efficiently
    • Maintain cash flow buffers

    Final Thoughts

    OPR is not just a technical banking term.

    It is the heartbeat of the financial system, influencing property prices, loan affordability, rental yields, and overall market sentiment.

    Understanding how it works allows you to:

    • Make better borrowing decisions
    • Time property acquisitions strategically
    • Structure financing intelligently

    If you are planning your next property move, always ask:

    “What is the interest rate cycle telling me?”

    Because in property investing,
    Timing and financing strategy often matter more than price.

  • Before You Buy Any Property, Run It Through This Simple Checklist

    Before You Buy Any Property, Run It Through This Simple Checklist

    Most property mistakes don’t happen after you buy.
    They happen before you sign.

    Over the years — working in banks, speaking on stages, and educating buyers and investors — I’ve noticed one consistent pattern:

    People buy property based on emotion, marketing, or price,
    instead of structure, numbers, and risk.

    Good property decisions are rarely accidental.
    They are the result of asking the right questions early.

    Let me show you the checklist I personally use — and teach — before anyone commits to a property purchase.


    1. Start With the Right Question (Not “Can I Buy?”)

    The wrong question is:

    “Can I get a loan?”

    The better question is:

    “Is this property right for me?”

    Before you look at projects, promotions, or discounts, be clear on your purpose:

    • Are you buying for own stay, rental income, or long-term growth?
    • Do you want monthly stability, future upside, or both?
    • How long are you prepared to hold this property?

    A good property for someone else can be a bad property for you.

    Clarity always comes before commitment.


    2. Understand Your Financial Comfort Zone

    Many buyers confuse approval with affordability.

    Just because you can commit, doesn’t mean you should.

    Before buying, be honest about:

    • Your monthly commitments after purchase
    • Your buffer if interest rates rise or income changes
    • Whether the property adds pressure or flexibility to your life

    A simple rule I often share:

    If a property causes stress from Day One, it’s already a bad decision.

    Property should support your long-term plan — not trap you in it.


    3. Protect Yourself Before You Celebrate

    Buying property is not just about price and location.
    It’s about rights, responsibilities, and clarity.

    Before you sign anything, make sure you understand:

    • What you truly own
    • Any conditions or restrictions attached to the property
    • Your obligations now and in the future
    • What happens if things don’t go according to plan

    Many buyers only realise what they signed after problems arise.
    By then, it’s often too late.

    Confidence comes from understanding — not assumptions.


    4. Look at the Real Cost, Not Just the Purchase Price

    The purchase price is only the beginning.

    You need to consider:

    • All upfront costs
    • Ongoing holding expenses
    • The impact of rental income on your overall finances
    • What you walk away with — not just what comes in

    A property that looks attractive on paper can disappoint once all costs are considered.

    Smart buyers focus on net outcome, not headline numbers.


    5. Evaluate the Property Like an Investor, Even If You’re Not One

    Even if you’re buying for own stay, think ahead.

    Ask yourself:

    • Who else would want this property in the future?
    • Is supply increasing in this area?
    • Are rental expectations realistic?
    • If you needed to sell, who would be your buyer?

    Hope is not a strategy.
    Every property should have a clear future story.


    6. A Simple Yes / No Filter I Personally Use

    Before I say yes to any property, I run through this:

    • ✅ Does this make sense financially over time?
    • ✅ Do I fully understand what I’m committing to?
    • ✅ Am I comfortable holding this through different market cycles?
    • ✅ Does this fit my life plan — not just today, but later?
    • ✅ Do I have flexibility if things change?

    If any answer is No, I pause.

    Property rewards patience far more than pressure.


    Final Thought: Learn First, Buy Second

    Property is not about buying fast or buying early.
    It’s about buying wisely.

    Too many people buy first — and learn later.
    The cost of that mistake can last decades.

    That’s why I believe education must always come before action.

    When you understand the decision fully, confidence follows naturally.

    And confident buyers make better property decisions — every time.

    From the desk of

    Miichael Yeoh

  • What the New EPF Policy Changes Mean for Your Retirement — and Your Financial Freedom in 2026

    What the New EPF Policy Changes Mean for Your Retirement — and Your Financial Freedom in 2026

    Happy New Year, friends! Starting today, a suite of important changes to the Employees Provident Fund (EPF) takes effect — and if you’re serious about building financial security and retirement freedom, you’ll want to know what these mean for you.

    As someone who talks to regular Malaysians about money, property and long-term planning every week, my goal is simple: help you turn policies into practical moves you can use to grow your wealth.

    Let’s break this down in a way that’s clear and actionable.


    🔹 1. Expanded Retirement Planning Tools (RIA Framework)

    EPF has introduced a Retirement Income Adequacy (RIA) Framework that gives benchmarks for how much you should aim to save by retirement:

    • Basic Savings: RM390,000
    • Adequate Savings: RM650,000
    • Enhanced Savings: RM1.3 million
      These are guidelines, not limits — but they are extremely useful targets to align your financial plan with real aspirations and lifestyle goals in retirement.

    🔹 2. More Flexibility for High-Savings Members

    If you’ve been disciplined and grown your EPF to more than RM1 million, the new rules give you more control over that excess:

    • From 2026, the threshold before you can withdraw excess savings will increase gradually — starting at RM1.1M this year, then RM1.2M and RM1.3M in future years.

    Why is this smart? Because the policy encourages strong retirement savings first before letting you unlock surplus funds — great if you are thinking about investment or business opportunities after securing your basics.


    🔹 3. New Opportunities for Gig and Informal Workers

    This is a huge deal for drivers, riders and the self-employed:
    EPF is launching i-Saraan Plus, an enhanced contribution scheme just for gig workers — with government matching of up to RM600 per year (capped at RM6,000 lifetime).

    This means you’re effectively getting a subsidy from the government just for saving — and that boosts your retirement-nest egg without extra burden.


    🔹 4. i-Suri Extended to Age 60

    For homemakers and spouses who contribute voluntarily under i-Suri, the eligibility age has been raised from 55 to 60.
    Plus, the 50% government matching incentive continues — meaning more government help to grow your savings pot.

    For many families, this is a practical way to build savings even without a traditional salary.


    🔹 5. Haj Withdrawal Limit Increased

    Good news if performing Hajj is in your 2026 plans:
    You can now withdraw up to RM10,000 from your EPF Hajj savings, up from RM3,000 previously — and with a simpler process.

    This change shows that EPF understands real life goals — not just retirement — and is adapting to help you plan important life milestones.


    🔹 6. Helpful Changes to Investment Eligibility

    The Members Investment Scheme (MIS) — which lets EPF contributors invest part of their savings — will now align with the basic RIA savings level.
    This means the minimum savings balance required for MIS participation increases gradually, ensuring that investment decisions don’t compromise your core retirement needs.


    What This Means for Your Money Strategy

    Here’s how you can think about these changes in your financial plan:

    ✅ Make EPF savings your foundation — the new RIA Framework gives goals to aim for.
    ✅ If you’re a gig worker or informal worker, take advantage of voluntary schemes like i-Saraan Plus — free government matching is like extra income.
    ✅ Plan ahead for retirement AND life goals — from Hajj to home deposits to future business capital.
    ✅ Keep investing mindfully — the MIS changes protect retirement security first, while letting disciplined savers grow their wealth.


    My Take: Retirement Isn’t Just an Age — It’s a Strategy

    Too many Malaysians think of EPF as just something you touch at 55. But with these changes, EPF is becoming a more powerful engine for lifelong financial planning — from your 20s all the way to retirement and beyond.

    If you’re building property portfolios, planning business income, or aiming for financial freedom, understanding how to use EPF strategically makes all the difference.

    Stay savvy, stay disciplined — and let’s make 2026 the year your financial future gets real traction.

    💬 Got questions about how to align these EPF changes with your property or investment goals? Ask me below!

    From the Desk of

    Miichael Yeoh

  • Property Refinancing in Malaysia

    Property Refinancing in Malaysia

    New Rules, Regulations & When Refinancing Actually Makes Sense

    Over the years, refinancing has been one of the most powerful financial tools for Malaysian homeowners and property investors. Used correctly, it can improve cash flow, reduce interest costs, or unlock equity for smarter investments.

    However, recent regulatory changes by Bank Negara Malaysia (BNM) mean refinancing is no longer as straightforward as before — especially when it involves cash-out.

    If you’re considering refinancing your property in 2025 or beyond, here’s what you must understand before making a move.


    What Is Property Refinancing?

    Property refinancing simply means replacing your existing home loan with a new loan, usually with another bank, based on your property’s current market value.

    Homeowners typically refinance to:

    • Get a lower interest rate
    • Reduce monthly instalments
    • Adjust loan tenure
    • Access cash from accumulated property equity
    • Consolidate high-interest debts

    The strategy itself hasn’t changed — the rules have.


    What’s New? Key Refinancing Rules You Must Know

    1. Cash-Out Refinancing Is Now More Restrictive

    One of the biggest changes affects cash-out refinancing.

    If you refinance and take extra cash for personal use (such as lifestyle spending, personal debts, or non-income-generating purposes), that portion may now be treated as personal financing, not a housing loan.

    👉 Key impact:

    • The cash-out portion may be capped at a maximum repayment tenure of 10 years
    • Monthly instalments will be significantly higher compared to spreading it over 30–35 years

    This is a major shift. In the past, many borrowers stretched cash-out amounts across the full home loan tenure, keeping instalments low but debt long.


    2. Stronger Affordability & DSR Checks

    Banks are now applying stricter Debt Service Ratio (DSR) assessments, especially for:

    • Multiple property owners
    • Refinancing with cash-out
    • Borrowers with existing personal loans or credit card balances

    Even if your property value has increased, approval is no longer guaranteed if your cash flow doesn’t support the new repayment structure.


    3. More Transparency on Loan Costs

    BNM has reinforced rules to ensure:

    • Clear disclosure of effective interest rates
    • Transparent breakdown of total repayment costs
    • Fair interest calculations based on reducing balance, not outdated methods

    This protects borrowers — but it also means banks are less flexible with “creative structuring”.


    Why Did Bank Negara Tighten Refinancing Rules?

    The objective is simple: reduce unhealthy household debt behaviour.

    Over the years, many Malaysians:

    • Used refinancing repeatedly for lifestyle spending
    • Rolled short-term debts into long-term housing loans
    • Focused on “low monthly instalment” instead of total debt impact

    The new rules encourage:

    • Responsible borrowing
    • Better financial planning
    • Using refinancing for productive purposes, not emotional decisions

    So… Why Should You Refinance a Property?

    Refinancing still makes sense — if done for the right reasons.

    1. To Lower Your Interest Rate

    If your current loan is:

    • On an old package
    • Above current market rates

    Refinancing can reduce:

    • Monthly instalments
    • Total interest paid over the loan tenure

    This is the cleanest and safest reason to refinance.


    2. To Improve Monthly Cash Flow

    Some homeowners refinance to:

    • Extend tenure
    • Reduce instalments
    • Create breathing space for cash flow

    This can be helpful during:

    • Business expansion
    • Income transition
    • Temporary financial tightening

    However, it must be done strategically, not emotionally.


    3. To Access Equity for Income-Producing Purposes

    This is where refinancing still shines — when the cash is used productively, such as:

    • Renovating a rental property
    • Funding another investment
    • Business expansion with clear returns

    Banks are generally more supportive when refinancing is tied to income generation, not consumption.


    4. Debt Consolidation (With Caution)

    Refinancing to clear:

    • Credit cards
    • Personal loans

    can reduce interest costs if discipline improves after refinancing.

    If spending habits remain unchanged, refinancing only delays the problem.


    5. To Restructure Your Property Portfolio

    For investors, refinancing can be used to:

    • Optimise loan structure across multiple properties
    • Release equity to rebalance portfolio risk
    • Improve overall holding power

    This requires proper planning — not just chasing approval.


    What You Should Consider Before Refinancing

    Before signing anything, ask yourself:

    ✔ Does refinancing truly save money after legal & valuation costs?
    ✔ Can I comfortably afford repayments if cash-out tenure is shorter?
    ✔ Am I refinancing for strategy — or short-term relief?
    ✔ Does this move strengthen my financial position 5–10 years from now?

    Refinancing is a tool. Used correctly, it builds wealth. Used wrongly, it creates silent financial stress.


    Final Thoughts from Miichael

    In today’s environment, refinancing is no longer about “how much cash can I take out”.

    The real question is:

    Does this refinancing decision improve my financial position — or just make today easier at tomorrow’s expense?

    With tighter rules in place, planning matters more than approval.

    If you’re unsure whether refinancing makes sense for your situation, get proper advice before committing. The cost of a wrong decision today can take years to undo.