Category: Property

  • Revisiting Malaysia’s Home Ownership Campaign: Mid-2025 Update

    Revisiting Malaysia’s Home Ownership Campaign: Mid-2025 Update

    As we come toward the mid of 2025, it’s timely to take a fresh look at the national Home Ownership Campaign (HOC) and related government initiatives aimed at making property ownership more accessible—especially for first-time buyers and middle-income earners.

    Launched originally as a short-term measure, the Home Ownership Campaign 2.0 has been extended until December 31, 2025, in recognition of ongoing housing affordability challenges faced by Malaysians. Alongside this, the Budget 2025 unveiled a series of new incentives designed to further ease the journey to homeownership.


    💡 What’s New in Mid-2025?

    1. Stamp Duty Exemption for First-Time Buyers

    One of the most attractive features of the HOC 2.0 is the 100% stamp duty exemption on properties priced at RM500,000 and below, specifically for first-time homeowners. This incentive significantly reduces the upfront cost of purchasing a home and encourages more young Malaysians to step into the property market.

    2. Housing Credit Guarantee Scheme (SJKP)
    To support those without fixed income documentation—such as gig workers, freelancers, or small business owners—the government continues to offer loan guarantees through SJKP. This allows banks to approve housing loans of up to RM500,000 even for applicants with non-traditional income streams.

    3. Step-Up Financing Scheme

    Also introduced under Budget 2025 is a new Step-Up Financing Scheme, which eases the repayment burden in the early years of a home loan. With government backing of RM5 billion, this scheme helps first-time buyers manage their finances while adjusting to homeownership.


    🧾 Tax Relief for First-Time Buyers

    From January 1, 2025, to December 31, 2027, buyers who sign a Sale and Purchase Agreement (SPA) can claim the following tax reliefs:

    • 🏠 Up to RM7,000/year for properties priced RM500,000 and below
    • 🏠 Up to RM5,000/year for properties priced between RM500,001 and RM750,000

    These tax incentives are designed to provide further savings for eligible homeowners over a 3-year period.


    🏗️ Affordable Housing Developments

    Budget 2025 also channels RM900 million toward affordable housing projects under the People’s Residency Program (PRR) and Rumah Mesra Rakyat (RMR). These programs aim to bridge the housing gap, particularly for B40 and M40 income groups, with strategic developments nationwide.

    In addition, special financial aid—up to RM90,000—is available for those building homes under schemes such as PPRT, including communities in Chinese new villages and fishing settlements.

    🔄 Rent-to-Own Scheme

    For those not ready to buy immediately, the Rent-to-Own (RTO) scheme allows applicants to rent a property for five years with the option to purchase it later. This offers a transitional pathway to homeownership while giving individuals time to strengthen their financial footing.


    ✅ Who’s Eligible?

    To enjoy the full benefits of these initiatives, applicants must typically meet the following conditions:

    • Must be Malaysian citizens aged 18 and above
    • Must be first-time homebuyers
    • Must purchase residential property priced within program thresholds
    • Some schemes may include income eligibility limits

    📊 Summary of Home Ownership Incentives (2025)

    IncentiveDetailsEligibility
    Stamp Duty Exemption100% exemption for properties ≤ RM500,000First-time buyers only
    Tax ReliefRM7,000/year (≤ RM500,000); RM5,000/year (RM500k–RM750k) for 3 yearsSPA signed between 2025–2027
    Housing Credit Guarantee (SJKP)Loan guarantee for properties ≤ RM500,000Buyers with irregular income
    Step-Up Financing SchemeReduced repayments for first 5 yearsFirst-time buyers
    Affordable Housing (PRR/RMR)RM900M allocated for low-income housing projectsB40 & M40 income groups
    Rent-to-Own (RTO) Scheme5-year rental with option to buyMiddle-income buyers

    📈 Potential Savings for a First-Time Homebuyer (Example Scenario)

    ComponentProperty Price: RM480,000Savings
    Stamp Duty (100% Exemption)Normally ~RM9,600RM9,600
    Tax Relief (RM7k/year x3)For 3 yearsRM21,000
    Lower Initial Loan Repaymentvia Step-Up Financing~RM15,000 over 5 years (est.)
    Total Potential Savings~RM45,600

    Note: Values are estimates and may vary by loan package and location.

    🏡 Final Thoughts

    Midway through 2025, Malaysia’s homeownership landscape remains favorable for aspiring buyers, thanks to proactive government support and long-term housing policies. Whether you’re looking to buy your first home, secure financing with flexible terms, or benefit from tax relief, now is an excellent time to take action.

    If you’re considering a property purchase this year, consult with certified property consultants or financial planners to understand how these incentives apply to your personal situation. With the right guidance, 2025 could be the year you unlock the door to your own home.

    From the Desk of

    Miichael Yeoh
  • Malaysia Property Market Sees 8.9% Decline in 1Q2025

    Malaysia Property Market Sees 8.9% Decline in 1Q2025

    Malaysia’s property market experienced a decline in transaction value in the first quarter of 2025 (1Q2025), with a drop of 8.9% to RM51.42 billion, compared to RM56.47 billion in the same period last year, according to the latest report from the National Property Information Centre (Napic).

    Transaction volume also decreased by 6.2% year-on-year, recording 97,772 transactions in 1Q2025, down from 104,194 transactions in 1Q2024, Napic stated in its Friday report.

    Despite the downturn, Valuation and Property Services Department director general Abdul Razak Yusak noted that the property market is expected to remain resilient, buoyed by growth in the construction sector and a rise in newly launched residential units.

    “Industry players and property developers should stay vigilant given the current market dynamics, global economic uncertainties, and evolving external factors,” he said.

    Residential Overhang and New Launches

    Napic reported a significant increase in new residential launches, with 12,498 units introduced in 1Q2025, more than double the 5,585 units launched in 1Q2024. However, the sales performance remained moderate, with a sales rate of 10.8%.

    The residential overhang rose slightly by 1.6% to 23,515 units valued at RM15 billion, a 7.7% increase in value compared to the same quarter last year. Nevertheless, on a quarterly basis, the overhang showed improvement, with volume and value declining by 2.9% and 9.0%, respectively.

    The serviced apartment sector recorded a 6.7% year-on-year reduction in overhang volume, totaling 18,246 units, while the value declined by 6.9% to RM14.61 billion. Abdul Razak noted that Johor Bahru’s serviced apartment market showed signs of recovery, with overhang units reducing by 5.6% in 1Q2025 compared to 4Q2024.

    Shopping complexes also saw a slight improvement in occupancy rates, rising to 79.0% from 78.8% in the previous quarter.

    Meanwhile, the Malaysian House Price Index (MHPI) for 1Q2025 stood at 225.3 points, with the average house price recorded at RM486,070, reflecting a modest annual growth rate of 0.9%.

    Impact on Property Market

    The decline in transaction value and volume in 1Q2025 may signal a period of caution for property investors. With a higher number of unsold units, developers might consider offering more incentives or adjusting pricing strategies to attract buyers. On the other hand, the rise in new launches indicates continued confidence in the market’s long-term potential. Investors are advised to monitor upcoming economic policies and market trends closely, as these factors could significantly influence buyer sentiment and market dynamics in the coming quarters.

    from the desk of

    Miichael Yeoh

    Latest Articles

    WEEKLY PROPERTY ROUNDUP

    Malaysia’s Budget 2027 puts first-home buyer support in focus, while infrastructure delivery in Sabah and fresh data from Australia and the UK offer important lessons for property buyers and investors.

    Is Now a Good Time to Buy Property in Malaysia ?

    This article emphasizes the importance of selecting the right property based on individual circumstances, rather than solely predicting market trends. It highlights Malaysia’s resilient property market , underscored by vital factors affecting demand.

  • Bank Negara Reduces SRR from 2% to 1%: What Does It Mean and How Will It Affect Us?

    Bank Negara Reduces SRR from 2% to 1%: What Does It Mean and How Will It Affect Us?

    Bank Negara Malaysia (BNM) has recently announced a reduction in the Statutory Reserve Requirement (SRR) ratio from 2% to 1%. This move is part of a broader strategy to ensure sufficient liquidity in the financial system, supporting economic growth amidst current economic challenges. But what exactly does this mean, and how will it impact individuals and businesses? Let’s break it down.

    Understanding SRR

    The Statutory Reserve Requirement (SRR) is the percentage of a bank’s total deposits that must be kept as reserves with Bank Negara Malaysia. Essentially, it is a tool used by the central bank to control the money supply in the economy. When the SRR is lowered, banks are required to hold less money in reserve, thereby freeing up more funds that can be lent out to businesses and individuals.

    Why Did BNM Reduce the SRR?

    The reduction in the SRR by 1% is expected to release approximately RM19 billion into the banking system, effective from 17 May 2025. This significant injection of liquidity aims to provide banks with more funds for lending and to stimulate economic activities during this period of economic uncertainty.

    The reduction in the SRR from 2% to 1% is aimed at increasing liquidity in the banking system. By allowing banks to keep less money in reserve, more funds become available for lending purposes. This is particularly crucial during periods of economic uncertainty when businesses and individuals may require more financial support. It also helps to reduce the cost of funds for banks, potentially leading to lower interest rates.

    How Does This Impact Us?

    1. More Accessible Loans: With more liquidity in the banking system, banks are more likely to offer loans to businesses and individuals. This can facilitate personal loans, home loans, and business financing, making it easier for borrowers to access funds.
    2. Lower Interest Rates: When banks have more funds to lend, competition among banks may increase, potentially leading to a reduction in lending rates. This is beneficial for borrowers seeking to refinance existing loans or take new loans.
    3. Impact on Savings and Fixed Deposits: On the flip side, while borrowers may benefit from lower interest rates, depositors may see a decrease in interest rates on their savings accounts and fixed deposits as banks adjust their rates to manage the increased liquidity.
    4. Business Expansion and Investment: With more funds available for lending, businesses may find it easier to obtain financing for expansion, investments, or operational costs. This can stimulate economic activity and potentially lead to job creation.

    Potential Risks and Considerations

    While the reduction in SRR can stimulate lending and economic growth, it is essential to consider potential risks. Increased lending could lead to higher household debt if borrowers overextend themselves. Additionally, excessive liquidity could contribute to asset bubbles if funds are channeled into speculative investments.

    Conclusion

    The reduction in SRR from 2% to 1% by Bank Negara Malaysia is a strategic move to increase liquidity and stimulate economic activity. While this creates more lending opportunities and potentially lower interest rates, it is crucial for borrowers to exercise caution and assess their financial capacity before taking on additional debt. Similarly, depositors should monitor interest rate trends to make informed decisions regarding their savings and investments.

    From The Desk of

    Miichael Yeoh

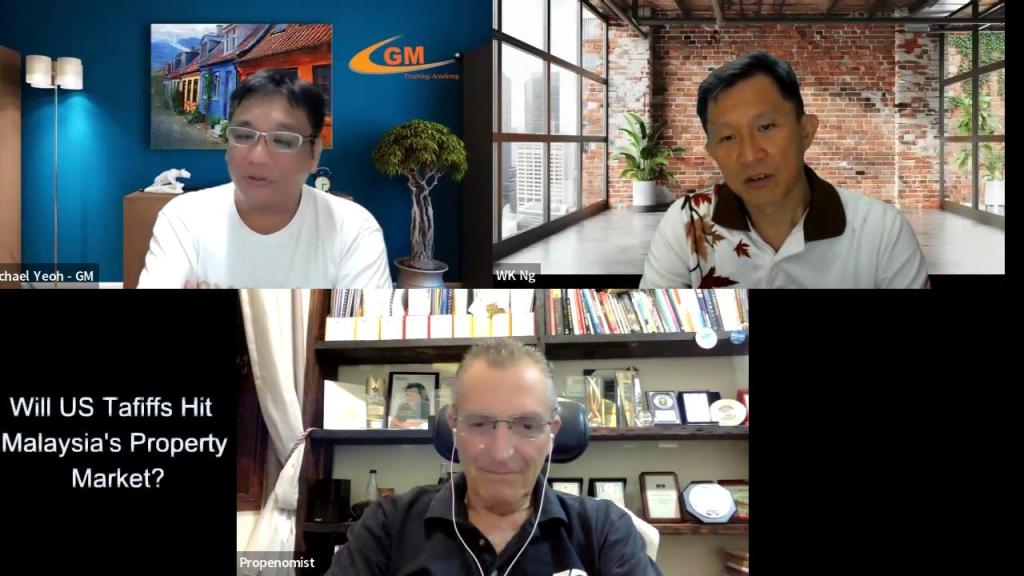
  • Will US Tariffs Hit Malaysia’s Market? Here’s What Experts Say

    Will US Tariffs Hit Malaysia’s Market? Here’s What Experts Say

    Over the past few weeks, the global economic community has been buzzing with concern: Will the U.S. impose new tariffs on Malaysia? And if so, what does it mean for our local economy — especially the property market?

    In response to growing public interest, I hosted a last-minute live Zoom forum on this critical issue, joined by three seasoned experts:

    🔹 Miichael Yeoh – CEO of GM Training Academy
    🔹 Dr. Daniele Gambero – economist and CEO of REI Group
    🔹 WK Ng – former Dell director turned full-time property investor

    View the recorded video for more information:

  • 109 Developers Blacklisted: Safeguards for Malaysian Homebuyers

    109 Developers Blacklisted: Safeguards for Malaysian Homebuyers

    The recent announcement by Housing and Local Government Minister Nga Kor Ming regarding the blacklisting of 109 housing developers is a significant step toward enhancing transparency and protecting homebuyers in Malaysia. By making this list publicly accessible on the ministry’s website, potential buyers can now verify the credibility of developers before making purchasing decisions.

    This initiative is part of broader efforts to address issues related to abandoned projects and fraudulent practices in the housing sector. The proposed amendments to the Housing Development (Control and Licensing) Act 1966 aim to impose stricter penalties on errant developers, including potential travel bans and substantial fines. ​

    While these measures demonstrate the government’s commitment to safeguarding homebuyers, it’s crucial for individuals to conduct thorough due diligence. Beyond consulting the blacklist, prospective buyers should assess developers’ track records, financial stability, and past project completions. Engaging with real estate professionals and seeking legal advice can further ensure informed decisions.​

    In summary, the public disclosure of blacklisted developers is a commendable move toward greater accountability in Malaysia’s housing industry. However, a collaborative approach involving stringent enforcement, legislative reforms, and proactive consumer awareness is essential to foster a trustworthy and resilient housing market.

    Read related article by The Star

    Homebuyers beware: 109 housing developers blacklisted, says Nga | The Star

    From the Desk of

    Miichael Yeoh

  • Unlock Wealth with Smart Mortgage Strategies

    Unlock Wealth with Smart Mortgage Strategies

    Did you know that 70% of Malaysians exhaust their EPF savings within just five years of retirement?

    This is a shocking reality, but it doesn’t have to be yours. Without proper financial and mortgage planning, many people find themselves struggling with rising living costs, increasing debt, and an uncertain future.

    Many people believe that simply saving money in a bank or relying on EPF will be enough to sustain them after retirement. However, with inflation, economic uncertainties, and an increasing cost of living, savings alone are not enough. To secure your financial future, you need a smart strategy that builds wealth while you sleep—and that’s where financial and mortgage planning come in.

    If you want to retire rich, not broke, it’s time to take control of your financial future!


    The Importance of Financial & Mortgage Planning

    1️⃣ Your Salary Alone is Not Enough

    Many Malaysians rely solely on their salaries as their primary source of income. However, depending only on salary comes with risks:
    ❌ Job insecurity – What happens if you lose your job or your business slows down?
    ❌ Limited earning potential – Salary increments may not keep up with rising expenses.
    ❌ No long-term wealth creation – Once you stop working, your income stops too.

    By understanding financial planning and leveraging mortgages, you can turn your income into wealth-building assets like property investments that generate passive income.

    ✅ Smart financial planning ensures that your money works for you, not the other way around.

    2️⃣ The Rising Cost of Living & Inflation

    The price of food, petrol, housing, and healthcare has been rising every year. What seems affordable today might be out of reach in the next five or ten years.

    📌 Example: 12 years ago, a property in Kuala Lumpur cost RM300,000. Today, the same property is worth RM600,000. If you had bought it back then, you would have gained RM300,000 in capital appreciation.

    Now imagine if you had invested in properties over the years—how much wealth would you have built?

    This is why financial planning and leveraging mortgages for property investment is crucial. The sooner you start, the better you can protect yourself from inflation and rising costs.

    3️⃣ Using Mortgages as a Wealth-Building Tool

    Many people see mortgages as a burden. But in reality, a mortgage is one of the most powerful financial tools you can use to build wealth.

    Here’s how:
    ✅ Leverage: With a mortgage, you can own high-value properties with only a fraction of the cost upfront.
    ✅ Passive Income: By renting out your properties, you create a steady income stream that covers loan repayments and generates profit.
    ✅ Capital Appreciation: Over time, property values tend to increase, helping you build long-term wealth.

    4️⃣ Securing Your Retirement with Smart Investments

    Many retirees face financial struggles because they failed to plan early. Without a steady stream of passive income, they depend entirely on their savings, which can deplete quickly.

    A well-structured mortgage plan can help you own multiple properties that generate rental income. This means that by the time you retire, you’ll have a steady cash flow to support your lifestyle—without relying on savings alone!


    How to Start Planning Your Financial Future Today

    🔹 Understand how mortgages work – Learn how to maximize loan approvals and use mortgages to grow your wealth.
    🔹 Invest in the right properties – Avoid costly mistakes and find properties that give high returns.
    🔹 Create multiple income streams – Secure your future with passive income from real estate investments.

    Final Thought: The Best Time to Invest is NOW!

    Many people delay financial planning, thinking they have plenty of time. But the truth is, the longer you wait, the harder it becomes to build wealth.

    💡 The best time to invest was yesterday. The second-best time is NOW!

    🚀 Don’t wait until it’s too late. Take charge of your financial future today!

    From the Desk of

    Miichael Yeoh

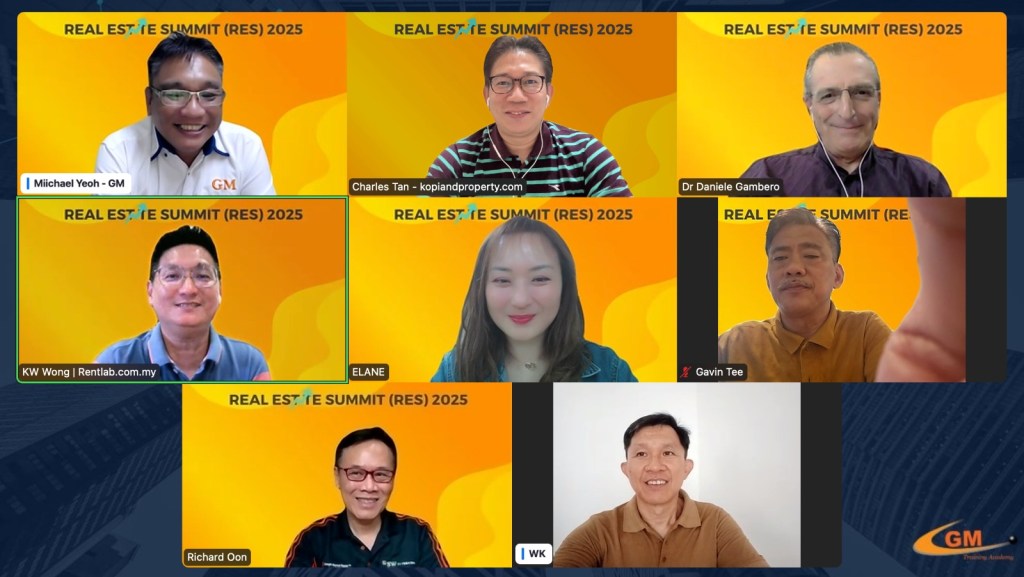
  • Real Estate Summit 2025: A Resounding Success!

    Real Estate Summit 2025: A Resounding Success!

    After two days of insightful discussions, expert sharing, and valuable networking, the Real Estate Summit 2025 (RES2025) has officially concluded! This event brought together some of the most renowned experts in real estate, finance, and investment, providing participants with actionable insights into the property market, financial planning, and smart investment strategies for 2025.

    We were honored to welcome participants from Malaysia, the Philippines, Singapore, the USA, Germany, and many other countries. The diversity of attendees enriched discussions and created a vibrant learning environment.

    A Heartfelt Thank You to Our Participants & Speakers

    First and foremost, we extend our deepest gratitude to all participants for attending RES2025. Your enthusiasm and eagerness to learn made this event truly impactful.

    A special appreciation to our distinguished speakers, whose expertise and insights played a crucial role in the success of RES2025:

    🔹 Dato’ Sri Gavin Tee – A real estate expert who shared his forecast on the 2025 property market and upcoming investment opportunities.
    🔹 Richard Oon – A taxation and financial planning specialist who guided participants on tax-saving strategies and financial management for property investors.
    🔹 Dr. Daniele Gambero – A respected market analyst who discussed real estate trends, mortgage challenges, and investment potential in 2025.
    🔹 Dr. Elane Goh – A finance and investment strategist who shared her insights on wealth creation through property investments and financial planning.
    🔹 WK Ng – A seasoned property investor who transitioned from the corporate world to full-time investing, providing real-life success strategies.
    🔹 KW Wong – A PropTech innovator and Secretary-General of the Malaysia PropTech Association, who spoke about the digital transformation of the rental market.
    🔹 Charles Tan – A leading property market analyst who offered valuable perspectives on Malaysia’s evolving real estate landscape.
    🔹 Miichael Yeoh – A mortgage and financial expert, who emphasized the importance of planning before making any major investment decisions.

    Your dedication and willingness to share your knowledge made RES2025 a game-changing event for all attendees.

    Special thanks to our co-organiser POLA Malaysia and our media partners Property Hunter and kopiandproperty.

    Key Takeaways from RES2025

    Throughout the two-day summit, participants gained powerful insights into the property industry, with topics covering:

    ✔️ Where to Invest in 2025 – Discovering high-potential investment hotspots.
    ✔️ Real Estate Market Trends – Adapting to economic shifts and evolving regulations.
    ✔️ Financial Planning & Taxation – Understanding tax incentives, financial structures, and mortgage strategies.
    ✔️ Mortgage Market 2025 – The latest developments in home financing and lending policies.
    ✔️ PropTech Innovations – The rise of digital property platforms and the impact on buying, selling, and renting.
    ✔️ Investment Strategies – How to build a profitable real estate portfolio.

    As Miichael Yeoh emphasized in his session: “Plan first before making your next move.” Strategic financial and investment planning is essential to achieving long-term success in real estate.

    The Power of Networking & Knowledge Sharing

    Beyond expert talks, RES2025 provided an invaluable opportunity for participants to connect with industry leaders, experienced investors, and like-minded individuals. The event fostered an environment where attendees could exchange ideas, gain exclusive insights, and build meaningful professional relationships.

    Looking Forward: What’s Next?

    The success of RES2025 reaffirms GM Training Academy’s commitment to empowering individuals with property education and financial literacy. We believe that informed decisions lead to successful investments, and we are dedicated to helping investors, homeowners, and professionals navigate the ever-changing real estate market.

    🚀 Upcoming Initiatives:

    ✅ More masterclasses and training workshops
    ✅ Exclusive webinars featuring top industry experts
    ✅ Property investment study tours
    ✅ Advanced financial and mortgage planning courses

    Stay Connected & Keep Learning

    📢 Missed RES2025? No worries! Stay connected with us for upcoming programs that will continue to provide valuable industry insights and expert guidance.

    Once again, THANK YOU to all our participants and speakers for making RES2025 a grand success! We look forward to seeing you at our next event.

  • Effects of OPR Changes on Borrowing and Savings

    Effects of OPR Changes on Borrowing and Savings

    As of January 2025, Bank Negara Malaysia (BNM) has maintained the Overnight Policy Rate (OPR) at 3.00%, a position held since May 2023.

    Understanding the Overnight Policy Rate (OPR)

    The OPR is the benchmark interest rate at which banks lend to one another overnight. Set by BNM, it serves as a primary monetary policy tool to regulate liquidity, control inflation, and sustain economic growth.

    Implications of an OPR Increase

    When BNM raises the OPR, it signals an intent to tighten monetary policy. The effects of such an increase include:

    Higher Borrowing Costs: Banks typically respond to an OPR hike by raising their base rates, leading to increased interest rates on loans and mortgages. This results in higher monthly repayments for borrowers.

    Enhanced Savings Returns: Conversely, depositors may benefit from higher interest earnings on savings and fixed deposits, encouraging increased savings.

    Controlled Inflation: Elevated borrowing costs can dampen consumer spending and business investments, helping to moderate demand-pull inflation.

    Currency Appreciation: Higher interest rates can attract foreign investment, potentially strengthening the Malaysian ringgit.

    Impact on Property Market: Increased interest rates may lead to higher mortgage costs, potentially cooling property demand and affecting market dynamics.

    Recent Economic Context

    In the third quarter of 2024, Malaysia’s economic growth slowed to 5.3% from 5.9% in the previous quarter, influenced by reduced oil and gas production. Despite this, robust household spending and increased investments provided support.

    BNM’s Monetary Policy Stance

    BNM has maintained the OPR at 3.00% since May 2023, citing positive economic growth and steady inflation. Economists anticipate that the central bank will keep the OPR unchanged until at least 2026, aligning with current economic assessments.

    Interest Rate Impact Example

    Let’s look at an example of how interest rates affect property loans. Assume you’re borrowing RM500,000 for 30 years:

    • Current Interest Rate (4.5%): Monthly repayment is approximately RM2,533.43.
    • If OPR Increases by 25 Basis Points (4.75%): Monthly repayment rises to around RM2,608.82.
    • Impact: This increase of RM75.39 per month adds up to RM27,140.40 over the loan’s term.

    This illustrates why understanding interest rates and their potential changes is crucial for planning your finances.

    Conclusion

    An increase in Malaysia’s OPR has multifaceted effects, influencing borrowing costs, savings returns, inflation, currency value, and the property market. Understanding these dynamics is crucial for individuals and businesses to make informed financial decisions in response to monetary policy changes.

    From the Desk of

    Miichael Yeoh
  • Avoid Costly Mistakes: 8 Reasons to Learn Before Investing in Real Estate

    Avoid Costly Mistakes: 8 Reasons to Learn Before Investing in Real Estate

    Purchasing or investing in property is one of the most significant financial decisions a person can make. While the prospect of owning a piece of real estate can be exciting, it’s also fraught with risks and complexities. Here are eight compelling reasons why educating yourself before taking the plunge is crucial:

    1. Understanding the Market

    The property market is dynamic, influenced by factors such as economic conditions, interest rates, and government policies. Without proper knowledge, you might buy at the wrong time or in the wrong location, potentially leading to financial losses. Education helps you grasp market cycles and trends, enabling informed decisions.

    2. Avoiding Costly Mistakes

    From overpaying for a property to falling victim to scams, the risks of making costly mistakes are high for uninformed buyers. Learning about property valuation, legal processes, and common pitfalls can save you from financial heartache.

    3. Maximizing Investment Returns

    Investing in property isn’t just about buying a house or apartment; it’s about choosing assets that will appreciate in value or generate steady rental income. Understanding key metrics such as ROI (Return on Investment) and cash flow can help you identify profitable opportunities.

    4. Navigating Legal and Financial Complexities

    Property transactions involve a maze of legal and financial considerations. From understanding loan agreements to navigating tax implications and zoning laws, there’s a lot to learn. A lack of knowledge could lead to delays or even legal troubles.

    5. Building Confidence

    The more you know, the more confident you’ll feel about your decisions. Knowledge reduces fear and uncertainty, empowering you to negotiate effectively, choose wisely, and stick to your long-term goals.

    6. Identifying Red Flags

    Not all properties are created equal. Structural issues, poor location, and hidden costs can turn a dream investment into a nightmare. Learning to conduct due diligence and property inspections ensures you spot potential problems early.

    7. Accessing Better Financing Options

    Understanding how mortgages and loans work can save you thousands of dollars over the life of your investment. Learning about different financing options and how to improve your creditworthiness can lead to better interest rates and loan terms.

    8. Planning for the Future

    Property investment is a long-term commitment. Learning helps you align your investment choices with your financial goals, whether it’s building wealth, securing passive income, or preparing for retirement. Knowledge enables strategic planning that benefits you in the long run.

    Conclusion

    Investing time and effort into learning before buying or investing in property is an investment in itself. It equips you with the tools and insights needed to make smart, informed decisions that align with your financial aspirations. Remember, in the world of property, knowledge isn’t just power; it’s profit.

  • Penang LRT Mutiara Line Depot Progress Report

    Penang LRT Mutiara Line Depot Progress Report

    Image Source: Buletin Mutiara

    The depot land for the Penang Light Rail Transit (LRT) Mutiara Line, located on Silicon Island, is progressing according to schedule and is expected to be completed and handed over to the project developer and asset owner, Mass Rapid Transit Corporation (MRT Corp), by the end of 2025. This key milestone is part of the ongoing development of the LRT system, which is set to improve public transportation in Penang.

    To date, 70 acres of the expansive 2,300-acre Silicon Island have been successfully reclaimed. Of this reclaimed land, six acres have been specifically allocated for the LRT depot, and reclamation work continues to progress smoothly, ensuring that the project will meet its handover deadline. Starting in 2025, the reclamation efforts will significantly ramp up, with an annual goal of reclaiming between 300 to 400 acres, which will further support the island’s development.

    Beyond the LRT depot, Silicon Island is being positioned as a central hub for economic growth in Penang, with plans to attract substantial investments, create thousands of jobs, and strengthen the region’s competitive edge on both a national and global scale. The development of Silicon Island is part of a broader strategy to transform Penang into a high-tech and innovation-driven economic powerhouse.

    Image Souce: Buletin Mutiara

    One of the most significant components of the island’s development is the Green Tech Park, which is being earmarked for industrial development. The first 100 acres of the park are expected to be ready for use by the first quarter of 2026. Shortly after, the construction of manufacturing facilities will begin, with operations expected to start by mid-2027. The Green Tech Park is expected to focus on high-value industries such as semiconductors, medical technology, and industrial automation, further boosting Penang’s role in the global economy.

    Silicon Island’s development is not just about infrastructure—it represents a comprehensive vision for sustainable growth. The project combines cutting-edge technology, environmental sustainability, and economic opportunity to create a balanced and forward-thinking approach to urban development. The island’s design integrates green technologies and sustainable practices that align with the state’s commitment to environmental responsibility.

    As the project continues to unfold, Silicon Island is set to redefine Penang’s future, turning it into a high-tech, innovation-driven economic hub that will leave a lasting impact on the region and contribute to Malaysia’s growth as a whole. Silicon Island is more than just a development project; it is a transformative initiative that will shape the future of Penang and play a key role in the country’s broader economic and technological advancements.

    From the Desk of

    Miichael Yeoh
  • Mike Tyson’s Resilience: Investment Lessons for Every Age

    Mike Tyson’s Resilience: Investment Lessons for Every Age

    Mike Tyson, the legendary former heavyweight boxing champion, shocked the world when he continues to maintain his fighting spirit at 58. His return wasn’t just about showcasing his physical prowess; it symbolized the unyielding human spirit and a refusal to let age define capabilities. Tyson’s story offers an invaluable lesson: it’s never too late to keep striving for your dreams, even after traditional retirement age.

    For property investors, Tyson’s journey serves as a powerful reminder that success often comes to those who refuse to give up, regardless of age or setbacks.

    Age is Just a Number in Life and Property Investment

    Many believe that real estate is a young person’s game. However, the truth is that property investment, much like Tyson’s boxing career, rewards perseverance, learning, and action—qualities that grow stronger with age and experience. Whether you’re in your 30s or your 60s, there’s always an opportunity to start or scale your property portfolio.

    The Beauty of Late Blooming

    Tyson isn’t alone in proving that success can come at any age. Many individuals have achieved extraordinary milestones well past the age society deems “prime.” These stories also align closely with property investment principles.

    1. Donald Trump

    Donald Trump built a significant part of his wealth through real estate. Even at 70, when he became the oldest first-term President of the United States in 2016, he demonstrated that reinvention is possible at any age. His story reminds property investors that it’s never too late to think big and make bold moves.

    2. Colonel Harland Sanders

    The founder of Kentucky Fried Chicken (KFC) started his fried chicken empire at 62 after facing multiple failures. Sanders’s persistence mirrors the journey of seasoned investors who’ve faced setbacks but ultimately built lasting wealth by taking calculated risks.

    3. Ray Kroc

    At 52, Ray Kroc transformed McDonald’s into a global powerhouse. Like in property investment, Kroc’s success required spotting a great opportunity and scaling it—a skill that improves with age and experience.

    4. Diana Nyad

    At 64, Diana Nyad became the first person to swim from Cuba to Florida without a shark cage. Her determination to push limits reflects the same mindset required in property investment: relentless focus and belief in achieving the impossible.

    Why Real Estate Works at Any Age

    1. Compounding Growth: Property investments tend to grow in value over time, making it ideal for those looking to build wealth regardless of when they start.
    2. Leverage Experience: With age comes wisdom—an invaluable asset in understanding market trends and avoiding costly mistakes.
    3. Passive Income: Rental properties offer a consistent income stream, making them perfect for retirement planning or financial independence at any stage of life.
    4. Opportunities for Reinvention: Like Tyson stepping back into the ring, seasoned individuals can pivot into property investment as a second career or passion project.

    Lessons from Tyson for Property Investors

    Tyson’s return to the ring, like the stories of Trump, Sanders, and others, underscores the importance of persistence and seizing opportunities. Property investment is no different. It requires:

    • Resilience: Markets fluctuate, but seasoned investors stay the course.
    • Action: It’s never too late to make that first purchase or expand your portfolio.
    • Vision: Investing in property, like boxing, requires foresight and planning to achieve long-term success.

    Making Your Comeback

    Whether you’re approaching retirement or already there, property investment offers one of the most reliable ways to achieve financial freedom. With proper guidance, anyone—regardless of age—can start building a portfolio that generates wealth for years to come.

    Just like Tyson’s return to the ring, starting or growing a property portfolio later in life is proof that you can achieve greatness in your “second act.” So, lace up your gloves, do your research, and take the first step—your property investment journey starts now!

  • Buying Property in Malaysia: A Foreigner’s Guide

    Buying Property in Malaysia: A Foreigner’s Guide

    Malaysia is an attractive destination for foreign property investors, offering a blend of vibrant cities, scenic landscapes, and a relatively easy property buying process. Whether you’re eyeing a luxury condo in Kuala Lumpur or a beachfront villa in Penang, understanding the essentials is crucial.

    Property prices have experienced significant growth, with the property index rising by 136% from Q1 2009 (92.4) to Q2 2024 (218.8), reflecting a clear upward trend in the market. This means that a property valued at RM1,000,000 in 2009 would now be worth RM2,360,000.

    Here are 7 key things every foreign buyer should know before purchasing property in Malaysia:

    1. Minimum Property Purchase Price

    To ensure housing affordability for locals, Malaysia has set minimum property prices for foreign buyers, which vary by state:

    • RM1,000,000: Terengganu, Pahang, Kuala Lumpur, Putrajaya, Kelantan, Perak, Labuan
    • RM2,000,000: Selangor (Zones 1 and 2), landed properties in international zones in Johor
    • RM600,000: High-rise properties in Sabah, Kedah (RM1,000,000 in Langkawi)
    • RM500,000: Sarawak and Perlis
    • Penang Island: RM1,800,000 for landed, RM800,000 for strata titles
    • Penang Mainland: RM750,000 for landed, RM400,000 for strata titles

    These thresholds determine the types of properties foreigners can buy in different regions.

    2. Stamp Duty Details

    Stamp duty is a tax applied to several documents in the property purchase process:

    • Sale and Purchase Agreement (SPA): A flat fee of RM10.
    • Instruments of Transfer: As of January 1, 2024, foreigners (except Malaysian permanent residents) will pay a flat 4% stamp duty on transfer documents such as the Memorandum of Transfer (MOT) or Deed of Assignment (DOA), replacing the previous tiered system.
    • Loan Agreement: A 0.5% stamp duty applies to the loan amount. For example, a RM500,000 loan incurs RM2,500 in stamp duty.

    3. Financing Options for Foreigners

    Foreigners can secure financing from Malaysian banks, but the terms differ from those for locals:

    • Down Payment: Typically, foreigners must pay 30% to 40% of the property’s value upfront.
    • Loan Tenure: Loan terms for foreigners are generally shorter, ranging from 15 to 25 years.
    • Interest Rates: Interest rates for foreign buyers are usually higher.

    Loan approvals are assessed on a case-by-case basis, so it’s advisable to consult a financial advisor who is familiar with the Malaysian property market to explore your best options.

    4. Real Property Gains Tax (RPGT)

    RPGT is a tax levied on profits from the sale of property:

    • 30% if sold within the first five years of ownership.
    • 10% if sold after five years.

    This tax is calculated on the profit after deducting the purchase price and related costs. As there are no exemptions for foreigners, it’s essential to account for RPGT in your investment plans.

    5. Legal Representation

    Hiring a knowledgeable lawyer is critical when buying property in Malaysia:

    • Legal Fees: Typically range from 0.5% to 1% of the property’s value.
    • Due Diligence: Your lawyer will ensure the property is free from legal complications and verify that the seller has the right to sell.
    • SPA Drafting: The lawyer will draft or review the Sale and Purchase Agreement (SPA) to protect your interests.

    A good lawyer helps prevent legal issues and ensures a smooth transaction.

    6. Foreign Ownership Restrictions

    Malaysia permits foreign ownership but with certain limitations:

    • Property Types: Foreigners cannot purchase low-cost housing, properties on Malay Reserve land, or certain agricultural land. However, they are permitted to buy luxury condos, high-rise units, and specific landed properties.
    • Quota Limits: Some developments cap foreign ownership at around 30% to maintain a balance between local and foreign buyers.

    Alternatively, you can consider joining Malaysia’s “Malaysia My Second Home” (MM2H) program, a government initiative that allows foreign nationals to live in Malaysia long-term. The program offers several tiers to accommodate different investment levels and lifestyle needs:

    1. MM2H Silver: Ideal for those seeking a five-year residency in Malaysia. This option requires a fixed deposit of USD $150,000 (RM705,000) and a mandatory property purchase of at least RM600,000. It’s a practical choice for retirees or individuals looking for short-to-mid-term residency.
    2. MM2H Gold: For those interested in a longer stay, the MM2H Gold offers a 15-year residency with a fixed deposit requirement of USD $500,000 (RM2.35 million) and a mandatory property purchase of at least RM1 million. This tier is suitable for investors who want more flexibility and a longer-term commitment in Malaysia.
    3. MM2H Platinum: The Platinum tier is designed for high-net-worth individuals seeking a 20-year visa. It requires a substantial fixed deposit of USD $1 million (RM4.7 million) and a minimum property purchase of RM2 million. This option provides the most extended residency and caters to those looking for significant investment opportunities and lifestyle benefits in Malaysia.

    The MM2H program not only provides an excellent gateway for foreign nationals to enjoy the lifestyle and economic opportunities Malaysia has to offer but also enables participants to explore property investments and business prospects in a stable and welcoming environment.

    7. Property Management for Non-Residents

    If you do not plan to live in Malaysia full-time, it’s advisable to hire a property management company:

    • Rental Management: These companies handle tenant placement, rent collection, and maintenance.
    • Upkeep: They ensure your property is well-maintained, preserving its value and condition—particularly useful if you own multiple properties or live abroad.

    Is Property Investment in Malaysia Worthwhile?

    As of 2025, Malaysia continues to offer excellent opportunities for property investment, especially through the Malaysia My Second Home (MM2H) program, which allows foreigners to live in the country on a long-term visa while investing in local real estate. With a growing economy and rising property demand, the Malaysian real estate market is positioned for stable capital growth and rental yields.

    Understanding these seven key points will help you make well-informed decisions and maximize your investment in Malaysia’s promising property market

    From the Desk of

    Miichael Yeoh