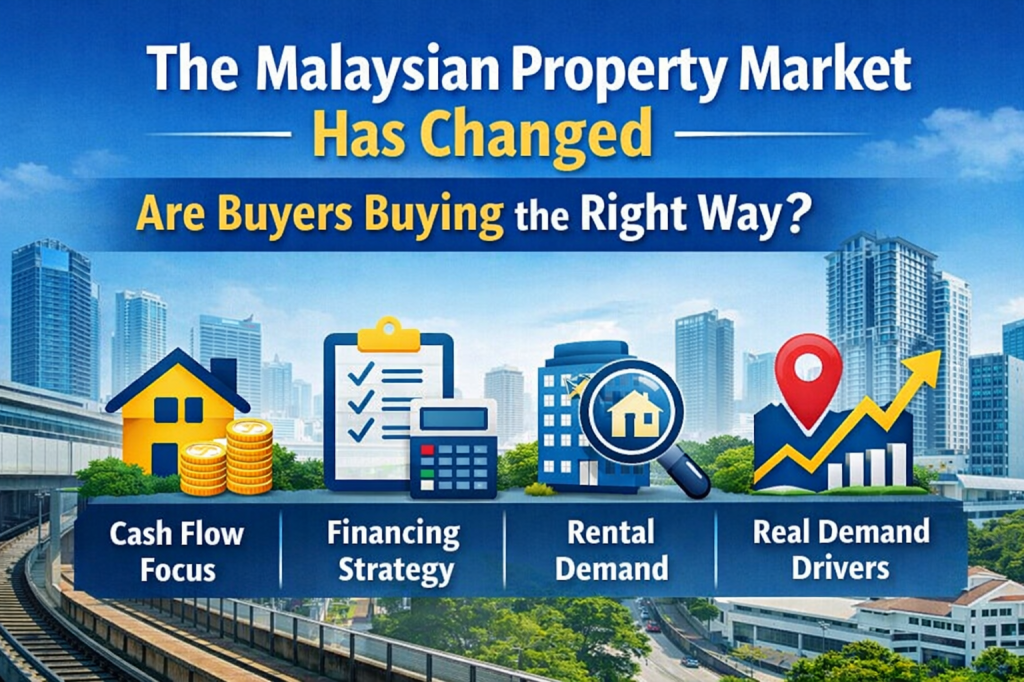
The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?
For many years, property investing in Malaysia followed a familiar formula.
Buy a new launch, wait a few years, and hope the price goes up.
This strategy worked reasonably well during earlier property cycles when prices were rising quickly, financing was easier, and supply was more limited. Many investors entered the market believing that capital appreciation alone would justify the purchase.
But today, the Malaysian property market has entered a different phase.
The question buyers should now ask is no longer “Will the price go up?” The more important question is “Can this property sustain itself financially?”
The Shift From Speculation to Sustainability
Over the past decade, the mindset of property buyers has gradually evolved.
Today’s buyers are more cautious, more analytical, and more focused on cash flow and long-term holding power.
Instead of relying purely on future price appreciation, investors are increasingly asking questions such as:
What is the rental demand in this area?
Can the rental cover most of the loan instalment?
What happens if interest rates increase?
Who is the actual tenant profile for this property?
These questions reflect a more mature approach to property investing.
The reality is simple: not every property will appreciate significantly in the short term. When appreciation slows, the ability of the property to generate rental income becomes far more important.
Financing Strategy Now Matters More Than Ever
Another major shift in the market is the growing importance of financing structure.
Many buyers focus heavily on the purchase price but pay little attention to how the property is financed. Yet the financing strategy can determine whether an investment becomes manageable or financially stressful.
Buyers today need to consider:
Loan margin and interest rates
Monthly instalment affordability
Holding power during market slowdowns
Overall debt exposure
A well-structured loan can give investors time and flexibility, while poor financial planning can force them to sell prematurely.
Thinking about financing before buying is no longer optional — it is essential.
Rental Demand Is Becoming a Key Decision Factor
One of the biggest mistakes many investors made in the past was buying properties without considering who would actually rent the unit.
Today, buyers are beginning to look more closely at demand drivers such as:
Proximity to employment hubs
Accessibility and transportation infrastructure
Nearby universities or hospitals
Tourism demand and short-term rental potential
In markets like Penang, Kuala Lumpur, and Johor Bahru, rental demand is increasingly shaping investment decisions.
For example, areas with strong tourism activity or major infrastructure developments may offer better rental prospects compared to purely speculative locations.
The key question investors should ask is:
“Who is my tenant?”
If there is no clear answer, the investment may not perform as expected.
The Role of Infrastructure and Economic Drivers
Another important factor influencing property performance today is real economic activity.
Infrastructure projects, transportation connectivity, employment centres, and tourism growth can significantly impact both rental demand and long-term property value.
For instance, upcoming transportation developments and urban revitalisation projects in cities such as Georgetown could change demand patterns in the coming years.
However, infrastructure alone does not guarantee success. The surrounding ecosystem — population growth, business activity, and lifestyle demand — must also support the property market.
Buying Property Today Requires a Different Mindset
The Malaysian property market has not disappeared. But the way buyers approach property must evolve.
Successful investors today tend to follow a more balanced approach:
Evaluate rental yield and cash flow
Structure financing carefully
Understand real demand drivers
Focus on long-term sustainability
In other words, the focus has shifted from short-term speculation to long-term investment discipline.
A Final Thought
Property has always been a long-term asset class.
But in today’s market environment, buying property requires more than just optimism about future price growth.
It requires careful thinking, realistic financial planning, and a clear understanding of market demand.
The Malaysian property market has changed.
The real question is — have buyers changed with it?
Miichael Yeoh has more than 28 years of experience spanning banking, mortgage advisory, property investment, and developer consultancy. He is also the author of Think Like a Banker, Act Like a Player, Property Investment BLT, and Buying Property Like A Pro.
Happy New Year, friends! Starting today, a suite of important changes to the Employees Provident Fund (EPF) takes effect — and if you’re serious about building financial security and retirement freedom, you’ll want to know what these mean for you.
As someone who talks to regular Malaysians about money, property and long-term planning every week, my goal is simple: help you turn policies into practical moves you can use to grow your wealth.
Let’s break this down in a way that’s clear and actionable.
EPF has introduced a Retirement Income Adequacy (RIA) Framework that gives benchmarks for how much you should aim to save by retirement:
Basic Savings: RM390,000
Adequate Savings: RM650,000
Enhanced Savings: RM1.3 million These are guidelines, not limits — but they are extremely useful targets to align your financial plan with real aspirations and lifestyle goals in retirement.
🔹 2. More Flexibility for High-Savings Members
If you’ve been disciplined and grown your EPF to more than RM1 million, the new rules give you more control over that excess:
From 2026, the threshold before you can withdraw excess savings will increase gradually — starting at RM1.1M this year, then RM1.2M and RM1.3M in future years.
Why is this smart? Because the policy encourages strong retirement savings first before letting you unlock surplus funds — great if you are thinking about investment or business opportunities after securing your basics.
🔹 3. New Opportunities for Gig and Informal Workers
This is a huge deal for drivers, riders and the self-employed: EPF is launching i-Saraan Plus, an enhanced contribution scheme just for gig workers — with government matching of up to RM600 per year (capped at RM6,000 lifetime).
This means you’re effectively getting a subsidy from the government just for saving — and that boosts your retirement-nest egg without extra burden.
🔹 4. i-Suri Extended to Age 60
For homemakers and spouses who contribute voluntarily under i-Suri, the eligibility age has been raised from 55 to 60. Plus, the 50% government matching incentive continues — meaning more government help to grow your savings pot.
For many families, this is a practical way to build savings even without a traditional salary.
🔹 5. Haj Withdrawal Limit Increased
Good news if performing Hajj is in your 2026 plans: You can now withdraw up to RM10,000 from your EPF Hajj savings, up from RM3,000 previously — and with a simpler process.
This change shows that EPF understands real life goals — not just retirement — and is adapting to help you plan important life milestones.
🔹 6. Helpful Changes to Investment Eligibility
The Members Investment Scheme (MIS) — which lets EPF contributors invest part of their savings — will now align with the basic RIA savings level. This means the minimum savings balance required for MIS participation increases gradually, ensuring that investment decisions don’t compromise your core retirement needs.
What This Means for Your Money Strategy
Here’s how you can think about these changes in your financial plan:
✅ Make EPF savings your foundation — the new RIA Framework gives goals to aim for. ✅ If you’re a gig worker or informal worker, take advantage of voluntary schemes like i-Saraan Plus — free government matching is like extra income. ✅ Plan ahead for retirement AND life goals — from Hajj to home deposits to future business capital. ✅ Keep investing mindfully — the MIS changes protect retirement security first, while letting disciplined savers grow their wealth.
My Take: Retirement Isn’t Just an Age — It’s a Strategy
Too many Malaysians think of EPF as just something you touch at 55. But with these changes, EPF is becoming a more powerful engine for lifelong financial planning — from your 20s all the way to retirement and beyond.
If you’re building property portfolios, planning business income, or aiming for financial freedom, understanding how to use EPF strategically makes all the difference.
Stay savvy, stay disciplined — and let’s make 2026 the year your financial future gets real traction.
💬 Got questions about how to align these EPF changes with your property or investment goals? Ask me below!
LHDN has officially released the 2025 Income Tax Relief List, and this is one update every Malaysian taxpayer should pay attention to — especially employees, business owners, and property investors.
Why? Because tax reliefs are legal ways to reduce your tax payable, yet many Malaysians either under-claim or miss them entirely due to poor planning or last-minute filing.
Let’s break down what this means and how you can optimise your tax position before the year ends.
What Is the LHDN Tax Relief List?
The LHDN Tax Relief List outlines approved expenses that taxpayers can deduct from their chargeable income when filing their annual income tax return.
Simply put: 👉 The more legitimate reliefs you claim, the less tax you pay — legally.
This list is updated periodically to reflect:
Rising cost of living
Education and healthcare needs
Retirement and family responsibilities
Digital and lifestyle expenses
Key Tax Reliefs Malaysians Can Claim in 2025
Below are some of the most commonly used — yet often under-claimed — tax reliefs for YA 2025.
1. Individual & Dependent Relief
Individual relief: RM9,000
Spouse (no income): RM4,000
Child relief: up to RM8,000 per child (higher for education level)
👉 Ensure your spouse and children details are properly declared.
2. Lifestyle Expenses (Up to RM2,500)
This remains one of the most popular reliefs, covering:
Books, journals, magazines
Sports equipment
Computer, smartphone, tablet
Internet subscription
⚠ Keep receipts — LHDN may request proof.
3. Medical Expenses (Self, Spouse & Parents)
You can claim medical expenses for:
Serious diseases
Medical check-ups
Dental treatment
Special needs and disabilities
Claims can go up to RM8,000, depending on category.
This is especially relevant for professionals and business owners upgrading their skills.
6. Housing-Related Reliefs (If Applicable)
Depending on eligibility:
Housing loan interest relief (subject to conditions)
First-time homebuyer incentives (if applicable)
⚠ These are often misunderstood — get proper advice before claiming.
Common Mistakes Taxpayers Make
From my experience, many taxpayers:
Rush to file without reviewing reliefs
Lose receipts and documentation
Assume certain expenses are “not claimable”
Follow advice from unverified online sources
Claim incorrectly and risk penalties later
Remember: ❌ Under-claiming = paying more tax than necessary ❌ Wrong claiming = penalties and audit risk
What You Should Do Before Year End
Here’s a simple checklist:
✔ Review the 2025 relief list early ✔ Plan major expenses before 31 December ✔ Organise receipts digitally ✔ Review EPF, insurance, and PRS contributions ✔ Seek advice if you have rental or business income
Tax planning is not done in April — it’s done before December ends.
Final Thoughts from Miichael
Tax reliefs are not loopholes — they are government-approved incentives meant to ease financial burden.
Those who benefit most are not the highest earners — but those who plan early and claim correctly.
If you’re unsure what you can claim, especially as a property investor, freelancer, or business owner, get clarity before filing.
The Malaysian property market has been through a lot in the last few years — pandemic, inflation, rising construction costs, slow wage growth, and changing buyer behaviour. But as we step into 2025, one thing is clear:
Property is still moving… but the market is no longer the same. Buyers are more cautious, banks are more selective, and affordability remains a major issue.
Here’s my take on what’s really happening in the residential property and mortgage landscape, and what you should pay attention to — especially if you’re planning to buy, invest, or restructure your loans.
📈 Long-Term Price Trend: Property Still Moves Up
Whether the market is “good” or “bad”, one fact remains consistent:
Property prices in Malaysia have been rising steadily for the last 20+ years.
Urban areas like Klang Valley, Penang and Johor consistently show appreciation because of:
population growth
job concentration
infrastructure development
scarcity of prime land
But here’s the catch: House prices have risen much faster than income, making affordability the No.1 challenge for Malaysians today.
This explains why many young buyers are stuck deciding between renting longer… or compromising on location and size.
🏘️ What’s Happening in the Market Now?
1. Transaction volume is rising — but buyers are choosy
2024 recorded strong growth in overall property transactions, and 2025 is projected to see single-digit positive growth. People are buying — but not blindly.
Buyers today compare:
price per sq ft
rental potential
exit value
access to MRT / LRT
developer reputation
Gone are the days when anything “new launch” can sell out. Today, value matters more than hype.
💰 Mortgage & Financing Trend: Here’s the Real Story
The biggest shift recently is OPR dropping to 2.75%, making borrowing cheaper.
This directly means:
Lower monthly instalments
Higher loan eligibility
Better cashflow for investors
But with great news comes reality… Banks are approving loans more carefully than ever.
Your CCRIS, CTOS, commitments and even gig-income consistency matter. If your financial health is not clean, even a low OPR won’t help you.
For many Malaysians, the challenge isn’t interest rate — it’s getting the loan approved.
🧱 Supply vs Demand: The Affordable Gap
You’re hearing this everywhere:
“So many houses unsold!” —but at the same time— “I can’t find any home I can afford!”
Why? Because the overhang is mainly:
too expensive for the mass market
too big (1,000 sq ft and above)
wrong location
This mismatch will continue unless developers pivot more aggressively into the mid-market segment.
🧭 What Buyers & Investors Should Look At Now
✔️ If you’re a first-time buyer
This is a golden window. Low OPR + many choices + developers offering incentives = value for money.
Look for:
good location > big size
future MRT/LRT corridors
reputable developers
high rental demand areas
✔️ If you’re an investor
Capital gain will still happen — but don’t expect overnight appreciation. Focus on:
rental yield
undervalued areas
distress or motivated sellers
T.O.P. projects with ready tenants
The smart investors in 2025 are not speculating. They’re buying below market value, or in growth corridors, or early in new infrastructure zones.
✔️ If you own multiple properties with loans
This is the best time to:
refinance
consolidate debts
reset your cashflow
restructure your portfolio
A small adjustment in interest rate can save thousands per year.
🧩 Conclusion: The Market Isn’t Booming, But It’s Moving
Malaysia’s residential market today is stable, resilient, and buyer-driven. We’re not in a bubble. We’re not in a crash.
We’re in a value-driven market, where the winners are: ✔️ informed buyers ✔️ strategic investors ✔️ those who manage their loans wisely
If you understand the trends — and you know how to analyse value correctly — 2025-2026 can be a very profitable year for you.
Tourism in Malaysia is bouncing back — and it’s not just recovering, it’s growing stronger than before. As we move closer to Visit Malaysia Year 2026 (VM2026), the numbers are looking solid, and the opportunities are exciting for those in travel, hospitality, and even property.
🇲🇾 The Big Picture
According to the Department of Statistics, domestic tourism in late 2024 hit 66.8 million trips, with Malaysians spending RM29 billion — that’s a 21% jump from the year before.
On the international front, Malaysia welcomed 12.9 million foreign visitors in just the first half of 2025. The sector is once again one of the country’s strongest pillars for growth — good news for business owners, developers, and local communities alike.
🌍 Top 5 Countries Visiting Malaysia (2024 Figures)
Rank
Country
Visitors
🥇 1
Singapore
9.10 million
🥈 2
Indonesia
3.65 million
🥉 3
China
3.29 million
4
Thailand
1.64 million
5
Brunei
1.14 million
(Source: The Star, Feb 2025)
In total, 25.02 million international tourists came to Malaysia in 2024 — up 24.2% from 2023 — generating RM106 billion in receipts.
No surprise that Singapore tops the list with easy land access and frequent travel. But what’s interesting is how China has made a strong comeback — Penang and KL are seeing a sharp rise in Chinese arrivals, especially after new flight routes were launched.
Indonesia remains one of our most loyal markets, with over 590 direct flights weekly between the two countries. And though Brunei and Thailand are smaller contributors, their proximity keeps border traffic vibrant, especially to East Malaysia.
✈️ What’s Driving Malaysia’s Tourism Growth
1️⃣ Better Connectivity
Penang alone recorded a 118% increase in Chinese arrivals early this year, thanks to more direct flights. Malaysia is also targeting 4.3 million Indonesian tourists in 2025 — and building new connections with Central Asia and the Middle East to diversify source markets.
2️⃣ Diversifying Tourism Beyond Beaches
Malaysia is moving beyond the usual “sun and sea” image. There’s now a stronger push for:
Medical tourism (especially Penang and KL)
Eco and community-based tourism (Sabah’s model brought in RM7 million in 2024 alone)
Cultural and food tourism (our nasi lemak and roti canai breakfast culture even got UNESCO recognition!)
3️⃣ Strong Branding and Recognition
Tourism Malaysia recently won the Asia Best Choice Tourism Organisation Award 2025, and Kuala Lumpur hosted over 600 international tourism buyers at the Global Tourism Meet 2025 — a big step toward positioning Malaysia as a MICE and event hub in ASEAN.
⚠️ A Few Challenges Ahead
While the outlook is bright, there are some issues to watch:
Rising hotel licence fees in places like Sabah could affect local operators.
Infrastructure and service quality need to keep up with rising tourist numbers.
Over-tourism management in hotspots like Penang and Langkawi is key to ensuring long-term sustainability.
💡 Why This Matters
For investors, this is a strong signal — hospitality, resort development, and even short-stay rentals are seeing renewed demand.
For local communities, tourism is becoming a source of empowerment, especially through rural and community-based tourism programs.
And for marketers, understanding the top five markets — Singapore, Indonesia, China, Thailand, and Brunei — is critical. Tailoring your messaging to their preferences, languages, and travel habits can make a huge difference.
🚀 What’s Next – Towards 2026
The upcoming Visit Malaysia Year 2026 aims to attract over 27 million visitors and generate RM120 billion in receipts. We can expect more funding in Budget 2026 for tourism infrastructure, digital promotion, and sustainability initiatives.
What’s clear is that travellers today want meaningful, authentic experiences — not just sightseeing. Malaysia, with its mix of culture, nature, and warm hospitality, fits that demand perfectly.
🏝️ My Take
Tourism Malaysia is back on the map — stronger, smarter, and more diverse. We’re seeing a solid mix of local and international growth, and if the country keeps focusing on value-driven, sustainable travel, Malaysia could easily become one of ASEAN’s top tourism powerhouses again by 2026.
The opportunity is right here — for investors, entrepreneurs, and communities to ride this new tourism wave together.
The Malaysian Budget 2026 was tabled yesterday by Prime Minister and Finance Minister Dato’ Seri Anwar Ibrahim, themed “Memacu Ekonomi MADANI: Memperkasa Rakyat.”
With a total allocation of RM470 billion, this budget continues the government’s commitment to building a fair and inclusive economy — with property and housing once again taking center stage.
Here’s my summary and insight on what Budget 2026 means for property buyers, developers, and investors.
🏡 1. Stamp Duty Exemption Extended for First-Time Buyers
Good news — the full stamp duty exemption on both the instrument of transfer and loan agreement for first-time buyers remains in place until 31 December 2027.
This applies to residential properties priced up to RM 500,000.
👉 What this means: If you’re planning to buy your first home, your upfront costs remain much lower. For many young Malaysians, this can be the difference between “maybe later” and “buy now.”
The Housing Credit Guarantee Scheme (SJKP) is being expanded from RM 10 billion to RM 20 billion, expected to help over 80,000 first-time buyers — including self-employed, gig workers, and informal earners.
👉 What this means: Loan approvals should become easier. This is crucial for those who may not have formal payslips but have consistent income — a growing segment of today’s workforce.
🌍 3. Higher Stamp Duty for Foreign Buyers
To cool speculative buying, stamp duty for non-citizens and foreign companies buying residential properties will rise from 4% to 8%.
Permanent residents (PRs) are not affected.
👉 What this means: Foreign investors will likely focus only on premium areas like KLCC, Mont Kiara, and Penang island. For locals, this could mean less competition — and potentially better entry prices.
🏢 4. Tax Deduction for Converting Commercial Buildings into Homes
A forward-thinking move — developers who convert old commercial buildings into residential use can now claim a 10% tax deduction (up to RM 10 million) on eligible renovation costs.
👉 What this means: Expect more adaptive reuse projects — turning old offices or malls into apartments or co-living units. This could help rejuvenate urban centers while reducing idle property stock.
🏠 5. Support for Rent-to-Own (RTO) and Build-Then-Sell (BTS) Schemes
Banks are encouraged to support RTO and BTS housing models to make ownership easier and reduce project abandonment.
👉 What this means: More flexibility for buyers who can’t yet afford a traditional down payment, and stronger assurance that projects are completed before full payment.
👨💼 6. Higher LPPSA Loan Limit for Civil Servants
The Public Sector Home Financing Board (LPPSA) limit will increase to RM 1 million in 2026.
👉 What this means: Civil servants can now afford better homes in urban areas without needing multiple loans.
🧱 7. RM 672 Million for Affordable Housing and Repairs
The government is allocating RM 672 million for:
Affordable homes (Residensi Rakyat, Rumah Mesra Rakyat)
Refurbishing old or dilapidated houses
Maintenance for low- and medium-cost flats (e.g. lift replacements)
👉 What this means: Positive for social stability and overall living quality. Also good news for contractors and local developers involved in affordable housing.
⚙️ 8. Construction and Tax Updates
SST on construction services will apply for new contracts from 1 Jan 2026.
Carbon tax will begin in stages, affecting material costs (cement, steel).
These may slightly raise overall building costs — developers should factor this into pricing.
🔎 My Insights: What to Watch in 2026
Affordable and Mid-Range Housing Remains the government’s priority. Buyers in this segment have strong support — expect steady demand.
Conversion Projects = Hidden Opportunity Old commercial spaces could become the next hot residential spots. Developers who act early may gain an edge.
Foreign Demand Softens, Local Focus Strengthens With higher duties, foreign demand may dip — but this creates more room for local owner-occupiers and long-term investors.
Construction Cost Pressure SST and carbon-related costs might raise project expenses by 3–5%. Efficient developers with strong cash flow will manage better.
Financing Still Key Even with incentives, loan approval remains the biggest hurdle. Buyers should prepare documentation properly (income proof, CCRIS record, existing commitments).
📈 Final Thoughts
Budget 2026 shows that Malaysia is moving toward a more sustainable and inclusive housing market — one that balances affordability with innovation.
For homebuyers, it’s a window of opportunity to act while incentives are strong. For investors, it’s time to look beyond traditional launches and explore conversion, rental, and co-living strategies. And for developers, the message is clear — adapt fast, innovate smart.
The property market in 2026 will favor those who understand trends early and act strategically.
Malaysian bank lending (especially for property purchases) is currently shaped by several key monetary, regulatory, and market-demand factors. Rates have been easing somewhat, but approval conditions remain cautious. Below are the latest numbers and trends.
Current Figures & Trends
Overnight Policy Rate (OPR) & Reference Rates
In July 2025, Bank Negara Malaysia (BNM) cut the OPR from 3.00% to 2.75% – the first cut in five years.
Major banks have adjusted their Standardised Base Rate (SBR) to 2.75% per annum following the OPR cut.
Base Rate (BR) has also been adjusted (for many banks) in line with this, though BR tends to be higher than SBR. For example, Alliance Bank’s BR is about 3.57%.
Base Lending Rate / Base Financing Rate (BLR/BFR)
The BLR or BFR (for Islamic financings) for many banks remains in the ~6.35% to ~6.65% range. For example, Maybank’s BLR is 6.40%, Hong Leong Bank’s is ~6.64%, etc. baserate.my+3Maybank2u+3NewPages+3
Effective Housing Loan Rates
While the base/reference rates give a starting point, effective lending rates (what borrowers actually pay) tend to be higher because banks add a margin/spread depending on risk, loan amount, tenure, etc.
Recent reports suggest effective rates for housing loans are in many cases 4.15% to 5.7% p.a. depending on bank, borrower profile, loan value, promotion, etc. Property Genie
Loan Approval & Volume
There was a 25.7% month-on-month increase in approvals of housing-loan applications in July 2025 after a slump in June. Focus Malaysia – Business & Beyond
The approval ratio (i.e. approved vs applied) in July 2025 was about 44.8%, up from ~42.6% in June 2025. Focus Malaysia – Business & Beyond
On a year-on-year basis, total approved loan volume declined by ~5.1% for that month; cumulatively over the first 7 months of 2025, approved property loans were ~RM 161.4 billion, about -1.5% relative to same period in previous year. Focus Malaysia – Business & Beyond
Outlook
With lower OPR and more competitive base/reference rates, there is optimism that loan approvals (both volume and ratio) may improve in the remaining months of 2025. Government’s likely to include incentives in Budget 2026 to support first-time buyers, low-to-middle income groups. Focus Malaysia – Business & Beyond
Steps Borrowers Can Take to Increase Chances of Loan Approval
Given the current environment, borrowers can do several things to strengthen their applications and improve likelihood of approval. Here are practical steps, both before and during application.
Step
What to Do
Why It Helps
1. Check & Clean Up Your Credit History
Obtain your credit report (e.g. through CTOS, CCRIS, Experian) ahead of time. Ensure there are no outstanding defaults, ensure credit card/HP payments are on time.
Banks check creditworthiness; a clean credit history reduces risk and may allow you to access better rates.
2. Assess Debt Service Ratio (DSR) / Total Commitments
Know your monthly obligations: other loans, credit cards, etc. Make sure your net income minus all obligations leaves enough room for loan instalments. Try to reduce existing liabilities if possible.
Banks often reject or charge higher margins if your debts relative to income are too high. Lower commitments improves affordability assessment.
3. Have Stable & Adequate Income
Demonstrate consistent employment or business income; have documentation (pay slips, tax returns, EPF contributions). If self-employed or commission-based, provide past 2-3 years’ income statements, audited if possible.
Stability & predictability of income give banks confidence in your ability to repay.
4. Make Reasonable Down Payment / Equity
The more you put down (lower loan-to-value ratio), the less risk for the bank. If you’re first-time buyer programs exist (often requiring only 10% payment), check eligibility, but be aware these may still have stricter conditions.
Less loan amount relative to property value helps bank exposure and reduces margin required.
5. Choose Appropriate Loan Tenure
Longer tenure reduces monthly instalments but increases total interest paid; very long tenure may raise risk from bank’s perspective (future rate changes, income changes). Balance payroll constraints with ability to service.
A manageable monthly repayment improves approval chances; less risk of default.
6. Prepare All Supporting Documents Properly
Have ready: identity documents, employment letters, income proof, EPF statements, tax returns (if applicable), bank statements, any other asset documentation. Ensure documents are current.
It speeds up processing and reduces grounds for rejection due to missing information.
7. Shop Around & Compare Offers
Different banks have different margins, promotions, and underwriting criteria. Get multiple quotes. Negotiate (sometimes banks reduce spread or offer incentives).
May get better rate, lower fees, more favorable terms.
8. Provide Clear Purpose & Property Details
Have the Sale & Purchase Agreement (SPA), valuation report (if needed), title deed, property details, etc. If property is new or under construction, ensure developer’s track record and required approvals are in order.
Having savings or avoid fully depleting your accounts helps; having reserves gives cushion in case of rate increases or unexpected expenses.
Shows financial discipline and lowers risk from bank’s viewpoint.
10. Understand Bank Fees & Requirements
Be aware of legal fees, valuation fees, stamp duties, insurance (MRTA/MRTT), and any bank-specific requirements (e.g. guarantor, joint-applicant). Make sure to budget for them.
Unexpected costs can derail the process; being well-prepared ensures smoother approval.
Challenges & What Borrowers Should Watch Out For
Even with OPR at 2.75% and SBR adjusted, banks’ margins/spreads can still be high depending on borrower risk. So effective rates may still be less favourable for some.
Approval ratios (~44-47%) show that over half of applications still get declined. That means it’s not just about rates; credit & affordability are being closely scrutinized. Focus Malaysia – Business & Beyond
Rising costs for legal fees, valuation, and sometimes hidden fees can make total cost of financing higher than expected.
Inflation, future rate rises, economic uncertainties mean banks may reserve right to tighten conditions suddenly.
Conclusion
Bank lending is currently becoming somewhat more favourable in Malaysia thanks to the OPR cut and adjusted reference rates. However, borrowers must still present strong, well-prepared loan applications. Cleaning up credit, reducing existing obligations, having stable income and proper documentation, and choosing appropriate loan terms are all crucial.
The Malaysian property market is buzzing with conversations in 2025 as investors, developers, and buyers respond to new trends, policy shifts, and emerging opportunities. From cooling measures to infrastructure-driven growth corridors, the landscape is evolving rapidly. Rising construction costs, industrial and logistics demand, and the spotlight on data centres are just some of the themes shaping discussions today.
The following are the current hot topics in Malaysia’s property market that every buyer and investor should be aware of:
House Price Growth Moderating Malaysia’s housing price index has been rising, but growth is slowing. For Q4 2024, the national average house price was ~ MYR 483,879, with year-on-year (YoY) growth modest. Global Property Guide There were quarter-on-quarter declines in Q4 2024 in many property types (terraced, high-rise, detached, semi-detached) — showing possible short-term corrections or softening. Global Property Guide
Regional Price Variations
In Penang, average house price remains well above MYR 400,000: about MYR 475,037 in Q4 2024. Global Property Guide
Kuala Lumpur is the most expensive, with average ~ MYR 794,467 in Q4 2024. Global Property Guide
Other states (e.g. Johor, Selangor) are in between; more affordable housing tends to be further out or in less central locations. Global Property Guide+1
Transaction Volume & Supply Residential transaction count rose ~4% in 2024 to about 260,516 units; transaction value grew ~5.9 % to ~MYR 106.92 billion. Global Property Guide The number of new housing starts rose ~20.6 % in 2024 (for both landed + high-rise) to ~106,236 units; completions rose ~9.7% to ~82,135 units. Global Property Guide Also, new planned supply was rising— ~100,461 units in 2024, up ~24.1%. Global Property Guide
Overhang / Unsold Stock Overhang remains a concern, especially in less premium or lower-value housing. The number of unsold affordable homes has increased. According to Rehda, in 1Q 2025 affordable homes accounted for ~20.7% of unsold residential units. EdgeProp.my In Penang, overhang has been showing improvement (decrease in unsold stock) but still persists, especially in certain price bands. Scoop
2. Developer Sentiment & New Launches
Reduced Developer Confidence The Rehda survey (1H 2025) shows confidence among developers fell sharply. Only ~19% were optimistic about market prospects mid-2025, down from ~51% six months earlier. EdgeProp.my Many developers are being more cautious: ~41% plan new launches in 2H 2025, versus higher rates earlier. Some are not looking to acquire new land because of cost and risk. EdgeProp.my
Mismatch of Supply vs Demand (especially “affordable” units) A big issue flagged by developers is that many affordable units are being built in locations or at price levels that are not aligned with what local buyers can afford / prefer. Even though lower-priced units tend to have higher demand, their take-up depends heavily on location, amenities, connectivity. EdgeProp.my+1
Prime / High-end / Branded Projects Doing Better In KL, new launches in “prime” segments are seeing 30-50% take-up rates. Buyers of premium / branded residences (or units in strong locations) are more willing to pay for quality, service, amenities. JLL Branded residences are more visible in Penang too (e.g. Marriott Residences at Gurney Drive) reflecting demand (or at least supply) for high-end product. Wikipedia
3. Commercial, Industrial & Office Sectors
Office Vacancy / Demand Kuala Lumpur’s office market is recovering: vacancy falling, net absorption positive. For example, KL City saw ~231,392 sq ft net absorption in Q2 2025. Vacancy in KL fell from ~23.6% (Q2 2024) to ~19.2% (Q2 2025). JLL Grade A office spaces (those with superior amenities, good location) are better placed; tenants are shifting to better quality buildings. JLL+1
Industrial / Logistics / Data Centres Growing Strong Demand for industrial space is strong — especially in prime logistics, e-commerce, and supply chain related sectors. In KL / Klang Valley, new supply is being absorbed, and vacancy rates are very low for good quality assets. JLL+1 The data centre pipeline is large: Malaysia has about 638 MW of capacity completed, ~1,300 MW under construction, and an even larger future pipeline. Investment in this space is seen as strategic. JLL
4. Government Policy, Taxation & Regulation
Budget 2025 Measures Budget 2025 includes support for infrastructure, sustainable development, and trying to attract investment in high-value sectors. Real estate/spatial planning tied to ESG / green building is emphasized. JLL There’s also focus on more efficient use of land, perhaps more mixed-use zoning or strategic zones. JLL
Tax / Fees / Local Levies In Penang, for instance, there is proposed quit rent increase (2026) — between ~29% to 200% increase for various land categories. For residential urban land, a hike is less steep; commercial / industrial parcels are more affected. Strata properties may face increases later (from 2027). The Vibes
Affordable Housing Policy Pressures Developers are required to allocate certain proportions of new developments to affordable housing, but this has led to some unintended consequences: in some cases, these units are in less attractive locations or are priced above what locals can realistically afford. This mismatch leads to slower sales/unsold inventory. EdgeProp.my
5. Regional Focus: Penang (and Selected States)
Overhang Glut Gradually Easing in Penang Penang had been among the states with large unsold property inventory. In recent years, unsold units in Penang have reduced (e.g. from ~5,493 in 2021 to ~2,796 in 2024). Scoop However, there are still mismatches: properties priced between RM 300,000–500,000 and below are struggling more; high-end (>RM1 million) do better. Location, amenities, connectivity remain critical. Scoop
Infrastructure & Transport Matters More Projects like the Penang Transport Master Plan (including the Mutiara LRT) are expected to impact property values / demand in areas served. Wikipedia Also, improvements like Gurney Bay / Gurney Bay waterfront park are enhancing appeal of coastal / beachfront / high-view precincts in George Town. Wikipedia
Local Revenue / Cost Pressures The quit rent hike in Penang is being discussed: residents are reacting, especially for commercial / industrial land. This adds to holding costs and might shift developers’ cost calculations. The Vibes
High-end / Branded Residences Becoming More Common Examples in Penang: Marriott Residences Penang is a new branded residential tower at Gurney Drive. Wikipedia The Muze @ PICC is also a large mixed residential project in Bayan Baru with tall towers. Wikipedia
6. Risks, Headwinds & Constraints
Cost Inflation, Construction / Input Costs Rising costs for materials, labour shortfalls, logistical challenges (supply chain) are squeezing margins. Developers have less flexibility on pricing vs cost. This trend is being widely reported. EdgeProp.my
Financing / Interest Rates Borrowing costs, stricter lending criteria, risk of loan rejection are issues especially for buyers of affordable homes. Developer access to finance is also more cautious. EdgeProp.my
Unsold Affordable Units Risk If many affordable units stay unsold, there is risk of overhang, lower returns for developers, possible depreciation in certain segments. Also risk of price stagnation in non-prime locations. EdgeProp.my+1
Regulatory Uncertainty / Local Policy Changes Increases in quit rent, possible changes in tax / service tax / sales tax, land use zoning, requirements for affordable housing quotas, etc., create uncertainty. Developers and investors are watching local councils, state governments.
Macro / External Risks Global supply chain disruptions (especially for industrial / data centre / electronics sectors), geopolitical tensions, input cost volatility, and currency / inflation risk. Also, any downturn in global trade could affect Malaysia’s manufacturing / export sectors (with knock-on effects on property demand, especially for worker housing, industrial real estate).
7. Opportunities & What to Watch
Strategically Located High-Quality / Branded Projects Projects with strong amenities, good connectivity (esp. to transit / highways / LRT etc.), high build quality, smart / green features, branded residences — these are likely to command premium pricing and maintain demand.
Industrial, Logistics & Data Centres Given the global trends (e-commerce, supply chain reshoring, semiconductor investment), Malaysia (especially Penang, Johor, Klang Valley) is seeing growing investor interest in industrial / logistics parks, warehouses, data centre space. These are viewed as relatively defensive assets.
Mixed-Use Development & Transit-Oriented Development (TOD) Areas around transport infrastructure (LRT, MRT, light rail, major highway nodes) are likely to benefit. Mixed-use developments (residential + retail + office or amenity) that offer a lifestyle component will be attractive.
Green / ESG / Sustainability Features Buyers / tenants increasingly consider energy efficiency, green certifications, smart home features, environmental impact. Developers incorporating these will have competitive advantage.
Government Incentives & Zone Designations Investment zones, special economic zones, incentives in Budget 2025, tax breaks (where available), and government infrastructure spending (transport, utilities) are going to influence property hot spots.
Price Correction / Buyer Power For savvy buyers, there might be opportunities: slower demand in non-prime sectors, more incentive packages by developers, better negotiations (price, furnishing, perks) especially in properties that are not moving quickly.
Conclusion
Malaysia’s property market in 2025 is at a turning point, balancing between growth opportunities and structural challenges. While affordability and regulatory changes continue to test both developers and buyers, new catalysts such as data centres, logistics demand, and large-scale infrastructure projects are reshaping the landscape.
For investors, the key lies in identifying which segments offer long-term resilience and value. For homeowners, understanding how policies, costs, and location trends play out will make all the difference. Ultimately, the hot topics of today are shaping the strategies, risks, and rewards of tomorrow’s property market.
Let’s Start with This: You’re Not Just Buying a Unit — You’re Buying Into a Community
When you own a condo, apartment, or any kind of strata property, you’re not just buying four walls. You’re also sharing ownership of everything outside your unit — the lifts, the corridors, the lobby, the pool, the roof, the water tank, the whole building.
That’s why every owner needs to pay maintenance fees and contribute to the sinking fund. It’s not a donation. It’s not optional. It’s your duty as a co-owner.
Let’s break it down in plain language…
1. These Are Not “Extra Charges” — They’re Your Legal Responsibility
Under Malaysia’s Strata Management Act 2013 (Act 757):
Section 25(1) (for Joint Management Body or JMB), and
Section 50(1) (for Management Corporation or MC),
…it clearly says: every unit owner must pay maintenance charges and sinking fund contributions.
These are not surprise charges or “admin fees.” They’re meant to cover your share of keeping the building clean, safe, and in working condition. It’s the same as chipping in for house bills when you live with housemates — it’s only fair.
2. “If Others Don’t Pay, Why Should I?”
This is a common complaint — and hey, we get it. Why should you be the good guy when others are skipping out?
But think about this:
If no one pays, who’s going to fix the lift?
Who’s going to pay the cleaners or security guards?
How will the broken tiles or leaking roof ever get fixed?
When people stop paying, the whole building suffers. And soon, even those who were paying start asking: “Why should I continue?” — and that’s when things spiral downhill.
You don’t just live in your unit. You share ownership of the entire building. So if everyone pays their part, everyone enjoys a better home.
3. What Happens If You Don’t Pay?
The law doesn’t just suggest — it enforces. If you don’t pay, the JMB or MC has the right to take action under Section 60(3) of the Strata Management Act.
Here’s what they can legally do:
Send you demand letters
File a claim with the Strata Tribunal or even in court
Charge up to 10% interest per year on overdue amounts
Block your access to facilities (like pool, gym, function room), with proper notice
So it’s not just about being fair to others — not paying could cost you more later, both in fees and reputation. And your outstanding dues? They’ll follow your unit, even if you try to sell.
4. Think of It as an Investment — Not a Burden
No one enjoys paying bills, we know that. But your maintenance charges are not “just another bill.” They’re an investment in your own home.
The money goes into:
Repairs and upkeep
Security and cleanliness
Ensuring your home is safe and comfortable
Keeping your property value high
Ever seen a badly maintained condo? Low resale value, fewer buyers, and complaints all around. Compare that to a well-managed building — units there sell faster and at better prices.
5. You Have the Right to Know Where the Money Goes
Worried that your money is being misused? The good news is: you have rights.
By law, the JMB or MC must:
Hold Annual General Meetings (AGM)
Present audited accounts and budgets
Use the sinking fund for long-term repairs like repainting, roofing, waterproofing, and lift upgrades
As an owner, you can (and should):
Ask for financial reports
Question how funds are being spent
Vote during AGMs
This is your money. And you deserve to know how it’s used.
In Summary: Don’t Just Own a Unit — Own the Responsibility
Paying your maintenance fees and sinking fund isn’t just about following the law. It’s about doing your part.
You’re not a tenant anymore. You’re an owner. You have a stake in the building — and your actions affect everyone else too.
So instead of thinking “Why me?” — let’s think “Why not us?”
Let’s build communities, not just condominiums. Let’s protect our investments, not neglect them. Let’s be the kind of owners who care.
Because a well-maintained building isn’t just a nicer place to live — it’s something you can be proud to call home.
After a strong run in 2023 and 2024, Malaysia’s residential property market is finally taking a breather. While some see this as a red flag, the data paints a more balanced picture—one of resilience and recalibration, not recession.
So, what exactly is happening in 2025? And should you be worried or ready to buy?
Let’s break it down.
📉 Q1 2025: Slower But Still Solid
Malaysia’s residential property transactions dropped 6.2% in Q1 2025 compared to Q4 2024. That’s the first notable slowdown after nearly two years of consistent growth.
But here’s the catch: activity levels are still higher than in 2022, which means we’re not seeing a crash—just a cooling-off.
“The slowdown is expected. It’s the market stabilizing after a hot streak,” said a property analyst from KL.
📈 Prices Are Still Moving Up
The national average house price reached RM483,879 in Q1, reflecting a +1.4% year-on-year increase. Areas like Klang Valley, Penang Island, and Johor Bahru continue to dominate in both value and volume.
Here’s a quick snapshot:
Area
Avg. Price (Q1 2025)
YoY Price Growth
Klang Valley
RM 550,000
+2.1%
Penang Island
RM 620,000
+1.8%
Johor Bahru
RM 460,000
+1.2%
🏗️ Developers Stay Selective with New Launches
With rising construction costs and cautious sentiment, developers are choosing quality over quantity. Most new launches are in well-connected, lifestyle-oriented locations—think smart townships, mixed developments, and green-certified homes.
Hot-selling projects like Elmina Ridge 2 and Avalon Cybersouth saw near 90% take-up rates, showing buyers are still ready to act—when the product is right.
🔍 What’s Supporting the Market?
Despite the slowdown in transactions, several key factors are helping the market stay afloat:
Stable interest rates (BNM kept the OPR steady).
Low unemployment rate (around 3.3%).
Young home-buying population (millennials & Gen Z entering the market).
MM2H visa tweaks requiring foreigners to purchase property.
These are long-term positives that signal stability in the residential segment.
⚠️ What Buyers & Investors Should Watch
While the fundamentals are strong, here are a few caution signs to keep in mind:
Affordability gaps in cities like KL and Penang may limit demand in certain price segments.
Oversupply risks in high-rise areas still exist, especially where demand isn’t organic.
Policy changes—any adjustments to RPGT, stamp duties, or loan rules could shift the playing field fast.
💡 Final Thoughts
If you’re a buyer or investor waiting for a market crash—you might be waiting for a while. What we’re seeing now is not the end of growth, but a healthier, more stable market emerging after years of turbulence.
This could actually be the perfect window to enter—especially if you’re eyeing the right locations, products, and long-term value.
🗣 “The best time to buy property is when others hesitate—because real opportunity hides in uncertainty.”
Need help identifying the right property in 2025? Join the Property EDU Club — get expert guidance, real-life case studies, and insider access to property deals most investors never see.