Tag: property investment malaysia

  • 💰 Household Debt in Malaysia – Should We Be Worried?

    💰 Household Debt in Malaysia – Should We Be Worried?

    If you’ve been hearing about household debt in the news and wondering what it means for us Malaysians, here’s the lowdown—without the boring jargon.

    Historical Context

    • 2008 marked a low point in household debt relative to GDP, at 60.4%, showing moderate borrowing during that period. CEIC Data
    • In 2020, debt peaked during the pandemic, reaching a record 93.1% of GDP. CEIC Data
    • As of 2023, debt remained elevated at 84.2% of GDP, up from 80.9% in 2022. CEIC Data

    These figures indicate that while debt declined from its 2020 high, it remains higher than pre-pandemic levels—an ongoing concern.

    The Latest Numbers (2024–2025)

    • In June 2024, household debt stood at around RM1.57 trillion, accounting for 83.8% of GDP. Housing loans comprised 61%, followed by vehicle loans (13.5%) and personal financing (12.4%).
    • By March 2025, debt rose to RM1.65 trillion, or 84.3% of GDP.

    Interestingly, household financial assets were reported to exceed debt by a factor of 2.1, suggesting Malaysians as a whole still have a substantial financial cushion. Additionally, prudent lending practices are maintained, with median debt service ratios (DSR) remaining at 34% for existing loans and 41% for newly approved loans (2024).

    What This Means for Malaysians

    Risks

    1. Sustained High Debt Load
      With debt hovering around 84% of GDP, many households must allocate a significant portion of income toward repayments—possibly limiting spending on essentials.
    2. Rising Youth Bankruptcy
      Between 2020 and early 2025, over 5,272 youths under 34 were declared bankrupt, with nearly 877 cases in 2024 alone. Personal loans accounted for 46.4% of these filings.
    3. Potential for Over-Leveraging via BNPL
      Growing use of “Buy Now, Pay Later” (BNPL) services (e.g., Atome, Grab PayLater) raises concerns, as they operate outside traditional credit tracking like CCRIS and may enable unmonitored debt accumulation.
    4. Lenient Lending to Young Graduates
      Experts warn that easy credit access for fresh graduates—especially via credit cards—could foster poor financial habits without proper income checks or financial literacy.

    Positive Offsets

    1. Healthy Asset Buffer
      Households’ financial assets outpacing their debts by over double implies a buffer that could cushion against economic shocks.
    2. Responsible Lending Frameworks
      With the Responsible Financing guidelines and relatively moderate DSRs, household borrowing still aligns with regulatory safety standards.
    3. Support Services Available
      Agencies like AKPK have helped over 64,000 borrowers settle loans, while nearly 270,000 others continue to receive support through debt management programs.

    Balancing Act: Looking Forward

    • Economic Growth vs. Debt Sustainability
      While household debt has eased somewhat from its pandemic-era peak, it remains elevated, and spikes in personal or BNPL borrowing could strain households—especially lower-income groups.
    • Youth Financial Health
      The rising bankruptcy trend among the young underscores the necessity of stronger financial education and tighter lending criteria for vulnerable demographics.
    • Policy Opportunities
      Strengthening regulation around new lending platforms like BNPL, embedding financial literacy into early education, and enforcing responsible credit access remain vital steps to prevent systemic vulnerabilities.

    In Summary

    Household debt in Malaysia has declined from its 2020 highs but remains elevated, hovering around 84% of GDP in 2024–2025. While household financial assets provide a buffer and regulatory frameworks offer some protection, rising personal debt—especially among youths and via emerging platforms like BNPL—pose risks. Continued focus on financial education, responsible lending policies, and inclusive support systems will be key to ensuring long-term household resilience.

  • Should You Buy Property in Malaysia Now? Insights 2025

    Should You Buy Property in Malaysia Now? Insights 2025

    Published: July 17, 2025
    By: Miichael Yeoh


    After a strong run in 2023 and 2024, Malaysia’s residential property market is finally taking a breather. While some see this as a red flag, the data paints a more balanced picture—one of resilience and recalibration, not recession.

    So, what exactly is happening in 2025? And should you be worried or ready to buy?

    Let’s break it down.


    📉 Q1 2025: Slower But Still Solid

    Malaysia’s residential property transactions dropped 6.2% in Q1 2025 compared to Q4 2024. That’s the first notable slowdown after nearly two years of consistent growth.

    But here’s the catch: activity levels are still higher than in 2022, which means we’re not seeing a crash—just a cooling-off.

    “The slowdown is expected. It’s the market stabilizing after a hot streak,” said a property analyst from KL.


    📈 Prices Are Still Moving Up

    The national average house price reached RM483,879 in Q1, reflecting a +1.4% year-on-year increase. Areas like Klang Valley, Penang Island, and Johor Bahru continue to dominate in both value and volume.

    Here’s a quick snapshot:

    AreaAvg. Price (Q1 2025)YoY Price Growth
    Klang ValleyRM 550,000+2.1%
    Penang IslandRM 620,000+1.8%
    Johor BahruRM 460,000+1.2%

    🏗️ Developers Stay Selective with New Launches

    With rising construction costs and cautious sentiment, developers are choosing quality over quantity. Most new launches are in well-connected, lifestyle-oriented locations—think smart townships, mixed developments, and green-certified homes.

    Hot-selling projects like Elmina Ridge 2 and Avalon Cybersouth saw near 90% take-up rates, showing buyers are still ready to act—when the product is right.


    🔍 What’s Supporting the Market?

    Despite the slowdown in transactions, several key factors are helping the market stay afloat:

    • Stable interest rates (BNM kept the OPR steady).
    • Low unemployment rate (around 3.3%).
    • Young home-buying population (millennials & Gen Z entering the market).
    • MM2H visa tweaks requiring foreigners to purchase property.

    These are long-term positives that signal stability in the residential segment.


    ⚠️ What Buyers & Investors Should Watch

    While the fundamentals are strong, here are a few caution signs to keep in mind:

    1. Affordability gaps in cities like KL and Penang may limit demand in certain price segments.
    2. Oversupply risks in high-rise areas still exist, especially where demand isn’t organic.
    3. Policy changes—any adjustments to RPGT, stamp duties, or loan rules could shift the playing field fast.

    💡 Final Thoughts

    If you’re a buyer or investor waiting for a market crash—you might be waiting for a while. What we’re seeing now is not the end of growth, but a healthier, more stable market emerging after years of turbulence.

    This could actually be the perfect window to enter—especially if you’re eyeing the right locations, products, and long-term value.

    🗣 “The best time to buy property is when others hesitate—because real opportunity hides in uncertainty.”


    Need help identifying the right property in 2025?
    Join the Property EDU Club — get expert guidance, real-life case studies, and insider access to property deals most investors never see.

    👉 Click here to learn more and join now

  • SST Increase from 6% to 8%: How It Will Impact Malaysia’s Property Industry

    SST Increase from 6% to 8%: How It Will Impact Malaysia’s Property Industry


    Introduction

    Starting July 1, 2025, the Malaysian government officially raised the Sales and Services Tax (SST) from 6% to 8%, aiming to increase national revenue and reduce fiscal deficits. While basic necessities and certain essential services remain exempt, many sectors — including construction, legal, professional, and property-related services — are now affected. This tax adjustment is expected to have ripple effects across various industries, especially the property market, which is already facing affordability challenges.

    This article examines how the SST hike impacts the property industry, giving practical examples and offering insights into how buyers, developers, and investors might respond.


    1. Scope of SST Increase in the Property Sector

    The SST increase does not apply directly to the sale of residential properties, which are exempt from SST. However, indirect costs will go up due to increased service charges in the construction, legal, and property management sectors. These cost increments will eventually be transferred to end buyers and tenants, especially in commercial and high-rise residential developments.


    2. Areas Affected in Property Development

    Here’s a breakdown of how the 2% SST increase affects the property ecosystem:

    Service TypeBaseOld SST (6%)New SST (8%)
    Architect/Engineer FeesRM100,000RM106,000RM108,000
    Legal/Stamping ServicesRM20,000RM21,200RM21,600
    Renovation/Interior Fit-OutRM150,000RM159,000RM162,000
    Property Management ServicesRM50,000RM53,000RM54,000
    Advertising & MarketingRM30,000RM31,800RM32,400

    Example:
    A developer constructing a new serviced apartment project incurs around RM5 million in professional and management fees. Under the previous 6% SST, the tax was RM300,000. Now, it’s RM400,000 — a 33% increase in SST cost, which could result in higher launch prices to maintain developer margins.


    3. Impact on Property Developers

    • Higher Development Cost: Most developers will face a 5–8% increase in overall project costs when combined with inflation and compliance costs.
    • Price Adjustment Pressure: Developers may either absorb the cost (lowering margins) or pass it to consumers — likely raising launch prices, especially in urban areas.
    • Delay in New Launches: Some developers may delay project launches until market conditions stabilize.

    4. Impact on Homebuyers

    Although SST is not directly charged on residential property purchases, buyers may feel the pinch in several ways:

    • Higher Property Prices: Due to rising development and marketing costs.
    • Increased Renovation Expenses: Renovation and interior design are service-based industries and are now charged 8% SST.
    • Increased Maintenance Fees: Management services in condos or commercial buildings may increase, translating to higher monthly maintenance charges for owners and tenants.

    5. Impact on Real Estate Investors

    Investors will also be affected indirectly:

    • Lower Rental Yield: If property prices go up but rental rates remain stagnant, net returns will shrink.
    • Higher Operational Costs: Especially for those managing short-term rentals or Airbnb units (cleaning, advertising, renovation services all now taxed at 8%).
    • Buyer Caution: Investors may delay purchases or switch to lower-risk assets like REITs or landed residential properties outside city centers.

    6. Outlook and Strategies

    Despite the challenges, the SST increase may drive some positive changes:

    • Developers may adopt cost-efficiency technologies to maintain affordability.
    • Buyers may turn to subsale markets, which are less affected by SST-related costs.
    • Investors may focus on cash-flow-positive properties, especially those with low operating costs.

    Conclusion

    The SST increase from 6% to 8% might seem modest on paper, but its cascading effect across the property value chain is real. While residential property sales remain tax-exempt, associated services — from construction to maintenance — will become costlier. As developers adjust pricing and investors reassess risk, Malaysia’s property market may experience a short-term slowdown but could stabilize as the market adapts.


    Final Thought
    For both buyers and investors, 2024–2025 will require careful financial planning and a close eye on property pricing trends. Understanding the real costs behind the price tag is more important than ever.

    From The Desk of Miichael Yeoh

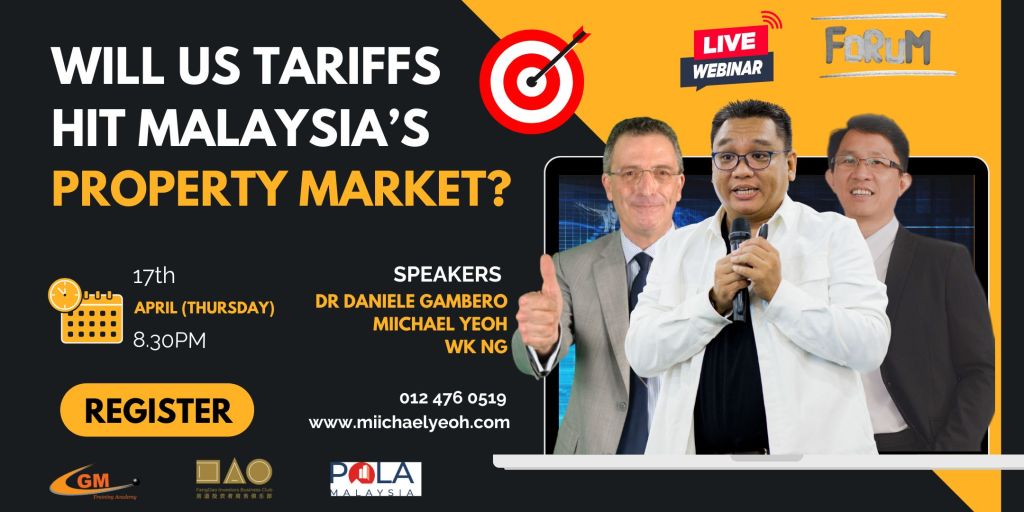
  • Will US Tariffs Hit Malaysia’s Market? Here’s What Experts Say

    Will US Tariffs Hit Malaysia’s Market? Here’s What Experts Say

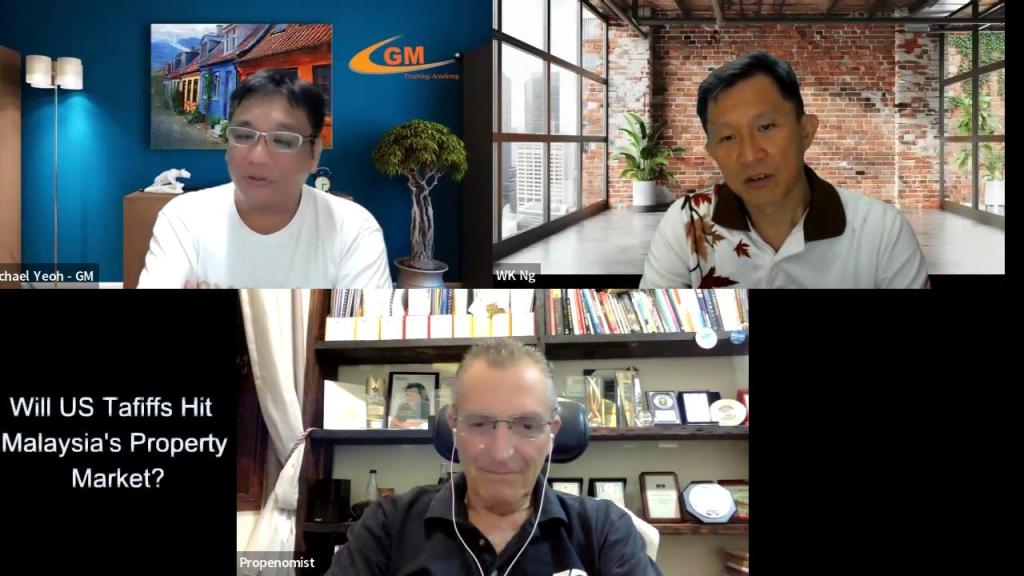
    Over the past few weeks, the global economic community has been buzzing with concern: Will the U.S. impose new tariffs on Malaysia? And if so, what does it mean for our local economy — especially the property market?

    In response to growing public interest, I hosted a last-minute live Zoom forum on this critical issue, joined by three seasoned experts:

    🔹 Miichael Yeoh – CEO of GM Training Academy
    🔹 Dr. Daniele Gambero – economist and CEO of REI Group
    🔹 WK Ng – former Dell director turned full-time property investor

    View the recorded video for more information:

  • Guide to Minimum Foreign Property Purchase Prices in Malaysia

    Guide to Minimum Foreign Property Purchase Prices in Malaysia

    In Malaysia, each state has its own regulations and conditions for foreign property purchases, including minimum purchase prices and additional requirements. Here’s a breakdown of the key differences across states:

    Minimum Property Purchase Prices for Foreigners (2024)

    Foreigners are generally required to buy properties above a certain price threshold, which varies by state:

    StateMinimum Price (MYR)Additional Conditions
    Kuala LumpurRM 1,000,000None for most properties; some high-end condos may have lower thresholds.
    SelangorRM 2,000,000Foreigners can only buy properties ≥RM 2M (since 2024).
    PenangRM 1,000,000 (Island)RM 800,000 for mainland (Seberang Perai). Some exceptions for high-end projects.
    JohorRM 1,000,000RM 2M for landed properties in certain zones (e.g., Iskandar Malaysia).
    MalaccaRM 1,000,000 (urban)RM 500,000 for rural areas (subject to state approval).
    SabahRM 1,000,000Additional approval from state authorities required.
    SarawakRM 1,000,000 (urban)Foreigners need special approval from state government; higher scrutiny.
    PerakRM 1,000,000RM 500,000 for some agricultural/industrial properties.
    PahangRM 1,000,000Lower thresholds (RM 500,000) for certain tourism projects.
    KedahRM 1,000,000RM 500,000 for industrial/commercial properties.
    KelantanRM 1,000,000Additional state consent required.
    TerengganuRM 1,000,000Some exceptions for tourism-related properties.
    Negeri SembilanRM 1,000,000RM 500,000 for commercial/industrial properties.
    PerlisRM 1,000,000Fewer foreign buyers; state approval needed.

    Key Conditions for Foreign Buyers

    1. State Consent Approval
      • Some states (e.g., Sarawak, Sabah, Kelantan, Johor) require additional state approval.
      • In Penang, foreigners must apply for state consent for properties below RM 3M.
    2. Restrictions on Landed Property
      • Foreigners are generally restricted from buying low-cost and Malay Reserve land.
      • In Johor, foreigners can only buy landed properties ≥RM 2M in certain zones.
    3. Additional Taxes & Fees
      • Real Property Gains Tax (RPGT): 30% if sold within 3 years (reduces over time).
      • Foreigner Acquisition Tax: Some states impose extra fees (e.g., Johor charges 2-4% for foreign purchases).
    4. Leasehold vs. Freehold
      • Most states allow foreigners to buy freehold properties, but leasehold purchases may require state approval.
    5. Special Exemptions
      • Malaysia My Second Home (MM2H) participants may enjoy relaxed rules in some states.
      • High-value investments (e.g., RM 5M+) may qualify for exemptions in certain states.

    Recent Changes (2024)

    • Selangor increased the minimum purchase price to RM 2M for foreigners.
    • Johor tightened rules on foreign ownership in Iskandar Malaysia.
    • Penang maintains stricter controls on high-density foreign purchases.

    Conclusion

    Foreign buyers should check with the state land office and consult a local lawyer before purchasing property in Malaysia, as rules can change. Popular investment destinations like Kuala Lumpur, Penang, and Johor have stricter conditions compared to smaller states.

    From the Desk of

    Miichael Yeoh

  • 109 Developers Blacklisted: Safeguards for Malaysian Homebuyers

    109 Developers Blacklisted: Safeguards for Malaysian Homebuyers

    The recent announcement by Housing and Local Government Minister Nga Kor Ming regarding the blacklisting of 109 housing developers is a significant step toward enhancing transparency and protecting homebuyers in Malaysia. By making this list publicly accessible on the ministry’s website, potential buyers can now verify the credibility of developers before making purchasing decisions.

    This initiative is part of broader efforts to address issues related to abandoned projects and fraudulent practices in the housing sector. The proposed amendments to the Housing Development (Control and Licensing) Act 1966 aim to impose stricter penalties on errant developers, including potential travel bans and substantial fines. ​

    While these measures demonstrate the government’s commitment to safeguarding homebuyers, it’s crucial for individuals to conduct thorough due diligence. Beyond consulting the blacklist, prospective buyers should assess developers’ track records, financial stability, and past project completions. Engaging with real estate professionals and seeking legal advice can further ensure informed decisions.​

    In summary, the public disclosure of blacklisted developers is a commendable move toward greater accountability in Malaysia’s housing industry. However, a collaborative approach involving stringent enforcement, legislative reforms, and proactive consumer awareness is essential to foster a trustworthy and resilient housing market.

    Read related article by The Star

    Homebuyers beware: 109 housing developers blacklisted, says Nga | The Star

    From the Desk of

    Miichael Yeoh

  • Unlock Real Estate Success with Property Study Tours

    Unlock Real Estate Success with Property Study Tours

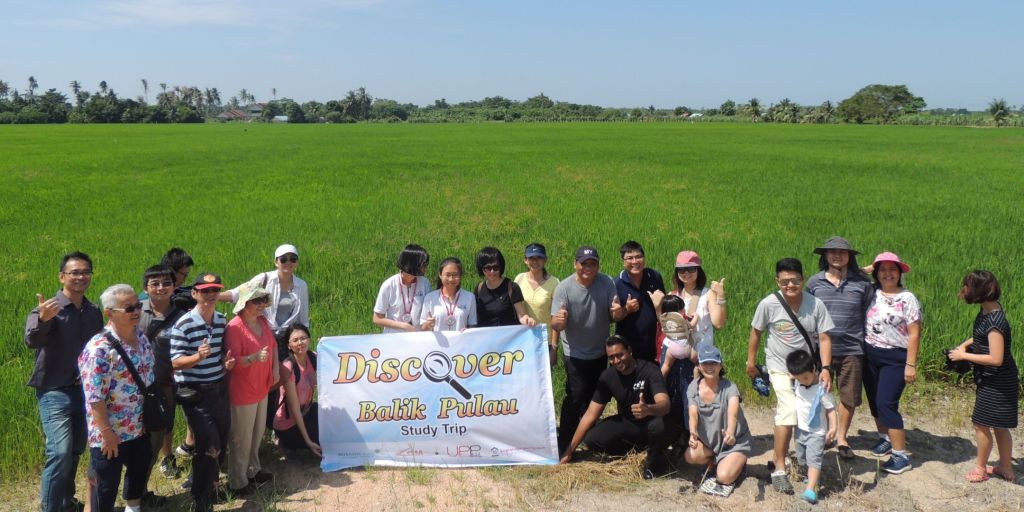
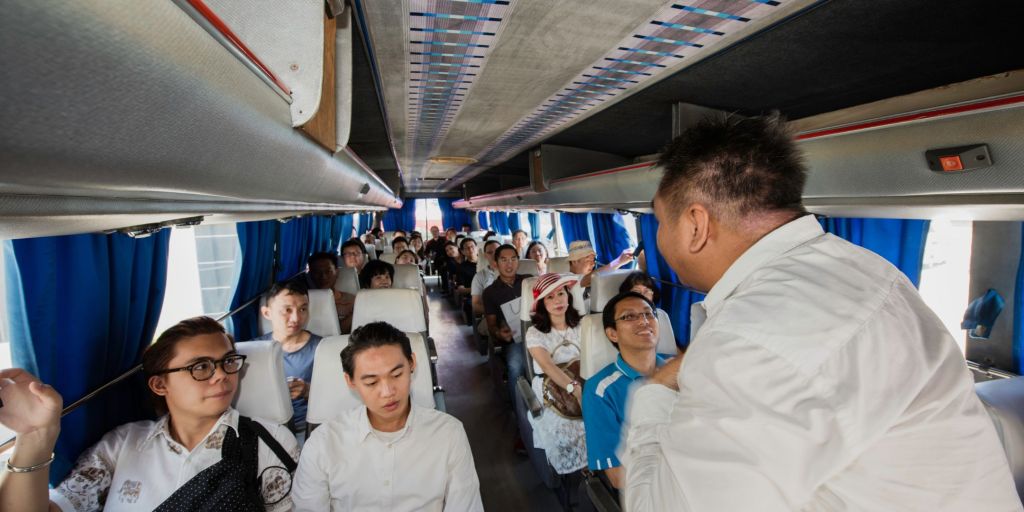
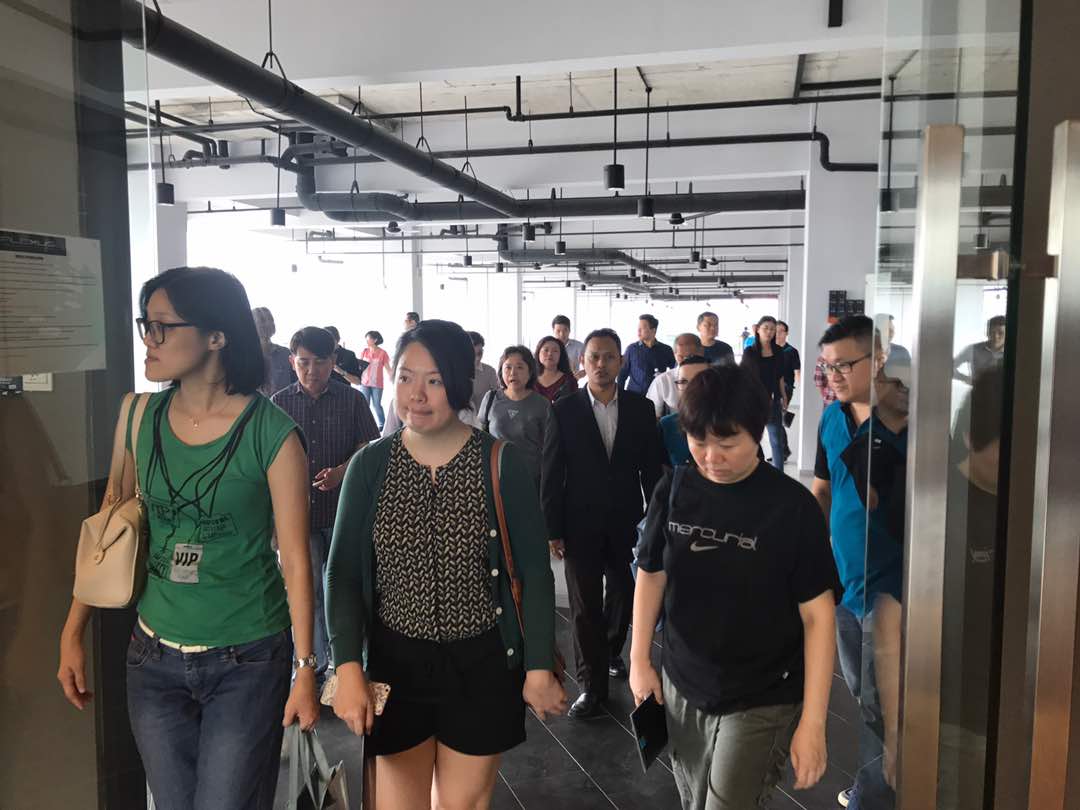
    As a property investment coach and mentor, I’ve seen firsthand how powerful a property study trip can be for investors at all levels. Whether you’re a seasoned investor or just starting out, nothing beats the experience of visiting properties in person, analyzing market trends, and networking with experts. That’s why I organize property study trips—to give you a competitive edge in the real estate market. Here’s why you should join me on this journey.

    1. Firsthand Property Inspection

    Browsing online listings and reading brochures only tell part of the story. When you join my property study tour, you’ll get to walk through the properties, examine the surroundings, and see if they align with your investment goals. I’ll guide you in assessing crucial aspects like location, infrastructure, and future development plans so you can make a well-informed decision. Plus, I’ll share my insights on what to look for in a profitable property, helping you avoid costly mistakes.

    2. Understand Market Trends and Insights

    Every property market operates differently, and the key to successful investing is understanding these nuances. On my study tours, I provide in-depth briefings on market trends, pricing structures, and upcoming investment hotspots. You’ll also hear from local experts who can offer data-driven insights into property price movements and rental yields. I’ve spent years studying the market, and I’ll help you cut through the noise to identify real opportunities.

    3. Network with Like-Minded Investors

    One of the biggest advantages of joining my study trips is the opportunity to meet and network with like-minded investors. Many of my past participants have formed business partnerships, co-invested in properties, or simply found a supportive community to grow with. Learning from the experiences of others can be incredibly valuable, and I make sure to create an environment where everyone can share and learn together.

    4. Exclusive Access to Off-Market Deals

    Through my network and relationships with developers, I often get access to exclusive deals that aren’t available to the general public. This means you’ll have the chance to secure high-potential properties before they hit the open market. Developers also offer special discounts, incentives, and flexible payment plans to my study trip attendees—something you wouldn’t get if you were searching on your own.

    5. Expert Guidance and Analysis

    Investing in property isn’t just about buying a house or unit—it’s about making the right investment decisions. I provide expert guidance throughout the trip, helping you analyze risks, assess potential returns, and navigate financing options. You’ll also gain insights into legal requirements, taxation, and property management. With my years of experience in property investment and financial consulting, I’ll make sure you’re equipped with the knowledge you need to succeed.

    6. Experience the Local Lifestyle and Environment

    A great investment isn’t just about the property itself—it’s also about the surrounding lifestyle, infrastructure, and amenities. By visiting the location in person, you’ll get a feel for the area, check out nearby facilities, and determine whether it aligns with your personal or investment objectives. I’ll also share my insights on which neighborhoods have the most growth potential and what to watch out for when assessing an area’s long-term viability.

    7. Gain Confidence in Your Investment Decisions

    One of the biggest challenges new investors face is hesitation and uncertainty. I believe that seeing is believing, and by joining my study trip, you’ll gain the confidence to make informed investment decisions. I’ll help you weigh the pros and cons of different properties so you can make a calculated decision rather than relying on guesswork.

    8. Exposure to Different Property Investment Strategies

    Not all property investments are the same. During the tour, I’ll introduce you to different strategies such as buying for rental yield, flipping properties, or capital appreciation. You’ll also learn about new trends like co-living spaces and serviced apartments that can diversify your portfolio. By understanding these strategies, you’ll be able to choose an approach that aligns with your financial goals.

    9. Learn from Real-Life Case Studies

    I always include real-life case studies in my study trips, sharing stories of successful property investors who have built wealth through smart real estate decisions. These case studies provide valuable lessons, helping you understand what works and what doesn’t in property investment. You’ll hear from actual investors who share their journeys, challenges, and strategies.

    10. Potential for Immediate Action

    Unlike attending a seminar or watching an online course, a property study tour allows you to take action immediately. If you find a property that meets your criteria, you can reserve it on the spot—often with exclusive perks and discounts. Many of my past participants have successfully secured properties during the trip, giving them a head start in their investment journey.

    Conclusion

    I’ve designed my property study tours to be an immersive, hands-on learning experience that equips you with the knowledge, connections, and confidence to invest successfully. Whether you’re looking for your first property or expanding your portfolio, this tour will give you a significant advantage. Don’t miss out on this opportunity—join me on the next study trip and take your property investment journey to the next level!

    Most importantly, my property study tours are not just about learning and investing—they’re also about having fun! You’ll get to travel, explore new locations, and enjoy meaningful conversations with fellow property enthusiasts. It’s a great way to bond with like-minded individuals, share experiences, and build lasting relationships in a relaxed and enjoyable setting. See you on the next trip!

  • Unlock Wealth with Smart Mortgage Strategies

    Unlock Wealth with Smart Mortgage Strategies

    Did you know that 70% of Malaysians exhaust their EPF savings within just five years of retirement?

    This is a shocking reality, but it doesn’t have to be yours. Without proper financial and mortgage planning, many people find themselves struggling with rising living costs, increasing debt, and an uncertain future.

    Many people believe that simply saving money in a bank or relying on EPF will be enough to sustain them after retirement. However, with inflation, economic uncertainties, and an increasing cost of living, savings alone are not enough. To secure your financial future, you need a smart strategy that builds wealth while you sleep—and that’s where financial and mortgage planning come in.

    If you want to retire rich, not broke, it’s time to take control of your financial future!


    The Importance of Financial & Mortgage Planning

    1️⃣ Your Salary Alone is Not Enough

    Many Malaysians rely solely on their salaries as their primary source of income. However, depending only on salary comes with risks:
    ❌ Job insecurity – What happens if you lose your job or your business slows down?
    ❌ Limited earning potential – Salary increments may not keep up with rising expenses.
    ❌ No long-term wealth creation – Once you stop working, your income stops too.

    By understanding financial planning and leveraging mortgages, you can turn your income into wealth-building assets like property investments that generate passive income.

    ✅ Smart financial planning ensures that your money works for you, not the other way around.

    2️⃣ The Rising Cost of Living & Inflation

    The price of food, petrol, housing, and healthcare has been rising every year. What seems affordable today might be out of reach in the next five or ten years.

    📌 Example: 12 years ago, a property in Kuala Lumpur cost RM300,000. Today, the same property is worth RM600,000. If you had bought it back then, you would have gained RM300,000 in capital appreciation.

    Now imagine if you had invested in properties over the years—how much wealth would you have built?

    This is why financial planning and leveraging mortgages for property investment is crucial. The sooner you start, the better you can protect yourself from inflation and rising costs.

    3️⃣ Using Mortgages as a Wealth-Building Tool

    Many people see mortgages as a burden. But in reality, a mortgage is one of the most powerful financial tools you can use to build wealth.

    Here’s how:
    ✅ Leverage: With a mortgage, you can own high-value properties with only a fraction of the cost upfront.
    ✅ Passive Income: By renting out your properties, you create a steady income stream that covers loan repayments and generates profit.
    ✅ Capital Appreciation: Over time, property values tend to increase, helping you build long-term wealth.

    4️⃣ Securing Your Retirement with Smart Investments

    Many retirees face financial struggles because they failed to plan early. Without a steady stream of passive income, they depend entirely on their savings, which can deplete quickly.

    A well-structured mortgage plan can help you own multiple properties that generate rental income. This means that by the time you retire, you’ll have a steady cash flow to support your lifestyle—without relying on savings alone!


    How to Start Planning Your Financial Future Today

    🔹 Understand how mortgages work – Learn how to maximize loan approvals and use mortgages to grow your wealth.
    🔹 Invest in the right properties – Avoid costly mistakes and find properties that give high returns.
    🔹 Create multiple income streams – Secure your future with passive income from real estate investments.

    Final Thought: The Best Time to Invest is NOW!

    Many people delay financial planning, thinking they have plenty of time. But the truth is, the longer you wait, the harder it becomes to build wealth.

    💡 The best time to invest was yesterday. The second-best time is NOW!

    🚀 Don’t wait until it’s too late. Take charge of your financial future today!

    From the Desk of

    Miichael Yeoh

  • Real Estate Summit 2025: A Resounding Success!

    Real Estate Summit 2025: A Resounding Success!

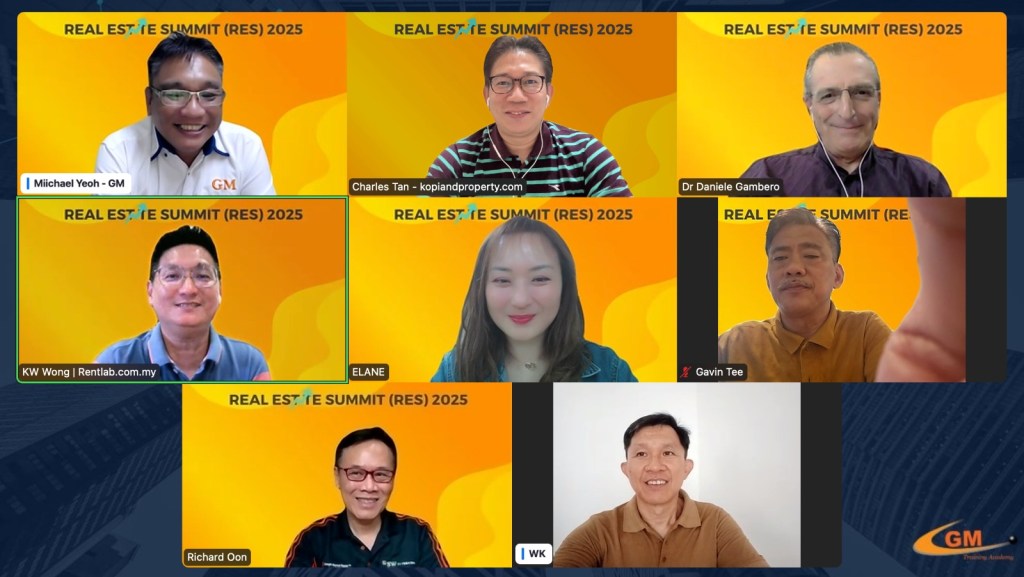
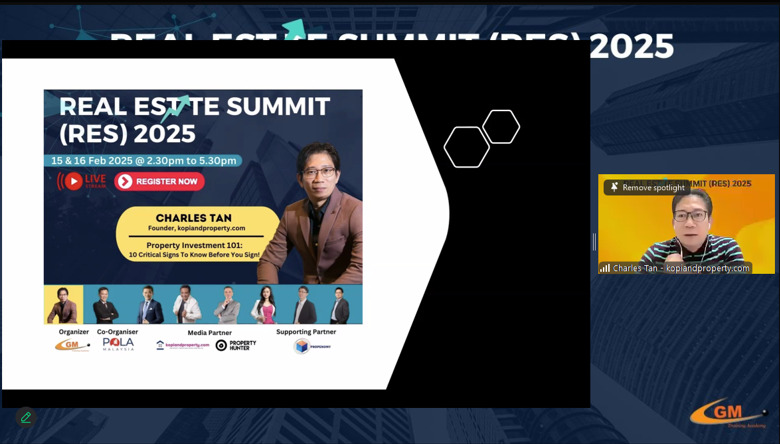
    After two days of insightful discussions, expert sharing, and valuable networking, the Real Estate Summit 2025 (RES2025) has officially concluded! This event brought together some of the most renowned experts in real estate, finance, and investment, providing participants with actionable insights into the property market, financial planning, and smart investment strategies for 2025.

    We were honored to welcome participants from Malaysia, the Philippines, Singapore, the USA, Germany, and many other countries. The diversity of attendees enriched discussions and created a vibrant learning environment.

    A Heartfelt Thank You to Our Participants & Speakers

    First and foremost, we extend our deepest gratitude to all participants for attending RES2025. Your enthusiasm and eagerness to learn made this event truly impactful.

    A special appreciation to our distinguished speakers, whose expertise and insights played a crucial role in the success of RES2025:

    🔹 Dato’ Sri Gavin Tee – A real estate expert who shared his forecast on the 2025 property market and upcoming investment opportunities.
    🔹 Richard Oon – A taxation and financial planning specialist who guided participants on tax-saving strategies and financial management for property investors.
    🔹 Dr. Daniele Gambero – A respected market analyst who discussed real estate trends, mortgage challenges, and investment potential in 2025.
    🔹 Dr. Elane Goh – A finance and investment strategist who shared her insights on wealth creation through property investments and financial planning.
    🔹 WK Ng – A seasoned property investor who transitioned from the corporate world to full-time investing, providing real-life success strategies.
    🔹 KW Wong – A PropTech innovator and Secretary-General of the Malaysia PropTech Association, who spoke about the digital transformation of the rental market.
    🔹 Charles Tan – A leading property market analyst who offered valuable perspectives on Malaysia’s evolving real estate landscape.
    🔹 Miichael Yeoh – A mortgage and financial expert, who emphasized the importance of planning before making any major investment decisions.

    Your dedication and willingness to share your knowledge made RES2025 a game-changing event for all attendees.

    Special thanks to our co-organiser POLA Malaysia and our media partners Property Hunter and kopiandproperty.

    Key Takeaways from RES2025

    Throughout the two-day summit, participants gained powerful insights into the property industry, with topics covering:

    ✔️ Where to Invest in 2025 – Discovering high-potential investment hotspots.
    ✔️ Real Estate Market Trends – Adapting to economic shifts and evolving regulations.
    ✔️ Financial Planning & Taxation – Understanding tax incentives, financial structures, and mortgage strategies.
    ✔️ Mortgage Market 2025 – The latest developments in home financing and lending policies.
    ✔️ PropTech Innovations – The rise of digital property platforms and the impact on buying, selling, and renting.
    ✔️ Investment Strategies – How to build a profitable real estate portfolio.

    As Miichael Yeoh emphasized in his session: “Plan first before making your next move.” Strategic financial and investment planning is essential to achieving long-term success in real estate.

    The Power of Networking & Knowledge Sharing

    Beyond expert talks, RES2025 provided an invaluable opportunity for participants to connect with industry leaders, experienced investors, and like-minded individuals. The event fostered an environment where attendees could exchange ideas, gain exclusive insights, and build meaningful professional relationships.

    Looking Forward: What’s Next?

    The success of RES2025 reaffirms GM Training Academy’s commitment to empowering individuals with property education and financial literacy. We believe that informed decisions lead to successful investments, and we are dedicated to helping investors, homeowners, and professionals navigate the ever-changing real estate market.

    🚀 Upcoming Initiatives:

    ✅ More masterclasses and training workshops
    ✅ Exclusive webinars featuring top industry experts
    ✅ Property investment study tours
    ✅ Advanced financial and mortgage planning courses

    Stay Connected & Keep Learning

    📢 Missed RES2025? No worries! Stay connected with us for upcoming programs that will continue to provide valuable industry insights and expert guidance.

    Once again, THANK YOU to all our participants and speakers for making RES2025 a grand success! We look forward to seeing you at our next event.

  • Malaysia’s Loan Scandal: Consultancies Siphon 35% from Borrowers

    Malaysia’s Loan Scandal: Consultancies Siphon 35% from Borrowers

    A major financial scandal in Malaysia has exposed a corrupt syndicate involving consultancy firms and bank officials, who siphoned 35% of approved loans from borrowers, primarily civil servants. The Malaysian Anti-Corruption Commission (MACC) revealed that these firms manipulated loan processes, securing multiple overlapping loans for victims, leaving them with crippling debts. Over RM700 million in loans were processed, but borrowers received only a fraction after exorbitant fees. The MACC’s ongoing crackdown has arrested 27 individuals and frozen RM22 million in assets, but the financial and emotional toll on victims remains severe.

    Click for more Information or Sign Up

    This issue has persisted for years, with many property buyers enticed to purchase multiple properties beyond their means. For instance, individuals with a RM5,000 salary were lured into buying 10 properties with high cashback offers, only to face financial ruin. In one case, a couple after attending my seminar shared how they were encouraged by a “Property Guru” to buy five properties at once, exploiting bank loopholes. They later discovered the properties were overpriced and unrentable, leaving them bankrupt with RM16,000 monthly installments and two young children to support. This highlights the dangers of reckless investment decisions. Always verify sources, avoid intermediaries charging excessive fees, and ensure investments align with your financial capacity.
    From the Desk of

    Miichael Yeoh

    Read the full article…..

    Bank Loan Scandal: How Consultancy Firms Pocketed 35% from Borrowers’ Loans

    By: Kpost

    A financial scandal of massive proportions has rocked Malaysia’s banking sector, exposing a corrupt syndicate that preyed on borrowers, especially civil servants, by siphoning off exorbitant fees from approved bank loans.

    The Malaysian Anti-Corruption Commission (MACC) recently uncovered that financial consultancy firms, operating under the guise of loan facilitators, were pocketing at least 35% of the approved loan amounts, leaving victims with far less than what they had borrowed.

    A Web of Deceit: How Borrowers Were Trapped

    The scheme involved consultancy firms manipulating the loan approval process in collusion with corrupt bank officials. According to MACC Chief Commissioner Tan Sri Azam Baki, the syndicate exploited desperate borrowers by securing multiple loans from various financial institutions simultaneously, orchestrating a complex scam that resulted in borrowers being burdened with insurmountable debts.

    “These firms orchestrated ‘multiple loans’ by manipulating bank systems and turn-around times, making it seem as if previous loans had been settled when, in reality, they had not. This deception ensured that borrowers would receive overlapping loans, only to have substantial portions deducted as ‘fees,’” said Azam.

    Many victims, entangled in financial distress and seeking funds to settle previous debts, unknowingly agreed to the terms set by these firms. In addition to the 35% consultancy fee, borrowers were also subjected to loan settlement charges of up to 40%, further exacerbating their financial woes.

    RM700 Million in Loans: But Victims Still Drowning in Debt

    The investigation, codenamed Ops Sky, revealed that the syndicate managed to secure approximately RM700 million in loans for borrowers. However, instead of receiving their full loan amounts, victims were left with only a fraction of what they applied for, leading to a debt crisis far beyond their means to repay.

    Despite the dismantling of the syndicate, the damage has already been done. Many victims now owe three times more than their financial capabilities allow, making repayment virtually impossible. “Even though the syndicate has been dismantled, borrowers remain indebted to the banks and must continue servicing their loans,” Azam stated.

    Massive Crackdown: Bank Officers and Syndicate Members Arrested

    In a coordinated crackdown, MACC and Bank Negara Malaysia raided 24 locations across the Klang Valley, including residences and offices linked to the syndicate. The operation led to the arrest of 12 key individuals, including bank officials and employees of the financial consultancy firms involved.

    Further investigations revealed that 98 company and personal bank accounts worth over RM22 million had been frozen, and nearly 4,000 documents seized as part of the evidence collection.

    A total of 27 individuals, including 18 bank officers, eight financial consultancy employees, and one member of the public, were detained before being released on bail.

    Social Media and Celebrities Used to Lure Victims

    Adding another layer to the scandal, the syndicate aggressively marketed its services using social media influencers, celebrities, and public figures to gain credibility.

    Advertisements flooded Facebook, TikTok, and Instagram, targeting schoolteachers, nurses, and government employees.

    The firms even conducted surveys, roadshows, and CSR programs at schools and hospitals, falsely promoting their services as legitimate financial solutions.

    What’s Next? Ongoing Investigations and a Warning to the Public

    The MACC has vowed to continue its investigations under Ops Sky, with more witnesses expected to be summoned. The public is urged to be cautious when dealing with financial consultancy firms that promise easy loans, especially those charging high service fees upfront. “This case serves as a stark warning and always verify loan processes directly with the bank and avoid intermediaries who demand excessive fees,” Azam cautioned.

    As investigations continue, Malaysians are left questioning how such large-scale corruption involving multiple financial institutions could have persisted unchecked for so long. The financial burden on victims remains heavy, and the battle for justice is far from over.

    Information Source: Newswav

  • Effects of OPR Changes on Borrowing and Savings

    Effects of OPR Changes on Borrowing and Savings

    As of January 2025, Bank Negara Malaysia (BNM) has maintained the Overnight Policy Rate (OPR) at 3.00%, a position held since May 2023.

    Understanding the Overnight Policy Rate (OPR)

    The OPR is the benchmark interest rate at which banks lend to one another overnight. Set by BNM, it serves as a primary monetary policy tool to regulate liquidity, control inflation, and sustain economic growth.

    Implications of an OPR Increase

    When BNM raises the OPR, it signals an intent to tighten monetary policy. The effects of such an increase include:

    Higher Borrowing Costs: Banks typically respond to an OPR hike by raising their base rates, leading to increased interest rates on loans and mortgages. This results in higher monthly repayments for borrowers.

    Enhanced Savings Returns: Conversely, depositors may benefit from higher interest earnings on savings and fixed deposits, encouraging increased savings.

    Controlled Inflation: Elevated borrowing costs can dampen consumer spending and business investments, helping to moderate demand-pull inflation.

    Currency Appreciation: Higher interest rates can attract foreign investment, potentially strengthening the Malaysian ringgit.

    Impact on Property Market: Increased interest rates may lead to higher mortgage costs, potentially cooling property demand and affecting market dynamics.

    Recent Economic Context

    In the third quarter of 2024, Malaysia’s economic growth slowed to 5.3% from 5.9% in the previous quarter, influenced by reduced oil and gas production. Despite this, robust household spending and increased investments provided support.

    BNM’s Monetary Policy Stance

    BNM has maintained the OPR at 3.00% since May 2023, citing positive economic growth and steady inflation. Economists anticipate that the central bank will keep the OPR unchanged until at least 2026, aligning with current economic assessments.

    Interest Rate Impact Example

    Let’s look at an example of how interest rates affect property loans. Assume you’re borrowing RM500,000 for 30 years:

    • Current Interest Rate (4.5%): Monthly repayment is approximately RM2,533.43.
    • If OPR Increases by 25 Basis Points (4.75%): Monthly repayment rises to around RM2,608.82.
    • Impact: This increase of RM75.39 per month adds up to RM27,140.40 over the loan’s term.

    This illustrates why understanding interest rates and their potential changes is crucial for planning your finances.

    Conclusion

    An increase in Malaysia’s OPR has multifaceted effects, influencing borrowing costs, savings returns, inflation, currency value, and the property market. Understanding these dynamics is crucial for individuals and businesses to make informed financial decisions in response to monetary policy changes.

    From the Desk of

    Miichael Yeoh

  • Avoid Costly Mistakes: 8 Reasons to Learn Before Investing in Real Estate

    Avoid Costly Mistakes: 8 Reasons to Learn Before Investing in Real Estate

    Purchasing or investing in property is one of the most significant financial decisions a person can make. While the prospect of owning a piece of real estate can be exciting, it’s also fraught with risks and complexities. Here are eight compelling reasons why educating yourself before taking the plunge is crucial:

    1. Understanding the Market

    The property market is dynamic, influenced by factors such as economic conditions, interest rates, and government policies. Without proper knowledge, you might buy at the wrong time or in the wrong location, potentially leading to financial losses. Education helps you grasp market cycles and trends, enabling informed decisions.

    2. Avoiding Costly Mistakes

    From overpaying for a property to falling victim to scams, the risks of making costly mistakes are high for uninformed buyers. Learning about property valuation, legal processes, and common pitfalls can save you from financial heartache.

    3. Maximizing Investment Returns

    Investing in property isn’t just about buying a house or apartment; it’s about choosing assets that will appreciate in value or generate steady rental income. Understanding key metrics such as ROI (Return on Investment) and cash flow can help you identify profitable opportunities.

    4. Navigating Legal and Financial Complexities

    Property transactions involve a maze of legal and financial considerations. From understanding loan agreements to navigating tax implications and zoning laws, there’s a lot to learn. A lack of knowledge could lead to delays or even legal troubles.

    5. Building Confidence

    The more you know, the more confident you’ll feel about your decisions. Knowledge reduces fear and uncertainty, empowering you to negotiate effectively, choose wisely, and stick to your long-term goals.

    6. Identifying Red Flags

    Not all properties are created equal. Structural issues, poor location, and hidden costs can turn a dream investment into a nightmare. Learning to conduct due diligence and property inspections ensures you spot potential problems early.

    7. Accessing Better Financing Options

    Understanding how mortgages and loans work can save you thousands of dollars over the life of your investment. Learning about different financing options and how to improve your creditworthiness can lead to better interest rates and loan terms.

    8. Planning for the Future

    Property investment is a long-term commitment. Learning helps you align your investment choices with your financial goals, whether it’s building wealth, securing passive income, or preparing for retirement. Knowledge enables strategic planning that benefits you in the long run.

    Conclusion

    Investing time and effort into learning before buying or investing in property is an investment in itself. It equips you with the tools and insights needed to make smart, informed decisions that align with your financial aspirations. Remember, in the world of property, knowledge isn’t just power; it’s profit.