Tag: property investment malaysia

  • Is Now a Good Time to Buy Property in Malaysia ?

    Is Now a Good Time to Buy Property in Malaysia ?

    Everyone wants to know whether property prices will rise or fall.

    But that’s not the question I would ask before buying a property.

    The better question is:

    “Is this the right property, at the right price, with the right financing, for my situation?”

    Because even if the market rises next year, you can still make a bad property decision today.

    And even if prices fall, waiting doesn’t automatically mean you will get a better deal.

    So, is 2026 a good time to buy property in Malaysia?

    My answer: It can be — but only if you stop trying to predict the market and start discovering the numbers behind the decision.


    What Is Actually Happening in the Malaysian Property Market?

    Let’s start with the facts.

    Malaysia’s property market remained resilient in the first half of 2026, recording 187,320 transactions worth RM105.12 billion. The market was supported by relatively stable transaction activity, prices and construction activity.

    At the same time, the market isn’t booming across every segment.

    Residential transactions in H1 2026 were 110,998, accounting for 59.3% of total property transactions. Completed unsold residential units increased to 33,094 units, worth about RM17.78 billion.

    That tells us something important.

    The market isn’t simply “good” or “bad”.

    There are areas of strength.

    There are areas of oversupply.

    There are properties with genuine demand.

    And there are properties that developers are struggling to sell.

    This is exactly why buyers need to become more selective.

    What About Interest Rates?

    This is probably one of the first things buyers look at.

    And understandably so.

    Bank Negara Malaysia has maintained the Overnight Policy Rate (OPR) at 2.75% throughout 2026, including its latest decision on 3 September 2026.

    That provides a relatively stable financing environment compared with periods of rapidly changing interest rates.

    But here’s where I think many buyers make a mistake.

    They see a stable or lower interest-rate environment and immediately think:

    “Good. Time to buy.”

    Not necessarily.

    The interest rate is one variable in your property decision.

    It is not the decision.

    A property that is overpriced by RM100,000 doesn’t suddenly become a good investment because your mortgage rate is slightly lower.


    Should You Wait for Property Prices to Fall?
    This is probably the question I hear most often.

    And it sounds logical.

    “If prices are going to fall, I’ll wait.”

    But there are two problems with this strategy.

    First, nobody knows exactly when prices will fall.

    And more importantly:

    Second, even if prices fall, you may not benefit.

    Why?

    Because the property you want may not fall.

    The bank may tighten lending.

    Your income may change.

    Interest rates may move.

    The developer may remove incentives.

    Another buyer may take the unit you wanted.

    Or the market may simply remain stable for several years.

    Waiting is not a neutral decision.

    Waiting is also a property decision.


    The Bigger Question: What Are You Actually Buying?

    This is where I believe buyers need to change their thinking.

    Don’t ask only:

    “Will property prices go up?”

    Ask:

    “What is creating the demand for this property?”

    Is it:

    • population growth?
    • new jobs?
    • infrastructure?
    • universities?
    • industrial development?
    • tourism?
    • rental demand?
    • limited land supply?
    • better connectivity?
    • genuine owner-occupier demand?

    Or is the main attraction simply:

    “The developer says prices will increase.”

    Those are very different things.


    5 Things I Would Check Before Buying Property
    1. Can You Actually Afford It?

    This sounds obvious.

    But affordability isn’t simply:

    “The bank approved my loan.”

    A bank’s approval tells you what the bank is prepared to lend.

    It doesn’t tell you what you should comfortably borrow.

    Before buying, calculate the full monthly cost:

    • mortgage instalment
    • maintenance fee
    • sinking fund
    • assessment
    • quit rent
    • insurance
    • utilities
    • repairs
    • furnishing
    • parking
    • transportation
    • other existing commitments

    Then ask:

    “If my income stays the same for the next three years, will this property still feel comfortable?”

    That’s a much better question than:

    “How much can the bank approve?”


    2. Is the Price Supported by the Market?

    Don’t fall in love with the launch price.

    Find out what similar properties are actually transacting for.

    NAPIC provides transaction, price, rental and property-market data, including state and district-level information.

    Compare:

    Asking price vs actual transaction price.

    Then compare:

    RM per sq ft vs comparable properties.

    Then ask:

    “What am I paying a premium for?”

    If the answer is simply:

    “Because this is a new launch.”

    That’s not enough.


    3. Is There Real Demand?

    A beautiful building isn’t demand.

    A famous developer isn’t demand.

    A fantastic showroom isn’t demand.

    Demand comes from people who genuinely want to live, work, rent or invest in that location.

    Ask:

    • Who is going to live here?
    • Who is going to rent here?
    • Where do these people work?
    • Why would they choose this location?
    • What alternatives do they have?
    • What competing projects are coming?

    This becomes particularly important when a market has significant unsold stock.

    Malaysia’s completed unsold residential inventory rose to 33,094 units in H1 2026.

    That doesn’t mean all property is bad.

    It means product selection matters.


    4. What Happens When More Supply Arrives?

    This is one of the most overlooked questions in property investing.

    Imagine you buy a condominium because the current rental demand looks excellent.

    But three years later, five more projects are completed nearby.

    Now you have thousands of competing units.

    Your tenant has choices.

    Your rental growth may slow.

    Your vacancy risk may increase.

    And when you eventually want to sell, you’re no longer competing only against today’s properties.

    You’re competing against tomorrow’s properties.

    That’s why I always tell buyers:

    Don’t just study the property. Study what is coming around the property.


    5. What’s Your Exit Strategy?

    This is perhaps the biggest difference between a home purchase and an investment purchase.

    A homeowner may be happy because:

    “I love the location.”

    An investor needs another question:

    “Who will buy this from me later?”

    Think about your exit before your entry.

    If you need to sell in five or ten years:

    • Who is your future buyer?
    • What will they be looking for?
    • What competing supply will exist?
    • Will your property still be relevant?
    • Will your price be affordable to the next buyer?
    • Will the rental market support your valuation?

    You don’t realise your investment return when you buy.

    You realise it when you eventually exit.


    So… Is 2026/2027 a Good Time to Buy Property?

    Here’s my answer.

    Yes — if you’re buying based on fundamentals.

    No — if you’re buying simply because you believe prices must go up.

    The Malaysian property market in 2026 is resilient, but the data also shows why buyers cannot treat the entire market as one big opportunity.

    Transaction activity remains substantial.

    Interest rates are relatively stable.

    But residential demand is uneven, completed unsold stock has increased, and affordability remains an important constraint.

    That creates an interesting environment.

    It may actually be a better time to be a selective buyer than an emotional buyer.

    You don’t necessarily need to wait for a market crash.

    You need to find the property where:

    Price + Location + Demand + Financing + Supply + Exit

    all make sense together.


    The PDS 7-Question Property Test

    Before I buy any property, I would want to answer these seven questions:

    1. Why this property?

    What problem does it solve?

    2. Why this location?

    What is creating sustainable demand?

    3. Why this price?

    What evidence supports the valuation?

    4. Who is the future buyer or tenant?

    Where does the demand come from?

    5. What competition is coming?

    What could affect rental and resale demand?

    6. Can I comfortably hold it?

    Not just today — but through different market conditions.

    7. How do I eventually exit?

    Who will buy it from me?

    If you can’t answer these questions, perhaps you are not ready to buy.

    And that’s okay.

    Not buying is sometimes a better decision than buying the wrong property.


    The Real Question Isn’t “When Should I Buy?”

    After more than two decades around banking, mortgages, property and investment decisions, I’ve learned that buyers often spend too much time trying to predict the market.

    The smarter approach is to understand the decision.

    You don’t need to know exactly where property prices will be five years from now.

    You need to understand why the property you’re considering should still have demand five years from now.

    That’s a very different way of looking at property.

    And it is the philosophy behind the Property Discovery System™.

    Don’t just ask whether now is a good time to buy.

    Discover whether this is the right property for you.

    Discover Better. Decide Smarter.

    Miichael Yeoh

    Property Strategist
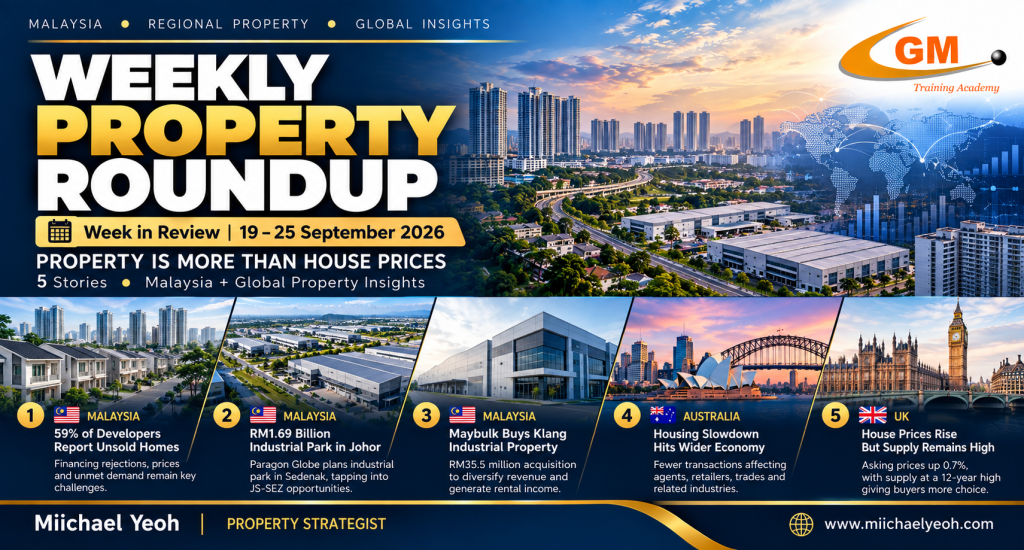
  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    Week in Review | 19–25 September 2026

    Malaysia • Regional Property • Global Insights

    The property market is not one market. Different assets, locations and economic forces are moving in very different directions.


    🇲🇾 1. Almost 60% of Developers Report Unsold Completed Homes

    https://images.openai.com/static-rsc-4/uJ1sXQYW8YNgLMcTGhfcD4h9AlGny1gVvYl0-3Z_UUWwYtxe0L-njDRK6hbq_nQHxshYIf8luumPsz7hwaFkeeFnY-h9INrh1M3Wsc166NXJCu6itg6Pu3naU9MIZA6kT81KGWzDrYNL-2laiMsgo-gFVvv0qAxul-Ei9rdVdXRqEG6ZpH0OrMh_BYhREWGV?purpose=fullsize

    What Happened

    A new REHDA Property Industry Survey found that 59% of 181 developers surveyed had unsold completed residential units as at 30 June 2026.

    The three main reasons cited were rejected end-financing applications, property prices and unreleased Bumiputera units.

    During the survey period, 54 respondents launched 15,834 units and sold 5,260 units, giving a take-up rate of 33.2%, only slightly higher than 32.2% previously.

    REHDA also highlighted rising construction costs, financing constraints and regulatory/compliance costs as pressures on housing affordability. An average 13% increase in construction costs was reported between March and June.

    Why It Matters

    This is an important distinction:

    A home can be “affordable” on paper but still unaffordable to the buyer.

    If financing is rejected, margins are lower or credit requirements become more difficult, the advertised selling price isn’t the whole affordability equation.

    For developers, unsold completed stock also ties up capital.

    Miichael’s Review

    This is exactly why I believe buyers should look beyond the headline price.

    Before deciding whether a property is affordable, ask:

    Can I actually obtain the financing?
    What is my monthly commitment?
    What happens if interest rates or my income situation changes?

    For developers, the lesson is equally important:

    Product pricing must match real purchasing power — not just construction cost plus desired margin.

    Source: EdgeProp — REHDA survey on unsold homes and EdgeProp — REHDA on housing costs


    🇲🇾 2. Johor: Paragon Globe Plans RM1.69 Billion Industrial Park

    What Happened

    Paragon Globe is pursuing additional land in Sedenak, Johor, for a proposed industrial park with an estimated gross development value of RM1.69 billion.

    The project sits within the Kulai-Sedenak zone of the Johor-Singapore Special Economic Zone (JS-SEZ) and is planned to include industrial factories, commercial components and worker accommodation.

    The group is also taking a more strategic approach to land development, looking at anchor occupiers and the ecosystems that can form around them, rather than simply developing land in isolation.

    Why It Matters

    This is bigger than another industrial-property announcement.

    The interesting part is the “anchor occupier” strategy.

    A major manufacturer can create demand for:

    • suppliers
    • logistics
    • warehouses
    • worker accommodation
    • retail
    • supporting services

    That can turn an industrial site into an economic ecosystem.

    Miichael’s Review

    This is the kind of development strategy I find interesting.

    The best land doesn’t necessarily have the highest GDV.

    Sometimes the real question is:

    “What economic activity will this land create around itself?”

    That is a much more powerful way to assess long-term land value.

    Source: The Star — Paragon Globe eyes RM1.69bil industrial park; EdgeProp — Paragon Globe landbank strategy


    🇲🇾 3. Klang: Maybulk Moves Into Industrial Property

    What Happened

    Maybulk has proposed acquiring an 8,346 sq m freehold industrial property in Bandar Bukit Raja, Klang, for RM35.5 million.

    The property includes an industrial building, warehouse and office facilities.

    Importantly, Maybulk said the move is part of a strategy to diversify its revenue streams and reduce reliance on its existing shipping and storage businesses.

    The acquisition would also immediately provide rental income once completed.

    Why It Matters

    This is a smaller transaction than the headline billion-ringgit deals — but strategically, it is very interesting.

    We’re seeing a company from outside traditional property development use industrial real estate as an income-producing asset.

    That reflects the growing attractiveness of industrial property as an investment class.

    Miichael’s Review

    I always find these transactions worth watching because they show how corporate investors think about property differently from individual buyers.

    For a corporate investor, property can be:

    An operating asset + rental income + capital preservation + diversification.

    That is very different from buying a property simply because “the area is going up.”

    Source: The Star — Maybulk proposes RM35.5mil Klang industrial acquisition


    🌏 4. Australia: The Housing Slowdown Is Hitting More Than Property Agents

    https://images.openai.com/static-rsc-4/Brs6pRtz5kYYyfE4NHjlwNYzDeZsQhdHN8Ay_xpJgbljRtmXqHfXrQ0ZJ7iHrrLLQKWOe0izOsryIQPmdtGfKgsZshly6_Y3bJOYhnrsCRXXrUXpoyniGMpBU6UiTg5U1rpeUgc7Zw_F7zL8TwPXur-FNtdpsHx7XF08Uo8dO-6FZFqw6SGoo2PIJCj64MzF?purpose=fullsize

    What Happened

    Australia’s housing slowdown is now affecting a much wider economic ecosystem.

    Reuters reported that Australian home sales volumes have fallen sharply, with turnover 15% below a year earlier in July/August and 10.5% below the five-year average.

    Reuters estimates that the reduction in housing activity could remove around A$2.8 billion to A$5.6 billion of annual spending from businesses connected to property transactions — including removalists, conveyancers, furniture retailers, tradespeople and renovation businesses.

    The important point is that prices themselves have not collapsed: Reuters reported prices were less than 4% below the March peak and still above year-ago levels. The bigger issue is fewer transactions.

    Why It Matters

    This is a fascinating distinction:

    Property prices can remain relatively resilient while the property economy slows dramatically.

    If fewer people buy and sell, many businesses around the property ecosystem suffer.

    Miichael’s Review

    This is a useful lesson for Malaysia too.

    When we analyse a property market, we shouldn’t look only at:

    “Are prices rising?”

    We should also watch:

    transaction volume, financing, turnover, inventory and buyer confidence.

    A market can look healthy from a price chart while becoming much less active underneath.

    Source: Reuters — Australia’s housing slowdown and wider economic impact


    🌏 5. UK Housing: Prices Bounce, But Buyers Remain Selective

    https://images.openai.com/static-rsc-4/AEe5M10FcR-kJRCayCQU6MvkhNhkoA3_xw2GGp_f6LLLxiydkqrUYPQL63QZdaCxQoINy6jL0mpDitHMoiolKW5iBFZCF_fbHycfkm-eMLNzJIn4oybRTkZ_P3qO1zOmbgx6hiVX8Ce5o71Tg2Q2XS9ZjNv5XPC_Gl731cYvpOuShOgWgt_lYJuEbdKNQVeu?purpose=fullsize

    What Happened

    UK asking prices rose 0.7% in September, equivalent to about £2,441, according to Rightmove data reported by The Times.

    The average asking price reached approximately £367,440.

    But the headline increase needs context: prices remained 0.8% below a year earlier, while housing supply was reported to be at a 12-year high.

    Why It Matters

    More supply gives buyers more choice — and therefore more negotiating power.

    A seller cannot simply assume that a higher asking price will translate into a higher achieved price.

    Miichael’s Review

    This is one of my favourite property lessons:

    The asking price is not necessarily the market value.

    When supply rises and buyers become more selective, pricing strategy becomes increasingly important.

    For investors, this also reinforces the need to distinguish between:

    headline price movement and actual market liquidity.

    Source: The Times — UK house prices rise for first time since May


    📊 PROPERTY NUMBER OF THE WEEK

    59%

    The percentage of surveyed Malaysian developers reporting unsold completed residential units.

    But the more interesting number may be:

    33.2%

    The reported take-up rate during the REHDA survey period.

    The lesson: demand exists — but buyers are becoming increasingly constrained by financing, affordability and product suitability.


    👀 WORTH WATCHING

    🇲🇾 Malaysia

    1. Housing affordability
    Will financing accessibility improve enough to reduce completed unsold stock?

    2. Johor industrial property
    Watch how the JS-SEZ develops around actual occupiers and employment rather than simply land speculation.

    3. Klang industrial assets
    Will more corporates diversify into income-producing industrial property?

    🌏 International

    4. Australia
    Whether weak transaction volumes persist even if prices remain relatively resilient.

    5. UK
    Whether increased housing supply eventually translates into more realistic pricing.


    💡 MIICHAEL’S TAKEAWAY

    This week gives us five very different property stories.

    Housing affordability.
    Industrial land strategy.
    Corporate property investment.
    Australia’s transaction slowdown.
    UK supply and pricing.

    And that’s exactly why I don’t believe we should talk about “the property market” as though it is one single thing.

    Different sectors behave differently.

    Different locations behave differently.

    And most importantly, different buyers have different problems.

    For someone buying a home, financing and affordability may matter most.

    For an investor, rental income and liquidity may matter more.

    For a developer, land cost, product positioning and absorption may determine success.

    And for a corporate investor, property may simply be another asset class for diversification.

    So perhaps the better question isn’t:

    “Is property a good investment?”

    It is:

    “Which property, in which location, for what purpose — and under what market conditions?”

    That is where better property decisions begin.

    Miichael Yeoh

    Property Strategist

  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    Week in Review | 22–28 August 2026

    Hi Everyone.

    This week’s property market highlights show one clear trend: the future value of property is increasingly being shaped by infrastructure, digital investment and the quality of the surrounding ecosystem.

    Here are the Top 5 developments that caught my attention.

    Looking down onto KLCC

    1. Data centres are redefining land value

    Mah Sing agreed to sell 78.8 acres of land at Southville City, Selangor, for approximately RM617.9 million to an international digital infrastructure group for data-centre development.

    Why it matters

    Land is no longer valued only for residential or commercial potential. Power capacity, fibre connectivity and digital infrastructure are becoming major value drivers.

    Miichael’s Review

    The real opportunity isn’t owning a data centre—it’s identifying the surrounding locations that will benefit from the jobs, businesses and ecosystem that follow.

    Aerial and ground view of high-voltage transmission towers in rural Malaysia, showing electricity infrastructure and power distribution network under bright sky.

    2. PJ Quarter brings new life to an established township

    Frasers Property and Tan & Tan announced PJ Quarter, a 5.15-hectare mixed-use redevelopment in Section 13, Petaling Jaya, integrating homes, retail, parks and community spaces.

    Why it matters

    This is a classic example of urban regeneration—creating value by improving the overall neighbourhood rather than simply building another project.

    Miichael’s Review

    A great location is more than an address. Sustainable value comes from the ecosystem around it: transport, education, healthcare, employment and lifestyle.

    Kepong New Condo Property Development | M Nova

    3. Malaysia’s industrial economy continues to support property demand

    Manufacturing and advanced industries continue to strengthen Malaysia’s investment landscape, particularly in Penang and key industrial corridors, reinforcing long-term demand for industrial and supporting residential property.

    Miichael’s Review

    Economic growth creates opportunities—but not every property benefits equally. Follow where employment and business investment are genuinely expanding.

    Johor Manufacturing - BizVantage 360 Malaysia

    4. Buyers are becoming more selective

    Developers and analysts continue to observe that today’s buyers are taking longer to make decisions, comparing projects more carefully and placing greater emphasis on affordability and long-term value.

    Miichael’s Review

    This is a healthy change. Instead of asking “Which project is the hottest?” buyers are beginning to ask “Which property makes the most sense for me?”

    Married couple reading carefully contract terms of conditions.

    5. The definition of property opportunity is changing

    Across this week’s stories, one message stands out: value is increasingly created by connectivity, infrastructure, regulation and economic activity, not simply by location alone.

    Miichael’s Review

    I believe the next successful property investor will not be the one who buys the most properties.

    It will be the one who understands why demand will exist five to ten years from now.

    Exploring the MRT Putrajaya : All you need to know about MRT Putrajaya in 2025! | PropertyGenie

    👀 Worth Watching

    I’ll be watching three areas over the coming weeks:

    • Growth of Malaysia’s digital infrastructure ecosystem
    • New urban regeneration projects in mature townships
    • Industrial investment creating new residential demand

    🎯 My Takeaway This Week

    The biggest lesson from this week is simple:

    Don’t just evaluate the property. Evaluate the ecosystem that supports it.

    Infrastructure, employment, connectivity and community are becoming the real foundations of long-term property value.

    That’s where better property decisions begin.

    Miichael Yeoh

    PROPERTY STRATEGIST

  • Am I buying the right property?

    Am I buying the right property?

    Why Some Penang Properties Generate Strong Rental Income While Others Struggle

    Over the years, I’ve met many property investors who ask me the same question:

    “Miichael, which property should I buy?”

    My answer is usually the same.

    The better question is:

    “Why do some properties perform better than others?”

    Today, Penang continues to be one of Malaysia’s most attractive destinations. People come here for the food, culture, medical tourism, business opportunities, education, and lifestyle.

    As tourism and visitor arrivals continue to grow, so does the demand for short-term accommodation.

    This has created exciting opportunities for property investors.

    However, here’s something many people overlook.

    Not every property benefits equally.

    I’ve seen investors buy properties in popular locations only to discover that rental demand wasn’t as strong as expected.

    I’ve also seen investors achieve impressive returns because they understood something others missed.

    The difference often comes down to understanding the numbers.

    Location matters.

    Demand matters.

    Timing matters.

    What do ADR (Average Daily Rate) and occupancy rates really tell us?

    But perhaps most importantly, understanding rental data matters.

    How do you identify an area before prices start moving?

    How do you distinguish between a property that looks good and a property that actually performs well?

    These are the questions every investor should be asking.

    Another common misconception is that you need a large amount of capital to invest successfully.

    While capital helps, I’ve seen many investors structure their purchases intelligently through financing strategies, proper planning, and understanding market opportunities.

    Sometimes it’s not about how much money you have.

    It’s about how well you use it.

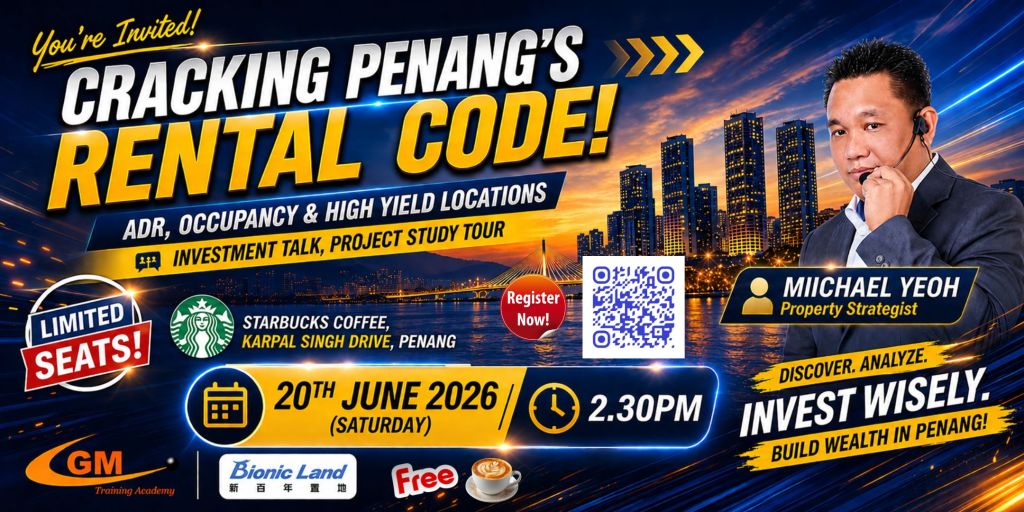
    That’s why I’ve decided to host a small-group sharing session in Penang where I’ll be revealing some of my latest research and observations on the rental market.

    We’ll discuss:

    ✔️ Insights from Penang’s Short-Term Rental Surge

    ✔️ How to identify high-yield property trends and focus areas

    ✔️ How to spot the right location before prices move

    ✔️ Understanding ADR, occupancy rates and real rental numbers

    ✔️ Building a profitable short-term rental strategy

    ✔️ Low-capital strategies that may help investors improve their returns

    Most importantly, this won’t be a typical seminar.

    We’ll be having discussions over coffee in a relaxed setting where you can ask questions and exchange ideas with fellow investors.

    Participants will also be invited to join an exclusive Property Study Tour to further enhance their understanding of location, demand drivers, and market opportunities.

    If you’re serious about understanding where Penang’s rental market is heading and how to position yourself for future opportunities, I believe you’ll find this session valuable.

    Event Details

    📅 Date: 20 June 2026 (Saturday)

    🕒 Time: 2:30 PM

    📍 Venue: Starbucks Coffee, Karpal Singh Drive, Penang

    ☕ Complimentary drink provided

    Seats are intentionally limited to ensure meaningful interaction and discussion.

    Register here: https://miichaelyeoh.com/event-page/

    I look forward to meeting you personally.

    — Miichael Yeoh

    Property Strategist | Developer Consultant | HRD Corp Certified Trainer
    Disclaimer: This reflects the author’s personal views based on market experience and current observations. It is not financial advice. Smart investors do their own research before making any move.

  • Property Is Still Alive — But the Game Has Changed

    Property Is Still Alive — But the Game Has Changed

    Buying a property today is very different compared to 10 or 20 years ago.

    Back then, property could sell very easily.
    Developers launched, buyers queued, and decisions were made quickly.

    Today, the world has changed.

    The way people buy property has changed.
    The way markets behave has changed.
    And more importantly, the way buyers think has changed.

    Buyers today are far more informed.

    Before even paying a booking fee, many would have already:

    • Compared multiple projects
    • Studied pricing trends
    • Checked developer track record
    • Analysed location fundamentals
    • Calculated loan eligibility and cash flow

    In other words, today’s buyers are not just buyers — they are researchers.


    At the same time, the global environment is not exactly calm.

    We are seeing ongoing geopolitical tensions — from the US–Iran situation to instability in parts of the Middle East.
    Interest rates, inflation, and currency movements continue to shift.

    All these create one thing: uncertainty.

    And when uncertainty comes in, market behaviour changes.

    From what I observe in today’s property market:

    • Investors are waiting — not exiting
    • Sellers are holding — not reducing
    • Buyers are selective — not absent

    Let that sink in.

    The market is not dead.
    It is simply… more cautious.


    And here is something many people miss:

    👉 When the market is not stable, that is where the opportunity lies.

    Why?

    Because:

    • Less emotional buying
    • More rational pricing
    • More room for negotiation
    • More time to analyse properly

    In a hot market, people chase.
    In a cautious market, people choose.

    And those who choose well, win.


    This is exactly why I started focusing on Property Market Intelligence.

    Not just looking at property as a product,
    but understanding:

    • Market timing
    • Buyer psychology
    • Financing structure
    • Exit strategy
    • Risk positioning

    This approach is built from more than 25 years in the property and banking industry.

    I have gone through multiple market cycles:

    • Asian Financial Crisis
    • Global Financial Crisis
    • Property slowdowns
    • Policy changes
    • And shifting buyer behaviours across decades

    Every cycle teaches one thing:

    👉 The market will always move — but not everyone moves with it.


    Today, success in property is no longer about:
    “Buy and wait.”

    It is about:
    “Buy with clarity.”

    Because in today’s market:

    • Information is everywhere
    • But insight is rare

    If you are buying today, don’t just ask:

    “Is this a good property?”

    Ask instead:

    • Who will buy from me later?
    • What is the demand driver here?
    • How does financing affect my holding power?
    • What happens if the market stays slow for 3–5 years?

    That is how professionals think.


    The market has not disappeared.

    It has simply matured.

    And in a mature market,
    strategy will always beat impulse.


    Miichael Yeoh
    Property Strategist | Author

    Author of:
    Think Like a Banker, Act Like a Player
    Property Investment BLT
    Buying Property Like a Pro (MPH Bestseller)

  • How AI Is Reshaping the Way We Buy Property

    How AI Is Reshaping the Way We Buy Property

    In today’s digital world, buying property is no longer just about location, price, and site visits. Artificial Intelligence (AI) is quietly influencing how buyers think, search, and eventually make decisions.

    Whether you realize it or not, AI is already part of your property journey.


    1. How AI Affects Our Buying Decisions

    AI has changed the way we consume information.

    In the past, buyers relied on agents, brochures, and physical visits. Today, what you see online is curated based on your behavior:

    • What you search
    • What you click
    • What you watch

    Over time, AI builds a profile of your preferences and starts feeding you properties that match your interest.

    Many buyers feel like they “found” the property themselves.

    But in reality, AI has already filtered the options for you.


    2. Property Marketing vs Other Products — Same Model, Different Weight

    From my experience, property marketing is not very different from other products.

    It follows a similar digital marketing structure.

    But the difference is this:

    👉 Property is a high-value, long-term commitment

    You are not buying something for RM1. You are committing hundreds of thousands or even millions.

    Because of that, the marketing is designed to:

    • Build trust
    • Educate
    • Reassure
    • Reduce risk

    It is less about pushing a sale, and more about guiding a decision.


    3. The Sales Funnel Is Always There

    Every product follows a sales funnel.

    Some marketers execute it well. Some only do part of it. Some only focus on getting attention.

    In property, you will typically go through stages like:

    • Seeing ads
    • Clicking to learn more
    • Registering interest
    • Communicating with salespeople
    • Visiting or evaluating

    Whether you notice it or not, you are being guided step by step.


    4. “Why Am I Suddenly Seeing Property Ads Everywhere?”

    This is something many people experience.

    You talk to a friend about buying property… You search a few listings…

    Next thing you know, when you open Facebook or Instagram:

    👉 Property ads start appearing everywhere.

    This is how AI and digital tracking work.

    It picks up signals from your behavior and starts showing you more relevant content.

    It is not magic — it is data.


    5. The Moment You Click, Your Journey Changes

    Once you click on an ad, your journey becomes more intentional.

    You may start seeing:

    • More related ads
    • Follow-up messages
    • Invitations to previews
    • Additional information and content

    This is how modern property marketing works today.


    6. Not All Campaigns Are the Same

    The experience you get depends on the developer or salesperson.

    Some are very basic. Some are more structured and consistent.

    But regardless of how advanced the system is, one thing remains the same:

    👉 The final decision is still yours.


    7. My Perspective as a Property Buyer

    From my own experience in property, one thing is very clear:

    👉 We cannot avoid AI.

    It is already part of how information is delivered to us.

    But here is the part many people overlook:

    AI can influence your interest, but it should not replace your judgment.

    At the end of the day:

    • You are not buying a cheap product
    • You are committing significant capital
    • You are making a long-term financial decision

    Because of that, buyers must still:

    ✔ Do proper research ✔ Understand the numbers ✔ Assess their holding power ✔ Evaluate the location and fundamentals

    And most importantly:

    👉 Listen to people who have real experience in property

    Not everything online tells the full story.


    Final Thoughts

    AI is a powerful tool.

    It can help you discover opportunities faster. It can guide you through options you may not have seen before.

    But it should never replace:

    • Due diligence
    • Critical thinking
    • Experience-based advice

    In property, the difference between a good decision and a bad one is not the advertisement you saw…

    It is the quality of the decision you make after that.

    At the end of the day, AI may influence what you see…

    But it should never replace how you think.

    Property is not a small purchase.
    It’s a long-term financial commitment.

    The difference is not in the advertisement you saw —
    It’s in the decision you make after that.

    Make sure it’s a well-informed one

    From the Desk of

    Miichael Yeoh

    Property Strategist | Author

    Author of:

    Think Like a Banker, Act Like a Player

    Property Investment BLT Buying

    Property Like a Pro (MPH Bestseller)

    P.S. Follow for consistent, experience-based property insights — beyond what marketing tells you.

  • Think Like a Banker Before You Buy Property

    Think Like a Banker Before You Buy Property

    One thing I learned from working closely with banks is this:

    Banks are extremely careful before approving a property loan.

    They analyse risks, stress-test your finances, and study whether you can survive difficult situations.

    But here’s the irony.

    Many property buyers don’t analyse their purchase the same way.

    They look at the show unit.
    They listen to marketing promises.
    They follow what others are buying.

    But they rarely ask the same questions a banker would ask.

    If you want to invest in property wisely, start by thinking like a banker.

    Here are three things bankers always analyse.


    1️⃣ Debt Ratio – Are You Stretching Yourself Too Thin?

    Banks look closely at your Debt Service Ratio (DSR).

    This measures how much of your income is used to pay debts.

    Even if a bank approves your loan, you should still ask yourself:

    • What happens if interest rates increase?
    • What if my income drops temporarily?
    • Will I still feel comfortable servicing the loan?

    A property might look affordable today.

    But bankers always plan for tomorrow’s risks.


    2️⃣ Holding Power – Can You Hold Through Market Cycles?

    Property markets don’t always go up.

    There will be slow periods.

    Bankers evaluate whether a borrower has the financial strength to continue paying during tough times.

    Smart investors should ask:

    • Can I hold this property for 5–10 years if needed?
    • Do I have cash reserves?
    • What if the market takes longer to recover?

    Many investors fail not because they bought the wrong property…

    They fail because they cannot hold it long enough.


    3️⃣ Rental Sustainability – Can the Property Support Itself?

    Another banker mindset is income sustainability.

    Before buying, ask:

    • Is there real rental demand here?
    • Who are the potential tenants?
    • Can the rental help support the loan?

    A strong investment property should ideally generate rental income that supports part of the financing.

    This reduces pressure and improves long-term stability.


    Final Thought

    Successful property investors don’t buy emotionally.

    They evaluate property like a banker evaluating risk.

    Before your next purchase, ask yourself:

    Does this property pass the banker’s test?

    When you start thinking like a banker, you don’t just buy property.

    You build a stronger and safer property portfolio.


    Miichael Yeoh
    Property Strategist | Developer Consultant | Investment & Mortgage Expert
    Author of Think Like a Banker, Act Like a Player

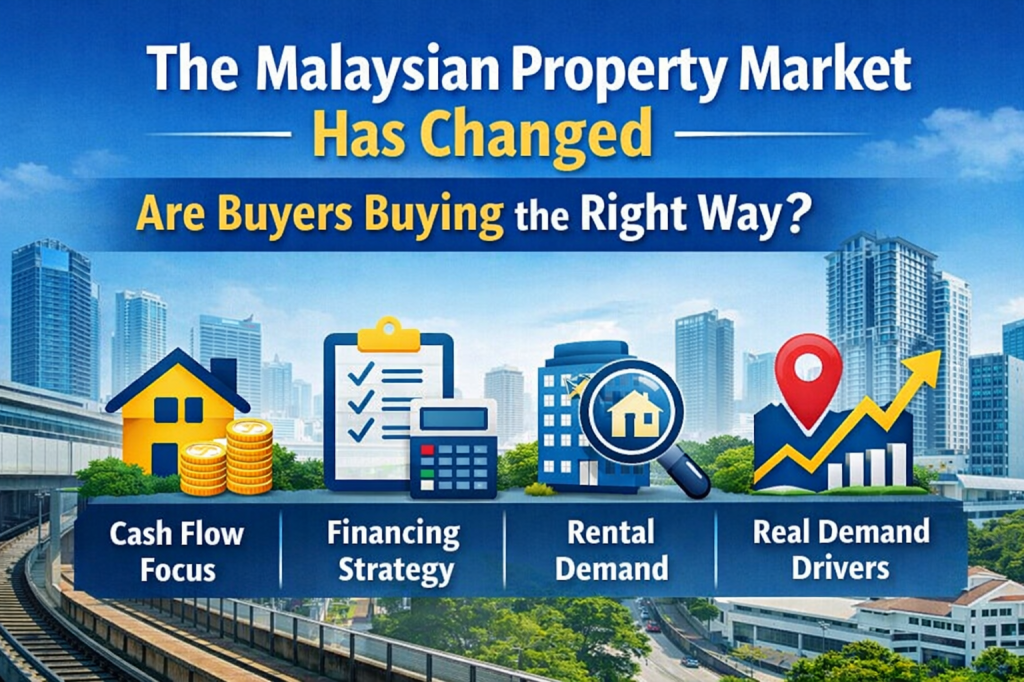
  • The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?

    The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?

    The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?

    For many years, property investing in Malaysia followed a familiar formula.

    Buy a new launch, wait a few years, and hope the price goes up.

    This strategy worked reasonably well during earlier property cycles when prices were rising quickly, financing was easier, and supply was more limited. Many investors entered the market believing that capital appreciation alone would justify the purchase.

    But today, the Malaysian property market has entered a different phase.

    The question buyers should now ask is no longer “Will the price go up?”
    The more important question is “Can this property sustain itself financially?”


    The Shift From Speculation to Sustainability

    Over the past decade, the mindset of property buyers has gradually evolved.

    Today’s buyers are more cautious, more analytical, and more focused on cash flow and long-term holding power.

    Instead of relying purely on future price appreciation, investors are increasingly asking questions such as:

    • What is the rental demand in this area?
    • Can the rental cover most of the loan instalment?
    • What happens if interest rates increase?
    • Who is the actual tenant profile for this property?

    These questions reflect a more mature approach to property investing.

    The reality is simple: not every property will appreciate significantly in the short term. When appreciation slows, the ability of the property to generate rental income becomes far more important.


    Financing Strategy Now Matters More Than Ever

    Another major shift in the market is the growing importance of financing structure.

    Many buyers focus heavily on the purchase price but pay little attention to how the property is financed. Yet the financing strategy can determine whether an investment becomes manageable or financially stressful.

    Buyers today need to consider:

    • Loan margin and interest rates
    • Monthly instalment affordability
    • Holding power during market slowdowns
    • Overall debt exposure

    A well-structured loan can give investors time and flexibility, while poor financial planning can force them to sell prematurely.

    Thinking about financing before buying is no longer optional — it is essential.


    Rental Demand Is Becoming a Key Decision Factor

    One of the biggest mistakes many investors made in the past was buying properties without considering who would actually rent the unit.

    Today, buyers are beginning to look more closely at demand drivers such as:

    • Proximity to employment hubs
    • Accessibility and transportation infrastructure
    • Nearby universities or hospitals
    • Tourism demand and short-term rental potential

    In markets like Penang, Kuala Lumpur, and Johor Bahru, rental demand is increasingly shaping investment decisions.

    For example, areas with strong tourism activity or major infrastructure developments may offer better rental prospects compared to purely speculative locations.

    The key question investors should ask is:

    “Who is my tenant?”

    If there is no clear answer, the investment may not perform as expected.


    The Role of Infrastructure and Economic Drivers

    Another important factor influencing property performance today is real economic activity.

    Infrastructure projects, transportation connectivity, employment centres, and tourism growth can significantly impact both rental demand and long-term property value.

    For instance, upcoming transportation developments and urban revitalisation projects in cities such as Georgetown could change demand patterns in the coming years.

    However, infrastructure alone does not guarantee success. The surrounding ecosystem — population growth, business activity, and lifestyle demand — must also support the property market.


    Buying Property Today Requires a Different Mindset

    The Malaysian property market has not disappeared. But the way buyers approach property must evolve.

    Successful investors today tend to follow a more balanced approach:

    • Evaluate rental yield and cash flow
    • Structure financing carefully
    • Understand real demand drivers
    • Focus on long-term sustainability

    In other words, the focus has shifted from short-term speculation to long-term investment discipline.


    A Final Thought

    Property has always been a long-term asset class.

    But in today’s market environment, buying property requires more than just optimism about future price growth.

    It requires careful thinking, realistic financial planning, and a clear understanding of market demand.

    The Malaysian property market has changed.

    The real question is — have buyers changed with it?


    Miichael Yeoh
    Property Strategist | Developer Consultant | HRD Corp Trainer

    Miichael Yeoh has more than 28 years of experience spanning banking, mortgage advisory, property investment, and developer consultancy. He is also the author of Think Like a Banker, Act Like a Player, Property Investment BLT, and Buying Property Like A Pro.

  • Property Refinancing in Malaysia

    Property Refinancing in Malaysia

    New Rules, Regulations & When Refinancing Actually Makes Sense

    Over the years, refinancing has been one of the most powerful financial tools for Malaysian homeowners and property investors. Used correctly, it can improve cash flow, reduce interest costs, or unlock equity for smarter investments.

    However, recent regulatory changes by Bank Negara Malaysia (BNM) mean refinancing is no longer as straightforward as before — especially when it involves cash-out.

    If you’re considering refinancing your property in 2025 or beyond, here’s what you must understand before making a move.


    What Is Property Refinancing?

    Property refinancing simply means replacing your existing home loan with a new loan, usually with another bank, based on your property’s current market value.

    Homeowners typically refinance to:

    • Get a lower interest rate
    • Reduce monthly instalments
    • Adjust loan tenure
    • Access cash from accumulated property equity
    • Consolidate high-interest debts

    The strategy itself hasn’t changed — the rules have.


    What’s New? Key Refinancing Rules You Must Know

    1. Cash-Out Refinancing Is Now More Restrictive

    One of the biggest changes affects cash-out refinancing.

    If you refinance and take extra cash for personal use (such as lifestyle spending, personal debts, or non-income-generating purposes), that portion may now be treated as personal financing, not a housing loan.

    👉 Key impact:

    • The cash-out portion may be capped at a maximum repayment tenure of 10 years
    • Monthly instalments will be significantly higher compared to spreading it over 30–35 years

    This is a major shift. In the past, many borrowers stretched cash-out amounts across the full home loan tenure, keeping instalments low but debt long.


    2. Stronger Affordability & DSR Checks

    Banks are now applying stricter Debt Service Ratio (DSR) assessments, especially for:

    • Multiple property owners
    • Refinancing with cash-out
    • Borrowers with existing personal loans or credit card balances

    Even if your property value has increased, approval is no longer guaranteed if your cash flow doesn’t support the new repayment structure.


    3. More Transparency on Loan Costs

    BNM has reinforced rules to ensure:

    • Clear disclosure of effective interest rates
    • Transparent breakdown of total repayment costs
    • Fair interest calculations based on reducing balance, not outdated methods

    This protects borrowers — but it also means banks are less flexible with “creative structuring”.


    Why Did Bank Negara Tighten Refinancing Rules?

    The objective is simple: reduce unhealthy household debt behaviour.

    Over the years, many Malaysians:

    • Used refinancing repeatedly for lifestyle spending
    • Rolled short-term debts into long-term housing loans
    • Focused on “low monthly instalment” instead of total debt impact

    The new rules encourage:

    • Responsible borrowing
    • Better financial planning
    • Using refinancing for productive purposes, not emotional decisions

    So… Why Should You Refinance a Property?

    Refinancing still makes sense — if done for the right reasons.

    1. To Lower Your Interest Rate

    If your current loan is:

    • On an old package
    • Above current market rates

    Refinancing can reduce:

    • Monthly instalments
    • Total interest paid over the loan tenure

    This is the cleanest and safest reason to refinance.


    2. To Improve Monthly Cash Flow

    Some homeowners refinance to:

    • Extend tenure
    • Reduce instalments
    • Create breathing space for cash flow

    This can be helpful during:

    • Business expansion
    • Income transition
    • Temporary financial tightening

    However, it must be done strategically, not emotionally.


    3. To Access Equity for Income-Producing Purposes

    This is where refinancing still shines — when the cash is used productively, such as:

    • Renovating a rental property
    • Funding another investment
    • Business expansion with clear returns

    Banks are generally more supportive when refinancing is tied to income generation, not consumption.


    4. Debt Consolidation (With Caution)

    Refinancing to clear:

    • Credit cards
    • Personal loans

    can reduce interest costs if discipline improves after refinancing.

    If spending habits remain unchanged, refinancing only delays the problem.


    5. To Restructure Your Property Portfolio

    For investors, refinancing can be used to:

    • Optimise loan structure across multiple properties
    • Release equity to rebalance portfolio risk
    • Improve overall holding power

    This requires proper planning — not just chasing approval.


    What You Should Consider Before Refinancing

    Before signing anything, ask yourself:

    ✔ Does refinancing truly save money after legal & valuation costs?
    ✔ Can I comfortably afford repayments if cash-out tenure is shorter?
    ✔ Am I refinancing for strategy — or short-term relief?
    ✔ Does this move strengthen my financial position 5–10 years from now?

    Refinancing is a tool. Used correctly, it builds wealth. Used wrongly, it creates silent financial stress.


    Final Thoughts from Miichael

    In today’s environment, refinancing is no longer about “how much cash can I take out”.

    The real question is:

    Does this refinancing decision improve my financial position — or just make today easier at tomorrow’s expense?

    With tighter rules in place, planning matters more than approval.

    If you’re unsure whether refinancing makes sense for your situation, get proper advice before committing. The cost of a wrong decision today can take years to undo.

  • Residential Property & Mortgage Trends in Malaysia (2026 and beyond)

    Residential Property & Mortgage Trends in Malaysia (2026 and beyond)

    By Miichael Yeoh

    The Malaysian property market has been through a lot in the last few years — pandemic, inflation, rising construction costs, slow wage growth, and changing buyer behaviour. But as we step into 2025, one thing is clear:

    Property is still moving… but the market is no longer the same.
    Buyers are more cautious, banks are more selective, and affordability remains a major issue.

    Here’s my take on what’s really happening in the residential property and mortgage landscape, and what you should pay attention to — especially if you’re planning to buy, invest, or restructure your loans.


    📈 Long-Term Price Trend: Property Still Moves Up

    Whether the market is “good” or “bad”, one fact remains consistent:

    Property prices in Malaysia have been rising steadily for the last 20+ years.

    Urban areas like Klang Valley, Penang and Johor consistently show appreciation because of:

    • population growth
    • job concentration
    • infrastructure development
    • scarcity of prime land

    But here’s the catch:
    House prices have risen much faster than income, making affordability the No.1 challenge for Malaysians today.

    This explains why many young buyers are stuck deciding between renting longer… or compromising on location and size.


    🏘️ What’s Happening in the Market Now?

    1. Transaction volume is rising — but buyers are choosy

    2024 recorded strong growth in overall property transactions, and 2025 is projected to see single-digit positive growth.
    People are buying — but not blindly.

    Buyers today compare:

    • price per sq ft
    • rental potential
    • exit value
    • access to MRT / LRT
    • developer reputation

    Gone are the days when anything “new launch” can sell out.
    Today, value matters more than hype.


    💰 Mortgage & Financing Trend: Here’s the Real Story

    The biggest shift recently is OPR dropping to 2.75%, making borrowing cheaper.

    This directly means:

    • Lower monthly instalments
    • Higher loan eligibility
    • Better cashflow for investors

    But with great news comes reality…
    Banks are approving loans more carefully than ever.

    Your CCRIS, CTOS, commitments and even gig-income consistency matter.
    If your financial health is not clean, even a low OPR won’t help you.

    For many Malaysians, the challenge isn’t interest rate — it’s getting the loan approved.


    🧱 Supply vs Demand: The Affordable Gap

    You’re hearing this everywhere:

    “So many houses unsold!”
    —but at the same time—
    “I can’t find any home I can afford!”

    Why?
    Because the overhang is mainly:

    • too expensive for the mass market
    • too big (1,000 sq ft and above)
    • wrong location

    This mismatch will continue unless developers pivot more aggressively into the mid-market segment.


    🧭 What Buyers & Investors Should Look At Now

    ✔️ If you’re a first-time buyer

    This is a golden window.
    Low OPR + many choices + developers offering incentives = value for money.

    Look for:

    • good location > big size
    • future MRT/LRT corridors
    • reputable developers
    • high rental demand areas

    ✔️ If you’re an investor

    Capital gain will still happen — but don’t expect overnight appreciation.
    Focus on:

    • rental yield
    • undervalued areas
    • distress or motivated sellers
    • T.O.P. projects with ready tenants

    The smart investors in 2025 are not speculating.
    They’re buying below market value, or in growth corridors, or early in new infrastructure zones.

    ✔️ If you own multiple properties with loans

    This is the best time to:

    • refinance
    • consolidate debts
    • reset your cashflow
    • restructure your portfolio

    A small adjustment in interest rate can save thousands per year.


    🧩 Conclusion: The Market Isn’t Booming, But It’s Moving

    Malaysia’s residential market today is stable, resilient, and buyer-driven.
    We’re not in a bubble.
    We’re not in a crash.

    We’re in a value-driven market, where the winners are:
    ✔️ informed buyers
    ✔️ strategic investors
    ✔️ those who manage their loans wisely

    If you understand the trends — and you know how to analyse value correctly — 2025-2026 can be a very profitable year for you.

  • The Property Guru Trap: How to Separate Education from Marketing

    The Property Guru Trap: How to Separate Education from Marketing

    By Miichael Yeoh


    Let’s be honest.

    Today, the property industry is noisier than ever. Everywhere you look — social media, webinars, billboards, YouTube ads — there’s a new “property guru” promising fast riches, zero-risk investments, and financial freedom in record time.

    The problem? Most Malaysians are not confused because property is complicated. They’re confused because they are overloaded with marketing disguised as education.

    And that’s where many fall into what I call The Property Guru Trap.


    When Marketing Pretends to Be Education

    Here’s the uncomfortable truth: not all property educators are educators. Many are simply excellent marketers.

    Their formula is simple:

    • Showcase luxury lifestyle
    • Highlight “student success” without context
    • Push urgency: Buy now or miss out forever
    • Sell emotion, not strategy

    You’re not being taught how to think. You’re being told what to buy.

    Real education gives you clarity. Marketing creates pressure. One empowers. The other manipulates.


    A Real Story I See Too Often

    Just last year, a couple in their early 30s came to me after attending my property seminar. They had purchased three so-called “hot projects” based on hype incentives.

    On paper, it looked attractive. In reality:

    • Both units were negative cashflow
    • Rental demand was weak
    • Their monthly commitments were choking their lifestyle

    They weren’t irresponsible. They were simply following loud voices instead of clear frameworks.

    And sadly, this is becoming the norm — not the exception.


    The Real Cost of Following the Wrong Advice

    I’ve met too many people who:

    • Bought units with negative cashflow
    • Overleveraged based on “hot tips”
    • Ended up with properties that can’t be rented
    • Are stuck servicing loans that don’t perform

    Not because they were careless — but because they trusted confidently delivered advice without understanding the fundamentals.

    A true educator helps you analyze. A salesperson helps you justify.

    There is a difference.


    How to Tell If You’re Learning or Being Sold To

    ✅ Real Education Will:

    • Teach you how to calculate ROI, yield, and risk
    • Help you understand bank approval logic
    • Show both pros AND cons of a deal
    • Focus on your personal financial situation
    • Encourage long-term thinking

    🚩 Pure Marketing Will:

    • Avoid numbers and focus on hype
    • “Guaranteed rental must make sense”
    • Emphasize lifestyle more than strategy
    • Create fear of missing out
    • Push for immediate commitment

    If the main goal is to close you fast — it’s not education. It’s sales.


    Property Success Is Built on Structure, Not Excitement

    Smart investors don’t rely on tips. They rely on process.

    They understand:

    • Why banks approve or reject loans
    • How debt strategy impacts long-term wealth
    • The difference between speculation and investment
    • That timing alone doesn’t beat fundamentals

    This is why structured learning matters. Not a weekend motivation high — but a system that builds independent decision-makers.


    The Role of a Real Property Educator

    A real educator doesn’t create dependency. They create capability.

    You should walk away able to:

    • Analyse any project yourself
    • Question assumptions
    • Say NO to bad deals
    • Build a property plan based on your life goals, not someone else’s wins

    Because the ultimate goal is not to follow a guru. It is to become your own strategist.


    My Commitment to Property Education

    For over a decade, my focus has never been about selling you a project. It has always been about equipping you with a framework:

    • A banker’s mindset to assess risk
    • An investor’s eye to spot opportunity
    • A player’s strategy to move smartly in the real world

    Property is a powerful wealth tool — but only when approached with clarity, structure, and knowledge.

    Not hype. Not shortcuts. Not empty promises.


    Final Thought

    Before you follow any advice, ask yourself:

    “Am I being educated — or am I being persuaded?”

    The moment you learn to differentiate the two, you stop being a follower… And start becoming a true property investor.


    Property Matching: The Missing Link Most Gurus Ignore

    One of the biggest differences between real education and marketing is this:

    Marketing pushes projects. Education focuses on property matching.

    Property matching means selecting a property based on who YOU are — not what the developer wants to sell.

    It considers:

    • Your income structure
    • Your existing commitments
    • Your risk profile
    • Your investment timeline
    • Your cashflow capability
    • Your long-term objectives

    Instead of asking: “Which project is hot now?”

    The right question is: “Which property fits my current financial position and future strategy?”

    This is exactly why many buyers end up stressed. They buy what is popular — not what is suitable.

    A proper property matching process helps you:

    • Avoid overcommitting
    • Prevent loan rejection issues
    • Choose units with realistic rental demand
    • Align property type with your wealth plan

    There is no such thing as a universally good property. Only a property that is good for the RIGHT person.

    And this step is often skipped in high-pressure sales environments — because matching takes time, analysis, and honesty.

    That’s not convenient for fast sales. But it is essential for sustainable investing.


    Ready to Learn Property the Right Way?

    If you’re serious about building wealth through property — not just buying based on emotion — then it’s time to approach it with strategy.

    ✅ Learn how banks really assess your loan ✅ Understand cashflow before committing ✅ Build a property roadmap aligned to your life goals

    Join my upcoming property programme or consultation session and start making decisions with clarity, not pressure.

    Because wealth is not built on motivation. It is built on informed decisions.

  • Boost Your Loan Approval Chances in Malaysia

    Boost Your Loan Approval Chances in Malaysia

    Malaysian bank lending (especially for property purchases) is currently shaped by several key monetary, regulatory, and market-demand factors. Rates have been easing somewhat, but approval conditions remain cautious. Below are the latest numbers and trends.


    Current Figures & Trends

    1. Overnight Policy Rate (OPR) & Reference Rates
      • In July 2025, Bank Negara Malaysia (BNM) cut the OPR from 3.00% to 2.75% – the first cut in five years.
      • Major banks have adjusted their Standardised Base Rate (SBR) to 2.75% per annum following the OPR cut.
      • Base Rate (BR) has also been adjusted (for many banks) in line with this, though BR tends to be higher than SBR. For example, Alliance Bank’s BR is about 3.57%.
    2. Base Lending Rate / Base Financing Rate (BLR/BFR)
      • The BLR or BFR (for Islamic financings) for many banks remains in the ~6.35% to ~6.65% range. For example, Maybank’s BLR is 6.40%, Hong Leong Bank’s is ~6.64%, etc. baserate.my+3Maybank2u+3NewPages+3
    3. Effective Housing Loan Rates
      • While the base/reference rates give a starting point, effective lending rates (what borrowers actually pay) tend to be higher because banks add a margin/spread depending on risk, loan amount, tenure, etc.
      • Recent reports suggest effective rates for housing loans are in many cases 4.15% to 5.7% p.a. depending on bank, borrower profile, loan value, promotion, etc. Property Genie
    4. Loan Approval & Volume
      • There was a 25.7% month-on-month increase in approvals of housing-loan applications in July 2025 after a slump in June. Focus Malaysia – Business & Beyond
      • The approval ratio (i.e. approved vs applied) in July 2025 was about 44.8%, up from ~42.6% in June 2025. Focus Malaysia – Business & Beyond
      • On a year-on-year basis, total approved loan volume declined by ~5.1% for that month; cumulatively over the first 7 months of 2025, approved property loans were ~RM 161.4 billion, about -1.5% relative to same period in previous year. Focus Malaysia – Business & Beyond
    5. Outlook
      • With lower OPR and more competitive base/reference rates, there is optimism that loan approvals (both volume and ratio) may improve in the remaining months of 2025. Government’s likely to include incentives in Budget 2026 to support first-time buyers, low-to-middle income groups. Focus Malaysia – Business & Beyond

    Steps Borrowers Can Take to Increase Chances of Loan Approval

    Given the current environment, borrowers can do several things to strengthen their applications and improve likelihood of approval. Here are practical steps, both before and during application.

    StepWhat to DoWhy It Helps
    1. Check & Clean Up Your Credit HistoryObtain your credit report (e.g. through CTOS, CCRIS, Experian) ahead of time. Ensure there are no outstanding defaults, ensure credit card/HP payments are on time.Banks check creditworthiness; a clean credit history reduces risk and may allow you to access better rates.
    2. Assess Debt Service Ratio (DSR) / Total CommitmentsKnow your monthly obligations: other loans, credit cards, etc. Make sure your net income minus all obligations leaves enough room for loan instalments. Try to reduce existing liabilities if possible.Banks often reject or charge higher margins if your debts relative to income are too high. Lower commitments improves affordability assessment.
    3. Have Stable & Adequate IncomeDemonstrate consistent employment or business income; have documentation (pay slips, tax returns, EPF contributions). If self-employed or commission-based, provide past 2-3 years’ income statements, audited if possible.Stability & predictability of income give banks confidence in your ability to repay.
    4. Make Reasonable Down Payment / EquityThe more you put down (lower loan-to-value ratio), the less risk for the bank. If you’re first-time buyer programs exist (often requiring only 10% payment), check eligibility, but be aware these may still have stricter conditions.Less loan amount relative to property value helps bank exposure and reduces margin required.
    5. Choose Appropriate Loan TenureLonger tenure reduces monthly instalments but increases total interest paid; very long tenure may raise risk from bank’s perspective (future rate changes, income changes). Balance payroll constraints with ability to service.A manageable monthly repayment improves approval chances; less risk of default.
    6. Prepare All Supporting Documents ProperlyHave ready: identity documents, employment letters, income proof, EPF statements, tax returns (if applicable), bank statements, any other asset documentation. Ensure documents are current.It speeds up processing and reduces grounds for rejection due to missing information.
    7. Shop Around & Compare OffersDifferent banks have different margins, promotions, and underwriting criteria. Get multiple quotes. Negotiate (sometimes banks reduce spread or offer incentives).May get better rate, lower fees, more favorable terms.
    8. Provide Clear Purpose & Property DetailsHave the Sale & Purchase Agreement (SPA), valuation report (if needed), title deed, property details, etc. If property is new or under construction, ensure developer’s track record and required approvals are in order.Banks assess property risk as well: location, title, developer credibility affect approval.
    9. Maintain Good Savings / ReservesHaving savings or avoid fully depleting your accounts helps; having reserves gives cushion in case of rate increases or unexpected expenses.Shows financial discipline and lowers risk from bank’s viewpoint.
    10. Understand Bank Fees & RequirementsBe aware of legal fees, valuation fees, stamp duties, insurance (MRTA/MRTT), and any bank-specific requirements (e.g. guarantor, joint-applicant). Make sure to budget for them.Unexpected costs can derail the process; being well-prepared ensures smoother approval.

    Challenges & What Borrowers Should Watch Out For

    • Even with OPR at 2.75% and SBR adjusted, banks’ margins/spreads can still be high depending on borrower risk. So effective rates may still be less favourable for some.
    • Approval ratios (~44-47%) show that over half of applications still get declined. That means it’s not just about rates; credit & affordability are being closely scrutinized. Focus Malaysia – Business & Beyond
    • Rising costs for legal fees, valuation, and sometimes hidden fees can make total cost of financing higher than expected.
    • Inflation, future rate rises, economic uncertainties mean banks may reserve right to tighten conditions suddenly.


    Conclusion

    Bank lending is currently becoming somewhat more favourable in Malaysia thanks to the OPR cut and adjusted reference rates. However, borrowers must still present strong, well-prepared loan applications. Cleaning up credit, reducing existing obligations, having stable income and proper documentation, and choosing appropriate loan terms are all crucial.