As someone who has spent nearly three decades in banking, mortgage advisory and property strategy, one question I get repeatedly from investors and homebuyers is:
“Why did my bank increase (or educe) my interest rate when I didn’t change anything?”
The answer almost always traces back to one key number — the Overnight Policy Rate (OPR).
Let’s break down how OPR is derived, who decides it, and how it directly affects your housing loan, business financing, and even fixed deposits.
What Is OPR?
Bank Negara Malaysia (BNM) uses the Overnight Policy Rate (OPR) as its main monetary policy tool.
The OPR is the interest rate at which banks lend money to one another overnight. It serves as the benchmark rate that influences all other interest rates in the country.
Think of it as the “master switch” of Malaysia’s financial system.
How Is OPR Derived?
OPR is not randomly adjusted. It is decided by BNM’s Monetary Policy Committee (MPC) based on several key economic indicators:
1️⃣ Inflation (Price Stability)
If inflation is rising too quickly, BNM may increase OPR to slow down spending and borrowing. If inflation is low or the economy is weak, BNM may reduce OPR to stimulate growth.
2️⃣ Economic Growth (GDP)
Strong economic growth may lead to higher OPR to prevent overheating. Weak GDP growth may lead to lower OPR to encourage borrowing and investment.
3️⃣ Employment & Consumer Spending
High unemployment? Lower OPR to boost activity. Strong consumer demand? Possibly tighten policy.
4️⃣ Global Economic Conditions
US Federal Reserve rates, global trade trends, currency strength, and geopolitical risks all influence Malaysia’s monetary decisions.
5️⃣ Financial System Stability
BNM ensures banks remain liquid and stable. OPR adjustments help manage systemic risk.
In simple terms:
OPR balances growth and inflation.
How OPR Affects Banks’ Interest Rates
When OPR changes, banks adjust their benchmark rates such as:
BR (Base Rate)
SBR (Standardised Base Rate)
Most housing loans today are priced as:
SBR + Spread (e.g., SBR + 1.5%)
When OPR increases:
SBR increases
Monthly instalments increase
Loan affordability reduces
When OPR decreases:
SBR decreases
Monthly instalments reduce
Borrowing becomes cheaper
Example: How It Impacts a Housing Loan
Let’s say:
Loan: RM500,000
Tenure: 35 years
Rate: SBR 3.00% + 1.50% = 4.50%
If OPR increases by 0.25%:
SBR may rise to 3.25%
New rate becomes 4.75%
Monthly instalment increases
Even a 0.25% increase can mean thousands of ringgit extra over the loan tenure.
This is why property investors must monitor OPR closely.
Impact on Different Groups
🏠 Homeowners
Higher OPR = higher instalments (if on floating rate).
🏢 Property Investors
Rental yield may be squeezed if instalments rise but rental cannot increase proportionally.
💼 Businesses
Cost of financing increases, affecting expansion decisions.
💰 Savers
Good news — Fixed deposit rates usually improve when OPR rises.
Why OPR Matters in Property Strategy
As a developer consultant and property strategist, I always advise clients:
Don’t only calculate today’s instalment. Stress-test at +1% or +2%.
Markets move in cycles. OPR will not stay low forever.
Smart investors:
Lock in good spreads during low-rate environments
Structure debt efficiently
Maintain cash flow buffers
Final Thoughts
OPR is not just a technical banking term.
It is the heartbeat of the financial system, influencing property prices, loan affordability, rental yields, and overall market sentiment.
Understanding how it works allows you to:
Make better borrowing decisions
Time property acquisitions strategically
Structure financing intelligently
If you are planning your next property move, always ask:
“What is the interest rate cycle telling me?”
Because in property investing, Timing and financing strategy often matter more than price.
The Malaysian property market has been through a lot in the last few years — pandemic, inflation, rising construction costs, slow wage growth, and changing buyer behaviour. But as we step into 2025, one thing is clear:
Property is still moving… but the market is no longer the same. Buyers are more cautious, banks are more selective, and affordability remains a major issue.
Here’s my take on what’s really happening in the residential property and mortgage landscape, and what you should pay attention to — especially if you’re planning to buy, invest, or restructure your loans.
📈 Long-Term Price Trend: Property Still Moves Up
Whether the market is “good” or “bad”, one fact remains consistent:
Property prices in Malaysia have been rising steadily for the last 20+ years.
Urban areas like Klang Valley, Penang and Johor consistently show appreciation because of:
population growth
job concentration
infrastructure development
scarcity of prime land
But here’s the catch: House prices have risen much faster than income, making affordability the No.1 challenge for Malaysians today.
This explains why many young buyers are stuck deciding between renting longer… or compromising on location and size.
🏘️ What’s Happening in the Market Now?
1. Transaction volume is rising — but buyers are choosy
2024 recorded strong growth in overall property transactions, and 2025 is projected to see single-digit positive growth. People are buying — but not blindly.
Buyers today compare:
price per sq ft
rental potential
exit value
access to MRT / LRT
developer reputation
Gone are the days when anything “new launch” can sell out. Today, value matters more than hype.
💰 Mortgage & Financing Trend: Here’s the Real Story
The biggest shift recently is OPR dropping to 2.75%, making borrowing cheaper.
This directly means:
Lower monthly instalments
Higher loan eligibility
Better cashflow for investors
But with great news comes reality… Banks are approving loans more carefully than ever.
Your CCRIS, CTOS, commitments and even gig-income consistency matter. If your financial health is not clean, even a low OPR won’t help you.
For many Malaysians, the challenge isn’t interest rate — it’s getting the loan approved.
🧱 Supply vs Demand: The Affordable Gap
You’re hearing this everywhere:
“So many houses unsold!” —but at the same time— “I can’t find any home I can afford!”
Why? Because the overhang is mainly:
too expensive for the mass market
too big (1,000 sq ft and above)
wrong location
This mismatch will continue unless developers pivot more aggressively into the mid-market segment.
🧭 What Buyers & Investors Should Look At Now
✔️ If you’re a first-time buyer
This is a golden window. Low OPR + many choices + developers offering incentives = value for money.
Look for:
good location > big size
future MRT/LRT corridors
reputable developers
high rental demand areas
✔️ If you’re an investor
Capital gain will still happen — but don’t expect overnight appreciation. Focus on:
rental yield
undervalued areas
distress or motivated sellers
T.O.P. projects with ready tenants
The smart investors in 2025 are not speculating. They’re buying below market value, or in growth corridors, or early in new infrastructure zones.
✔️ If you own multiple properties with loans
This is the best time to:
refinance
consolidate debts
reset your cashflow
restructure your portfolio
A small adjustment in interest rate can save thousands per year.
🧩 Conclusion: The Market Isn’t Booming, But It’s Moving
Malaysia’s residential market today is stable, resilient, and buyer-driven. We’re not in a bubble. We’re not in a crash.
We’re in a value-driven market, where the winners are: ✔️ informed buyers ✔️ strategic investors ✔️ those who manage their loans wisely
If you understand the trends — and you know how to analyse value correctly — 2025-2026 can be a very profitable year for you.
The recent announcement by Housing and Local Government Minister Nga Kor Ming regarding the blacklisting of 109 housing developers is a significant step toward enhancing transparency and protecting homebuyers in Malaysia. By making this list publicly accessible on the ministry’s website, potential buyers can now verify the credibility of developers before making purchasing decisions.
This initiative is part of broader efforts to address issues related to abandoned projects and fraudulent practices in the housing sector. The proposed amendments to the Housing Development (Control and Licensing) Act 1966 aim to impose stricter penalties on errant developers, including potential travel bans and substantial fines.
While these measures demonstrate the government’s commitment to safeguarding homebuyers, it’s crucial for individuals to conduct thorough due diligence. Beyond consulting the blacklist, prospective buyers should assess developers’ track records, financial stability, and past project completions. Engaging with real estate professionals and seeking legal advice can further ensure informed decisions.
In summary, the public disclosure of blacklisted developers is a commendable move toward greater accountability in Malaysia’s housing industry. However, a collaborative approach involving stringent enforcement, legislative reforms, and proactive consumer awareness is essential to foster a trustworthy and resilient housing market.
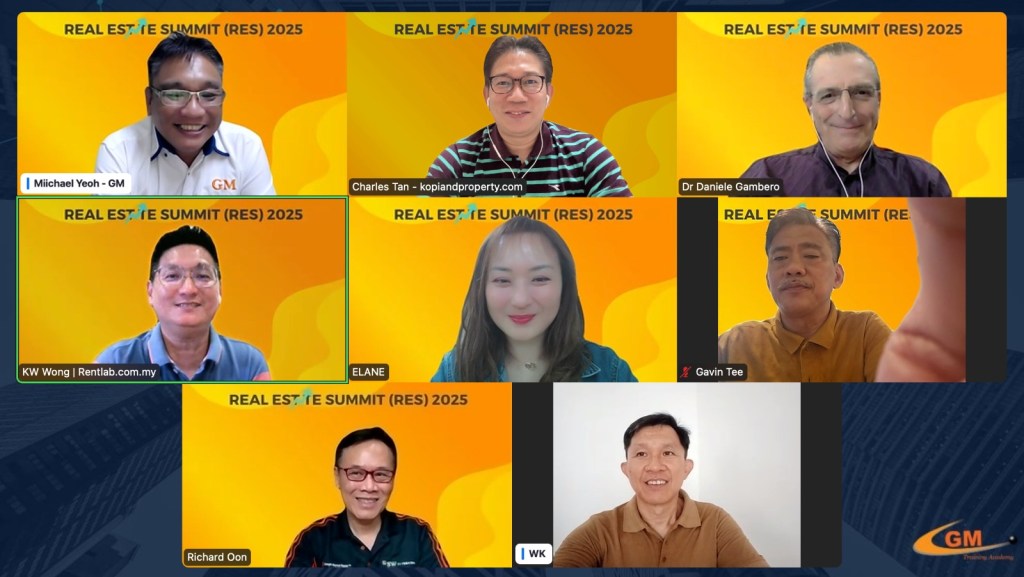
After two days of insightful discussions, expert sharing, and valuable networking, the Real Estate Summit 2025 (RES2025) has officially concluded! This event brought together some of the most renowned experts in real estate, finance, and investment, providing participants with actionable insights into the property market, financial planning, and smart investment strategies for 2025.
We were honored to welcome participants from Malaysia, the Philippines, Singapore, the USA, Germany, and many other countries. The diversity of attendees enriched discussions and created a vibrant learning environment.
A Heartfelt Thank You to Our Participants & Speakers
First and foremost, we extend our deepest gratitude to all participants for attending RES2025. Your enthusiasm and eagerness to learn made this event truly impactful.
A special appreciation to our distinguished speakers, whose expertise and insights played a crucial role in the success of RES2025:
🔹 Dato’ Sri Gavin Tee – A real estate expert who shared his forecast on the 2025 property market and upcoming investment opportunities. 🔹 Richard Oon – A taxation and financial planning specialist who guided participants on tax-saving strategies and financial management for property investors. 🔹 Dr. Daniele Gambero – A respected market analyst who discussed real estate trends, mortgage challenges, and investment potential in 2025. 🔹 Dr. Elane Goh – A finance and investment strategist who shared her insights on wealth creation through property investments and financial planning. 🔹 WK Ng – A seasoned property investor who transitioned from the corporate world to full-time investing, providing real-life success strategies. 🔹 KW Wong – A PropTech innovator and Secretary-General of the Malaysia PropTech Association, who spoke about the digital transformation of the rental market. 🔹 Charles Tan – A leading property market analyst who offered valuable perspectives on Malaysia’s evolving real estate landscape. 🔹 Miichael Yeoh – A mortgage and financial expert, who emphasized the importance of planning before making any major investment decisions.
Your dedication and willingness to share your knowledge made RES2025 a game-changing event for all attendees.
Special thanks to our co-organiser POLA Malaysia and our media partners Property Hunter and kopiandproperty.
Key Takeaways from RES2025
Throughout the two-day summit, participants gained powerful insights into the property industry, with topics covering:
✔️ Where to Invest in 2025 – Discovering high-potential investment hotspots. ✔️ Real Estate Market Trends – Adapting to economic shifts and evolving regulations. ✔️ Financial Planning & Taxation – Understanding tax incentives, financial structures, and mortgage strategies. ✔️ Mortgage Market 2025 – The latest developments in home financing and lending policies. ✔️ PropTech Innovations – The rise of digital property platforms and the impact on buying, selling, and renting. ✔️ Investment Strategies – How to build a profitable real estate portfolio.
As Miichael Yeoh emphasized in his session: “Plan first before making your next move.” Strategic financial and investment planning is essential to achieving long-term success in real estate.
The Power of Networking & Knowledge Sharing
Beyond expert talks, RES2025 provided an invaluable opportunity for participants to connect with industry leaders, experienced investors, and like-minded individuals. The event fostered an environment where attendees could exchange ideas, gain exclusive insights, and build meaningful professional relationships.
Looking Forward: What’s Next?
The success of RES2025 reaffirms GM Training Academy’s commitment to empowering individuals with property education and financial literacy. We believe that informed decisions lead to successful investments, and we are dedicated to helping investors, homeowners, and professionals navigate the ever-changing real estate market.
🚀 Upcoming Initiatives:
✅ More masterclasses and training workshops ✅ Exclusive webinars featuring top industry experts ✅ Property investment study tours ✅ Advanced financial and mortgage planning courses
Stay Connected & Keep Learning
📢 Missed RES2025? No worries! Stay connected with us for upcoming programs that will continue to provide valuable industry insights and expert guidance.
Once again, THANK YOU to all our participants and speakers for making RES2025 a grand success! We look forward to seeing you at our next event.
A major financial scandal in Malaysia has exposed a corrupt syndicate involving consultancy firms and bank officials, who siphoned 35% of approved loans from borrowers, primarily civil servants. The Malaysian Anti-Corruption Commission (MACC) revealed that these firms manipulated loan processes, securing multiple overlapping loans for victims, leaving them with crippling debts. Over RM700 million in loans were processed, but borrowers received only a fraction after exorbitant fees. The MACC’s ongoing crackdown has arrested 27 individuals and frozen RM22 million in assets, but the financial and emotional toll on victims remains severe.
Click for more Information or Sign Up
This issue has persisted for years, with many property buyers enticed to purchase multiple properties beyond their means. For instance, individuals with a RM5,000 salary were lured into buying 10 properties with high cashback offers, only to face financial ruin. In one case, a couple after attending my seminar shared how they were encouraged by a “Property Guru” to buy five properties at once, exploiting bank loopholes. They later discovered the properties were overpriced and unrentable, leaving them bankrupt with RM16,000 monthly installments and two young children to support. This highlights the dangers of reckless investment decisions. Always verify sources, avoid intermediaries charging excessive fees, and ensure investments align with your financial capacity.
A financial scandal of massive proportions has rocked Malaysia’s banking sector, exposing a corrupt syndicate that preyed on borrowers, especially civil servants, by siphoning off exorbitant fees from approved bank loans.
The Malaysian Anti-Corruption Commission (MACC) recently uncovered that financial consultancy firms, operating under the guise of loan facilitators, were pocketing at least 35% of the approved loan amounts, leaving victims with far less than what they had borrowed.
A Web of Deceit: How Borrowers Were Trapped
The scheme involved consultancy firms manipulating the loan approval process in collusion with corrupt bank officials. According to MACC Chief Commissioner Tan Sri Azam Baki, the syndicate exploited desperate borrowers by securing multiple loans from various financial institutions simultaneously, orchestrating a complex scam that resulted in borrowers being burdened with insurmountable debts.
“These firms orchestrated ‘multiple loans’ by manipulating bank systems and turn-around times, making it seem as if previous loans had been settled when, in reality, they had not. This deception ensured that borrowers would receive overlapping loans, only to have substantial portions deducted as ‘fees,’” said Azam.
Many victims, entangled in financial distress and seeking funds to settle previous debts, unknowingly agreed to the terms set by these firms. In addition to the 35% consultancy fee, borrowers were also subjected to loan settlement charges of up to 40%, further exacerbating their financial woes.
RM700 Million in Loans: But Victims Still Drowning in Debt
The investigation, codenamed Ops Sky, revealed that the syndicate managed to secure approximately RM700 million in loans for borrowers. However, instead of receiving their full loan amounts, victims were left with only a fraction of what they applied for, leading to a debt crisis far beyond their means to repay.
Despite the dismantling of the syndicate, the damage has already been done. Many victims now owe three times more than their financial capabilities allow, making repayment virtually impossible. “Even though the syndicate has been dismantled, borrowers remain indebted to the banks and must continue servicing their loans,” Azam stated.
Massive Crackdown: Bank Officers and Syndicate Members Arrested
In a coordinated crackdown, MACC and Bank Negara Malaysia raided 24 locations across the Klang Valley, including residences and offices linked to the syndicate. The operation led to the arrest of 12 key individuals, including bank officials and employees of the financial consultancy firms involved.
Further investigations revealed that 98 company and personal bank accounts worth over RM22 million had been frozen, and nearly 4,000 documents seized as part of the evidence collection.
A total of 27 individuals, including 18 bank officers, eight financial consultancy employees, and one member of the public, were detained before being released on bail.
Social Media and Celebrities Used to Lure Victims
Adding another layer to the scandal, the syndicate aggressively marketed its services using social media influencers, celebrities, and public figures to gain credibility.
Advertisements flooded Facebook, TikTok, and Instagram, targeting schoolteachers, nurses, and government employees.
The firms even conducted surveys, roadshows, and CSR programs at schools and hospitals, falsely promoting their services as legitimate financial solutions.
What’s Next? Ongoing Investigations and a Warning to the Public
The MACC has vowed to continue its investigations under Ops Sky, with more witnesses expected to be summoned. The public is urged to be cautious when dealing with financial consultancy firms that promise easy loans, especially those charging high service fees upfront. “This case serves as a stark warning and always verify loan processes directly with the bank and avoid intermediaries who demand excessive fees,” Azam cautioned.
As investigations continue, Malaysians are left questioning how such large-scale corruption involving multiple financial institutions could have persisted unchecked for so long. The financial burden on victims remains heavy, and the battle for justice is far from over.
As of January 2025, Bank Negara Malaysia (BNM) has maintained the Overnight Policy Rate (OPR) at 3.00%, a position held since May 2023.
Understanding the Overnight Policy Rate (OPR)
The OPR is the benchmark interest rate at which banks lend to one another overnight. Set by BNM, it serves as a primary monetary policy tool to regulate liquidity, control inflation, and sustain economic growth.
Implications of an OPR Increase
When BNM raises the OPR, it signals an intent to tighten monetary policy. The effects of such an increase include:
Higher Borrowing Costs: Banks typically respond to an OPR hike by raising their base rates, leading to increased interest rates on loans and mortgages. This results in higher monthly repayments for borrowers.
Enhanced Savings Returns: Conversely, depositors may benefit from higher interest earnings on savings and fixed deposits, encouraging increased savings.
Controlled Inflation: Elevated borrowing costs can dampen consumer spending and business investments, helping to moderate demand-pull inflation.
Currency Appreciation: Higher interest rates can attract foreign investment, potentially strengthening the Malaysian ringgit.
Impact on Property Market: Increased interest rates may lead to higher mortgage costs, potentially cooling property demand and affecting market dynamics.
Recent Economic Context
In the third quarter of 2024, Malaysia’s economic growth slowed to 5.3% from 5.9% in the previous quarter, influenced by reduced oil and gas production. Despite this, robust household spending and increased investments provided support.
BNM’s Monetary Policy Stance
BNM has maintained the OPR at 3.00% since May 2023, citing positive economic growth and steady inflation. Economists anticipate that the central bank will keep the OPR unchanged until at least 2026, aligning with current economic assessments.
Interest Rate Impact Example
Let’s look at an example of how interest rates affect property loans. Assume you’re borrowing RM500,000 for 30 years:
Current Interest Rate (4.5%): Monthly repayment is approximately RM2,533.43.
If OPR Increases by 25 Basis Points (4.75%): Monthly repayment rises to around RM2,608.82.
Impact: This increase of RM75.39 per month adds up to RM27,140.40 over the loan’s term.
This illustrates why understanding interest rates and their potential changes is crucial for planning your finances.
Conclusion
An increase in Malaysia’s OPR has multifaceted effects, influencing borrowing costs, savings returns, inflation, currency value, and the property market. Understanding these dynamics is crucial for individuals and businesses to make informed financial decisions in response to monetary policy changes.
Purchasing or investing in property is one of the most significant financial decisions a person can make. While the prospect of owning a piece of real estate can be exciting, it’s also fraught with risks and complexities. Here are eight compelling reasons why educating yourself before taking the plunge is crucial:
1. Understanding the Market
The property market is dynamic, influenced by factors such as economic conditions, interest rates, and government policies. Without proper knowledge, you might buy at the wrong time or in the wrong location, potentially leading to financial losses. Education helps you grasp market cycles and trends, enabling informed decisions.
2. Avoiding Costly Mistakes
From overpaying for a property to falling victim to scams, the risks of making costly mistakes are high for uninformed buyers. Learning about property valuation, legal processes, and common pitfalls can save you from financial heartache.
3. Maximizing Investment Returns
Investing in property isn’t just about buying a house or apartment; it’s about choosing assets that will appreciate in value or generate steady rental income. Understanding key metrics such as ROI (Return on Investment) and cash flow can help you identify profitable opportunities.
4. Navigating Legal and Financial Complexities
Property transactions involve a maze of legal and financial considerations. From understanding loan agreements to navigating tax implications and zoning laws, there’s a lot to learn. A lack of knowledge could lead to delays or even legal troubles.
5. Building Confidence
The more you know, the more confident you’ll feel about your decisions. Knowledge reduces fear and uncertainty, empowering you to negotiate effectively, choose wisely, and stick to your long-term goals.
6. Identifying Red Flags
Not all properties are created equal. Structural issues, poor location, and hidden costs can turn a dream investment into a nightmare. Learning to conduct due diligence and property inspections ensures you spot potential problems early.
7. Accessing Better Financing Options
Understanding how mortgages and loans work can save you thousands of dollars over the life of your investment. Learning about different financing options and how to improve your creditworthiness can lead to better interest rates and loan terms.
8. Planning for the Future
Property investment is a long-term commitment. Learning helps you align your investment choices with your financial goals, whether it’s building wealth, securing passive income, or preparing for retirement. Knowledge enables strategic planning that benefits you in the long run.
Conclusion
Investing time and effort into learning before buying or investing in property is an investment in itself. It equips you with the tools and insights needed to make smart, informed decisions that align with your financial aspirations. Remember, in the world of property, knowledge isn’t just power; it’s profit.
Ever come across the term Debt Service Coverage Ratio (DSCR)? If not, don’t worry—I’m here to simplify it for you. While it might seem complex, DSCR is actually a straightforward concept that plays a crucial role in real estate investing.
What is Debt Service Coverage Ratio (DSCR)?
The Debt Service Coverage Ratio (DSCR) is a key metric that assesses whether a property’s income is sufficient to cover its debt obligations. Think of it as a financial report card for real estate investors, showing if a property is financially sustainable. Let’s break it down for easier understanding:
The DSCR Formula
DSCR = Net Operating Income (NOI) / Total Debt Service (TDS)
Net Operating Income (NOI): The income generated by the property, including rent and other sources, after deducting expenses like maintenance, property management fees, and taxes.
Total Debt Service (TDS): The total annual payments required to service the loan, covering both principal and interest.
How to Interpret DSCR
DSCR > 1: The property generates more income than needed to cover its debt—this is a positive sign!
DSCR < 1: The property’s income is insufficient to cover the debt—this signals potential risk.
A higher DSCR indicates a lower risk of default, making the property more attractive to lenders.
How DSCR Works in Practice
Let’s see DSCR in action with a practical example:
With a DSCR of 1.25, Peter’s property generates more income than needed to cover the debt, indicating financial stability and a comfortable margin for loan payments.
Why DSCR Matters?
The Debt Service Coverage Ratio (DSCR) is a critical indicator in real estate investing, helping you assess whether a property’s income can cover its debt obligations. Whether you’re looking to own rental properties or simply exploring the real estate market, understanding DSCR is essential for your success. By maintaining a healthy DSCR, you can build a solid foundation for your investments and ensure long-term profitability.
From The Desk of Miichael Yeoh
Check out the latest article on how Budget 2025 impacts the property sector
Here is the recorded version of my bi-weekly talk with Mr. WK Ng from last Thursday. We had an in-depth discussion covering everything from buying your first house to property investing. With over 30 years of experience as an investor, Mr. Ng offers valuable insights and a methodical approach that should not be missed.
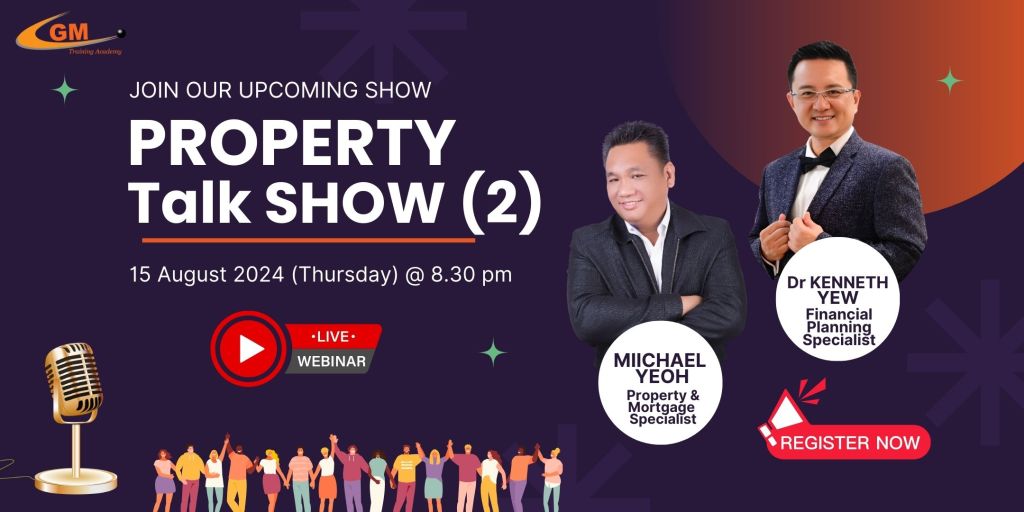
Join us for our upcoming live webinar (EP 2) on Thursday, 15th August 2024, at 8:30 PM. Our special guest, Dr. Kenneth Yew, will be discussing property financial planning.
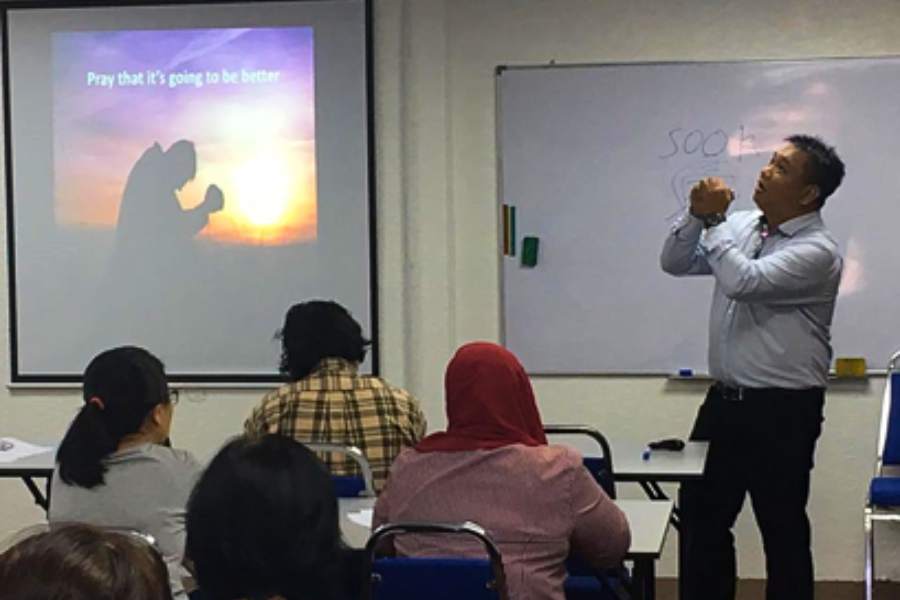
In the picture, what do you think I am doing? Praying for the money to drop
I do not really depend on these. I don’t think money will suddenly drop from the sky or hoping for a miracle to happen. If a car were to break down, you will need a mechanic to fix the problem. He will have to follow a series of steps in doing repair and to make sure your car is running again.
Likewise, in mortgage approval you cannot wait for miracle things to happen. To me, luck have nothing to do on mortgage approval. Many borrowers and agents, prefer to photocopy many stacks of financial documents and give to every bank they know off or can find and submit to them for approval. Is this the right way?
Do you know that every time your documents are submitted, the banks will record and send to Bank Negara which in turn will update the Central Credit Information System (CCRIS) every month? No matter whether your loan is approved or rejected it will be updated on the last page of your record. Let’s say Bank A rejects your loan, Bank B,C and D also rejects but Bank E actually can approve your loan but seeing so many banks rejected your loan the chances are they will also reject your loan.
Never expose yourself. Every bank have different approval criteria. Some banks might not like you but some does. I have a case once, his Debt Service Ratio is very high at 150% in which is higher than the normal 70-85%. Either the banks rejects or do not want to waste time processing his case. I reviewed his documents and to cut things short, I managed to get 70% loan approval. This case is a fine example where the borrower will have to do the following:
Do a Know yourself (KYS) test.
Check your credit status
Check which bank is suitable for you.
You will have to do more work on the last step. You will need to find out each bank approval criteria and also the different types of documents for approval. You are not buying a RM1,000 property but hundreds or even millions worth of property. It is good to do a research first. It is hard to go back when your loan had been rejected. It is easier to diagnose a problem first.
















 Miichael Yeoh
