Tag: mortagge-loan

  • 8 Strategies for Paying Off Your Home Loan Faster

    8 Strategies for Paying Off Your Home Loan Faster

    Without a doubt, your mortgage represents one of the most significant financial commitments you’ll undertake. Over its lifespan, the interest paid to the bank alone can skyrocket into tens of thousands. Consider this: by adhering to a 30-year home loan term, you may ultimately shell out twice the original loan amount in total.

    Did you know that within the first five years of a 30-year loan, you’re likely to reduce only about 7% of the principal? Even by the 20th year, you might still be grappling with less than half. It’s high time to reclaim control over your loan and expedite its repayment to save substantial sums in interest.

    Gone are the days of rigid loan structures prevalent from the 1960s to the 1990s. Today, borrowers have access to a plethora of tools and flexible bank policies, enabling them to slash down loan tenures.

    The sooner you bid farewell to your home loan, the sooner you’ll inch closer to retirement and debt-free living. While myriad methods exist to accelerate repayment, not all may be a perfect fit for your situation. It’s imperative to conduct thorough research and select the strategies best aligned with your needs.

    Here are some actionable ways to expedite home loan repayment:

    1. Making Extra Payments: Witness the magic unfold by utilizing a mortgage calculator to see how even modest additional monthly payments can drastically reduce interest and hasten home loan repayment. Remember, every dollar directed towards the principal shrinks the interest burden and speeds up loan clearance
    2. Refinance: Take advantage of prevailing lower interest rates by refinancing your loan. Use a mortgage calculator to gauge potential interest savings, but don’t forget to factor in associated costs like penalties and legal fees.
    3. Negotiate Interest Rate Adjustments: Keep a keen eye on interest rate fluctuations and consider negotiating with your bank for a reduction. Maintaining current installment amounts despite rate reductions can substantially reduce repayment years
    4. Utilize Flexi Mortgages: Explore flexible mortgage options like the Flexi Mortgage or Money Merge Account, where daily interest calculations and account consolidation accelerate principal reduction, thus shortening loan tenure.
    5. Interest Rate Adjustments: Strategize responses to fluctuating interest rates by either increasing monthly installments to maintain repayment duration or maintaining installments to reduce repayment years.
    6. EPF Withdrawals: Tap into your EPF Account II to swiftly reduce principal and expedite loan repayment. This can even be arranged on a monthly basis for added convenience. In Malaysia it is called EPF or Employee Provident Fund. Its a retirement saving account.
    7. Continuous Monitoring and Adjustment: Regularly monitor your loan progress and financial situation, adjusting strategies as needed to optimize repayment efficiency.
    8. Bi-Weekly Payments: Divide your monthly installment into bi-weekly payments, effectively making 13 monthly payments annually. This simple adjustment can shave off at least four years from a typical 30-year loan term, although availability may vary by region. Please take note that not every country has this package.

    By diligently implementing these strategies, you can significantly alleviate the burden of your home loan and pave the way towards financial freedom.

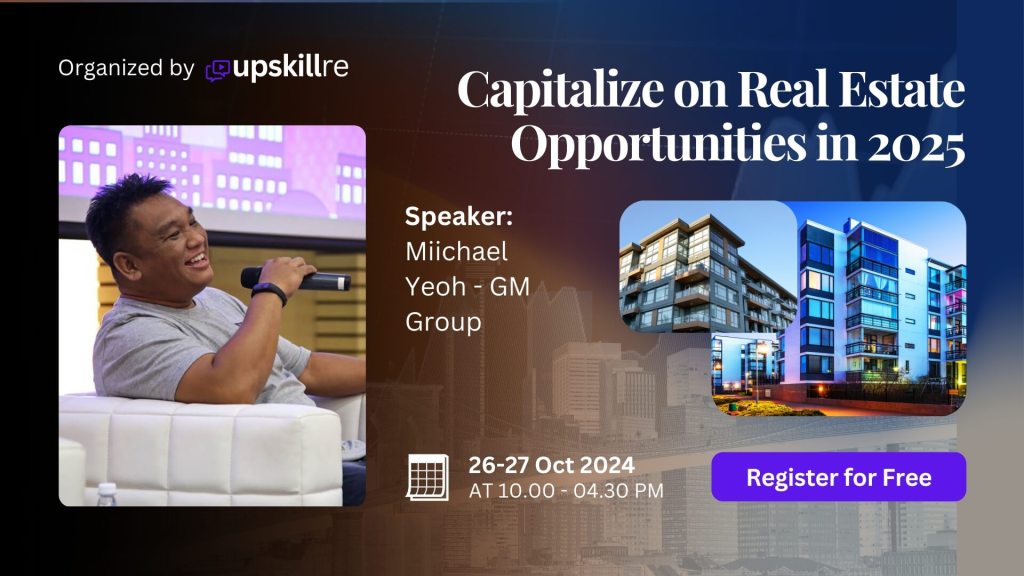
    From the desk of Miichael Yeoh
  • Mastering Your Financial Future: A Guide to Financial Planning

    Mastering Your Financial Future: A Guide to Financial Planning

    Financial planning is the cornerstone of a secure and prosperous future. It involves setting realistic goals, creating a roadmap to achieve them, and making informed decisions about your money. Whether you’re just starting your career or nearing retirement, having a solid financial plan in place is essential for building wealth, managing risks, and achieving financial independence. In this article, we’ll explore the key components of financial planning and provide actionable tips to help you navigate your financial journey with confidence.

    1. Assess Your Current Financial Situation: The first step in financial planning is to assess your current financial situation. Take stock of your income, expenses, assets, and liabilities. Create a detailed budget to track your spending habits and identify areas where you can save money. Calculate your net worth by subtracting your liabilities from your assets. This snapshot of your finances will help you understand where you stand and identify areas for improvement.

    2.Set SMART Financial Goals: Once you have a clear understanding of your financial situation, it’s time to set SMART (Specific, Measurable, Achievable, Relevant, Time-bound) financial goals. Whether it’s buying a home, saving for your children’s education, or planning for retirement, clearly define your goals and prioritize them based on their importance and urgency. Break down each goal into smaller, manageable milestones to track your progress along the way.

    3.Create a Budget and Stick to It: A budget is a powerful tool that helps you allocate your income towards your financial goals while ensuring that you live within your means. Start by listing your fixed expenses such as rent/mortgage, utilities, and loan payments, then allocate a portion of your income towards savings and investments. Be mindful of discretionary spending and look for opportunities to cut unnecessary expenses. Regularly review and adjust your budget as your financial situation changes.

    4. Build an Emergency Fund: Life is unpredictable, and unexpected expenses can derail your financial plans if you’re not prepared. That’s why it’s crucial to build an emergency fund to cover unforeseen expenses such as medical emergencies, car repairs, or job loss. Aim to save at least three to six months’ worth of living expenses in a liquid, accessible account like a savings account or money market fund. Having an emergency fund provides peace of mind and financial security during challenging times.

      5. Manage Debt Wisely: Debt can be a significant obstacle to achieving your financial goals if not managed wisely. Prioritize paying off high-interest debt such as credit cards and personal loans to minimize interest payments and improve your financial health. Consider consolidating debt or negotiating lower interest rates to accelerate your debt repayment journey. Avoid taking on new debt unless absolutely necessary and use credit responsibly to build a positive credit history.

      6. Invest for the Future: Investing is a powerful wealth-building tool that allows your money to grow over time through the power of compounding. Determine your risk tolerance and investment objectives, then develop a diversified investment portfolio tailored to your goals and timeline. Consider investing in a mix of stocks, bonds, mutual funds, and other asset classes to spread risk and maximize returns. Regularly review and rebalance your portfolio to ensure it remains aligned with your objectives.

      7. Plan for Retirement: Retirement may seem far off, but it’s never too early to start planning for your golden years. Take advantage of employer-sponsored retirement plans such as 401(k)s or IRAs to save for retirement tax-efficiently. Contribute enough to qualify for employer matching contributions and increase your contributions over time as your income grows. Consider working with a financial advisor to develop a personalized retirement plan and explore options such as annuities or pension plans to supplement your retirement income.

      8. Protect Yourself and Your Loved Ones: Insurance is an essential component of financial planning that provides protection against unforeseen events such as illness, disability, or death. Review your insurance coverage regularly to ensure it adequately protects you and your loved ones. Consider policies such as health insurance, life insurance, disability insurance, and long-term care insurance based on your needs and circumstances. Don’t overlook estate planning, including drafting a will and establishing powers of attorney to protect your assets and ensure your wishes are carried out.

      Financial planning is a lifelong journey that requires diligence, discipline, and adaptability. By following these key principles and incorporating them into your financial strategy, you can take control of your finances, build wealth, and achieve your long-term goals. Remember that financial planning is not a one-time event but a continuous process that evolves with your life circumstances. Stay proactive, stay informed, and stay committed to securing your financial future.

      From the Desk of

      Miichael Yeoh

    1. 10 Commandments of Mortgage Approval

      10 Commandments of Mortgage Approval

      Prior to diving into the mortgage application process, it’s essential to heed this advice, which could potentially spare you valuable time and considerable financial resources. Delve into these 10 commandments before embarking on your property journey to equip yourself with the knowledge necessary for a successful and cost-effective experience.

      1. Thou Shall not cheat the bank

      If you are thinking of buying many properties with just 1 income and well above your eligible limits, please think again. Now the banks do check the CCRIS again before releasing the loan. The have the right to reduce the loan limit as stated in the letter of offer you signed.

      2. Thou Shall not fake documents

      Some people have difficulties getting their loan approval. Thus, they resorted to doing fake documents. There are even companies specialized in this area to do it on behalf of the borrower. Let me tell you, banks are not stupid. They always double check before approving any loans. Currently, the check are getting tighter. Once caught,  it will be a police case.

      3. Thou Shall not be greedy

      The word GREED seems very familiar to everyone. Now instead of buying 1 property within your capacity, you instead buy 5. You have been thought how to achieve a lifetime goal of financial freedom at a very short time. If you are lucky you can be an instant millionaire but if you are not, you end to be an instant millionhair.

      4. Thou Shall not be guarantor

      Do you know that been a guarantor for someone else loan can be lead to loan rejection. Many years back, I have this case where a couple were planning to buy a house because they are getting married 6 months later.  They told me that all installments are promptly paid and they do not have any problem with the banks. Their loan was actually rejected by the bank because the lady stand as a guarantor for the brother’s loan. The brother’s car was repossessed by the bank. Her property loan is affected also.

      5. Thou Shall not incur debts

      The more debt you have the more difficult to get loan approval. Debts such as personal loans, car loans and etc are calculated in Debt Service Ratio (DSR) and will be part of approval. High personal DSR can either cost you your loan rejection or a very low margin of finance approval. The smart way is to minimize your debts or to repay all debts.

      6. Thou Shall not use credit card

      Do you know that credit card is the main culprit for loan rejection? Out of 10 loan rejected 65% are from credit card usage. Credit card function like a free money. Use now pay later. As in the term and conditions,

       your only required to pay 5% of the usage every month. Many people also resort to buying things in credit via credit card. All these will be calculated as your debts. The banks will take 5% of the outstanding amount as calculation. If the credit card usage is more than 70% of the approve limit, you are deemed as a high risk person even though you paid the minimum 5% monthly. Your loan approval will be affected.

      7. Thou Shall pay all your loan promptly

      As a bank, they will reject a loan if they were to find out that you have not paid your existing loan promptly. They can see from your CCRIS record. The bank will be worried as they are going to lend you some more but you have already showed to them you are not a good paymaster. They will assume that in future they will have the same problem. They rather not lend to you.

      8. Thou Shall only buy what you can afford

      Many people especially youngsters because of peer pressure buy property that they cannot afford to pay. The person can only afford RM300,000 property but end up buying RM600,000. The installment will be double. As the bank have their strict calculations on approval, the loans might be rejected or the margin slash. We cannot blame the bank for this as they are not charity organization.

      9. Thou Shall not change job

      You might think that what changing job have to do with loan approval. Please do not take this lightly. To the bank you are new to the company although you’re already working for years in your previous company. As you are new, your job is not secured and you might be terminated in 3 or 6 months period. So, the right way to do it is to apply the loan while you are at the existing company. After approval you move on to another company will not affect your loan.

      10. Thou Shall do at least one facility

      Why you may asked? Isn’t no debts at all easier to get approval? You are wrong. To the banks, if you do not have any facility at all you are too cleaned. They do not know who you are. Your CCRIS is too clean. Yeah, I agree getting a loan nowadays are very troublesome.  Well very simple to overcome this. Apply for a credit card, make sure you use it (every month fully paid is ok) then the banks will grant you the loan.