Tag: Finance

  • Before You Buy Property, Do This First — Or You’re Just Guessing

    Before You Buy Property, Do This First — Or You’re Just Guessing

    Smart Investors Don’t Start With Property — They Start With Demand

    Most people think property investment starts with:

    Location.
    Price.
    Developer.

    It doesn’t.

    It starts with a much more fundamental question:

    Are you buying for own use… or for investment?

    Because if you get this wrong, everything else becomes noise.


    Step 1: Define Your Purpose (No Grey Area)

    I’ve seen buyers say they are investing…

    But make decisions based on:

    • Design
    • Lifestyle
    • Personal preference

    That’s not investing.

    That’s emotion.

    If it’s own stay, you follow your lifestyle.

    If it’s investment, you follow demand and numbers.


    Step 2: Know Your Budget (This Sets Your Playing Field)

    Before anything else:

    • What is your true affordability?
    • What is your financing capacity?
    • What is your holding strength?

    Because in property:

    You don’t lose money when you buy wrong.
    You lose money when you can’t hold.

    Especially for investors—cash flow and holding power are everything.

    Step 3: Real Investors Do One Thing Differently — They RESEARCH

    This is the biggest gap in the market.

    Most buyers rely on:

    • Marketing materials
    • Sales narratives
    • “Good location” claims

    But experienced investors?

    They study the market before they commit.


    What Do You Actually Research?

    1. Demand & Demographics (The Real Starting Point)

    Forget the building first.

    Ask:

    Who is the end user of this property?

    • Young professionals?
    • Families?
    • Tourists?
    • Businesses?

    If you don’t understand demand,
    you’re not investing—you’re guessing.


    And This Is Where Industrial Property Becomes Interesting

    For big-budget investors, the shift is already happening.

    Demand is no longer driven by lifestyle.

    It’s driven by business movement and capital flow.

    Look at what’s happening:

    • Manufacturing relocation into Malaysia
    • Growth in logistics and warehousing
    • E-commerce expansion
    • Supply chain restructuring across ASEAN

    This creates a different type of demand:

    • Larger space requirements
    • Functional layouts over aesthetics
    • Accessibility to ports, highways, and labour
    • Long-term tenancy from businesses (not individuals)

    In other words:

    Industrial demand is economic-driven, not sentiment-driven.

    And that’s exactly what sophisticated investors are looking for.


    2. Price Per Square Foot (Entry Determines Exit)

    You make money when you buy right.

    Compare:

    • Nearby transactions
    • Competing projects
    • Replacement cost

    If you enter too high, your upside is already limited.


    3. Surrounding Supply (The Silent Risk)

    Most investors ignore this.

    But supply determines:

    • Rental pressure
    • Vacancy risk
    • Exit liquidity

    Too much incoming supply?

    Even a “good project” can underperform.


    4. Infrastructure & Connectivity (Follow the Growth)

    No area grows randomly.

    Growth follows:

    • Highways
    • Ports
    • Rail (LRT / MRT / logistics links)
    • Industrial corridors

    If infrastructure is expanding, demand usually follows.


    5. Rental & Yield Reality Check

    At the end of the day:

    Can it generate income?

    • What is the realistic rental?
    • Who is the tenant profile?
    • What is the occupancy expectation?

    If the numbers don’t work on paper,
    don’t rely on hope.


    What I’ve Learned From the Ground

    After evaluating multiple projects and markets, one thing is clear:

    The winners are not those who buy the most.
    The winners are those who understand demand the best.

    Every property I consider goes through:

    • Demand validation
    • Market comparison
    • Supply analysis
    • Financial assessment

    Because once you commit,
    you’re not just buying property…

    You’re locking in a decision for years.


    Final Thought

    Property investment has evolved.

    It’s no longer about chasing what’s popular.

    It’s about understanding why demand exists—and where it’s going next.

    Those who do the work will always have an edge.

    Those who don’t…

    Will always be reacting.


    Disclaimer: This reflects the author’s personal views based on market experience and current observations. It is not financial advice. Smart investors do their own research before making any move.

    From the Desk of

    Miichael Yeoh
  • Property Is Still Alive — But the Game Has Changed

    Property Is Still Alive — But the Game Has Changed

    Buying a property today is very different compared to 10 or 20 years ago.

    Back then, property could sell very easily.
    Developers launched, buyers queued, and decisions were made quickly.

    Today, the world has changed.

    The way people buy property has changed.
    The way markets behave has changed.
    And more importantly, the way buyers think has changed.

    Buyers today are far more informed.

    Before even paying a booking fee, many would have already:

    • Compared multiple projects
    • Studied pricing trends
    • Checked developer track record
    • Analysed location fundamentals
    • Calculated loan eligibility and cash flow

    In other words, today’s buyers are not just buyers — they are researchers.


    At the same time, the global environment is not exactly calm.

    We are seeing ongoing geopolitical tensions — from the US–Iran situation to instability in parts of the Middle East.
    Interest rates, inflation, and currency movements continue to shift.

    All these create one thing: uncertainty.

    And when uncertainty comes in, market behaviour changes.

    From what I observe in today’s property market:

    • Investors are waiting — not exiting
    • Sellers are holding — not reducing
    • Buyers are selective — not absent

    Let that sink in.

    The market is not dead.
    It is simply… more cautious.


    And here is something many people miss:

    👉 When the market is not stable, that is where the opportunity lies.

    Why?

    Because:

    • Less emotional buying
    • More rational pricing
    • More room for negotiation
    • More time to analyse properly

    In a hot market, people chase.
    In a cautious market, people choose.

    And those who choose well, win.


    This is exactly why I started focusing on Property Market Intelligence.

    Not just looking at property as a product,
    but understanding:

    • Market timing
    • Buyer psychology
    • Financing structure
    • Exit strategy
    • Risk positioning

    This approach is built from more than 25 years in the property and banking industry.

    I have gone through multiple market cycles:

    • Asian Financial Crisis
    • Global Financial Crisis
    • Property slowdowns
    • Policy changes
    • And shifting buyer behaviours across decades

    Every cycle teaches one thing:

    👉 The market will always move — but not everyone moves with it.


    Today, success in property is no longer about:
    “Buy and wait.”

    It is about:
    “Buy with clarity.”

    Because in today’s market:

    • Information is everywhere
    • But insight is rare

    If you are buying today, don’t just ask:

    “Is this a good property?”

    Ask instead:

    • Who will buy from me later?
    • What is the demand driver here?
    • How does financing affect my holding power?
    • What happens if the market stays slow for 3–5 years?

    That is how professionals think.


    The market has not disappeared.

    It has simply matured.

    And in a mature market,
    strategy will always beat impulse.


    Miichael Yeoh
    Property Strategist | Author

    Author of:
    Think Like a Banker, Act Like a Player
    Property Investment BLT
    Buying Property Like a Pro (MPH Bestseller)

  • Think Like a Banker Before You Buy Property

    Think Like a Banker Before You Buy Property

    One thing I learned from working closely with banks is this:

    Banks are extremely careful before approving a property loan.

    They analyse risks, stress-test your finances, and study whether you can survive difficult situations.

    But here’s the irony.

    Many property buyers don’t analyse their purchase the same way.

    They look at the show unit.
    They listen to marketing promises.
    They follow what others are buying.

    But they rarely ask the same questions a banker would ask.

    If you want to invest in property wisely, start by thinking like a banker.

    Here are three things bankers always analyse.


    1️⃣ Debt Ratio – Are You Stretching Yourself Too Thin?

    Banks look closely at your Debt Service Ratio (DSR).

    This measures how much of your income is used to pay debts.

    Even if a bank approves your loan, you should still ask yourself:

    • What happens if interest rates increase?
    • What if my income drops temporarily?
    • Will I still feel comfortable servicing the loan?

    A property might look affordable today.

    But bankers always plan for tomorrow’s risks.


    2️⃣ Holding Power – Can You Hold Through Market Cycles?

    Property markets don’t always go up.

    There will be slow periods.

    Bankers evaluate whether a borrower has the financial strength to continue paying during tough times.

    Smart investors should ask:

    • Can I hold this property for 5–10 years if needed?
    • Do I have cash reserves?
    • What if the market takes longer to recover?

    Many investors fail not because they bought the wrong property…

    They fail because they cannot hold it long enough.


    3️⃣ Rental Sustainability – Can the Property Support Itself?

    Another banker mindset is income sustainability.

    Before buying, ask:

    • Is there real rental demand here?
    • Who are the potential tenants?
    • Can the rental help support the loan?

    A strong investment property should ideally generate rental income that supports part of the financing.

    This reduces pressure and improves long-term stability.


    Final Thought

    Successful property investors don’t buy emotionally.

    They evaluate property like a banker evaluating risk.

    Before your next purchase, ask yourself:

    Does this property pass the banker’s test?

    When you start thinking like a banker, you don’t just buy property.

    You build a stronger and safer property portfolio.


    Miichael Yeoh
    Property Strategist | Developer Consultant | Investment & Mortgage Expert
    Author of Think Like a Banker, Act Like a Player

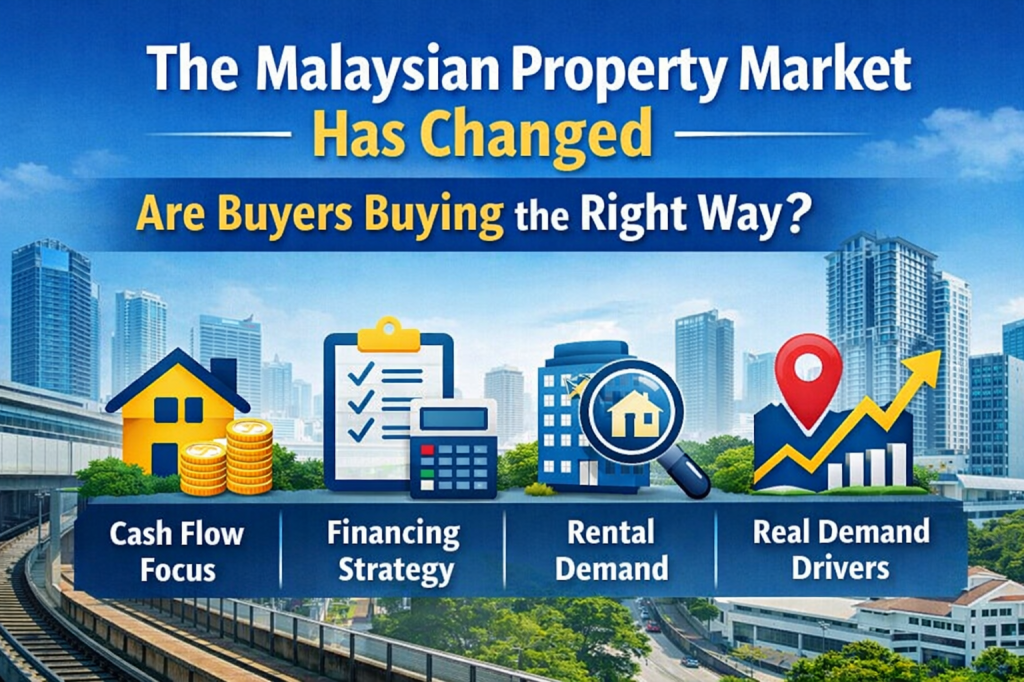
  • The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?

    The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?

    The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?

    For many years, property investing in Malaysia followed a familiar formula.

    Buy a new launch, wait a few years, and hope the price goes up.

    This strategy worked reasonably well during earlier property cycles when prices were rising quickly, financing was easier, and supply was more limited. Many investors entered the market believing that capital appreciation alone would justify the purchase.

    But today, the Malaysian property market has entered a different phase.

    The question buyers should now ask is no longer “Will the price go up?”
    The more important question is “Can this property sustain itself financially?”


    The Shift From Speculation to Sustainability

    Over the past decade, the mindset of property buyers has gradually evolved.

    Today’s buyers are more cautious, more analytical, and more focused on cash flow and long-term holding power.

    Instead of relying purely on future price appreciation, investors are increasingly asking questions such as:

    • What is the rental demand in this area?
    • Can the rental cover most of the loan instalment?
    • What happens if interest rates increase?
    • Who is the actual tenant profile for this property?

    These questions reflect a more mature approach to property investing.

    The reality is simple: not every property will appreciate significantly in the short term. When appreciation slows, the ability of the property to generate rental income becomes far more important.


    Financing Strategy Now Matters More Than Ever

    Another major shift in the market is the growing importance of financing structure.

    Many buyers focus heavily on the purchase price but pay little attention to how the property is financed. Yet the financing strategy can determine whether an investment becomes manageable or financially stressful.

    Buyers today need to consider:

    • Loan margin and interest rates
    • Monthly instalment affordability
    • Holding power during market slowdowns
    • Overall debt exposure

    A well-structured loan can give investors time and flexibility, while poor financial planning can force them to sell prematurely.

    Thinking about financing before buying is no longer optional — it is essential.


    Rental Demand Is Becoming a Key Decision Factor

    One of the biggest mistakes many investors made in the past was buying properties without considering who would actually rent the unit.

    Today, buyers are beginning to look more closely at demand drivers such as:

    • Proximity to employment hubs
    • Accessibility and transportation infrastructure
    • Nearby universities or hospitals
    • Tourism demand and short-term rental potential

    In markets like Penang, Kuala Lumpur, and Johor Bahru, rental demand is increasingly shaping investment decisions.

    For example, areas with strong tourism activity or major infrastructure developments may offer better rental prospects compared to purely speculative locations.

    The key question investors should ask is:

    “Who is my tenant?”

    If there is no clear answer, the investment may not perform as expected.


    The Role of Infrastructure and Economic Drivers

    Another important factor influencing property performance today is real economic activity.

    Infrastructure projects, transportation connectivity, employment centres, and tourism growth can significantly impact both rental demand and long-term property value.

    For instance, upcoming transportation developments and urban revitalisation projects in cities such as Georgetown could change demand patterns in the coming years.

    However, infrastructure alone does not guarantee success. The surrounding ecosystem — population growth, business activity, and lifestyle demand — must also support the property market.


    Buying Property Today Requires a Different Mindset

    The Malaysian property market has not disappeared. But the way buyers approach property must evolve.

    Successful investors today tend to follow a more balanced approach:

    • Evaluate rental yield and cash flow
    • Structure financing carefully
    • Understand real demand drivers
    • Focus on long-term sustainability

    In other words, the focus has shifted from short-term speculation to long-term investment discipline.


    A Final Thought

    Property has always been a long-term asset class.

    But in today’s market environment, buying property requires more than just optimism about future price growth.

    It requires careful thinking, realistic financial planning, and a clear understanding of market demand.

    The Malaysian property market has changed.

    The real question is — have buyers changed with it?


    Miichael Yeoh
    Property Strategist | Developer Consultant | HRD Corp Trainer

    Miichael Yeoh has more than 28 years of experience spanning banking, mortgage advisory, property investment, and developer consultancy. He is also the author of Think Like a Banker, Act Like a Player, Property Investment BLT, and Buying Property Like A Pro.

  • What Is OPR in Malaysia and How Does It Affect Housing Loan Interest Rates?

    What Is OPR in Malaysia and How Does It Affect Housing Loan Interest Rates?

    By Miichael Yeoh

    As someone who has spent nearly three decades in banking, mortgage advisory and property strategy, one question I get repeatedly from investors and homebuyers is:

    “Why did my bank increase (or educe) my interest rate when I didn’t change anything?”

    The answer almost always traces back to one key number — the Overnight Policy Rate (OPR).

    Let’s break down how OPR is derived, who decides it, and how it directly affects your housing loan, business financing, and even fixed deposits.


    What Is OPR?

    Bank Negara Malaysia (BNM) uses the Overnight Policy Rate (OPR) as its main monetary policy tool.

    The OPR is the interest rate at which banks lend money to one another overnight. It serves as the benchmark rate that influences all other interest rates in the country.

    Think of it as the “master switch” of Malaysia’s financial system.


    How Is OPR Derived?

    OPR is not randomly adjusted. It is decided by BNM’s Monetary Policy Committee (MPC) based on several key economic indicators:

    1️⃣ Inflation (Price Stability)

    If inflation is rising too quickly, BNM may increase OPR to slow down spending and borrowing.
    If inflation is low or the economy is weak, BNM may reduce OPR to stimulate growth.

    2️⃣ Economic Growth (GDP)

    Strong economic growth may lead to higher OPR to prevent overheating.
    Weak GDP growth may lead to lower OPR to encourage borrowing and investment.

    3️⃣ Employment & Consumer Spending

    High unemployment? Lower OPR to boost activity.
    Strong consumer demand? Possibly tighten policy.

    4️⃣ Global Economic Conditions

    US Federal Reserve rates, global trade trends, currency strength, and geopolitical risks all influence Malaysia’s monetary decisions.

    5️⃣ Financial System Stability

    BNM ensures banks remain liquid and stable. OPR adjustments help manage systemic risk.

    In simple terms:

    OPR balances growth and inflation.


    How OPR Affects Banks’ Interest Rates

    When OPR changes, banks adjust their benchmark rates such as:

    • BR (Base Rate)
    • SBR (Standardised Base Rate)

    Most housing loans today are priced as:

    SBR + Spread (e.g., SBR + 1.5%)

    When OPR increases:

    • SBR increases
    • Monthly instalments increase
    • Loan affordability reduces

    When OPR decreases:

    • SBR decreases
    • Monthly instalments reduce
    • Borrowing becomes cheaper

    Example: How It Impacts a Housing Loan

    Let’s say:

    • Loan: RM500,000
    • Tenure: 35 years
    • Rate: SBR 3.00% + 1.50% = 4.50%

    If OPR increases by 0.25%:

    • SBR may rise to 3.25%
    • New rate becomes 4.75%
    • Monthly instalment increases

    Even a 0.25% increase can mean thousands of ringgit extra over the loan tenure.

    This is why property investors must monitor OPR closely.


    Impact on Different Groups

    🏠 Homeowners

    Higher OPR = higher instalments (if on floating rate).

    🏢 Property Investors

    Rental yield may be squeezed if instalments rise but rental cannot increase proportionally.

    💼 Businesses

    Cost of financing increases, affecting expansion decisions.

    💰 Savers

    Good news — Fixed deposit rates usually improve when OPR rises.


    Why OPR Matters in Property Strategy

    As a developer consultant and property strategist, I always advise clients:

    Don’t only calculate today’s instalment. Stress-test at +1% or +2%.

    Markets move in cycles. OPR will not stay low forever.

    Smart investors:

    • Lock in good spreads during low-rate environments
    • Structure debt efficiently
    • Maintain cash flow buffers

    Final Thoughts

    OPR is not just a technical banking term.

    It is the heartbeat of the financial system, influencing property prices, loan affordability, rental yields, and overall market sentiment.

    Understanding how it works allows you to:

    • Make better borrowing decisions
    • Time property acquisitions strategically
    • Structure financing intelligently

    If you are planning your next property move, always ask:

    “What is the interest rate cycle telling me?”

    Because in property investing,
    Timing and financing strategy often matter more than price.

  • LHDN Just Released the 2025 Tax Relief List

    LHDN Just Released the 2025 Tax Relief List

    LHDN Just Released the 2025 Tax Relief List

    Here’s What You Can Claim Before the Year Ends

    LHDN has officially released the 2025 Income Tax Relief List, and this is one update every Malaysian taxpayer should pay attention to — especially employees, business owners, and property investors.

    Why?
    Because tax reliefs are legal ways to reduce your tax payable, yet many Malaysians either under-claim or miss them entirely due to poor planning or last-minute filing.

    Let’s break down what this means and how you can optimise your tax position before the year ends.


    What Is the LHDN Tax Relief List?

    The LHDN Tax Relief List outlines approved expenses that taxpayers can deduct from their chargeable income when filing their annual income tax return.

    Simply put:
    👉 The more legitimate reliefs you claim, the less tax you pay — legally.

    This list is updated periodically to reflect:

    • Rising cost of living
    • Education and healthcare needs
    • Retirement and family responsibilities
    • Digital and lifestyle expenses

    Key Tax Reliefs Malaysians Can Claim in 2025

    Below are some of the most commonly used — yet often under-claimed — tax reliefs for YA 2025.


    1. Individual & Dependent Relief

    • Individual relief: RM9,000
    • Spouse (no income): RM4,000
    • Child relief: up to RM8,000 per child (higher for education level)

    👉 Ensure your spouse and children details are properly declared.


    2. Lifestyle Expenses (Up to RM2,500)

    This remains one of the most popular reliefs, covering:

    • Books, journals, magazines
    • Sports equipment
    • Computer, smartphone, tablet
    • Internet subscription

    ⚠ Keep receipts — LHDN may request proof.


    3. Medical Expenses (Self, Spouse & Parents)

    You can claim medical expenses for:

    • Serious diseases
    • Medical check-ups
    • Dental treatment
    • Special needs and disabilities

    Claims can go up to RM8,000, depending on category.


    4. EPF, Insurance & Retirement Planning

    One of the most powerful tax-saving tools:

    • EPF contributions: up to RM4,000
    • Life insurance: up to RM3,000
    • PRS contributions: additional relief available

    👉 Smart retirement planning = lower tax + future security.


    5. Education & Skill Development

    You may claim:

    • Self-education fees (recognised courses)
    • Professional certifications
    • Postgraduate studies

    This is especially relevant for professionals and business owners upgrading their skills.


    6. Housing-Related Reliefs (If Applicable)

    Depending on eligibility:

    • Housing loan interest relief (subject to conditions)
    • First-time homebuyer incentives (if applicable)

    ⚠ These are often misunderstood — get proper advice before claiming.


    Common Mistakes Taxpayers Make

    From my experience, many taxpayers:

    • Rush to file without reviewing reliefs
    • Lose receipts and documentation
    • Assume certain expenses are “not claimable”
    • Follow advice from unverified online sources
    • Claim incorrectly and risk penalties later

    Remember:
    ❌ Under-claiming = paying more tax than necessary
    ❌ Wrong claiming = penalties and audit risk


    What You Should Do Before Year End

    Here’s a simple checklist:

    ✔ Review the 2025 relief list early
    ✔ Plan major expenses before 31 December
    ✔ Organise receipts digitally
    ✔ Review EPF, insurance, and PRS contributions
    ✔ Seek advice if you have rental or business income

    Tax planning is not done in April — it’s done before December ends.


    Final Thoughts from Miichael

    Tax reliefs are not loopholes — they are government-approved incentives meant to ease financial burden.

    Those who benefit most are not the highest earners —
    but those who plan early and claim correctly.

    If you’re unsure what you can claim, especially as a property investor, freelancer, or business owner, get clarity before filing.

    From the desk of

    Miichael Yeoh

  • Residential Property & Mortgage Trends in Malaysia (2026 and beyond)

    Residential Property & Mortgage Trends in Malaysia (2026 and beyond)

    By Miichael Yeoh

    The Malaysian property market has been through a lot in the last few years — pandemic, inflation, rising construction costs, slow wage growth, and changing buyer behaviour. But as we step into 2025, one thing is clear:

    Property is still moving… but the market is no longer the same.
    Buyers are more cautious, banks are more selective, and affordability remains a major issue.

    Here’s my take on what’s really happening in the residential property and mortgage landscape, and what you should pay attention to — especially if you’re planning to buy, invest, or restructure your loans.


    📈 Long-Term Price Trend: Property Still Moves Up

    Whether the market is “good” or “bad”, one fact remains consistent:

    Property prices in Malaysia have been rising steadily for the last 20+ years.

    Urban areas like Klang Valley, Penang and Johor consistently show appreciation because of:

    • population growth
    • job concentration
    • infrastructure development
    • scarcity of prime land

    But here’s the catch:
    House prices have risen much faster than income, making affordability the No.1 challenge for Malaysians today.

    This explains why many young buyers are stuck deciding between renting longer… or compromising on location and size.


    🏘️ What’s Happening in the Market Now?

    1. Transaction volume is rising — but buyers are choosy

    2024 recorded strong growth in overall property transactions, and 2025 is projected to see single-digit positive growth.
    People are buying — but not blindly.

    Buyers today compare:

    • price per sq ft
    • rental potential
    • exit value
    • access to MRT / LRT
    • developer reputation

    Gone are the days when anything “new launch” can sell out.
    Today, value matters more than hype.


    💰 Mortgage & Financing Trend: Here’s the Real Story

    The biggest shift recently is OPR dropping to 2.75%, making borrowing cheaper.

    This directly means:

    • Lower monthly instalments
    • Higher loan eligibility
    • Better cashflow for investors

    But with great news comes reality…
    Banks are approving loans more carefully than ever.

    Your CCRIS, CTOS, commitments and even gig-income consistency matter.
    If your financial health is not clean, even a low OPR won’t help you.

    For many Malaysians, the challenge isn’t interest rate — it’s getting the loan approved.


    🧱 Supply vs Demand: The Affordable Gap

    You’re hearing this everywhere:

    “So many houses unsold!”
    —but at the same time—
    “I can’t find any home I can afford!”

    Why?
    Because the overhang is mainly:

    • too expensive for the mass market
    • too big (1,000 sq ft and above)
    • wrong location

    This mismatch will continue unless developers pivot more aggressively into the mid-market segment.


    🧭 What Buyers & Investors Should Look At Now

    ✔️ If you’re a first-time buyer

    This is a golden window.
    Low OPR + many choices + developers offering incentives = value for money.

    Look for:

    • good location > big size
    • future MRT/LRT corridors
    • reputable developers
    • high rental demand areas

    ✔️ If you’re an investor

    Capital gain will still happen — but don’t expect overnight appreciation.
    Focus on:

    • rental yield
    • undervalued areas
    • distress or motivated sellers
    • T.O.P. projects with ready tenants

    The smart investors in 2025 are not speculating.
    They’re buying below market value, or in growth corridors, or early in new infrastructure zones.

    ✔️ If you own multiple properties with loans

    This is the best time to:

    • refinance
    • consolidate debts
    • reset your cashflow
    • restructure your portfolio

    A small adjustment in interest rate can save thousands per year.


    🧩 Conclusion: The Market Isn’t Booming, But It’s Moving

    Malaysia’s residential market today is stable, resilient, and buyer-driven.
    We’re not in a bubble.
    We’re not in a crash.

    We’re in a value-driven market, where the winners are:
    ✔️ informed buyers
    ✔️ strategic investors
    ✔️ those who manage their loans wisely

    If you understand the trends — and you know how to analyse value correctly — 2025-2026 can be a very profitable year for you.

  • 🇲🇾 Malaysia Budget 2026: What Property Buyers and Investors Need to Know

    🇲🇾 Malaysia Budget 2026: What Property Buyers and Investors Need to Know

    By Miichael Yeoh | October 11, 2025

    The Malaysian Budget 2026 was tabled yesterday by Prime Minister and Finance Minister Dato’ Seri Anwar Ibrahim, themed “Memacu Ekonomi MADANI: Memperkasa Rakyat.”

    With a total allocation of RM470 billion, this budget continues the government’s commitment to building a fair and inclusive economy — with property and housing once again taking center stage.

    Here’s my summary and insight on what Budget 2026 means for property buyers, developers, and investors.


    🏡 1. Stamp Duty Exemption Extended for First-Time Buyers

    Good news — the full stamp duty exemption on both the instrument of transfer and loan agreement for first-time buyers remains in place until 31 December 2027.

    This applies to residential properties priced up to RM 500,000.

    👉 What this means:
    If you’re planning to buy your first home, your upfront costs remain much lower. For many young Malaysians, this can be the difference between “maybe later” and “buy now.”


    💰 2. Bigger Housing Loan Guarantee (SJKP Doubled to RM 20 Billion)

    The Housing Credit Guarantee Scheme (SJKP) is being expanded from RM 10 billion to RM 20 billion, expected to help over 80,000 first-time buyers — including self-employed, gig workers, and informal earners.

    👉 What this means:
    Loan approvals should become easier. This is crucial for those who may not have formal payslips but have consistent income — a growing segment of today’s workforce.


    🌍 3. Higher Stamp Duty for Foreign Buyers

    To cool speculative buying, stamp duty for non-citizens and foreign companies buying residential properties will rise from 4% to 8%.

    Permanent residents (PRs) are not affected.

    👉 What this means:
    Foreign investors will likely focus only on premium areas like KLCC, Mont Kiara, and Penang island. For locals, this could mean less competition — and potentially better entry prices.


    🏢 4. Tax Deduction for Converting Commercial Buildings into Homes

    A forward-thinking move — developers who convert old commercial buildings into residential use can now claim a 10% tax deduction (up to RM 10 million) on eligible renovation costs.

    👉 What this means:
    Expect more adaptive reuse projects — turning old offices or malls into apartments or co-living units. This could help rejuvenate urban centers while reducing idle property stock.


    🏠 5. Support for Rent-to-Own (RTO) and Build-Then-Sell (BTS) Schemes

    Banks are encouraged to support RTO and BTS housing models to make ownership easier and reduce project abandonment.

    👉 What this means:
    More flexibility for buyers who can’t yet afford a traditional down payment, and stronger assurance that projects are completed before full payment.


    👨‍💼 6. Higher LPPSA Loan Limit for Civil Servants

    The Public Sector Home Financing Board (LPPSA) limit will increase to RM 1 million in 2026.

    👉 What this means:
    Civil servants can now afford better homes in urban areas without needing multiple loans.


    🧱 7. RM 672 Million for Affordable Housing and Repairs

    The government is allocating RM 672 million for:

    • Affordable homes (Residensi Rakyat, Rumah Mesra Rakyat)
    • Refurbishing old or dilapidated houses
    • Maintenance for low- and medium-cost flats (e.g. lift replacements)

    👉 What this means:
    Positive for social stability and overall living quality. Also good news for contractors and local developers involved in affordable housing.


    ⚙️ 8. Construction and Tax Updates

    • SST on construction services will apply for new contracts from 1 Jan 2026.
    • Carbon tax will begin in stages, affecting material costs (cement, steel).
    • These may slightly raise overall building costs — developers should factor this into pricing.

    🔎 My Insights: What to Watch in 2026

    1. Affordable and Mid-Range Housing
      Remains the government’s priority. Buyers in this segment have strong support — expect steady demand.
    2. Conversion Projects = Hidden Opportunity
      Old commercial spaces could become the next hot residential spots. Developers who act early may gain an edge.
    3. Foreign Demand Softens, Local Focus Strengthens
      With higher duties, foreign demand may dip — but this creates more room for local owner-occupiers and long-term investors.
    4. Construction Cost Pressure
      SST and carbon-related costs might raise project expenses by 3–5%. Efficient developers with strong cash flow will manage better.
    5. Financing Still Key
      Even with incentives, loan approval remains the biggest hurdle. Buyers should prepare documentation properly (income proof, CCRIS record, existing commitments).

    📈 Final Thoughts

    Budget 2026 shows that Malaysia is moving toward a more sustainable and inclusive housing market — one that balances affordability with innovation.

    For homebuyers, it’s a window of opportunity to act while incentives are strong.
    For investors, it’s time to look beyond traditional launches and explore conversion, rental, and co-living strategies.
    And for developers, the message is clear — adapt fast, innovate smart.

    The property market in 2026 will favor those who understand trends early and act strategically.

  • Boost Your Loan Approval Chances in Malaysia

    Boost Your Loan Approval Chances in Malaysia

    Malaysian bank lending (especially for property purchases) is currently shaped by several key monetary, regulatory, and market-demand factors. Rates have been easing somewhat, but approval conditions remain cautious. Below are the latest numbers and trends.


    Current Figures & Trends

    1. Overnight Policy Rate (OPR) & Reference Rates
      • In July 2025, Bank Negara Malaysia (BNM) cut the OPR from 3.00% to 2.75% – the first cut in five years.
      • Major banks have adjusted their Standardised Base Rate (SBR) to 2.75% per annum following the OPR cut.
      • Base Rate (BR) has also been adjusted (for many banks) in line with this, though BR tends to be higher than SBR. For example, Alliance Bank’s BR is about 3.57%.
    2. Base Lending Rate / Base Financing Rate (BLR/BFR)
      • The BLR or BFR (for Islamic financings) for many banks remains in the ~6.35% to ~6.65% range. For example, Maybank’s BLR is 6.40%, Hong Leong Bank’s is ~6.64%, etc. baserate.my+3Maybank2u+3NewPages+3
    3. Effective Housing Loan Rates
      • While the base/reference rates give a starting point, effective lending rates (what borrowers actually pay) tend to be higher because banks add a margin/spread depending on risk, loan amount, tenure, etc.
      • Recent reports suggest effective rates for housing loans are in many cases 4.15% to 5.7% p.a. depending on bank, borrower profile, loan value, promotion, etc. Property Genie
    4. Loan Approval & Volume
      • There was a 25.7% month-on-month increase in approvals of housing-loan applications in July 2025 after a slump in June. Focus Malaysia – Business & Beyond
      • The approval ratio (i.e. approved vs applied) in July 2025 was about 44.8%, up from ~42.6% in June 2025. Focus Malaysia – Business & Beyond
      • On a year-on-year basis, total approved loan volume declined by ~5.1% for that month; cumulatively over the first 7 months of 2025, approved property loans were ~RM 161.4 billion, about -1.5% relative to same period in previous year. Focus Malaysia – Business & Beyond
    5. Outlook
      • With lower OPR and more competitive base/reference rates, there is optimism that loan approvals (both volume and ratio) may improve in the remaining months of 2025. Government’s likely to include incentives in Budget 2026 to support first-time buyers, low-to-middle income groups. Focus Malaysia – Business & Beyond

    Steps Borrowers Can Take to Increase Chances of Loan Approval

    Given the current environment, borrowers can do several things to strengthen their applications and improve likelihood of approval. Here are practical steps, both before and during application.

    StepWhat to DoWhy It Helps
    1. Check & Clean Up Your Credit HistoryObtain your credit report (e.g. through CTOS, CCRIS, Experian) ahead of time. Ensure there are no outstanding defaults, ensure credit card/HP payments are on time.Banks check creditworthiness; a clean credit history reduces risk and may allow you to access better rates.
    2. Assess Debt Service Ratio (DSR) / Total CommitmentsKnow your monthly obligations: other loans, credit cards, etc. Make sure your net income minus all obligations leaves enough room for loan instalments. Try to reduce existing liabilities if possible.Banks often reject or charge higher margins if your debts relative to income are too high. Lower commitments improves affordability assessment.
    3. Have Stable & Adequate IncomeDemonstrate consistent employment or business income; have documentation (pay slips, tax returns, EPF contributions). If self-employed or commission-based, provide past 2-3 years’ income statements, audited if possible.Stability & predictability of income give banks confidence in your ability to repay.
    4. Make Reasonable Down Payment / EquityThe more you put down (lower loan-to-value ratio), the less risk for the bank. If you’re first-time buyer programs exist (often requiring only 10% payment), check eligibility, but be aware these may still have stricter conditions.Less loan amount relative to property value helps bank exposure and reduces margin required.
    5. Choose Appropriate Loan TenureLonger tenure reduces monthly instalments but increases total interest paid; very long tenure may raise risk from bank’s perspective (future rate changes, income changes). Balance payroll constraints with ability to service.A manageable monthly repayment improves approval chances; less risk of default.
    6. Prepare All Supporting Documents ProperlyHave ready: identity documents, employment letters, income proof, EPF statements, tax returns (if applicable), bank statements, any other asset documentation. Ensure documents are current.It speeds up processing and reduces grounds for rejection due to missing information.
    7. Shop Around & Compare OffersDifferent banks have different margins, promotions, and underwriting criteria. Get multiple quotes. Negotiate (sometimes banks reduce spread or offer incentives).May get better rate, lower fees, more favorable terms.
    8. Provide Clear Purpose & Property DetailsHave the Sale & Purchase Agreement (SPA), valuation report (if needed), title deed, property details, etc. If property is new or under construction, ensure developer’s track record and required approvals are in order.Banks assess property risk as well: location, title, developer credibility affect approval.
    9. Maintain Good Savings / ReservesHaving savings or avoid fully depleting your accounts helps; having reserves gives cushion in case of rate increases or unexpected expenses.Shows financial discipline and lowers risk from bank’s viewpoint.
    10. Understand Bank Fees & RequirementsBe aware of legal fees, valuation fees, stamp duties, insurance (MRTA/MRTT), and any bank-specific requirements (e.g. guarantor, joint-applicant). Make sure to budget for them.Unexpected costs can derail the process; being well-prepared ensures smoother approval.

    Challenges & What Borrowers Should Watch Out For

    • Even with OPR at 2.75% and SBR adjusted, banks’ margins/spreads can still be high depending on borrower risk. So effective rates may still be less favourable for some.
    • Approval ratios (~44-47%) show that over half of applications still get declined. That means it’s not just about rates; credit & affordability are being closely scrutinized. Focus Malaysia – Business & Beyond
    • Rising costs for legal fees, valuation, and sometimes hidden fees can make total cost of financing higher than expected.
    • Inflation, future rate rises, economic uncertainties mean banks may reserve right to tighten conditions suddenly.


    Conclusion

    Bank lending is currently becoming somewhat more favourable in Malaysia thanks to the OPR cut and adjusted reference rates. However, borrowers must still present strong, well-prepared loan applications. Cleaning up credit, reducing existing obligations, having stable income and proper documentation, and choosing appropriate loan terms are all crucial.

  • Inheritance Law and Joint Ownership Explained

    Inheritance Law and Joint Ownership Explained

    Written by Jocelline Chee from Rightwill | Edited by Miichael Yeoh

    When it comes to inheritance, things can get complicated—and emotional—especially when property is involved. In Malaysia, many people assume that putting property under joint names (like with a spouse or child) will make things smoother when someone passes away. Unfortunately, it’s not always that simple.

    If you’re planning to leave a property behind for your loved ones, it’s important to understand how inheritance laws work in Malaysia and the potential problems that can pop up with joint ownership.


    🏛️ How Inheritance Works in Malaysia

    Inheritance laws in Malaysia depend on your religion:

    • For Muslims, faraid (Islamic inheritance law) applies. It has fixed rules on how the estate is divided among family members.
    • For non-Muslims, the Distribution Act 1958 (amended in 1997) applies. This Act lays out who gets what—based on whether the deceased leaves behind a spouse, children, or parents.

    If someone dies without a will, the law decides how the assets are shared. That’s why it’s so important to have a valid will—it ensures your wishes are followed.

    Example under the Distribution Act:

    If the deceased leaves behind…Parent(s) getSpouse getsChildren get
    Parents, spouse & children1/41/41/2

    🏠 Joint Name Properties – Not As Simple As You Think

    Many Malaysians put properties under joint names thinking it will automatically go to the other person when they pass away. But that’s not always true.

    There are two main types of joint ownership in property law:

    1. Joint Tenancy
      • Comes with the right of survivorship.
      • If one owner dies, the property automatically goes to the surviving owner.
      • This is common among married couples.
    2. Tenancy in Common
      • Each person owns a specific share.
      • When one dies, their share becomes part of their estate and is distributed according to their will or the law.
      • This is more common in Malaysia, even when it’s between family members.

    Here’s the catch: Most joint name properties in Malaysia are actually treated as tenancy in common, unless stated otherwise. That means—even if your name is on the title—the other person’s share doesn’t automatically go to you. It becomes part of their estate and is shared out according to their will or inheritance laws.


    ⚠️ Common Pitfalls to Watch Out For

    1. Unclear Ownership Type
      If it’s not clearly stated whether it’s joint tenancy or tenancy in common, it can lead to confusion—and disputes.
    2. Unequal Contributions
      One person may have paid more, but the property is split 50-50 on paper. This often leads to disagreements among family members.
    3. Family Conflicts
      Things can get messy with children from previous marriages, siblings, or estranged family members. Without clear planning, emotions can take over.
    4. Outdated or No Will
      A will that hasn’t been updated—or worse, no will at all—can cause contradictions and legal battles during probate.

    ✅ What You Should Do

    To protect your assets and your loved ones from future disputes:

    • ✅ Talk to a professional estate planner or lawyer
    • ✅ Make sure your will is valid, updated, and matches your current ownership structure
    • ✅ Clearly state the type of joint ownership on your property documents
    • ✅ Keep your family informed, so there are no surprises later

    Joint ownership may seem like the easy way, but without proper planning, it can create unnecessary complications. A little preparation now can give your family peace of mind in the future.

    From the desk Of

    Miichael Yeoh
    Property Strategist

    Thank you for subscribing!

    Please check your email to confirming your subscription.

  • Why Every Condo Owner Must Pay Maintenance Fees

    Why Every Condo Owner Must Pay Maintenance Fees

    By Ken Teo | Edited by Miichael Yeoh

    Let’s Start with This: You’re Not Just Buying a Unit — You’re Buying Into a Community

    When you own a condo, apartment, or any kind of strata property, you’re not just buying four walls. You’re also sharing ownership of everything outside your unit — the lifts, the corridors, the lobby, the pool, the roof, the water tank, the whole building.

    That’s why every owner needs to pay maintenance fees and contribute to the sinking fund. It’s not a donation. It’s not optional. It’s your duty as a co-owner.

    Let’s break it down in plain language…


    1. These Are Not “Extra Charges” — They’re Your Legal Responsibility

    Under Malaysia’s Strata Management Act 2013 (Act 757):

    • Section 25(1) (for Joint Management Body or JMB), and
    • Section 50(1) (for Management Corporation or MC),

    …it clearly says: every unit owner must pay maintenance charges and sinking fund contributions.

    These are not surprise charges or “admin fees.” They’re meant to cover your share of keeping the building clean, safe, and in working condition. It’s the same as chipping in for house bills when you live with housemates — it’s only fair.


    2. “If Others Don’t Pay, Why Should I?”

    This is a common complaint — and hey, we get it. Why should you be the good guy when others are skipping out?

    But think about this:

    • If no one pays, who’s going to fix the lift?
    • Who’s going to pay the cleaners or security guards?
    • How will the broken tiles or leaking roof ever get fixed?

    When people stop paying, the whole building suffers. And soon, even those who were paying start asking: “Why should I continue?” — and that’s when things spiral downhill.

    You don’t just live in your unit. You share ownership of the entire building. So if everyone pays their part, everyone enjoys a better home.


    3. What Happens If You Don’t Pay?

    The law doesn’t just suggest — it enforces. If you don’t pay, the JMB or MC has the right to take action under Section 60(3) of the Strata Management Act.

    Here’s what they can legally do:

    • Send you demand letters
    • File a claim with the Strata Tribunal or even in court
    • Charge up to 10% interest per year on overdue amounts
    • Block your access to facilities (like pool, gym, function room), with proper notice

    So it’s not just about being fair to others — not paying could cost you more later, both in fees and reputation. And your outstanding dues? They’ll follow your unit, even if you try to sell.


    4. Think of It as an Investment — Not a Burden

    No one enjoys paying bills, we know that. But your maintenance charges are not “just another bill.” They’re an investment in your own home.

    The money goes into:

    • Repairs and upkeep
    • Security and cleanliness
    • Ensuring your home is safe and comfortable
    • Keeping your property value high

    Ever seen a badly maintained condo? Low resale value, fewer buyers, and complaints all around. Compare that to a well-managed building — units there sell faster and at better prices.


    5. You Have the Right to Know Where the Money Goes

    Worried that your money is being misused? The good news is: you have rights.

    By law, the JMB or MC must:

    • Hold Annual General Meetings (AGM)
    • Present audited accounts and budgets
    • Use the sinking fund for long-term repairs like repainting, roofing, waterproofing, and lift upgrades

    As an owner, you can (and should):

    • Ask for financial reports
    • Question how funds are being spent
    • Vote during AGMs

    This is your money. And you deserve to know how it’s used.


    In Summary: Don’t Just Own a Unit — Own the Responsibility

    Paying your maintenance fees and sinking fund isn’t just about following the law. It’s about doing your part.

    You’re not a tenant anymore. You’re an owner. You have a stake in the building — and your actions affect everyone else too.

    So instead of thinking “Why me?” — let’s think “Why not us?”

    Let’s build communities, not just condominiums.
    Let’s protect our investments, not neglect them.
    Let’s be the kind of owners who care.

    Because a well-maintained building isn’t just a nicer place to live — it’s something you can be proud to call home.

  • Should You Buy Property in Malaysia Now? Insights 2025

    Should You Buy Property in Malaysia Now? Insights 2025

    Published: July 17, 2025
    By: Miichael Yeoh


    After a strong run in 2023 and 2024, Malaysia’s residential property market is finally taking a breather. While some see this as a red flag, the data paints a more balanced picture—one of resilience and recalibration, not recession.

    So, what exactly is happening in 2025? And should you be worried or ready to buy?

    Let’s break it down.


    📉 Q1 2025: Slower But Still Solid

    Malaysia’s residential property transactions dropped 6.2% in Q1 2025 compared to Q4 2024. That’s the first notable slowdown after nearly two years of consistent growth.

    But here’s the catch: activity levels are still higher than in 2022, which means we’re not seeing a crash—just a cooling-off.

    “The slowdown is expected. It’s the market stabilizing after a hot streak,” said a property analyst from KL.


    📈 Prices Are Still Moving Up

    The national average house price reached RM483,879 in Q1, reflecting a +1.4% year-on-year increase. Areas like Klang Valley, Penang Island, and Johor Bahru continue to dominate in both value and volume.

    Here’s a quick snapshot:

    AreaAvg. Price (Q1 2025)YoY Price Growth
    Klang ValleyRM 550,000+2.1%
    Penang IslandRM 620,000+1.8%
    Johor BahruRM 460,000+1.2%

    🏗️ Developers Stay Selective with New Launches

    With rising construction costs and cautious sentiment, developers are choosing quality over quantity. Most new launches are in well-connected, lifestyle-oriented locations—think smart townships, mixed developments, and green-certified homes.

    Hot-selling projects like Elmina Ridge 2 and Avalon Cybersouth saw near 90% take-up rates, showing buyers are still ready to act—when the product is right.


    🔍 What’s Supporting the Market?

    Despite the slowdown in transactions, several key factors are helping the market stay afloat:

    • Stable interest rates (BNM kept the OPR steady).
    • Low unemployment rate (around 3.3%).
    • Young home-buying population (millennials & Gen Z entering the market).
    • MM2H visa tweaks requiring foreigners to purchase property.

    These are long-term positives that signal stability in the residential segment.


    ⚠️ What Buyers & Investors Should Watch

    While the fundamentals are strong, here are a few caution signs to keep in mind:

    1. Affordability gaps in cities like KL and Penang may limit demand in certain price segments.
    2. Oversupply risks in high-rise areas still exist, especially where demand isn’t organic.
    3. Policy changes—any adjustments to RPGT, stamp duties, or loan rules could shift the playing field fast.

    💡 Final Thoughts

    If you’re a buyer or investor waiting for a market crash—you might be waiting for a while. What we’re seeing now is not the end of growth, but a healthier, more stable market emerging after years of turbulence.

    This could actually be the perfect window to enter—especially if you’re eyeing the right locations, products, and long-term value.

    🗣 “The best time to buy property is when others hesitate—because real opportunity hides in uncertainty.”


    Need help identifying the right property in 2025?
    Join the Property EDU Club — get expert guidance, real-life case studies, and insider access to property deals most investors never see.

    👉 Click here to learn more and join now