Category: Mortgage

  • Malaysia’s Loan Scandal: Consultancies Siphon 35% from Borrowers

    Malaysia’s Loan Scandal: Consultancies Siphon 35% from Borrowers

    A major financial scandal in Malaysia has exposed a corrupt syndicate involving consultancy firms and bank officials, who siphoned 35% of approved loans from borrowers, primarily civil servants. The Malaysian Anti-Corruption Commission (MACC) revealed that these firms manipulated loan processes, securing multiple overlapping loans for victims, leaving them with crippling debts. Over RM700 million in loans were processed, but borrowers received only a fraction after exorbitant fees. The MACC’s ongoing crackdown has arrested 27 individuals and frozen RM22 million in assets, but the financial and emotional toll on victims remains severe.
    Click for more Information or Sign Up

    This issue has persisted for years, with many property buyers enticed to purchase multiple properties beyond their means. For instance, individuals with a RM5,000 salary were lured into buying 10 properties with high cashback offers, only to face financial ruin. In one case, a couple after attending my seminar shared how they were encouraged by a “Property Guru” to buy five properties at once, exploiting bank loopholes. They later discovered the properties were overpriced and unrentable, leaving them bankrupt with RM16,000 monthly installments and two young children to support. This highlights the dangers of reckless investment decisions. Always verify sources, avoid intermediaries charging excessive fees, and ensure investments align with your financial capacity.

    From the Desk of

    Miichael Yeoh

    Read the full article…..

    Bank Loan Scandal: How Consultancy Firms Pocketed 35% from Borrowers’ Loans

    By: Kpost

    A financial scandal of massive proportions has rocked Malaysia’s banking sector, exposing a corrupt syndicate that preyed on borrowers, especially civil servants, by siphoning off exorbitant fees from approved bank loans.

    The Malaysian Anti-Corruption Commission (MACC) recently uncovered that financial consultancy firms, operating under the guise of loan facilitators, were pocketing at least 35% of the approved loan amounts, leaving victims with far less than what they had borrowed.

    A Web of Deceit: How Borrowers Were Trapped

    The scheme involved consultancy firms manipulating the loan approval process in collusion with corrupt bank officials. According to MACC Chief Commissioner Tan Sri Azam Baki, the syndicate exploited desperate borrowers by securing multiple loans from various financial institutions simultaneously, orchestrating a complex scam that resulted in borrowers being burdened with insurmountable debts.

    “These firms orchestrated ‘multiple loans’ by manipulating bank systems and turn-around times, making it seem as if previous loans had been settled when, in reality, they had not. This deception ensured that borrowers would receive overlapping loans, only to have substantial portions deducted as ‘fees,’” said Azam.

    Many victims, entangled in financial distress and seeking funds to settle previous debts, unknowingly agreed to the terms set by these firms. In addition to the 35% consultancy fee, borrowers were also subjected to loan settlement charges of up to 40%, further exacerbating their financial woes.

    RM700 Million in Loans: But Victims Still Drowning in Debt

    The investigation, codenamed Ops Sky, revealed that the syndicate managed to secure approximately RM700 million in loans for borrowers. However, instead of receiving their full loan amounts, victims were left with only a fraction of what they applied for, leading to a debt crisis far beyond their means to repay.

    Despite the dismantling of the syndicate, the damage has already been done. Many victims now owe three times more than their financial capabilities allow, making repayment virtually impossible. “Even though the syndicate has been dismantled, borrowers remain indebted to the banks and must continue servicing their loans,” Azam stated.

    Massive Crackdown: Bank Officers and Syndicate Members Arrested

    In a coordinated crackdown, MACC and Bank Negara Malaysia raided 24 locations across the Klang Valley, including residences and offices linked to the syndicate. The operation led to the arrest of 12 key individuals, including bank officials and employees of the financial consultancy firms involved.

    Further investigations revealed that 98 company and personal bank accounts worth over RM22 million had been frozen, and nearly 4,000 documents seized as part of the evidence collection.

    A total of 27 individuals, including 18 bank officers, eight financial consultancy employees, and one member of the public, were detained before being released on bail.

    Social Media and Celebrities Used to Lure Victims

    Adding another layer to the scandal, the syndicate aggressively marketed its services using social media influencers, celebrities, and public figures to gain credibility.

    Advertisements flooded Facebook, TikTok, and Instagram, targeting schoolteachers, nurses, and government employees.

    The firms even conducted surveys, roadshows, and CSR programs at schools and hospitals, falsely promoting their services as legitimate financial solutions.

    What’s Next? Ongoing Investigations and a Warning to the Public

    The MACC has vowed to continue its investigations under Ops Sky, with more witnesses expected to be summoned. The public is urged to be cautious when dealing with financial consultancy firms that promise easy loans, especially those charging high service fees upfront. “This case serves as a stark warning and always verify loan processes directly with the bank and avoid intermediaries who demand excessive fees,” Azam cautioned.

    As investigations continue, Malaysians are left questioning how such large-scale corruption involving multiple financial institutions could have persisted unchecked for so long. The financial burden on victims remains heavy, and the battle for justice is far from over.

    Information Source: Newswav
  • Effects of OPR Changes on Borrowing and Savings

    Effects of OPR Changes on Borrowing and Savings

    As of January 2025, Bank Negara Malaysia (BNM) has maintained the Overnight Policy Rate (OPR) at 3.00%, a position held since May 2023.

    Understanding the Overnight Policy Rate (OPR)

    The OPR is the benchmark interest rate at which banks lend to one another overnight. Set by BNM, it serves as a primary monetary policy tool to regulate liquidity, control inflation, and sustain economic growth.

    Implications of an OPR Increase

    When BNM raises the OPR, it signals an intent to tighten monetary policy. The effects of such an increase include:

    Higher Borrowing Costs: Banks typically respond to an OPR hike by raising their base rates, leading to increased interest rates on loans and mortgages. This results in higher monthly repayments for borrowers.

    Enhanced Savings Returns: Conversely, depositors may benefit from higher interest earnings on savings and fixed deposits, encouraging increased savings.

    Controlled Inflation: Elevated borrowing costs can dampen consumer spending and business investments, helping to moderate demand-pull inflation.

    Currency Appreciation: Higher interest rates can attract foreign investment, potentially strengthening the Malaysian ringgit.

    Impact on Property Market: Increased interest rates may lead to higher mortgage costs, potentially cooling property demand and affecting market dynamics.

    Recent Economic Context

    In the third quarter of 2024, Malaysia’s economic growth slowed to 5.3% from 5.9% in the previous quarter, influenced by reduced oil and gas production. Despite this, robust household spending and increased investments provided support.

    BNM’s Monetary Policy Stance

    BNM has maintained the OPR at 3.00% since May 2023, citing positive economic growth and steady inflation. Economists anticipate that the central bank will keep the OPR unchanged until at least 2026, aligning with current economic assessments.

    Interest Rate Impact Example

    Let’s look at an example of how interest rates affect property loans. Assume you’re borrowing RM500,000 for 30 years:

    • Current Interest Rate (4.5%): Monthly repayment is approximately RM2,533.43.
    • If OPR Increases by 25 Basis Points (4.75%): Monthly repayment rises to around RM2,608.82.
    • Impact: This increase of RM75.39 per month adds up to RM27,140.40 over the loan’s term.

    This illustrates why understanding interest rates and their potential changes is crucial for planning your finances.

    Conclusion

    An increase in Malaysia’s OPR has multifaceted effects, influencing borrowing costs, savings returns, inflation, currency value, and the property market. Understanding these dynamics is crucial for individuals and businesses to make informed financial decisions in response to monetary policy changes.

    From the Desk of

    Miichael Yeoh

  • Avoid Costly Mistakes: 8 Reasons to Learn Before Investing in Real Estate

    Avoid Costly Mistakes: 8 Reasons to Learn Before Investing in Real Estate

    Purchasing or investing in property is one of the most significant financial decisions a person can make. While the prospect of owning a piece of real estate can be exciting, it’s also fraught with risks and complexities. Here are eight compelling reasons why educating yourself before taking the plunge is crucial:

    1. Understanding the Market

    The property market is dynamic, influenced by factors such as economic conditions, interest rates, and government policies. Without proper knowledge, you might buy at the wrong time or in the wrong location, potentially leading to financial losses. Education helps you grasp market cycles and trends, enabling informed decisions.

    2. Avoiding Costly Mistakes

    From overpaying for a property to falling victim to scams, the risks of making costly mistakes are high for uninformed buyers. Learning about property valuation, legal processes, and common pitfalls can save you from financial heartache.

    3. Maximizing Investment Returns

    Investing in property isn’t just about buying a house or apartment; it’s about choosing assets that will appreciate in value or generate steady rental income. Understanding key metrics such as ROI (Return on Investment) and cash flow can help you identify profitable opportunities.

    4. Navigating Legal and Financial Complexities

    Property transactions involve a maze of legal and financial considerations. From understanding loan agreements to navigating tax implications and zoning laws, there’s a lot to learn. A lack of knowledge could lead to delays or even legal troubles.

    5. Building Confidence

    The more you know, the more confident you’ll feel about your decisions. Knowledge reduces fear and uncertainty, empowering you to negotiate effectively, choose wisely, and stick to your long-term goals.

    6. Identifying Red Flags

    Not all properties are created equal. Structural issues, poor location, and hidden costs can turn a dream investment into a nightmare. Learning to conduct due diligence and property inspections ensures you spot potential problems early.

    7. Accessing Better Financing Options

    Understanding how mortgages and loans work can save you thousands of dollars over the life of your investment. Learning about different financing options and how to improve your creditworthiness can lead to better interest rates and loan terms.

    8. Planning for the Future

    Property investment is a long-term commitment. Learning helps you align your investment choices with your financial goals, whether it’s building wealth, securing passive income, or preparing for retirement. Knowledge enables strategic planning that benefits you in the long run.

    Conclusion

    Investing time and effort into learning before buying or investing in property is an investment in itself. It equips you with the tools and insights needed to make smart, informed decisions that align with your financial aspirations. Remember, in the world of property, knowledge isn’t just power; it’s profit.

  • Unlock Rental Property Success with a Strong DSCR

    Unlock Rental Property Success with a Strong DSCR

    Ever come across the term Debt Service Coverage Ratio (DSCR)? If not, don’t worry—I’m here to simplify it for you. While it might seem complex, DSCR is actually a straightforward concept that plays a crucial role in real estate investing.

    What is Debt Service Coverage Ratio (DSCR)?

    The Debt Service Coverage Ratio (DSCR) is a key metric that assesses whether a property’s income is sufficient to cover its debt obligations. Think of it as a financial report card for real estate investors, showing if a property is financially sustainable. Let’s break it down for easier understanding:

    The DSCR Formula

    DSCR = Net Operating Income (NOI) / Total Debt Service (TDS)

    • Net Operating Income (NOI): The income generated by the property, including rent and other sources, after deducting expenses like maintenance, property management fees, and taxes.
    • Total Debt Service (TDS): The total annual payments required to service the loan, covering both principal and interest.

    How to Interpret DSCR

    • DSCR > 1: The property generates more income than needed to cover its debt—this is a positive sign!
    • DSCR < 1: The property’s income is insufficient to cover the debt—this signals potential risk.

    A higher DSCR indicates a lower risk of default, making the property more attractive to lenders.

    How DSCR Works in Practice

    Let’s see DSCR in action with a practical example:

    1. Net Operating Income (NOI):
      • Peter’s rental property generates RM50,000 annually.
      • Annual expenses total RM20,000.
      • NOI = RM50,000 – RM20,000 = RM30,000.
    1. Total Debt Service (TDS):
      • Peter’s annual mortgage payment is RM24,000.
      • Total Debt Service (TDS) = RM24,000.
    1. DSCR Calculation:
      • DSCR = RM30,000 (NOI) / RM24,000 (TDS) = 1.25.

    With a DSCR of 1.25, Peter’s property generates more income than needed to cover the debt, indicating financial stability and a comfortable margin for loan payments.

    Why DSCR Matters?

    The Debt Service Coverage Ratio (DSCR) is a critical indicator in real estate investing, helping you assess whether a property’s income can cover its debt obligations. Whether you’re looking to own rental properties or simply exploring the real estate market, understanding DSCR is essential for your success. By maintaining a healthy DSCR, you can build a solid foundation for your investments and ensure long-term profitability.

    From The Desk of Miichael Yeoh

    Check out the latest article on how Budget 2025 impacts the property sector

  • Property Investment: Success or Bankrupt?

    Property Investment: Success or Bankrupt?

    Many people are enthusiastic about making money from property investment. After all, who wouldn’t want a reliable safety net for the future? Property can indeed offer financial security, but this is only true if you plan properly and do your due diligence before buying. While it may sound lucrative, without the correct approach, it can quickly turn into a financial disaster.

    I recall an incident that starkly highlights this point. After one of my seminars organized by a property developer, a couple in their 30s approached me. They shared a heartbreaking story: they had declared bankruptcy and had a 6-year-old child to care for. Their downfall began when they followed advice from a so-called property expert and started purchasing properties beyond their financial means. The rental income from these properties was either too low or non-existent, and they couldn’t find tenants. To make matters worse, the so-called expert was nowhere to be found, leaving the couple to face the harsh realities alone.

    What lesson can we draw from this? The pursuit of wealth through property investment can sometimes turn into a nightmare, even if you believe such misfortune won’t happen to you.

    Click Register NOW

    Let’s rewind a bit. Had this couple engaged in proper financial planning, their situation might have been very different. A crucial aspect of financial planning is understanding your monthly income against your expenses. Personally, I wouldn’t consider purchasing a property unless I had at least 12 months of installment payments saved in advance, especially if I had to take a loan from the bank. There is much more to financial planning, but diving into the details would be lengthy. The key takeaway is this: invest within your capacity. Don’t let greed drive your decisions, as it might be too late to turn back once you’re down that road.

    The desire to become a successful property millionaire is understandable, but it’s essential to think carefully before making such a bold step.

    I hope this article opens your eyes to the realities of property investment.

    If you need expert advice on your property investment journey, please email us at info@miichaelyeoh.com.

    From the Desk of Miichael Yeoh

  • Discover The Keys to Successful Property Investment (Live Webinar)

    Discover The Keys to Successful Property Investment (Live Webinar)

    Are these familiar struggles for you?

    🏠 Feeling lost in the world of property investment?

    💰 Watching your investments drain your finances?

    😱 Scared off by terrifying investment horror stories?

    💸 Struggling to secure funds for investment?

    🏦 Facing obstacles getting a loan from the bank?

    🔍 Bought a property but can’t find a tenant?

    You’re not alone. But here’s what awaits you on the other side:

    • Witnessing others prosper through property investment while you sit on the sidelines.
    • Regretting missed opportunities for passive income generation.
    • Reflecting on how better financial planning could have changed your life.

    What’s in store for you at my seminar?

    🔍 Insights to equip yourself for successful property investment.

    ⚠️ Awareness of common pitfalls to avoid in the property market.

    🏡 Understanding the crucial components of property investment.

    📊 Appreciation for the importance of property data analysis.

    🔍 Guidance on conducting thorough due diligence before buying.

    💼 Experience the transformative power of effective financial planning.

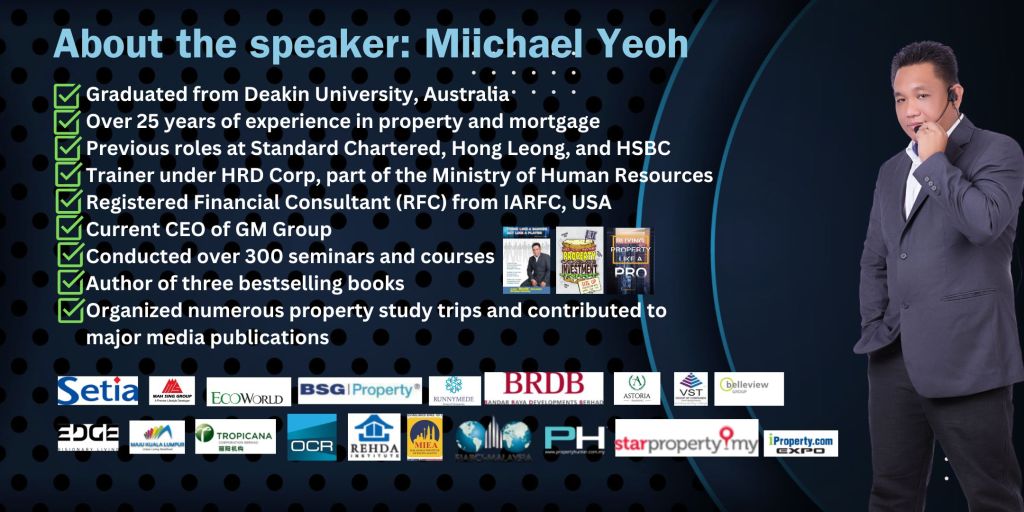
    Audiences and events I’ve spoken and organized for property buyers/investors, developers, conventions, and property study trips.

    Don’t let uncertainty or fear hold you back! Join me and unlock the doors to a brighter financial future!

    Register your FREE SEATS Now as seats are limited…..

    See you soon,

    Miichael Yeoh

  • From Property Millionaire to Property Millionhair

    From Property Millionaire to Property Millionhair

    Many individuals aspire to become property millionaires. They immerse themselves in books, seminars, and courses, each with their own pace – some favoring quick success, while others opt for a slower, steadier approach. What’s your preference?

    But caution is warranted. Sadly, many who aspire to property wealth end up with a different outcome – becoming “property millionhairs” instead. Take Jerry, for example (not his real name). Despite a net income of RM5K, he impulsively purchased five properties at once, enticed by promises of a RM200k cashback per unit. With five units, he envisioned instant wealth. However, blinded by the prospect of millionaire status, he overlooked critical details, such as the absence of the cashback clause in the contract.

    To realize his dream, Jerry enlisted his girlfriend’s help to secure mortgage approval, as his income alone wasn’t sufficient. The terms seemed promising – the cashback would be disbursed upon the bank’s final payment release, just a few months away. Jerry was ecstatic, anticipating wealth raining down on him.

    When the cashback arrived, Jerry felt like royalty. His eyes gleamed with newfound riches, and he indulged in extravagant purchases – a RM300k car, luxury watches, jewelry, and more. He also spent a substantial sum renovating his properties for potential tenants.

    Yet, eight months later, reality set in. Jerry’s million was dwindling rapidly, with vacant units generating no income to offset his hefty RM12k monthly mortgage payments. Facing financial ruin, he discovered his properties were valued 40% below their purchase price, rendering them unsellable without further financial strain.

    Do you want to emulate Jerry’s fate? Consider these warnings:

    Packages like Jerry’s often involve properties with poor marketability.

    Jerry’s scheme of securing multiple loans or called compression method with a single income is fraudulent and can lead to legal consequences.

    Jerry may have salvaged some funds, but others haven’t been as fortunate. I’ve encountered individuals on the brink of bankruptcy, struggling to provide for their families, a heartbreaking reality.

    Banks are now more vigilant, scrutinizing loan applications meticulously to prevent such misfortunes. Yet, at the heart of it lies human greed, fueled by promises of grandeur.

    For me, prudence reigns supreme. I advocate for careful planning, eschewing shortcuts for a methodical approach. If I can’t cover at least 12 months of mortgage payments, I refrain from purchasing, no matter how enticing the property. Financial responsibility dictates my decisions. To everyone out there, heed this advice: stay within your means. When deals seem too good to be true, exercise caution. Protect your financial well-being, for our lives are invaluable.

    From the Desk of Miichael Yeoh

  • Praying For Luck in Mortgage Approval

    Praying For Luck in Mortgage Approval

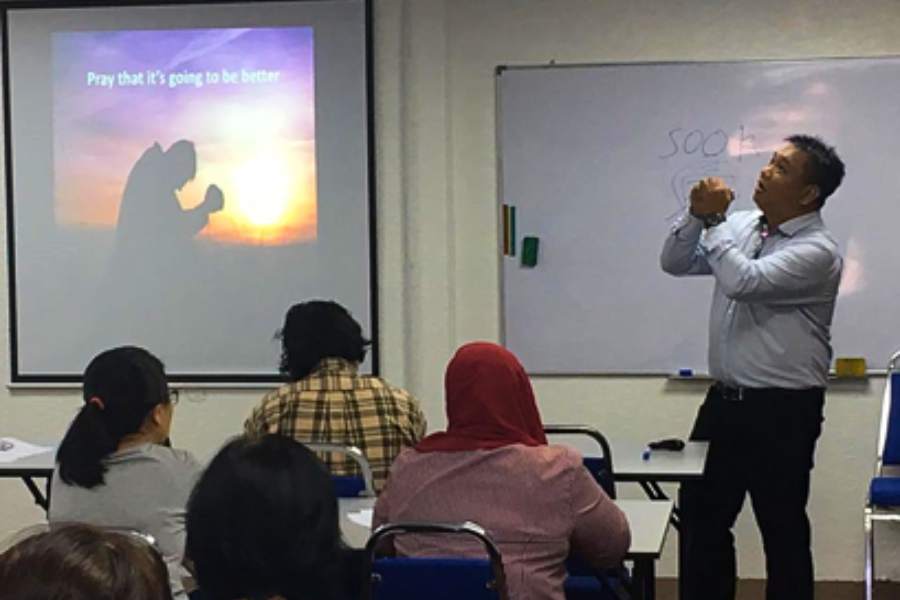
    In the picture, what do you think I am doing? Praying for the money to drop

    I do not really depend on these. I don’t think money will suddenly drop from the sky or hoping for a miracle to happen. If a car were to break down, you will need a mechanic to fix the problem. He will have to follow a series of steps in doing repair and to make sure your car is running again.

    Likewise, in mortgage approval you cannot wait for miracle things to happen. To me, luck have nothing to do on mortgage approval. Many borrowers and agents, prefer to photocopy many stacks of financial documents and give to every bank they know off or can find and submit to them for approval. Is this the right way?

    Do you know that every time your documents are submitted, the banks will record and send to Bank Negara which in turn will update the Central Credit Information System (CCRIS) every month? No matter whether your loan is approved or rejected it will be updated on the last page of your record. Let’s say Bank A rejects your loan, Bank B,C and D also rejects but Bank E actually can approve your loan but seeing so many banks rejected your loan the chances are they will also reject your loan.

    Never expose yourself. Every bank have different approval criteria. Some banks might not like you but some does. I have a case once, his Debt Service Ratio is very high at 150% in which is higher than the normal 70-85%. Either the banks rejects or do not want to waste time processing his case. I reviewed his documents and to cut things short, I managed to get 70% loan approval. This case is a fine example where the borrower will have to do the following:

    • Do a Know yourself (KYS) test.
    • Check your credit status
    • Check which bank is suitable for you.

    You will have to do more work on the last step. You will need to find out each bank approval criteria and also the different types of documents for approval. You are not buying a RM1,000 property but hundreds or even millions worth of property. It is good to do a research first. It is hard to go back when your loan had been rejected. It is easier to diagnose a problem first.

    Related article https://miichaelyeoh.com/2024/04/07/what-you-should-do-before-applying-a-loan/

    From the desk of Miichael Yeoh

  • BNM Maintain OPR at 3% – Updated 9th May

    BNM Maintain OPR at 3% – Updated 9th May

    Bank Negara Malaysia (BNM) has announced today (9th May 2024) that the Overnight Policy Rate (OPR) will remain steady at 3%. This rate has remained unchanged since May 2023, marking a year of consistent monetary policy.

    The monetary policy meets six times annually to deliberate on the OPR.

    Source: BNM

    Looking ahead , there is uncertainty surrounding whether the OPR will stay at 3% or increase further. Historically, the highest OPR since April 2015 was 3.50%, and the lowest was 1.75% in July 2020 during the COVID-19 pandemic. Typically, changes in the OPR are made in increments of 25 basis points (0.25%).

    As for the likelihood of an OPR increase this year, it appears unlikely that there will be a reduction in the near future. Instead, the OPR will either hold steady or increase depending on several factors:

    1. EPF Withdrawals: Starting May 11, 2024, contributors to the Employees Provident Fund (EPF) can withdraw from Account 3 at any time, potentially leading to RM25 billion (around 1.3% of GDP) in withdrawals. This could result in increased demand-driven inflation.
    2. Civil Service Salary Hike: There may be a raise in civil service salaries by over 13% beginning in December, which could also contribute to inflationary pressures.
    3. Fuel Subsidy Rationalization: Implementation of fuel subsidy rationalization could occur in 2025 or earlier, which may further increase inflation risk.

    Get ready to seize this incredible opportunity and make your purchase! Get your copy NOW…

    Given these factors, my prediction is that the OPR is likely to remain unchanged at 3% this year, but it could increase in 2025 due to inflationary pressures. This would allow BNM to maintain stability in the economy while also addressing any potential inflation concerns.

    From the Desk of Miichael Yeoh

  • 8 Strategies for Paying Off Your Home Loan Faster

    8 Strategies for Paying Off Your Home Loan Faster

    Without a doubt, your mortgage represents one of the most significant financial commitments you’ll undertake. Over its lifespan, the interest paid to the bank alone can skyrocket into tens of thousands. Consider this: by adhering to a 30-year home loan term, you may ultimately shell out twice the original loan amount in total.

    Did you know that within the first five years of a 30-year loan, you’re likely to reduce only about 7% of the principal? Even by the 20th year, you might still be grappling with less than half. It’s high time to reclaim control over your loan and expedite its repayment to save substantial sums in interest.

    Gone are the days of rigid loan structures prevalent from the 1960s to the 1990s. Today, borrowers have access to a plethora of tools and flexible bank policies, enabling them to slash down loan tenures.

    The sooner you bid farewell to your home loan, the sooner you’ll inch closer to retirement and debt-free living. While myriad methods exist to accelerate repayment, not all may be a perfect fit for your situation. It’s imperative to conduct thorough research and select the strategies best aligned with your needs.

    Here are some actionable ways to expedite home loan repayment:

    1. Making Extra Payments: Witness the magic unfold by utilizing a mortgage calculator to see how even modest additional monthly payments can drastically reduce interest and hasten home loan repayment. Remember, every dollar directed towards the principal shrinks the interest burden and speeds up loan clearance
    2. Refinance: Take advantage of prevailing lower interest rates by refinancing your loan. Use a mortgage calculator to gauge potential interest savings, but don’t forget to factor in associated costs like penalties and legal fees.
    3. Negotiate Interest Rate Adjustments: Keep a keen eye on interest rate fluctuations and consider negotiating with your bank for a reduction. Maintaining current installment amounts despite rate reductions can substantially reduce repayment years
    4. Utilize Flexi Mortgages: Explore flexible mortgage options like the Flexi Mortgage or Money Merge Account, where daily interest calculations and account consolidation accelerate principal reduction, thus shortening loan tenure.
    5. Interest Rate Adjustments: Strategize responses to fluctuating interest rates by either increasing monthly installments to maintain repayment duration or maintaining installments to reduce repayment years.
    6. EPF Withdrawals: Tap into your EPF Account II to swiftly reduce principal and expedite loan repayment. This can even be arranged on a monthly basis for added convenience. In Malaysia it is called EPF or Employee Provident Fund. Its a retirement saving account.
    7. Continuous Monitoring and Adjustment: Regularly monitor your loan progress and financial situation, adjusting strategies as needed to optimize repayment efficiency.
    8. Bi-Weekly Payments: Divide your monthly installment into bi-weekly payments, effectively making 13 monthly payments annually. This simple adjustment can shave off at least four years from a typical 30-year loan term, although availability may vary by region. Please take note that not every country has this package.

    By diligently implementing these strategies, you can significantly alleviate the burden of your home loan and pave the way towards financial freedom.

    From the desk of Miichael Yeoh

  • Who is to blame if a loan is rejected?

    Who is to blame if a loan is rejected?

    After all the searching, surveying and checking, you have finally found your perfect home. Now comes the hardest part. The property is not yours to call home yet. Unless you buy it in cash, like most homebuyers, you would need to rely on a bank loan to turn your dream into reality.

    Applying for a home loan can be quite nerve-wracking especially for first-time home buyer. What’s more, it can be very frustrating if the application is unsuccessful. If your loan is rejected, it’s not the end of the world, but it is human nature to put the blame on someone else. In a way, pointing the finger may also help you understand why your application was rejected, and what you can do differently in your next attempt. We have made a list of the top 3 contenders for the blame game:

    1. Bank Negara Malaysia
    2. The Banks
    3. We, as borrowers

    Now, who would you choose to blame?

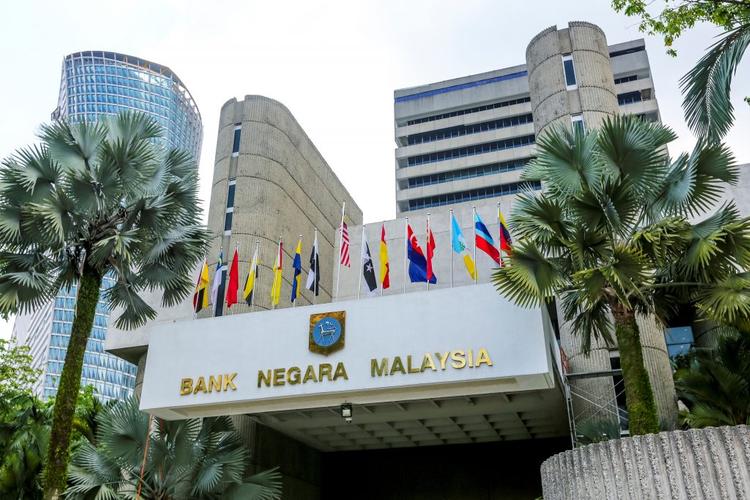
    1. Bank Negara Malaysia

    bank-negara-malaysia-bnm
    © Abdul Razak Latif | 123rf

    Plenty of people blame Bank Negara Malaysia (BNM) for the many loan rejections in Malaysia. Are they the culprit, though? Well, BNM is the one making all the loan policies in Malaysia and most people may feel that the ever-tightening policies are making it more difficult to borrow from banks.

    However, we need to look at this from another point perspective. If BNM did not have all these policies in place, we will most likely face a subprime mortgage crisis, as what occurred in the USA in 2008. How did this crisis come about? This happens when banks get greedy and start lending to anyone, even to borrowers who have a history of low credit scores and problems with debt. In time, these high-risk borrowers will default on their loan repayment and this will have a ripple effect and evolve into a national issue.

    The Solution: Keep tabs on Bank Negara Malaysia’s latest borrowing regulations

    With the country’s current slow but fluctuating economic growth, it’s beneficial to keep yourself updated with the latest Bank Negara Malaysia (BNM) borrowing regulations and not depend on word of mouth from friends or relatives.

    Prior to that, homeowners were allowed to get their homes refinanced for up to 90% of their value with a maximum repayment tenure of 35 years and were able to use the cashed-out portion for investments. But in the 2014 revision, BNM capped the tenure of personal loans at 10 years.

    So why does this matter? Well, take this example: your existing home loan with Bank A is RM400,000 and perhaps because of lower interest rates, you want to refinance your home for RM550,000 at Bank B. The additional RM150,000 would be classified as a personal loan and the 10-year repayment tenure would kick in.

    This means that the DSR of the cashed-out portion would be calculated using the 10-year tenure, resulting in a much higher DSR and thereby affecting your overall credit score and potentially leading to your loan application getting rejected.

    Besides that, BNM recently shared that many banks were using unfair T&Cs in housing loan contracts. BNM has assured that it will be releasing a set of standard T&Cs soon to keep Financial Service Providers in check – where they must act in good faith by ensuring the fairness of contract terms, provide clear and concise product information as well as offer appropriate advice/recommendation based on the needs and financial circumstances of loan applicants.

    As a savvy consumer, you would want to equip yourself with these standards once it is out and study your rights as a financial consumer before approaching a bank for a home loan.

    Therefore, we must remember that under BNM, we have a prudent and balanced lending policy. We need it to protect our country. Best to think again before pushing the blame onto BNM.

    2. The banks

    bank-malaysia-BLR-base-rate
    © Dmitry Chulov | 123rf

    If we do not blame BNM, can we blame the banks instead? After all, they are the ones who approve or reject the loans. Let’s try this – put yourself in the bank’s shoes. Say you are the lender, and your friend the borrower, wants to borrow RM50,000 from you. You know that your friend earns RM5,000 a month. Each month, most of his money goes into paying off his debts. The big question here is, will you lend the money to him? The risk of not getting your money back is very high. Logically, most people would think twice or not even consider lending their friend that sum of money. A bank thinks the same way – they are not a charity, but a profit-driven organization who are accountable to their shareholders.

    Some banks have their own internal policies in lending on top of the existing BNM policies – such as having their own scoring system. As different banks have different lending policies you need to know which bank is the most suitable one for you by conducting your own research and comparison. But do keep in mind that even before they look at your documents, they will first check your credit rating. If your rating is low, it’s not hard to see why your application may be rejected immediately. Do you still think we should be blaming the banks?

    But do keep in mind that even before they look at your documents, they will first check your credit rating. If your rating is low, it’s not hard to see why your application may be rejected immediately.

    The Solution: Determine the best bank DSR (which will match your DSR)

    To reduce the chances of getting your home loan application rejected, you should first calculate your Debt to Service ratio (DSR), which is the calculation of your debt against your monthly income.

    DSR = (Total commitment ÷ Nett Income) x 100

    One of the most common reasons why banks would reject a home loan application is if the applicant’s DSR is above the bank’s maximum allowable DSR. This can get tricky as every bank will have its own respective guidelines for the maximum allowable DSR that they are willing to accept.

    It could be affected by various factors such as income, age, qualifications and even your net worth. The most ideal DSR range would be between 50%-60% as it would hit below the maximum allowable DSR of many banks and thus the likelihood of loan approval would increase.

    If your DSR is the reason why your loan application was rejected, don’t worry! You can start improving your DSR by either reducing your current debts or by consolidating your unsecured loans and credit card bills. Check out LoanCare, which calculates and uses your DSR to help you compare home loan products across at least 10 banks in Malaysia.

    3. The borrowers

    How about if we blame ourselves, the borrowers? Plenty of people are laden with debts from credit cards, personal loans, luxury cars and such. Would it be fair to ask the banks to lend them more money? The risk of non-repayment is very high.

    The Solution: Determine your CCRIS report pitfalls

    If your home loan is denied, the first thing you want to do is to check your CCRIS report. However, these days it’s rare to find anyone who isn’t aware that they must first check their credit score via The Central Credit Reference Information System (CCRIS). This system reflects your past 12 months of credit activities and shows the bank whether you are a good or bad paymaster.

    However, the buck does not stop at having a great credit score. There are other factors which might skew your report. For instance, there is always the question, “If my loan is declined, when can I apply again?”

    Did you know that all of your loan rejections are also reflected in your CCRIS? This can prove to be fatal for those that cast a wide net by submitting loan applications to multiple banks. Banks would usually be aware of any prior rejections via their CCRIS record, and thus, applicants would have to wait between 3-6 months before attempting to apply for another loan.

    As such, it’s wise to improve your credit score before your next attempt. If you have multiple credit cards and loans attached to your name, making timely payments could help show that you are able to manage your commitments and are a good paymaster.

    Besides that, zero obligations are not necessarily a good thing either. Keep in mind that banks would also be reluctant to approve your loan application if your CCRIS report is blank or ‘clean’ – where there are no credit cards/loan/overdraft facilities under your name. Better to have at least one active credit facility with timely payments to prove to the bank that you are able to take on and handle debt obligations responsibly.

    The Next Step: Prepare at least 6 months of documentation

    After fixing your credit score, the next thing you want to do to prove to the bank that you will be a good paymaster is to prepare at least 6 months’ worth of documentation. Regardless of whether you are a salaried employee or a freelancer, keeping meticulous records of all your financial documents is especially beneficial as the bank requires proof of financial capability.

    In order to make your life much easier when it is time to submit your loan application, it’s advisable to keep on hand a record of the latest 6 months’ documentation of the following:

    (a) EA Form/Form BE/Form B: Always file and pay your income taxes within the prescribed dateline.

    (b) Salary slip/proof of income: Banks will require a continuous monthly record of your proof of income whether it’s salary slips or business banking statements. As such, make sure that your records are well organised with every month accounted for.

    (c) EPF statements: This will not be a problem if you are a salaried employee as both you and your employer are required by law to make monthly contributions to your EPF. However, if you are a freelancer, consider making voluntary monthly contributions as a way to boost your credit portfolio.

    (d) Bank account statements: Having either a current account or a separate saving account with a steady and consistent balance is another method that can help bolster your image as a responsible and credible borrower.

    Related Post: https://miichaelyeoh.com/2024/04/07/what-you-should-do-before-applying-a-loan/

    From the Desk of Miichael Yeoh

  • What is Reserve Mortgage?

    What is Reserve Mortgage?

    What exactly is a reverse mortgage, and could it be introduced in Malaysia? This financial product, which has been in use in the West for quite some time, allows senior citizens who own property to leverage it for a loan without the burden of monthly repayments. Instead of the borrower making payments to the bank, the bank pays the borrower based on a percentage of the property’s value, typically around 50 to 60%. Repayment is due upon the borrower’s passing, property sale, or refinancing.

    How does the bank pay me?

    Homeowners can choose one of three ways to obtain their borrowing from the bank: a fixed monthly payment with a predetermined number of months/years of payout, a lump sum payment upfront, or a combination of both.

    Who owns the house?

     Just like any mortgage taken from the bank, you are still the owner of the house. You mortgage the property to take out a loan. The agreement will terminate when the borrower passes away, sells the house, or refinances with another bank.

    How much does it cost?

    Here are some of the costs that you will need to pay: legal fees, valuation fees, mortgage insurance, and monthly maintenance fees. Depending on the bank you apply to, some will advance the costs and put them into the loan.

    Pros and Cons of Reverse Mortgage: In any mortgage borrowing, there are advantages and disadvantages. Borrowers are advised to choose wisely when applying.

    Pros:

    1. You do not need to pay monthly installments.
    2. Funds can help with living expenses such as medical bills and debt repayment.
    3. The fund can help homeowners enjoy their retirement.
    4. With the fund, homeowners will be able to maintain their current lifestyle.

    Cons:

    1. The closing costs, such as legal fees and insurance, can be steep.
    2. The property will be mortgaged with the bank.

    Will Reverse Mortgage come to Malaysia?

    Banks need a healthy mortgage portfolio, and reverse mortgage could provide them with a new avenue to expand their products. Currently, in Malaysia, it is under Cagamas (Mortgage Corporation of Malaysia) and is called Skim Saraan Bercagar (SSB) and SSB Islamic (SSB-i).

    Here are the criteria for borrowers:

    a) Malaysian

    b) 55 years old and above

    c) Owner or joint owners of a residential property

    d) For a joint loan, the joint borrower can be a partner, parent, sibling, or child, subject to age limit

    Do take note of the property criteria:

    a) Residential property in Malaysia held in Borrower’s or joint borrowers’ name(s).

    b) For a joint Skim Saraan Bercagar Loan, joint ownership of property is required.

    c) Property must be owner-occupied and be the primary place of residence.

    d) Freehold property or leasehold property with remaining lease tenure not less than 90 years

    e) Free from encumbrances such as mortgage and other financial liabilities.

    For more detailed information on SSB and SSB-i, interested individuals can visit https://ssb.cagamas.com.my/. It’s essential to thoroughly understand the terms and conditions before applying for a reverse mortgage.

    From the Desk of Miichael Yeoh