Category: Mortgage

  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    10–16 October 2026

    LOOK BEYOND THE PRICE

    Five stories. Three Malaysian developments. Two international markets. One objective: helping buyers and investors make better-informed property decisions.

    🇲🇾 MALAYSIA PROPERTY MARKET

    STORY 1 — Why Are Malaysian Property Developers Becoming More Cautious?
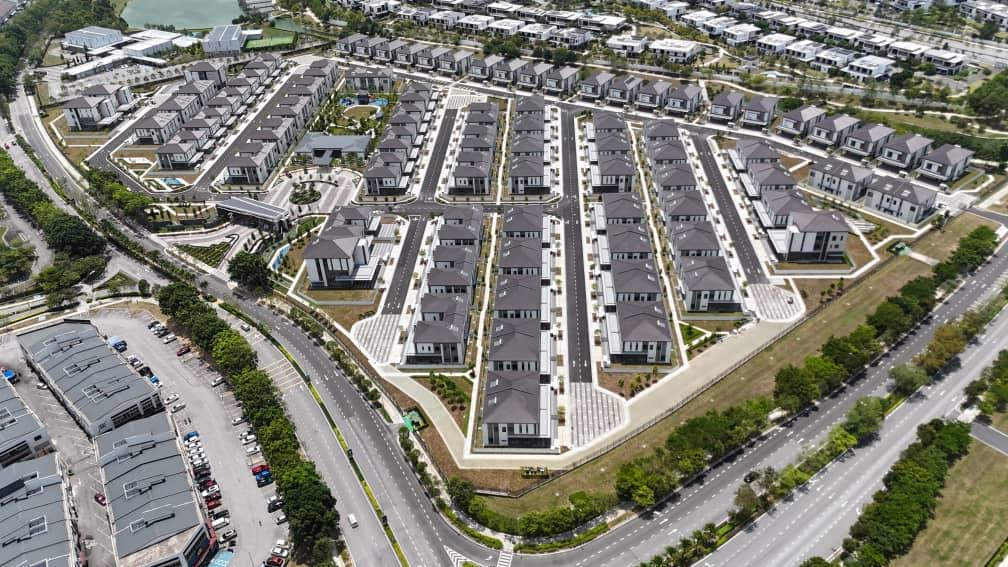
    What Happened?

    A property industry survey reported by The Edge Malaysia on 15 October revealed that 63% of surveyed developers had no plans to launch residential projects in the second half of 2026.

    The survey by the Real Estate and Housing Developers’ Association Malaysia (REHDA) covered 181 respondents in Peninsular Malaysia.

    Key findings included:

    • 114 of 181 respondents had no plans for residential launches in the second half of 2026.
    • The remaining respondents planned to launch 18,696 units.
    • 77% of respondents reported financing difficulties during the first half of 2026.
    • 59% of respondents with relevant data reported unsold completed residential units as at 30 June 2026.
    • Among respondents who reported unsold completed units, 32% said some of their stock had remained unsold for more than three years.

    Developers cited market conditions, approval delays and existing unsold inventory as reasons for their cautious approach. The Edge Malaysia

    Source: The Edge Malaysia — REHDA property industry survey, 15 October 2026

    Why It Matters

    This is an important signal for Malaysia’s property market.

    A high number of new launches does not automatically mean a healthy market. What matters is whether homes are priced appropriately, buyers can obtain financing and completed units find genuine occupants.

    The financing figures are particularly noteworthy. Demand for housing may exist, but prospective buyers still need to qualify for loans and manage their financial commitments.

    Developers must also balance construction costs against what their target customers can realistically afford.

    Miichael’s Review

    I see this as a reminder that property development must follow real demand, not simply market excitement.

    When developers become more cautious, buyers should look beyond promotional campaigns and ask some practical questions:

    1. How many comparable properties are already available?
    2. Are existing developments attracting genuine buyers?
    3. Are asking prices supported by recent transactions?
    4. Can the intended buyers realistically obtain financing?
    5. Is the development designed for actual occupants or mainly for investors hoping to resell?

    The survey also suggests that different property categories are performing differently. Buyers should therefore avoid treating the entire Malaysian market as one uniform market.

    My view: A more selective market can reward careful research. Buyers need to distinguish between a property that is attractively marketed and one that is genuinely well positioned.


    STORY 2 — Malaysia Reports 1,726 Revived Housing Projects: What Does This Mean for Buyers?

    What Happened?

    On 14 October, EdgeProp Malaysia reported on the Housing and Local Government Ministry’s update that 1,726 sick or abandoned private housing projects had been revived since 2023.

    The projects involved approximately:

    • 199,643 housing units
    • RM158 billion in gross development value
    • 1,542 sick projects completed with Certificates of Completion and Compliance
    • 147 projects restored to smooth status
    • 37 abandoned projects resolved through physical completion or arrangements benefiting buyers

    The ministry also reported that, as at 31 August 2026, Kuala Lumpur still had seven projects classified as abandoned and another 12 classified as sick.

    The government has set a target of eliminating sick and abandoned housing projects by 2030. EdgeProp

    Source: EdgeProp Malaysia — Housing project rehabilitation update, 14 October 2026

    Why It Matters

    A stalled housing project can create serious financial and emotional difficulties for buyers.

    They may have paid deposits and progressive payments, committed to housing loans and continued paying rent while waiting for their homes.

    The reported rehabilitation figures are encouraging, but one distinction matters: a project being revived does not necessarily mean every unit has been completed and handed over.

    The different outcomes must be examined individually.

    For prospective buyers, this is also a reminder to assess the delivery record of a developer and the actual status of a project before committing.

    Miichael’s Review

    I welcome efforts to protect homebuyers and resolve problematic developments.

    However, I would assess a project’s progress using evidence rather than announcements alone.

    Before buying into an ongoing development, I would want to understand:

    • The developer’s financial and delivery track record.
    • The project’s construction progress.
    • Whether the required approvals and legal arrangements are in place.
    • Whether there are known disputes or rehabilitation issues.
    • The expected completion date and the evidence supporting it.

    For buyers already affected by a stalled project, the available rehabilitation route and legal position are particularly important.

    My view: The real measure of success is not simply how many projects have been declared revived. It is how many affected buyers ultimately receive the homes or appropriate resolutions they were promised.


    STORY 3 — IOI Properties Advances Its Proposed RM7.66 Billion REIT Listing

    What Happened?

    IOI Properties Group Berhad advanced its proposed Malaysian real estate investment trust (REIT) listing after signing an underwriting agreement with six financial institutions.

    According to EdgeProp Malaysia on 12 October:

    • The proposed REIT has nine initial assets.
    • The portfolio was valued at approximately RM7.66 billion as at 31 May 2026.
    • The proposed offering could involve up to 2.2 billion units.
    • The underwriting agreement covers 165 million offer units, subject to the offering’s allocation provisions.
    • The prospectus was targeted for the fourth quarter of 2026, with listing targeted by year-end.

    The initial portfolio includes IOI City Mall, six hotels and two office properties.

    These are proposed listing arrangements; the announcement did not mean the IPO had already been completed. EdgeProp

    Source: EdgeProp Malaysia — IOI Properties advances proposed REIT IPO, 12 October 2026

    Why It Matters

    A REIT provides a way for investors to gain exposure to income-generating property through a listed investment vehicle rather than purchasing an entire property themselves.

    For the property sector, a listing can provide another route for capital management and potentially broaden investor participation.

    However, a large property portfolio does not automatically make a REIT an attractive investment.

    Investors still need to examine rental income, occupancy, financing costs, debt levels, asset valuations and the proposed distribution policy.

    Miichael’s Review

    This is worth watching because it connects property ownership with capital markets.

    For individual investors, a REIT may offer a different way to participate in commercial property, hotels and retail assets without directly managing a building.

    But the decision should be based on the investment’s fundamentals.

    I would look carefully at:

    1. The quality and location of the underlying assets.
    2. The sustainability of rental income.
    3. Financing costs and gearing.
    4. The proposed distribution yield and how it is calculated.
    5. Whether the offering valuation is reasonable relative to comparable investments.

    My view: The important question is not merely how much the portfolio is worth. It is whether its assets can generate sustainable income at a valuation that makes sense for investors.


    🌏 INTERNATIONAL PROPERTY WATCH

    🇦🇪 STORY 4 — Dubai Buyers Shift Towards Completed Homes as the Market Becomes More Selective
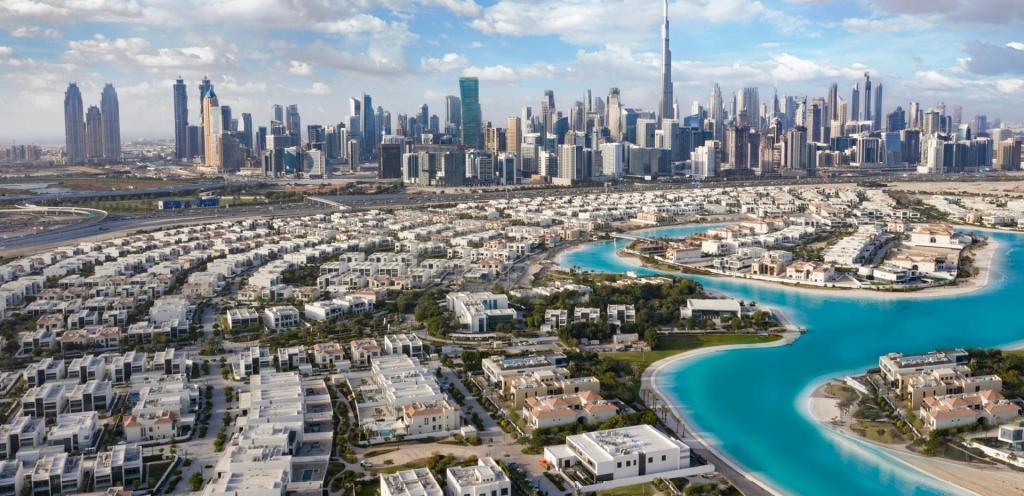
    What Happened?

    A third-quarter 2026 residential market report from betterhomes, reported by Khaleej Times on 15 October, showed a shift towards completed homes in Dubai.

    Key findings included:

    • Sales of ready residential properties rose 16% quarter-on-quarter.
    • Secondary-market transactions reached 10,055, with a total value of Dh27.1 billion.
    • Secondary-market transactions accounted for 29% of total residential sales, up from 24% in the second quarter.
    • Overall residential sales totalled 34,615 transactions during the quarter, broadly unchanged from the previous quarter.
    • Median apartment prices declined 2.4% between June and September, while villa and townhouse prices fell 2.3%.

    Despite the quarterly price declines, prices remained higher than a year earlier. Rental enquiries also rose sharply, although median rents eased in several market segments. Khaleej Times

    Source: Khaleej Times — Dubai ready-home sales jump 16%, 15 October 2026

    Why It Matters

    The figures suggest that buyers are becoming more selective about the type of property they purchase.

    Completed homes offer advantages that off-plan properties cannot immediately provide: buyers can inspect the actual unit, assess the surrounding community and potentially receive rental income sooner.

    However, the reported shift does not mean off-plan properties have become universally unattractive. Different buyers have different financial circumstances, objectives and risk tolerances.

    The decline in quarterly prices also highlights the importance of comparing actual transactions rather than relying exclusively on advertised prices.

    Miichael’s Review

    This is an interesting development for property investors.

    A completed property may provide greater visibility into its condition, rental demand and surrounding environment. An off-plan property may offer different advantages, but it also requires buyers to assess delivery risk and future market conditions.

    I would compare both options using the same criteria:

    • Total acquisition cost.
    • Expected rental income.
    • Maintenance and other holding expenses.
    • Financing commitments.
    • Comparable transaction prices.
    • Exit options if market conditions change.

    My view: A completed property is not automatically a better investment, just as an off-plan property is not automatically a better bargain. The right choice depends on the numbers, the risks and the buyer’s objectives.


    🇨🇦 STORY 5 — Canadian Home Sales Fall Again as Mortgage Rates Weigh on Buyers

    What Happened?

    On 16 October, Reuters reported that Canadian home sales declined again in September as higher mortgage rates and expectations of a possible interest-rate increase weighed on market activity.

    According to the Canadian Real Estate Association (CREA):

    • National home sales fell 2.3% month-on-month in September, following a 0.7% decline in August.
    • Sales were down 7.7% year-on-year on an unadjusted basis.
    • The Home Price Index declined 0.4% month-on-month and 3.4% year-on-year.
    • New property listings fell 1.8% from August.
    • The seasonally adjusted sales-to-new-listings ratio slipped to 48.8%, below its long-term average of 54.7%.

    At the time of the report, financial markets were pricing in the possibility of a 25-basis-point Bank of Canada rate increase in December. This was a market expectation, not a confirmed policy decision. Reuters

    Source: Reuters — Canadian home sales fall in September as mortgage rates increase, 16 October 2026

    Why It Matters

    The Canadian market demonstrates how financing conditions can affect property transactions.

    Even when prospective buyers want to purchase homes, higher mortgage costs can reduce borrowing capacity or make buyers more cautious about committing.

    A slower market may give some buyers more time to negotiate. However, it does not automatically mean that every property is attractively priced.

    Local conditions also matter: national figures can conceal significant differences between cities, neighbourhoods and property types.

    Miichael’s Review

    For me, the main lesson is the relationship between financing and affordability.

    When interest rates rise, a buyer may qualify for a smaller loan or face a higher monthly repayment. That can change which properties are financially sensible.

    Before committing, I would ask:

    1. Can I afford the repayments if borrowing costs increase?
    2. Does the property remain affordable after taxes, insurance and maintenance?
    3. Is the asking price supported by recent comparable transactions?
    4. Can I sustain ownership if resale takes longer than expected?
    5. Am I buying because the property suits my needs, or because I expect prices to rise?

    My view: A property purchase should be financially sustainable even when market conditions become less favourable. Buyers who understand their financing limits are better placed to make measured decisions.


    WORTH WATCHING

    Here are five developments I would monitor over the coming weeks.

    AreaWhat to watchWhy it matters
    MalaysiaDeveloper launch plans and sales performanceShows whether supply is responding to genuine demand.
    MalaysiaRehabilitation of sick and abandoned housing projectsBuyers need evidence of actual progress and resolution.
    MalaysiaIOI Properties’ proposed REIT prospectusProvides details for evaluating the portfolio, pricing and distribution policy.
    UAECompleted-home prices, rents and transaction activityHelps investors assess whether market conditions support their objectives.
    CanadaMortgage rates, sales activity and home-price trendsProvides an indication of how financing conditions affect affordability and demand.

    MY TAKEAWAY THIS WEEK

    This week’s property news reinforces a principle that applies across markets:

    Property decisions should be based on fundamentals, not headlines.

    In Malaysia, developers are becoming more cautious, housing-project rehabilitation remains important, and a proposed REIT listing offers another way to participate in property investment.

    In Dubai, buyers are showing greater interest in completed homes, while prices and rents are becoming more competitive in some segments.

    In Canada, higher borrowing costs are weighing on transactions.

    These markets have different conditions, but the underlying questions are similar.

    • Is the property priced reasonably?
    • Is there genuine demand?
    • Can the buyer afford to own it comfortably?
    • Does the investment generate sustainable income?
    • Are the risks manageable if the market changes?

    A property can look attractive on paper but still be unsuitable for a particular buyer.

    Look beyond the price. Understand the fundamentals before making the decision.

    Miichael Yeoh
    PROPERTY STRATEGIST
    miichaelyeoh.com
  • Is Now a Good Time to Buy Property in Malaysia ?

    Is Now a Good Time to Buy Property in Malaysia ?

    Everyone wants to know whether property prices will rise or fall.

    But that’s not the question I would ask before buying a property.

    The better question is:

    “Is this the right property, at the right price, with the right financing, for my situation?”

    Because even if the market rises next year, you can still make a bad property decision today.

    And even if prices fall, waiting doesn’t automatically mean you will get a better deal.

    So, is 2026 a good time to buy property in Malaysia?

    My answer: It can be — but only if you stop trying to predict the market and start discovering the numbers behind the decision.


    What Is Actually Happening in the Malaysian Property Market?

    Let’s start with the facts.

    Malaysia’s property market remained resilient in the first half of 2026, recording 187,320 transactions worth RM105.12 billion. The market was supported by relatively stable transaction activity, prices and construction activity.

    At the same time, the market isn’t booming across every segment.

    Residential transactions in H1 2026 were 110,998, accounting for 59.3% of total property transactions. Completed unsold residential units increased to 33,094 units, worth about RM17.78 billion.

    That tells us something important.

    The market isn’t simply “good” or “bad”.

    There are areas of strength.

    There are areas of oversupply.

    There are properties with genuine demand.

    And there are properties that developers are struggling to sell.

    This is exactly why buyers need to become more selective.


    What About Interest Rates?

    This is probably one of the first things buyers look at.

    And understandably so.

    Bank Negara Malaysia has maintained the Overnight Policy Rate (OPR) at 2.75% throughout 2026, including its latest decision on 3 September 2026.

    That provides a relatively stable financing environment compared with periods of rapidly changing interest rates.

    But here’s where I think many buyers make a mistake.

    They see a stable or lower interest-rate environment and immediately think:

    “Good. Time to buy.”

    Not necessarily.

    The interest rate is one variable in your property decision.

    It is not the decision.

    A property that is overpriced by RM100,000 doesn’t suddenly become a good investment because your mortgage rate is slightly lower.


    Should You Wait for Property Prices to Fall?

    This is probably the question I hear most often.

    And it sounds logical.

    “If prices are going to fall, I’ll wait.”

    But there are two problems with this strategy.

    First, nobody knows exactly when prices will fall.

    And more importantly:

    Second, even if prices fall, you may not benefit.

    Why?

    Because the property you want may not fall.

    The bank may tighten lending.

    Your income may change.

    Interest rates may move.

    The developer may remove incentives.

    Another buyer may take the unit you wanted.

    Or the market may simply remain stable for several years.

    Waiting is not a neutral decision.

    Waiting is also a property decision.


    The Bigger Question: What Are You Actually Buying?

    This is where I believe buyers need to change their thinking.

    Don’t ask only:

    “Will property prices go up?”

    Ask:

    “What is creating the demand for this property?”

    Is it:

    • population growth?
    • new jobs?
    • infrastructure?
    • universities?
    • industrial development?
    • tourism?
    • rental demand?
    • limited land supply?
    • better connectivity?
    • genuine owner-occupier demand?

    Or is the main attraction simply:

    “The developer says prices will increase.”

    Those are very different things.


    5 Things I Would Check Before Buying Property

    1. Can You Actually Afford It?

    This sounds obvious.

    But affordability isn’t simply:

    “The bank approved my loan.”

    A bank’s approval tells you what the bank is prepared to lend.

    It doesn’t tell you what you should comfortably borrow.

    Before buying, calculate the full monthly cost:

    • mortgage instalment
    • maintenance fee
    • sinking fund
    • assessment
    • quit rent
    • insurance
    • utilities
    • repairs
    • furnishing
    • parking
    • transportation
    • other existing commitments

    Then ask:

    “If my income stays the same for the next three years, will this property still feel comfortable?”

    That’s a much better question than:

    “How much can the bank approve?”


    2. Is the Price Supported by the Market?

    Don’t fall in love with the launch price.

    Find out what similar properties are actually transacting for.

    NAPIC provides transaction, price, rental and property-market data, including state and district-level information.

    Compare:

    Asking price vs actual transaction price.

    Then compare:

    RM per sq ft vs comparable properties.

    Then ask:

    “What am I paying a premium for?”

    If the answer is simply:

    “Because this is a new launch.”

    That’s not enough.


    3. Is There Real Demand?

    A beautiful building isn’t demand.

    A famous developer isn’t demand.

    A fantastic showroom isn’t demand.
    Demand comes from people who genuinely want to live, work, rent or invest in that location.

    Ask:

    • Who is going to live here?
    • Who is going to rent here?
    • Where do these people work?
    • Why would they choose this location?
    • What alternatives do they have?
    • What competing projects are coming?

    This becomes particularly important when a market has significant unsold stock.

    Malaysia’s completed unsold residential inventory rose to 33,094 units in H1 2026.

    That doesn’t mean all property is bad.

    It means product selection matters.


    4. What Happens When More Supply Arrives?

    This is one of the most overlooked questions in property investing.

    Imagine you buy a condominium because the current rental demand looks excellent.

    But three years later, five more projects are completed nearby.

    Now you have thousands of competing units.

    Your tenant has choices.

    Your rental growth may slow.

    Your vacancy risk may increase.

    And when you eventually want to sell, you’re no longer competing only against today’s properties.

    You’re competing against tomorrow’s properties.

    That’s why I always tell buyers:

    Don’t just study the property. Study what is coming around the property.


    5. What’s Your Exit Strategy?

    This is perhaps the biggest difference between a home purchase and an investment purchase.

    A homeowner may be happy because:

    “I love the location.”

    An investor needs another question:

    “Who will buy this from me later?”

    Think about your exit before your entry.

    If you need to sell in five or ten years:

    • Who is your future buyer?
    • What will they be looking for?
    • What competing supply will exist?
    • Will your property still be relevant?
    • Will your price be affordable to the next buyer?
    • Will the rental market support your valuation?

    You don’t realise your investment return when you buy.

    You realise it when you eventually exit.


    So… Is 2026/2027 a Good Time to Buy Property?

    Here’s my answer.

    Yes — if you’re buying based on fundamentals.

    No — if you’re buying simply because you believe prices must go up.

    The Malaysian property market in 2026 is resilient, but the data also shows why buyers cannot treat the entire market as one big opportunity.

    Transaction activity remains substantial.

    Interest rates are relatively stable.

    But residential demand is uneven, completed unsold stock has increased, and affordability remains an important constraint.

    That creates an interesting environment.

    It may actually be a better time to be a selective buyer than an emotional buyer.

    You don’t necessarily need to wait for a market crash.

    You need to find the property where:

    Price + Location + Demand + Financing + Supply + Exit

    all make sense together.


    The PDS 7-Question Property Test

    Before I buy any property, I would want to answer these seven questions:

    1. Why this property?

    What problem does it solve?

    2. Why this location?

    What is creating sustainable demand?

    3. Why this price?

    What evidence supports the valuation?

    4. Who is the future buyer or tenant?

    Where does the demand come from?

    5. What competition is coming?

    What could affect rental and resale demand?

    6. Can I comfortably hold it?

    Not just today — but through different market conditions.

    7. How do I eventually exit?

    Who will buy it from me?

    If you can’t answer these questions, perhaps you are not ready to buy.

    And that’s okay.

    Not buying is sometimes a better decision than buying the wrong property.


    The Real Question Isn’t “When Should I Buy?”

    After more than two decades around banking, mortgages, property and investment decisions, I’ve learned that buyers often spend too much time trying to predict the market.

    The smarter approach is to understand the decision.

    You don’t need to know exactly where property prices will be five years from now.

    You need to understand why the property you’re considering should still have demand five years from now.

    That’s a very different way of looking at property.

    And it is the philosophy behind the Property Discovery System™.

    Don’t just ask whether now is a good time to buy.

    Discover whether this is the right property for you.

    Discover Better. Decide Smarter.

    Miichael Yeoh

    Property Strategist

  • Malaysia Property Market 2026: 33,094 Unsold Homes — Are They Really “For Sale” to Everyone?

    Malaysia Property Market 2026: 33,094 Unsold Homes — Are They Really “For Sale” to Everyone?

    33,094

    That is the number currently attracting attention in Malaysia’s property market.

    As at the first half of 2026, 33,094 completed residential units worth RM17.78 billion remained unsold.

    The figure is up from 30,471 units in the previous period.

    Naturally, the immediate question is:

    Why aren’t Malaysians buying these homes?

    The usual answers come quickly.

    Homes are too expensive.

    Buyers cannot afford them.

    Banks are rejecting loans.

    Developers are building too much.

    All of these factors may play a role.

    But I think we need to ask a more fundamental question:

    What does “unsold” actually mean?

    Because an unsold property is not necessarily a property that is simply sitting on the open market waiting for any Malaysian to buy it.

    And that distinction matters.


    The Unsold Property Paradox

    Let’s start with something that may surprise many people.

    Malaysia’s property market is still active.

    In the first half of 2026, the country recorded 187,320 property transactions worth RM105.12 billion.

    Residential property accounted for 110,998 transactions, representing 59.3% of total transactions and RM47.11 billion in transaction value.

    So this isn’t a story about Malaysians suddenly refusing to buy property.

    There are buyers.

    There are transactions.

    There is demand.

    Yet at the same time, tens of thousands of completed homes remain unsold.

    That is the paradox.

    People are buying property — but some completed properties are still not finding buyers.

    This tells us that the problem is more complicated than simply:

    “Malaysians cannot afford houses.”


    Not Every Unsold Unit Has the Same Problem

    This is where I believe we need to look at the property market differently.

    An “unsold” unit could be unsold for very different reasons.

    1. The buyer doesn’t want it.

    The location may not be attractive.

    The layout may not fit the target market.

    The facilities may not justify the price.

    The surrounding environment may not match what buyers want.


    2. The buyer wants it — but cannot get financing.

    This is a very real issue.

    The latest REHDA Property Industry Survey found that 59% of surveyed developers reported unsold completed residential units.

    Among the factors highlighted were end-financing rejection, property prices and unreleased Bumiputera units.

    The survey covered 181 REHDA members in Peninsular Malaysia.

    A buyer can therefore say:

    “I want this property.”

    But the bank may effectively say:

    “You cannot finance it.”

    Those are two completely different problems.


    3. Some units are not immediately available to the entire market

    This is another part of the conversation that deserves more attention.

    Some residential developments contain Bumiputera quota units.

    Where those units remain unsold, developers may need to go through the relevant state process before they can be released to the wider market.

    The rules are not identical across Malaysia.

    In Penang, for example, the state has a formal Bumiputera quota release process, including requirements relating to the physical progress of the development and evidence of marketing efforts to Bumiputera purchasers.

    So an important distinction needs to be made:

    A unit can be recorded as “unsold” without necessarily being immediately available to every buyer in the market.

    And depending on the state and applicable scheme, releasing such units can also involve specific conditions or financial contributions.

    This matters because we should be careful not to treat every unit in the RM17.78 billion figure as if it represents exactly the same market problem.


    4. The product may simply be wrong for today’s buyer

    This is probably one of the most overlooked questions in property development.

    A project may have been conceived several years ago.

    The developer may have studied:

    • population growth,
    • household formation,
    • income levels,
    • infrastructure,
    • competition,
    • buyer profiles,
    • pricing,
    • and future demand.

    Then the project goes through planning, approvals, construction and completion.

    By the time the keys are ready…

    The market may have changed.

    Buyers’ expectations change.

    Household sizes change.

    Working patterns change.

    Transport patterns change.

    Financing conditions change.

    Lifestyle preferences change.

    And competing developments enter the market.

    A product that looked attractive when the development was planned may not necessarily be equally attractive when it is completed.


    And this is where “affordable” becomes an interesting word

    The government has reported that properties priced RM300,000 and below accounted for 51.6% of residential transactions in H1 2026.

    At the same time, the government has acknowledged that completed unsold residential stock is not confined to high-end properties. It is also significant in affordable and mid-priced segments.

    So perhaps we need to distinguish between:

    Affordable by price

    and

    Affordable and desirable to the target buyer.

    They are not necessarily the same thing.

    A RM300,000 property may be affordable on paper.

    But if it is two hours from the buyer’s workplace…

    If public transport is poor…

    If the layout doesn’t suit the family…

    If the maintenance costs are too high…

    If financing is difficult…

    If the buyer doesn’t see future resale demand…

    Then the buyer may still decide:

    “This isn’t for me.”

    And that isn’t necessarily an affordability problem.

    It may be a product-market fit problem.


    This is where the PDS perspective comes in

    For years, much of the property industry has operated around a relatively simple sequence:

    Build → Market → Sell

    But perhaps we need to rethink the sequence.

    The PDS philosophy starts with a different question:

    Discover the buyer before you build for the buyer.

    Who exactly is the intended buyer?

    What problem are they trying to solve?

    Where do they want to live?

    What can they realistically afford?

    Can they obtain financing?

    What type of property fits their lifestyle?

    What compromises are they willing to make?

    What alternatives are available?

    What would make them choose this property over another?

    And perhaps most importantly:

    What evidence would give them confidence to make the decision?


    From “Selling Property” to “Helping Buyers Decide”

    This is a subtle but important shift.

    A traditional sales approach may ask:

    How do we sell this unit?

    A PDS approach asks:

    Why should this buyer choose this unit — and is it actually the right choice for them?

    That changes the conversation.

    Instead of starting with the brochure, we start with the buyer.

    Instead of starting with the promotion, we start with the problem.

    Instead of asking:

    “How much discount do we need to give?”

    we should also be asking:

    “Why isn’t the buyer convinced at the current value proposition?”

    Sometimes the answer may be price.

    Sometimes financing.

    Sometimes location.

    Sometimes product design.

    Sometimes timing.

    Sometimes competition.

    Sometimes eligibility.

    And sometimes the property simply isn’t solving a sufficiently important problem for the intended buyer.


    The Developer’s Question Should Change Too

    Perhaps developers should not only ask:

    “How many units can we sell?”

    They should ask:

    “How many units does this market actually need — and what type?”

    That means looking beyond headline demand.

    It means understanding:

    Demand

    → Who needs the property?

    Ability

    → Who can actually afford it?

    Eligibility

    → Who can legally or practically purchase it?

    Financing

    → Who can obtain the required loan?

    Location

    → Who wants to live there?

    Product

    → What configuration do they want?

    Value

    → Does the property justify the price?

    Confidence

    → What information does the buyer need before deciding?

    This is a much more complete view of property demand.


    The Real Property Overhang May Be an Alignment Problem

    Perhaps Malaysia doesn’t simply have a shortage of buyers.

    Perhaps we have a shortage of alignment.

    Alignment between:

    What developers build

    and

    what buyers actually want.

    Between:

    Price

    and

    purchasing power.

    Between:

    Location

    and

    daily life.

    Between:

    Product

    and

    lifestyle.

    Between:

    Eligibility

    and

    the available buyer pool.

    Between:

    financing

    and

    the buyer’s financial profile.

    And ultimately:

    what is being offered

    and

    what the buyer is prepared to decide on.


    So, What Should We Do About the 33,094?

    I don’t think the answer is simply:

    “Make property cheaper.”

    Nor is it simply:

    “Give buyers more incentives.”

    And it certainly isn’t enough to say:

    “Malaysians aren’t buying.”

    We need to understand why each segment of unsold stock remains unsold.

    Because the solution to a financing problem is different from the solution to a location problem.

    The solution to a Bumiputera quota-release issue is different from the solution to a product-market mismatch.

    And the solution to an overpriced property is different from the solution to a property that is fairly priced but poorly positioned.

    One number can hide many different problems.

    That is why we need to go beyond the headline.


    The PDS Way

    At the Property Discovery System, we believe property decisions should begin with discovery, not selling.

    For buyers:

    Discover the market.
    Understand the property.
    Test the numbers.
    Assess the risks.
    Compare the alternatives.
    Then decide.

    For developers:

    Discover the demand.
    Understand the buyer.
    Design the right product.
    Position it correctly.
    Build trust.
    Then sell.

    Because the objective shouldn’t simply be to sell more properties.

    It should be to create better alignment between property supply and real buyer demand.


    The question we should really be asking

    The headline today is:

    33,094 completed homes remain unsold.

    But perhaps the more important question is:

    Why are these particular homes still unsold?

    Until we answer that question at the unit, project, location, price, financing and buyer level, we risk treating very different problems as if they were the same problem.

    And if we keep treating the symptoms instead of understanding the buyer…

    We may simply build another 33,094 homes to replace them.

    Property is not just about selling a product.

    It is about helping people make better decisions.

    Discover Better. Decide Smarter.

    That is the PDS way.


    Sources &

    • National Property Information Centre (NAPIC), Property Market Report H1 2026. NAPIC — H1 2026 Property Market Report
    • Ministry of Finance Malaysia, launch remarks on the H1 2026 Property Market Report.
    • REHDA Property Industry Survey 1H2026, reported by EdgeProp.
    • Penang State Housing Board, Guidelines for Application for Release of Bumiputera Quota.

  • Think Like a Banker Before You Buy Property

    Think Like a Banker Before You Buy Property

    One thing I learned from working closely with banks is this:

    Banks are extremely careful before approving a property loan.

    They analyse risks, stress-test your finances, and study whether you can survive difficult situations.

    But here’s the irony.

    Many property buyers don’t analyse their purchase the same way.

    They look at the show unit.
    They listen to marketing promises.
    They follow what others are buying.

    But they rarely ask the same questions a banker would ask.

    If you want to invest in property wisely, start by thinking like a banker.

    Here are three things bankers always analyse.


    1️⃣ Debt Ratio – Are You Stretching Yourself Too Thin?

    Banks look closely at your Debt Service Ratio (DSR).

    This measures how much of your income is used to pay debts.

    Even if a bank approves your loan, you should still ask yourself:

    • What happens if interest rates increase?
    • What if my income drops temporarily?
    • Will I still feel comfortable servicing the loan?

    A property might look affordable today.

    But bankers always plan for tomorrow’s risks.


    2️⃣ Holding Power – Can You Hold Through Market Cycles?

    Property markets don’t always go up.

    There will be slow periods.

    Bankers evaluate whether a borrower has the financial strength to continue paying during tough times.

    Smart investors should ask:

    • Can I hold this property for 5–10 years if needed?
    • Do I have cash reserves?
    • What if the market takes longer to recover?

    Many investors fail not because they bought the wrong property…

    They fail because they cannot hold it long enough.


    3️⃣ Rental Sustainability – Can the Property Support Itself?

    Another banker mindset is income sustainability.

    Before buying, ask:

    • Is there real rental demand here?
    • Who are the potential tenants?
    • Can the rental help support the loan?

    A strong investment property should ideally generate rental income that supports part of the financing.

    This reduces pressure and improves long-term stability.


    Final Thought

    Successful property investors don’t buy emotionally.

    They evaluate property like a banker evaluating risk.

    Before your next purchase, ask yourself:

    Does this property pass the banker’s test?

    When you start thinking like a banker, you don’t just buy property.

    You build a stronger and safer property portfolio.


    Miichael Yeoh
    Property Strategist | Developer Consultant | Investment & Mortgage Expert
    Author of Think Like a Banker, Act Like a Player

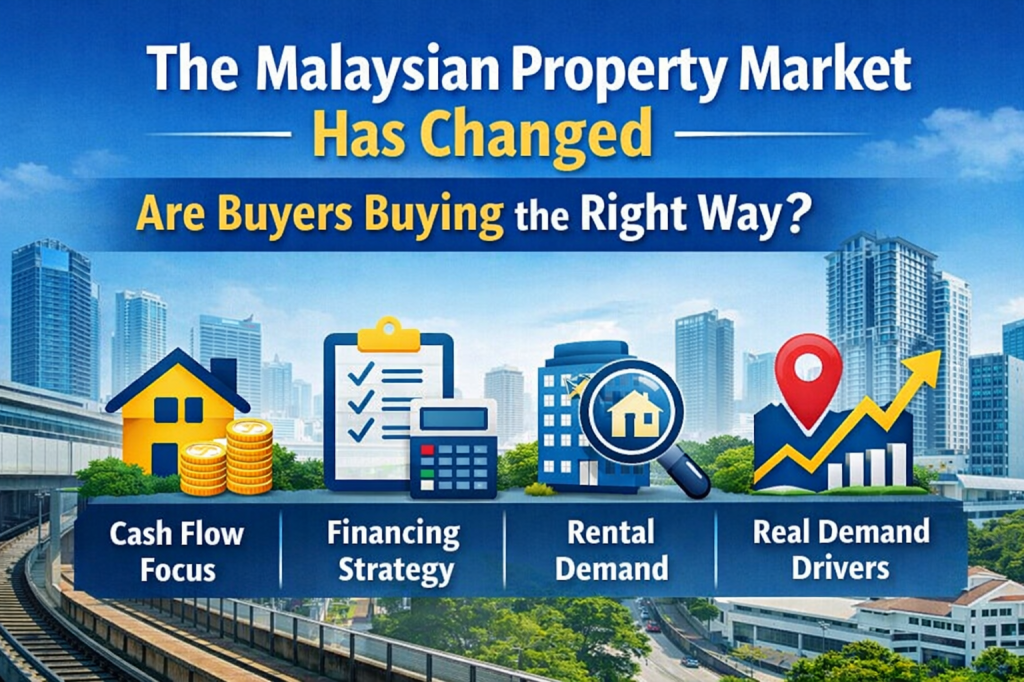
  • The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?

    The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?

    The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?

    For many years, property investing in Malaysia followed a familiar formula.

    Buy a new launch, wait a few years, and hope the price goes up.

    This strategy worked reasonably well during earlier property cycles when prices were rising quickly, financing was easier, and supply was more limited. Many investors entered the market believing that capital appreciation alone would justify the purchase.

    But today, the Malaysian property market has entered a different phase.

    The question buyers should now ask is no longer “Will the price go up?”
    The more important question is “Can this property sustain itself financially?”


    The Shift From Speculation to Sustainability

    Over the past decade, the mindset of property buyers has gradually evolved.

    Today’s buyers are more cautious, more analytical, and more focused on cash flow and long-term holding power.

    Instead of relying purely on future price appreciation, investors are increasingly asking questions such as:

    • What is the rental demand in this area?
    • Can the rental cover most of the loan instalment?
    • What happens if interest rates increase?
    • Who is the actual tenant profile for this property?

    These questions reflect a more mature approach to property investing.

    The reality is simple: not every property will appreciate significantly in the short term. When appreciation slows, the ability of the property to generate rental income becomes far more important.


    Financing Strategy Now Matters More Than Ever

    Another major shift in the market is the growing importance of financing structure.

    Many buyers focus heavily on the purchase price but pay little attention to how the property is financed. Yet the financing strategy can determine whether an investment becomes manageable or financially stressful.

    Buyers today need to consider:

    • Loan margin and interest rates
    • Monthly instalment affordability
    • Holding power during market slowdowns
    • Overall debt exposure

    A well-structured loan can give investors time and flexibility, while poor financial planning can force them to sell prematurely.

    Thinking about financing before buying is no longer optional — it is essential.


    Rental Demand Is Becoming a Key Decision Factor

    One of the biggest mistakes many investors made in the past was buying properties without considering who would actually rent the unit.

    Today, buyers are beginning to look more closely at demand drivers such as:

    • Proximity to employment hubs
    • Accessibility and transportation infrastructure
    • Nearby universities or hospitals
    • Tourism demand and short-term rental potential

    In markets like Penang, Kuala Lumpur, and Johor Bahru, rental demand is increasingly shaping investment decisions.

    For example, areas with strong tourism activity or major infrastructure developments may offer better rental prospects compared to purely speculative locations.

    The key question investors should ask is:

    “Who is my tenant?”

    If there is no clear answer, the investment may not perform as expected.


    The Role of Infrastructure and Economic Drivers

    Another important factor influencing property performance today is real economic activity.

    Infrastructure projects, transportation connectivity, employment centres, and tourism growth can significantly impact both rental demand and long-term property value.

    For instance, upcoming transportation developments and urban revitalisation projects in cities such as Georgetown could change demand patterns in the coming years.

    However, infrastructure alone does not guarantee success. The surrounding ecosystem — population growth, business activity, and lifestyle demand — must also support the property market.


    Buying Property Today Requires a Different Mindset

    The Malaysian property market has not disappeared. But the way buyers approach property must evolve.

    Successful investors today tend to follow a more balanced approach:

    • Evaluate rental yield and cash flow
    • Structure financing carefully
    • Understand real demand drivers
    • Focus on long-term sustainability

    In other words, the focus has shifted from short-term speculation to long-term investment discipline.


    A Final Thought

    Property has always been a long-term asset class.

    But in today’s market environment, buying property requires more than just optimism about future price growth.

    It requires careful thinking, realistic financial planning, and a clear understanding of market demand.

    The Malaysian property market has changed.

    The real question is — have buyers changed with it?


    Miichael Yeoh
    Property Strategist | Developer Consultant | HRD Corp Trainer

    Miichael Yeoh has more than 28 years of experience spanning banking, mortgage advisory, property investment, and developer consultancy. He is also the author of Think Like a Banker, Act Like a Player, Property Investment BLT, and Buying Property Like A Pro.

  • What Is OPR in Malaysia and How Does It Affect Housing Loan Interest Rates?

    What Is OPR in Malaysia and How Does It Affect Housing Loan Interest Rates?

    By Miichael Yeoh

    As someone who has spent nearly three decades in banking, mortgage advisory and property strategy, one question I get repeatedly from investors and homebuyers is:

    “Why did my bank increase (or educe) my interest rate when I didn’t change anything?”

    The answer almost always traces back to one key number — the Overnight Policy Rate (OPR).

    Let’s break down how OPR is derived, who decides it, and how it directly affects your housing loan, business financing, and even fixed deposits.


    What Is OPR?

    Bank Negara Malaysia (BNM) uses the Overnight Policy Rate (OPR) as its main monetary policy tool.

    The OPR is the interest rate at which banks lend money to one another overnight. It serves as the benchmark rate that influences all other interest rates in the country.

    Think of it as the “master switch” of Malaysia’s financial system.


    How Is OPR Derived?

    OPR is not randomly adjusted. It is decided by BNM’s Monetary Policy Committee (MPC) based on several key economic indicators:

    1️⃣ Inflation (Price Stability)

    If inflation is rising too quickly, BNM may increase OPR to slow down spending and borrowing.
    If inflation is low or the economy is weak, BNM may reduce OPR to stimulate growth.

    2️⃣ Economic Growth (GDP)

    Strong economic growth may lead to higher OPR to prevent overheating.
    Weak GDP growth may lead to lower OPR to encourage borrowing and investment.

    3️⃣ Employment & Consumer Spending

    High unemployment? Lower OPR to boost activity.
    Strong consumer demand? Possibly tighten policy.

    4️⃣ Global Economic Conditions

    US Federal Reserve rates, global trade trends, currency strength, and geopolitical risks all influence Malaysia’s monetary decisions.

    5️⃣ Financial System Stability

    BNM ensures banks remain liquid and stable. OPR adjustments help manage systemic risk.

    In simple terms:

    OPR balances growth and inflation.


    How OPR Affects Banks’ Interest Rates

    When OPR changes, banks adjust their benchmark rates such as:

    • BR (Base Rate)
    • SBR (Standardised Base Rate)

    Most housing loans today are priced as:

    SBR + Spread (e.g., SBR + 1.5%)

    When OPR increases:

    • SBR increases
    • Monthly instalments increase
    • Loan affordability reduces

    When OPR decreases:

    • SBR decreases
    • Monthly instalments reduce
    • Borrowing becomes cheaper

    Example: How It Impacts a Housing Loan

    Let’s say:

    • Loan: RM500,000
    • Tenure: 35 years
    • Rate: SBR 3.00% + 1.50% = 4.50%

    If OPR increases by 0.25%:

    • SBR may rise to 3.25%
    • New rate becomes 4.75%
    • Monthly instalment increases

    Even a 0.25% increase can mean thousands of ringgit extra over the loan tenure.

    This is why property investors must monitor OPR closely.


    Impact on Different Groups

    🏠 Homeowners

    Higher OPR = higher instalments (if on floating rate).

    🏢 Property Investors

    Rental yield may be squeezed if instalments rise but rental cannot increase proportionally.

    💼 Businesses

    Cost of financing increases, affecting expansion decisions.

    💰 Savers

    Good news — Fixed deposit rates usually improve when OPR rises.


    Why OPR Matters in Property Strategy

    As a developer consultant and property strategist, I always advise clients:

    Don’t only calculate today’s instalment. Stress-test at +1% or +2%.

    Markets move in cycles. OPR will not stay low forever.

    Smart investors:

    • Lock in good spreads during low-rate environments
    • Structure debt efficiently
    • Maintain cash flow buffers

    Final Thoughts

    OPR is not just a technical banking term.

    It is the heartbeat of the financial system, influencing property prices, loan affordability, rental yields, and overall market sentiment.

    Understanding how it works allows you to:

    • Make better borrowing decisions
    • Time property acquisitions strategically
    • Structure financing intelligently

    If you are planning your next property move, always ask:

    “What is the interest rate cycle telling me?”

    Because in property investing,
    Timing and financing strategy often matter more than price.

  • Property Refinancing in Malaysia

    Property Refinancing in Malaysia

    New Rules, Regulations & When Refinancing Actually Makes Sense

    Over the years, refinancing has been one of the most powerful financial tools for Malaysian homeowners and property investors. Used correctly, it can improve cash flow, reduce interest costs, or unlock equity for smarter investments.

    However, recent regulatory changes by Bank Negara Malaysia (BNM) mean refinancing is no longer as straightforward as before — especially when it involves cash-out.

    If you’re considering refinancing your property in 2025 or beyond, here’s what you must understand before making a move.


    What Is Property Refinancing?

    Property refinancing simply means replacing your existing home loan with a new loan, usually with another bank, based on your property’s current market value.

    Homeowners typically refinance to:

    • Get a lower interest rate
    • Reduce monthly instalments
    • Adjust loan tenure
    • Access cash from accumulated property equity
    • Consolidate high-interest debts

    The strategy itself hasn’t changed — the rules have.


    What’s New? Key Refinancing Rules You Must Know

    1. Cash-Out Refinancing Is Now More Restrictive

    One of the biggest changes affects cash-out refinancing.

    If you refinance and take extra cash for personal use (such as lifestyle spending, personal debts, or non-income-generating purposes), that portion may now be treated as personal financing, not a housing loan.

    👉 Key impact:

    • The cash-out portion may be capped at a maximum repayment tenure of 10 years
    • Monthly instalments will be significantly higher compared to spreading it over 30–35 years

    This is a major shift. In the past, many borrowers stretched cash-out amounts across the full home loan tenure, keeping instalments low but debt long.


    2. Stronger Affordability & DSR Checks

    Banks are now applying stricter Debt Service Ratio (DSR) assessments, especially for:

    • Multiple property owners
    • Refinancing with cash-out
    • Borrowers with existing personal loans or credit card balances

    Even if your property value has increased, approval is no longer guaranteed if your cash flow doesn’t support the new repayment structure.


    3. More Transparency on Loan Costs

    BNM has reinforced rules to ensure:

    • Clear disclosure of effective interest rates
    • Transparent breakdown of total repayment costs
    • Fair interest calculations based on reducing balance, not outdated methods

    This protects borrowers — but it also means banks are less flexible with “creative structuring”.


    Why Did Bank Negara Tighten Refinancing Rules?

    The objective is simple: reduce unhealthy household debt behaviour.

    Over the years, many Malaysians:

    • Used refinancing repeatedly for lifestyle spending
    • Rolled short-term debts into long-term housing loans
    • Focused on “low monthly instalment” instead of total debt impact

    The new rules encourage:

    • Responsible borrowing
    • Better financial planning
    • Using refinancing for productive purposes, not emotional decisions

    So… Why Should You Refinance a Property?

    Refinancing still makes sense — if done for the right reasons.

    1. To Lower Your Interest Rate

    If your current loan is:

    • On an old package
    • Above current market rates

    Refinancing can reduce:

    • Monthly instalments
    • Total interest paid over the loan tenure

    This is the cleanest and safest reason to refinance.


    2. To Improve Monthly Cash Flow

    Some homeowners refinance to:

    • Extend tenure
    • Reduce instalments
    • Create breathing space for cash flow

    This can be helpful during:

    • Business expansion
    • Income transition
    • Temporary financial tightening

    However, it must be done strategically, not emotionally.


    3. To Access Equity for Income-Producing Purposes

    This is where refinancing still shines — when the cash is used productively, such as:

    • Renovating a rental property
    • Funding another investment
    • Business expansion with clear returns

    Banks are generally more supportive when refinancing is tied to income generation, not consumption.


    4. Debt Consolidation (With Caution)

    Refinancing to clear:

    • Credit cards
    • Personal loans

    can reduce interest costs if discipline improves after refinancing.

    If spending habits remain unchanged, refinancing only delays the problem.


    5. To Restructure Your Property Portfolio

    For investors, refinancing can be used to:

    • Optimise loan structure across multiple properties
    • Release equity to rebalance portfolio risk
    • Improve overall holding power

    This requires proper planning — not just chasing approval.


    What You Should Consider Before Refinancing

    Before signing anything, ask yourself:

    ✔ Does refinancing truly save money after legal & valuation costs?
    ✔ Can I comfortably afford repayments if cash-out tenure is shorter?
    ✔ Am I refinancing for strategy — or short-term relief?
    ✔ Does this move strengthen my financial position 5–10 years from now?

    Refinancing is a tool. Used correctly, it builds wealth. Used wrongly, it creates silent financial stress.


    Final Thoughts from Miichael

    In today’s environment, refinancing is no longer about “how much cash can I take out”.

    The real question is:

    Does this refinancing decision improve my financial position — or just make today easier at tomorrow’s expense?

    With tighter rules in place, planning matters more than approval.

    If you’re unsure whether refinancing makes sense for your situation, get proper advice before committing. The cost of a wrong decision today can take years to undo.

  • Revisiting Malaysia’s Home Ownership Campaign: Mid-2025 Update

    Revisiting Malaysia’s Home Ownership Campaign: Mid-2025 Update

    As we come toward the mid of 2025, it’s timely to take a fresh look at the national Home Ownership Campaign (HOC) and related government initiatives aimed at making property ownership more accessible—especially for first-time buyers and middle-income earners.

    Launched originally as a short-term measure, the Home Ownership Campaign 2.0 has been extended until December 31, 2025, in recognition of ongoing housing affordability challenges faced by Malaysians. Alongside this, the Budget 2025 unveiled a series of new incentives designed to further ease the journey to homeownership.


    💡 What’s New in Mid-2025?

    1. Stamp Duty Exemption for First-Time Buyers

    One of the most attractive features of the HOC 2.0 is the 100% stamp duty exemption on properties priced at RM500,000 and below, specifically for first-time homeowners. This incentive significantly reduces the upfront cost of purchasing a home and encourages more young Malaysians to step into the property market.

    2. Housing Credit Guarantee Scheme (SJKP)

    To support those without fixed income documentation—such as gig workers, freelancers, or small business owners—the government continues to offer loan guarantees through SJKP. This allows banks to approve housing loans of up to RM500,000 even for applicants with non-traditional income streams.

    3. Step-Up Financing Scheme

    Also introduced under Budget 2025 is a new Step-Up Financing Scheme, which eases the repayment burden in the early years of a home loan. With government backing of RM5 billion, this scheme helps first-time buyers manage their finances while adjusting to homeownership.


    🧾 Tax Relief for First-Time Buyers

    From January 1, 2025, to December 31, 2027, buyers who sign a Sale and Purchase Agreement (SPA) can claim the following tax reliefs:

    • 🏠 Up to RM7,000/year for properties priced RM500,000 and below
    • 🏠 Up to RM5,000/year for properties priced between RM500,001 and RM750,000

    These tax incentives are designed to provide further savings for eligible homeowners over a 3-year period.


    🏗️ Affordable Housing Developments

    Budget 2025 also channels RM900 million toward affordable housing projects under the People’s Residency Program (PRR) and Rumah Mesra Rakyat (RMR). These programs aim to bridge the housing gap, particularly for B40 and M40 income groups, with strategic developments nationwide.

    In addition, special financial aid—up to RM90,000—is available for those building homes under schemes such as PPRT, including communities in Chinese new villages and fishing settlements.


    🔄 Rent-to-Own Scheme

    For those not ready to buy immediately, the Rent-to-Own (RTO) scheme allows applicants to rent a property for five years with the option to purchase it later. This offers a transitional pathway to homeownership while giving individuals time to strengthen their financial footing.


    ✅ Who’s Eligible?

    To enjoy the full benefits of these initiatives, applicants must typically meet the following conditions:

    • Must be Malaysian citizens aged 18 and above
    • Must be first-time homebuyers
    • Must purchase residential property priced within program thresholds
    • Some schemes may include income eligibility limits

    📊 Summary of Home Ownership Incentives (2025)

    IncentiveDetailsEligibility
    Stamp Duty Exemption100% exemption for properties ≤ RM500,000First-time buyers only
    Tax ReliefRM7,000/year (≤ RM500,000); RM5,000/year (RM500k–RM750k) for 3 yearsSPA signed between 2025–2027
    Housing Credit Guarantee (SJKP)Loan guarantee for properties ≤ RM500,000Buyers with irregular income
    Step-Up Financing SchemeReduced repayments for first 5 yearsFirst-time buyers
    Affordable Housing (PRR/RMR)RM900M allocated for low-income housing projectsB40 & M40 income groups
    Rent-to-Own (RTO) Scheme5-year rental with option to buyMiddle-income buyers

    📈 Potential Savings for a First-Time Homebuyer (Example Scenario)

    ComponentProperty Price: RM480,000Savings
    Stamp Duty (100% Exemption)Normally ~RM9,600RM9,600
    Tax Relief (RM7k/year x3)For 3 yearsRM21,000
    Lower Initial Loan Repaymentvia Step-Up Financing~RM15,000 over 5 years (est.)
    Total Potential Savings~RM45,600

    Note: Values are estimates and may vary by loan package and location.

    🏡 Final Thoughts

    Midway through 2025, Malaysia’s homeownership landscape remains favorable for aspiring buyers, thanks to proactive government support and long-term housing policies. Whether you’re looking to buy your first home, secure financing with flexible terms, or benefit from tax relief, now is an excellent time to take action.

    If you’re considering a property purchase this year, consult with certified property consultants or financial planners to understand how these incentives apply to your personal situation. With the right guidance, 2025 could be the year you unlock the door to your own home.

    From the Desk of

    Miichael Yeoh

  • Bank Negara Reduces SRR from 2% to 1%: What Does It Mean and How Will It Affect Us?

    Bank Negara Reduces SRR from 2% to 1%: What Does It Mean and How Will It Affect Us?

    Bank Negara Malaysia (BNM) has recently announced a reduction in the Statutory Reserve Requirement (SRR) ratio from 2% to 1%. This move is part of a broader strategy to ensure sufficient liquidity in the financial system, supporting economic growth amidst current economic challenges. But what exactly does this mean, and how will it impact individuals and businesses? Let’s break it down.

    Understanding SRR

    The Statutory Reserve Requirement (SRR) is the percentage of a bank’s total deposits that must be kept as reserves with Bank Negara Malaysia. Essentially, it is a tool used by the central bank to control the money supply in the economy. When the SRR is lowered, banks are required to hold less money in reserve, thereby freeing up more funds that can be lent out to businesses and individuals.

    Why Did BNM Reduce the SRR?

    The reduction in the SRR by 1% is expected to release approximately RM19 billion into the banking system, effective from 17 May 2025. This significant injection of liquidity aims to provide banks with more funds for lending and to stimulate economic activities during this period of economic uncertainty.

    The reduction in the SRR from 2% to 1% is aimed at increasing liquidity in the banking system. By allowing banks to keep less money in reserve, more funds become available for lending purposes. This is particularly crucial during periods of economic uncertainty when businesses and individuals may require more financial support. It also helps to reduce the cost of funds for banks, potentially leading to lower interest rates.

    How Does This Impact Us?

    1. More Accessible Loans: With more liquidity in the banking system, banks are more likely to offer loans to businesses and individuals. This can facilitate personal loans, home loans, and business financing, making it easier for borrowers to access funds.
    2. Lower Interest Rates: When banks have more funds to lend, competition among banks may increase, potentially leading to a reduction in lending rates. This is beneficial for borrowers seeking to refinance existing loans or take new loans.
    3. Impact on Savings and Fixed Deposits: On the flip side, while borrowers may benefit from lower interest rates, depositors may see a decrease in interest rates on their savings accounts and fixed deposits as banks adjust their rates to manage the increased liquidity.
    4. Business Expansion and Investment: With more funds available for lending, businesses may find it easier to obtain financing for expansion, investments, or operational costs. This can stimulate economic activity and potentially lead to job creation.

    Potential Risks and Considerations

    While the reduction in SRR can stimulate lending and economic growth, it is essential to consider potential risks. Increased lending could lead to higher household debt if borrowers overextend themselves. Additionally, excessive liquidity could contribute to asset bubbles if funds are channeled into speculative investments.

    Conclusion

    The reduction in SRR from 2% to 1% by Bank Negara Malaysia is a strategic move to increase liquidity and stimulate economic activity. While this creates more lending opportunities and potentially lower interest rates, it is crucial for borrowers to exercise caution and assess their financial capacity before taking on additional debt. Similarly, depositors should monitor interest rate trends to make informed decisions regarding their savings and investments.

    From The Desk of

    Miichael Yeoh

  • Unlock Wealth with Smart Mortgage Strategies

    Unlock Wealth with Smart Mortgage Strategies

    Did you know that 70% of Malaysians exhaust their EPF savings within just five years of retirement?

    This is a shocking reality, but it doesn’t have to be yours. Without proper financial and mortgage planning, many people find themselves struggling with rising living costs, increasing debt, and an uncertain future.

    Many people believe that simply saving money in a bank or relying on EPF will be enough to sustain them after retirement. However, with inflation, economic uncertainties, and an increasing cost of living, savings alone are not enough. To secure your financial future, you need a smart strategy that builds wealth while you sleep—and that’s where financial and mortgage planning come in.

    If you want to retire rich, not broke, it’s time to take control of your financial future!


    The Importance of Financial & Mortgage Planning

    1️⃣ Your Salary Alone is Not Enough

    Many Malaysians rely solely on their salaries as their primary source of income. However, depending only on salary comes with risks:
    ❌ Job insecurity – What happens if you lose your job or your business slows down?
    ❌ Limited earning potential – Salary increments may not keep up with rising expenses.
    ❌ No long-term wealth creation – Once you stop working, your income stops too.

    By understanding financial planning and leveraging mortgages, you can turn your income into wealth-building assets like property investments that generate passive income.

    ✅ Smart financial planning ensures that your money works for you, not the other way around.

    2️⃣ The Rising Cost of Living & Inflation

    The price of food, petrol, housing, and healthcare has been rising every year. What seems affordable today might be out of reach in the next five or ten years.

    📌 Example: 12 years ago, a property in Kuala Lumpur cost RM300,000. Today, the same property is worth RM600,000. If you had bought it back then, you would have gained RM300,000 in capital appreciation.

    Now imagine if you had invested in properties over the years—how much wealth would you have built?

    This is why financial planning and leveraging mortgages for property investment is crucial. The sooner you start, the better you can protect yourself from inflation and rising costs.

    3️⃣ Using Mortgages as a Wealth-Building Tool

    Many people see mortgages as a burden. But in reality, a mortgage is one of the most powerful financial tools you can use to build wealth.

    Here’s how:
    ✅ Leverage: With a mortgage, you can own high-value properties with only a fraction of the cost upfront.
    ✅ Passive Income: By renting out your properties, you create a steady income stream that covers loan repayments and generates profit.
    ✅ Capital Appreciation: Over time, property values tend to increase, helping you build long-term wealth.

    4️⃣ Securing Your Retirement with Smart Investments

    Many retirees face financial struggles because they failed to plan early. Without a steady stream of passive income, they depend entirely on their savings, which can deplete quickly.

    A well-structured mortgage plan can help you own multiple properties that generate rental income. This means that by the time you retire, you’ll have a steady cash flow to support your lifestyle—without relying on savings alone!


    How to Start Planning Your Financial Future Today

    🔹 Understand how mortgages work – Learn how to maximize loan approvals and use mortgages to grow your wealth.
    🔹 Invest in the right properties – Avoid costly mistakes and find properties that give high returns.
    🔹 Create multiple income streams – Secure your future with passive income from real estate investments.

    Final Thought: The Best Time to Invest is NOW!

    Many people delay financial planning, thinking they have plenty of time. But the truth is, the longer you wait, the harder it becomes to build wealth.

    💡 The best time to invest was yesterday. The second-best time is NOW!

    🚀 Don’t wait until it’s too late. Take charge of your financial future today!

    From the Desk of

    Miichael Yeoh

  • Real Estate Summit 2025: A Resounding Success!

    Real Estate Summit 2025: A Resounding Success!

    After two days of insightful discussions, expert sharing, and valuable networking, the Real Estate Summit 2025 (RES2025) has officially concluded! This event brought together some of the most renowned experts in real estate, finance, and investment, providing participants with actionable insights into the property market, financial planning, and smart investment strategies for 2025.

    We were honored to welcome participants from Malaysia, the Philippines, Singapore, the USA, Germany, and many other countries. The diversity of attendees enriched discussions and created a vibrant learning environment.

    A Heartfelt Thank You to Our Participants & Speakers

    First and foremost, we extend our deepest gratitude to all participants for attending RES2025. Your enthusiasm and eagerness to learn made this event truly impactful.

    A special appreciation to our distinguished speakers, whose expertise and insights played a crucial role in the success of RES2025:

    🔹 Dato’ Sri Gavin Tee – A real estate expert who shared his forecast on the 2025 property market and upcoming investment opportunities.
    🔹 Richard Oon – A taxation and financial planning specialist who guided participants on tax-saving strategies and financial management for property investors.
    🔹 Dr. Daniele Gambero – A respected market analyst who discussed real estate trends, mortgage challenges, and investment potential in 2025.
    🔹 Dr. Elane Goh – A finance and investment strategist who shared her insights on wealth creation through property investments and financial planning.
    🔹 WK Ng – A seasoned property investor who transitioned from the corporate world to full-time investing, providing real-life success strategies.
    🔹 KW Wong – A PropTech innovator and Secretary-General of the Malaysia PropTech Association, who spoke about the digital transformation of the rental market.
    🔹 Charles Tan – A leading property market analyst who offered valuable perspectives on Malaysia’s evolving real estate landscape.
    🔹 Miichael Yeoh – A mortgage and financial expert, who emphasized the importance of planning before making any major investment decisions.

    Your dedication and willingness to share your knowledge made RES2025 a game-changing event for all attendees.

    Special thanks to our co-organiser POLA Malaysia and our media partners Property Hunter and kopiandproperty.

    Key Takeaways from RES2025

    Throughout the two-day summit, participants gained powerful insights into the property industry, with topics covering:

    ✔️ Where to Invest in 2025 – Discovering high-potential investment hotspots.
    ✔️ Real Estate Market Trends – Adapting to economic shifts and evolving regulations.
    ✔️ Financial Planning & Taxation – Understanding tax incentives, financial structures, and mortgage strategies.
    ✔️ Mortgage Market 2025 – The latest developments in home financing and lending policies.
    ✔️ PropTech Innovations – The rise of digital property platforms and the impact on buying, selling, and renting.
    ✔️ Investment Strategies – How to build a profitable real estate portfolio.

    As Miichael Yeoh emphasized in his session: “Plan first before making your next move.” Strategic financial and investment planning is essential to achieving long-term success in real estate.

    The Power of Networking & Knowledge Sharing

    Beyond expert talks, RES2025 provided an invaluable opportunity for participants to connect with industry leaders, experienced investors, and like-minded individuals. The event fostered an environment where attendees could exchange ideas, gain exclusive insights, and build meaningful professional relationships.

    Looking Forward: What’s Next?

    The success of RES2025 reaffirms GM Training Academy’s commitment to empowering individuals with property education and financial literacy. We believe that informed decisions lead to successful investments, and we are dedicated to helping investors, homeowners, and professionals navigate the ever-changing real estate market.

    🚀 Upcoming Initiatives:

    ✅ More masterclasses and training workshops
    ✅ Exclusive webinars featuring top industry experts
    ✅ Property investment study tours
    ✅ Advanced financial and mortgage planning courses

    Stay Connected & Keep Learning

    📢 Missed RES2025? No worries! Stay connected with us for upcoming programs that will continue to provide valuable industry insights and expert guidance.

    Once again, THANK YOU to all our participants and speakers for making RES2025 a grand success! We look forward to seeing you at our next event.

  • Malaysia’s Loan Scandal: Consultancies Siphon 35% from Borrowers

    Malaysia’s Loan Scandal: Consultancies Siphon 35% from Borrowers

    A major financial scandal in Malaysia has exposed a corrupt syndicate involving consultancy firms and bank officials, who siphoned 35% of approved loans from borrowers, primarily civil servants. The Malaysian Anti-Corruption Commission (MACC) revealed that these firms manipulated loan processes, securing multiple overlapping loans for victims, leaving them with crippling debts. Over RM700 million in loans were processed, but borrowers received only a fraction after exorbitant fees. The MACC’s ongoing crackdown has arrested 27 individuals and frozen RM22 million in assets, but the financial and emotional toll on victims remains severe.

    Click for more Information or Sign Up

    This issue has persisted for years, with many property buyers enticed to purchase multiple properties beyond their means. For instance, individuals with a RM5,000 salary were lured into buying 10 properties with high cashback offers, only to face financial ruin. In one case, a couple after attending my seminar shared how they were encouraged by a “Property Guru” to buy five properties at once, exploiting bank loopholes. They later discovered the properties were overpriced and unrentable, leaving them bankrupt with RM16,000 monthly installments and two young children to support. This highlights the dangers of reckless investment decisions. Always verify sources, avoid intermediaries charging excessive fees, and ensure investments align with your financial capacity.

    From the Desk of

    Miichael Yeoh

    Read the full article…..

    Bank Loan Scandal: How Consultancy Firms Pocketed 35% from Borrowers’ Loans

    By: Kpost

    A financial scandal of massive proportions has rocked Malaysia’s banking sector, exposing a corrupt syndicate that preyed on borrowers, especially civil servants, by siphoning off exorbitant fees from approved bank loans.

    The Malaysian Anti-Corruption Commission (MACC) recently uncovered that financial consultancy firms, operating under the guise of loan facilitators, were pocketing at least 35% of the approved loan amounts, leaving victims with far less than what they had borrowed.

    A Web of Deceit: How Borrowers Were Trapped

    The scheme involved consultancy firms manipulating the loan approval process in collusion with corrupt bank officials. According to MACC Chief Commissioner Tan Sri Azam Baki, the syndicate exploited desperate borrowers by securing multiple loans from various financial institutions simultaneously, orchestrating a complex scam that resulted in borrowers being burdened with insurmountable debts.

    “These firms orchestrated ‘multiple loans’ by manipulating bank systems and turn-around times, making it seem as if previous loans had been settled when, in reality, they had not. This deception ensured that borrowers would receive overlapping loans, only to have substantial portions deducted as ‘fees,’” said Azam.

    Many victims, entangled in financial distress and seeking funds to settle previous debts, unknowingly agreed to the terms set by these firms. In addition to the 35% consultancy fee, borrowers were also subjected to loan settlement charges of up to 40%, further exacerbating their financial woes.

    RM700 Million in Loans: But Victims Still Drowning in Debt

    The investigation, codenamed Ops Sky, revealed that the syndicate managed to secure approximately RM700 million in loans for borrowers. However, instead of receiving their full loan amounts, victims were left with only a fraction of what they applied for, leading to a debt crisis far beyond their means to repay.

    Despite the dismantling of the syndicate, the damage has already been done. Many victims now owe three times more than their financial capabilities allow, making repayment virtually impossible. “Even though the syndicate has been dismantled, borrowers remain indebted to the banks and must continue servicing their loans,” Azam stated.

    Massive Crackdown: Bank Officers and Syndicate Members Arrested

    In a coordinated crackdown, MACC and Bank Negara Malaysia raided 24 locations across the Klang Valley, including residences and offices linked to the syndicate. The operation led to the arrest of 12 key individuals, including bank officials and employees of the financial consultancy firms involved.

    Further investigations revealed that 98 company and personal bank accounts worth over RM22 million had been frozen, and nearly 4,000 documents seized as part of the evidence collection.

    A total of 27 individuals, including 18 bank officers, eight financial consultancy employees, and one member of the public, were detained before being released on bail.

    Social Media and Celebrities Used to Lure Victims

    Adding another layer to the scandal, the syndicate aggressively marketed its services using social media influencers, celebrities, and public figures to gain credibility.

    Advertisements flooded Facebook, TikTok, and Instagram, targeting schoolteachers, nurses, and government employees.

    The firms even conducted surveys, roadshows, and CSR programs at schools and hospitals, falsely promoting their services as legitimate financial solutions.

    What’s Next? Ongoing Investigations and a Warning to the Public

    The MACC has vowed to continue its investigations under Ops Sky, with more witnesses expected to be summoned. The public is urged to be cautious when dealing with financial consultancy firms that promise easy loans, especially those charging high service fees upfront. “This case serves as a stark warning and always verify loan processes directly with the bank and avoid intermediaries who demand excessive fees,” Azam cautioned.

    As investigations continue, Malaysians are left questioning how such large-scale corruption involving multiple financial institutions could have persisted unchecked for so long. The financial burden on victims remains heavy, and the battle for justice is far from over.

    Information Source: Newswav