Tag: michael yeoh

  • Before You Buy Property, Do This First — Or You’re Just Guessing

    Before You Buy Property, Do This First — Or You’re Just Guessing

    Smart Investors Don’t Start With Property — They Start With Demand

    Most people think property investment starts with:

    Location.
    Price.
    Developer.

    It doesn’t.

    It starts with a much more fundamental question:

    Are you buying for own use… or for investment?

    Because if you get this wrong, everything else becomes noise.


    Step 1: Define Your Purpose (No Grey Area)

    I’ve seen buyers say they are investing…

    But make decisions based on:

    • Design
    • Lifestyle
    • Personal preference

    That’s not investing.

    That’s emotion.

    If it’s own stay, you follow your lifestyle.

    If it’s investment, you follow demand and numbers.


    Step 2: Know Your Budget (This Sets Your Playing Field)

    Before anything else:

    • What is your true affordability?
    • What is your financing capacity?
    • What is your holding strength?

    Because in property:

    You don’t lose money when you buy wrong.
    You lose money when you can’t hold.

    Especially for investors—cash flow and holding power are everything.

    Step 3: Real Investors Do One Thing Differently — They RESEARCH

    This is the biggest gap in the market.

    Most buyers rely on:

    • Marketing materials
    • Sales narratives
    • “Good location” claims

    But experienced investors?

    They study the market before they commit.


    What Do You Actually Research?

    1. Demand & Demographics (The Real Starting Point)

    Forget the building first.

    Ask:

    Who is the end user of this property?

    • Young professionals?
    • Families?
    • Tourists?
    • Businesses?

    If you don’t understand demand,
    you’re not investing—you’re guessing.


    And This Is Where Industrial Property Becomes Interesting

    For big-budget investors, the shift is already happening.

    Demand is no longer driven by lifestyle.

    It’s driven by business movement and capital flow.

    Look at what’s happening:

    • Manufacturing relocation into Malaysia
    • Growth in logistics and warehousing
    • E-commerce expansion
    • Supply chain restructuring across ASEAN

    This creates a different type of demand:

    • Larger space requirements
    • Functional layouts over aesthetics
    • Accessibility to ports, highways, and labour
    • Long-term tenancy from businesses (not individuals)

    In other words:

    Industrial demand is economic-driven, not sentiment-driven.

    And that’s exactly what sophisticated investors are looking for.


    2. Price Per Square Foot (Entry Determines Exit)

    You make money when you buy right.

    Compare:

    • Nearby transactions
    • Competing projects
    • Replacement cost

    If you enter too high, your upside is already limited.


    3. Surrounding Supply (The Silent Risk)

    Most investors ignore this.

    But supply determines:

    • Rental pressure
    • Vacancy risk
    • Exit liquidity

    Too much incoming supply?

    Even a “good project” can underperform.


    4. Infrastructure & Connectivity (Follow the Growth)

    No area grows randomly.

    Growth follows:

    • Highways
    • Ports
    • Rail (LRT / MRT / logistics links)
    • Industrial corridors

    If infrastructure is expanding, demand usually follows.


    5. Rental & Yield Reality Check

    At the end of the day:

    Can it generate income?

    • What is the realistic rental?
    • Who is the tenant profile?
    • What is the occupancy expectation?

    If the numbers don’t work on paper,
    don’t rely on hope.


    What I’ve Learned From the Ground

    After evaluating multiple projects and markets, one thing is clear:

    The winners are not those who buy the most.
    The winners are those who understand demand the best.

    Every property I consider goes through:

    • Demand validation
    • Market comparison
    • Supply analysis
    • Financial assessment

    Because once you commit,
    you’re not just buying property…

    You’re locking in a decision for years.


    Final Thought

    Property investment has evolved.

    It’s no longer about chasing what’s popular.

    It’s about understanding why demand exists—and where it’s going next.

    Those who do the work will always have an edge.

    Those who don’t…

    Will always be reacting.


    Disclaimer: This reflects the author’s personal views based on market experience and current observations. It is not financial advice. Smart investors do their own research before making any move.

    From the Desk of

    Miichael Yeoh
  • Property Is Still Alive — But the Game Has Changed

    Property Is Still Alive — But the Game Has Changed

    Buying a property today is very different compared to 10 or 20 years ago.

    Back then, property could sell very easily.
    Developers launched, buyers queued, and decisions were made quickly.

    Today, the world has changed.

    The way people buy property has changed.
    The way markets behave has changed.
    And more importantly, the way buyers think has changed.

    Buyers today are far more informed.

    Before even paying a booking fee, many would have already:

    • Compared multiple projects
    • Studied pricing trends
    • Checked developer track record
    • Analysed location fundamentals
    • Calculated loan eligibility and cash flow

    In other words, today’s buyers are not just buyers — they are researchers.


    At the same time, the global environment is not exactly calm.

    We are seeing ongoing geopolitical tensions — from the US–Iran situation to instability in parts of the Middle East.
    Interest rates, inflation, and currency movements continue to shift.

    All these create one thing: uncertainty.

    And when uncertainty comes in, market behaviour changes.

    From what I observe in today’s property market:

    • Investors are waiting — not exiting
    • Sellers are holding — not reducing
    • Buyers are selective — not absent

    Let that sink in.

    The market is not dead.
    It is simply… more cautious.


    And here is something many people miss:

    👉 When the market is not stable, that is where the opportunity lies.

    Why?

    Because:

    • Less emotional buying
    • More rational pricing
    • More room for negotiation
    • More time to analyse properly

    In a hot market, people chase.
    In a cautious market, people choose.

    And those who choose well, win.


    This is exactly why I started focusing on Property Market Intelligence.

    Not just looking at property as a product,
    but understanding:

    • Market timing
    • Buyer psychology
    • Financing structure
    • Exit strategy
    • Risk positioning

    This approach is built from more than 25 years in the property and banking industry.

    I have gone through multiple market cycles:

    • Asian Financial Crisis
    • Global Financial Crisis
    • Property slowdowns
    • Policy changes
    • And shifting buyer behaviours across decades

    Every cycle teaches one thing:

    👉 The market will always move — but not everyone moves with it.


    Today, success in property is no longer about:
    “Buy and wait.”

    It is about:
    “Buy with clarity.”

    Because in today’s market:

    • Information is everywhere
    • But insight is rare

    If you are buying today, don’t just ask:

    “Is this a good property?”

    Ask instead:

    • Who will buy from me later?
    • What is the demand driver here?
    • How does financing affect my holding power?
    • What happens if the market stays slow for 3–5 years?

    That is how professionals think.


    The market has not disappeared.

    It has simply matured.

    And in a mature market,
    strategy will always beat impulse.


    Miichael Yeoh
    Property Strategist | Author

    Author of:
    Think Like a Banker, Act Like a Player
    Property Investment BLT
    Buying Property Like a Pro (MPH Bestseller)

  • Will the US–Israel–Iran War Affect Property in Malaysia?

    Will the US–Israel–Iran War Affect Property in Malaysia?

    Will the US–Israel–Iran War Affect Property in Malaysia?

    Most people think war is “far away”.

    Middle East… not Malaysia… not our problem.

    But if you’ve been in property long enough, you’ll realise this:

    What happens globally will always find its way into your loan, your instalment, and your tenant’s wallet.

    Let’s break it down — from a real-world property perspective.


    1. The Impact Will Not Be Direct — But It Will Be Real

    Malaysia is not at war.

    Our property market is not suddenly crashing tomorrow.

    In fact, economists say the direct impact on Malaysia is limited — but the indirect effects are where things get interesting.

    And property… is always affected by indirect forces.


    2. The First Domino: Oil Prices

    Right now, oil prices are already spiking above USD100 due to the conflict.

    Why does this matter?

    Because oil affects everything:

    • Construction cost (cement, steel, transport)
    • Developer margins
    • Inflation
    • Interest rates

    When oil goes up → cost of living goes up → buyers become more cautious

    And this is where property sentiment starts to shift.


    3. Rising Cost of Living = Slower Property Decisions

    Experts already warn that prolonged conflict will push up:

    • Food prices
    • Fertiliser costs
    • Transportation costs

    We are already seeing supply chain disruptions globally.

    Simple logic:

    When people feel poorer… they delay big decisions.

    And property is the biggest decision of all.

    From my experience:

    • First-time buyers will hesitate
    • Investors will become more selective
    • Loan approvals may tighten

    4. Interest Rates — The Silent Killer

    War → Inflation → Central banks stay cautious

    Even if Bank Negara doesn’t immediately raise rates, the global environment matters.

    If inflation remains high:

    • Financing cost stays elevated
    • Instalments stay high
    • Yield becomes more important than ever

    This is where many investors get it wrong.

    They buy based on “price appreciation”.

    But in uncertain times:

    Cash flow becomes king.


    5. Currency & Investor Sentiment

    During global conflict:

    • Money flows to “safe havens”
    • Emerging markets (like Malaysia) can see weaker currency

    This affects:

    • Foreign investment
    • High-end property demand
    • Developer confidence

    It doesn’t crash the market…

    But it slows momentum.


    6. The Hidden Opportunity (Most People Miss This)

    Here’s the part many don’t talk about.

    Malaysia is actually in a neutral advantage position:

    • We are politically stable
    • Not directly involved
    • Still attractive compared to more volatile regions

    Historically, during global uncertainty:

    Smart investors don’t exit — they reposition.

    Opportunities may appear in:

    • Undervalued projects
    • Developers needing stronger sales
    • Better packages (rebates, freebies, furnished units)

    Sound familiar?


    7. My Personal Take (From the Ground)

    I’ve gone through multiple cycles — financial crisis, policy changes, Covid.

    War is just another external shock.

    And property always reacts in the same pattern:

    Phase 1: Fear
    Phase 2: Slowdown
    Phase 3: Adjustment
    Phase 4: Opportunity

    Right now, we are somewhere between Phase 1 and 2.


    Final Thought

    Will this war affect Malaysia property?

    Yes — but not in the way most people think.

    It won’t crash the market overnight.

    But it will:

    • Change buyer behaviour
    • Shift investor strategy
    • Reward those who understand fundamentals

    And this is where experience matters.


    My Advice

    If you are buying:

    • Don’t panic
    • Don’t rush
    • Focus on cash flow, not speculation

    If you are investing:

    This is the time to be sharper — not quieter.


    Miichael Yeoh
    Property Strategist | Author

    Author of:
    Think Like a Banker, Act Like a Player
    Property Investment BLT
    Buying Property Like a Pro (MPH Bestseller)

  • How AI Is Reshaping the Way We Buy Property

    How AI Is Reshaping the Way We Buy Property

    In today’s digital world, buying property is no longer just about location, price, and site visits. Artificial Intelligence (AI) is quietly influencing how buyers think, search, and eventually make decisions.

    Whether you realize it or not, AI is already part of your property journey.


    1. How AI Affects Our Buying Decisions

    AI has changed the way we consume information.

    In the past, buyers relied on agents, brochures, and physical visits. Today, what you see online is curated based on your behavior:

    • What you search
    • What you click
    • What you watch

    Over time, AI builds a profile of your preferences and starts feeding you properties that match your interest.

    Many buyers feel like they “found” the property themselves.

    But in reality, AI has already filtered the options for you.


    2. Property Marketing vs Other Products — Same Model, Different Weight

    From my experience, property marketing is not very different from other products.

    It follows a similar digital marketing structure.

    But the difference is this:

    👉 Property is a high-value, long-term commitment

    You are not buying something for RM1. You are committing hundreds of thousands or even millions.

    Because of that, the marketing is designed to:

    • Build trust
    • Educate
    • Reassure
    • Reduce risk

    It is less about pushing a sale, and more about guiding a decision.


    3. The Sales Funnel Is Always There

    Every product follows a sales funnel.

    Some marketers execute it well. Some only do part of it. Some only focus on getting attention.

    In property, you will typically go through stages like:

    • Seeing ads
    • Clicking to learn more
    • Registering interest
    • Communicating with salespeople
    • Visiting or evaluating

    Whether you notice it or not, you are being guided step by step.


    4. “Why Am I Suddenly Seeing Property Ads Everywhere?”

    This is something many people experience.

    You talk to a friend about buying property… You search a few listings…

    Next thing you know, when you open Facebook or Instagram:

    👉 Property ads start appearing everywhere.

    This is how AI and digital tracking work.

    It picks up signals from your behavior and starts showing you more relevant content.

    It is not magic — it is data.


    5. The Moment You Click, Your Journey Changes

    Once you click on an ad, your journey becomes more intentional.

    You may start seeing:

    • More related ads
    • Follow-up messages
    • Invitations to previews
    • Additional information and content

    This is how modern property marketing works today.


    6. Not All Campaigns Are the Same

    The experience you get depends on the developer or salesperson.

    Some are very basic. Some are more structured and consistent.

    But regardless of how advanced the system is, one thing remains the same:

    👉 The final decision is still yours.


    7. My Perspective as a Property Buyer

    From my own experience in property, one thing is very clear:

    👉 We cannot avoid AI.

    It is already part of how information is delivered to us.

    But here is the part many people overlook:

    AI can influence your interest, but it should not replace your judgment.

    At the end of the day:

    • You are not buying a cheap product
    • You are committing significant capital
    • You are making a long-term financial decision

    Because of that, buyers must still:

    ✔ Do proper research ✔ Understand the numbers ✔ Assess their holding power ✔ Evaluate the location and fundamentals

    And most importantly:

    👉 Listen to people who have real experience in property

    Not everything online tells the full story.


    Final Thoughts

    AI is a powerful tool.

    It can help you discover opportunities faster. It can guide you through options you may not have seen before.

    But it should never replace:

    • Due diligence
    • Critical thinking
    • Experience-based advice

    In property, the difference between a good decision and a bad one is not the advertisement you saw…

    It is the quality of the decision you make after that.

    At the end of the day, AI may influence what you see…

    But it should never replace how you think.

    Property is not a small purchase.
    It’s a long-term financial commitment.

    The difference is not in the advertisement you saw —
    It’s in the decision you make after that.

    Make sure it’s a well-informed one

    From the Desk of

    Miichael Yeoh
    Property Strategist | Author

    Author of:

    Think Like a Banker, Act Like a Player

    Property Investment BLT Buying

    Property Like a Pro (MPH Bestseller)

    P.S. Follow for consistent, experience-based property insights — beyond what marketing tells you.

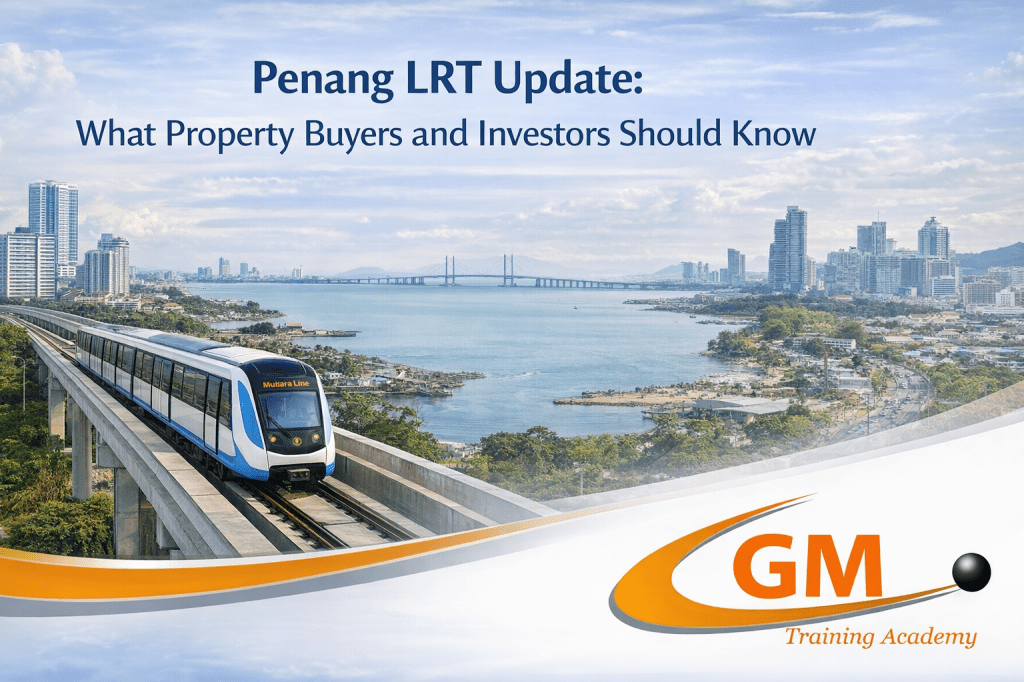
  • Penang LRT Update: What Property Buyers and Investors Should Know

    Penang LRT Update: What Property Buyers and Investors Should Know

    For years, the lack of rail transit has been one of the biggest infrastructure gaps in Penang. While cities like Kuala Lumpur have extensive rail networks, Penang has relied heavily on cars and buses.

    That is now changing.

    The Penang Light Rail Transit (LRT) project — known as the Mutiara Line — is officially underway, marking one of the largest infrastructure developments in northern Malaysia. For property buyers and investors, this project will reshape accessibility, mobility, and potentially property values across key corridors in Penang.

    In this article, we explore the latest updates on the Penang LRT and what it means for the property market.


    1. Overview of the Penang LRT (Mutiara Line)

    The Mutiara Line will be Penang’s first urban rail system and the first LRT outside the Klang Valley. It forms a key component of the Penang Transport Master Plan (PTMP) aimed at improving connectivity across the island and mainland.

    Key facts about the project:

    • Length: approximately 29.5 km
    • Stations: about 21 stations
    • Type: elevated light rail system
    • Estimated cost: about RM16–17 billion
    • Target completion: around 2031

    The line will connect Silicon Island / Penang South Reclamation area to Penang Sentral, passing through major areas such as:

    • Bayan Lepas
    • Sungai Tiram
    • Gelugor
    • Jelutong
    • George Town (Komtar)

    It will also link with Penang Sentral, providing connections to ETS, KTM Komuter and ferry services.

    This integration is designed to create a seamless transport system between Penang Island and Seberang Perai.


    2. Latest Construction Updates (2025–2026)

    Recent developments show that the project has moved from planning into active implementation.

    Penang projects powering ahead

    Important milestones include:

    Construction has begun
    The first phase of works started in 2025, with contractors appointed and preliminary works such as soil investigations and site preparation underway.

    Major works expanding in 2026
    Construction activity is expected to intensify throughout 2026, including elevated track construction and station development.

    Traffic diversions already in place
    Road diversions along areas such as Jalan Sultan Azlan Shah near Bayan Lepas have begun to accommodate construction works that may last up to 38 months.

    Public inspection of revised rail scheme
    Authorities have also opened a public inspection period for revised plans, including a proposed cross-sea link to Penang Sentral, which will strengthen connectivity between the island and mainland.


    3. Why the LRT Matters for the Property Market

    Infrastructure has always played a major role in shaping property values.

    Based on experiences in Kuala Lumpur, rail transit typically creates three types of property impact.

    1️⃣ Transit-Oriented Development (TOD)

    Properties located near LRT stations tend to see increased demand due to convenience and connectivity.

    Areas expected to benefit include:

    • Bayan Lepas
    • Sungai Nibong
    • Gelugor
    • Jelutong
    • Komtar / George Town

    These areas could evolve into future TOD zones, attracting both residential and commercial developments.


    2️⃣ Improved Accessibility

    Currently, travelling from Bayan Lepas to George Town during peak hours can take more than an hour.

    With the LRT:

    • Travel time could be significantly reduced
    • Workers in the Bayan Lepas industrial zone gain easier access to the city
    • Tourism and business mobility improve

    Better connectivity often leads to stronger rental demand.


    3️⃣ Long-Term Economic Growth

    The LRT is not just a transport project. It is also a strategic economic infrastructure designed to support:

    • Silicon Island development
    • the Bayan Lepas industrial hub
    • tourism in George Town
    • cross-strait connectivity with mainland Penang

    Large infrastructure projects tend to stimulate surrounding investments and commercial activity.


    4. A Strategic Perspective for Property Buyers

    However, buying property purely because it is near an LRT station is not enough.

    From an investment perspective, buyers should still analyse:

    • Rental demand around the station
    • Employment nodes nearby
    • Supply of new developments
    • Holding power during construction years

    The Penang LRT is expected to complete around 2031, meaning property investors must adopt a long-term view rather than short-term speculation.


    Final Thoughts

    The Penang LRT has been discussed for more than a decade. Now that construction has begun, the project is moving from concept to reality.

    For Penang, the LRT represents more than just a transport system — it is a structural shift in how the city grows and how people move.

    For property buyers and investors, the key question is no longer whether the LRT will happen.

    The real question is:

    Are you positioning your property decisions ahead of this infrastructure transformation?


    Written by:
    Miichael Yeoh
    Property Strategist | Developer Consultant | Investment & Mortgage


    References

    1. MRT Corp – Mutiara Line Project Information
    2. Bernama – Penang LRT construction update
    3. The Star / Penang infrastructure updates
    4. Malay Mail / Infrastructure reports on LRT cost and timeline
    5. Wikipedia – Mutiara Line LRT project overview
  • Think Like a Banker Before You Buy Property

    Think Like a Banker Before You Buy Property

    One thing I learned from working closely with banks is this:

    Banks are extremely careful before approving a property loan.

    They analyse risks, stress-test your finances, and study whether you can survive difficult situations.

    But here’s the irony.

    Many property buyers don’t analyse their purchase the same way.

    They look at the show unit.
    They listen to marketing promises.
    They follow what others are buying.

    But they rarely ask the same questions a banker would ask.

    If you want to invest in property wisely, start by thinking like a banker.

    Here are three things bankers always analyse.


    1️⃣ Debt Ratio – Are You Stretching Yourself Too Thin?

    Banks look closely at your Debt Service Ratio (DSR).

    This measures how much of your income is used to pay debts.

    Even if a bank approves your loan, you should still ask yourself:

    • What happens if interest rates increase?
    • What if my income drops temporarily?
    • Will I still feel comfortable servicing the loan?

    A property might look affordable today.

    But bankers always plan for tomorrow’s risks.


    2️⃣ Holding Power – Can You Hold Through Market Cycles?

    Property markets don’t always go up.

    There will be slow periods.

    Bankers evaluate whether a borrower has the financial strength to continue paying during tough times.

    Smart investors should ask:

    • Can I hold this property for 5–10 years if needed?
    • Do I have cash reserves?
    • What if the market takes longer to recover?

    Many investors fail not because they bought the wrong property…

    They fail because they cannot hold it long enough.


    3️⃣ Rental Sustainability – Can the Property Support Itself?

    Another banker mindset is income sustainability.

    Before buying, ask:

    • Is there real rental demand here?
    • Who are the potential tenants?
    • Can the rental help support the loan?

    A strong investment property should ideally generate rental income that supports part of the financing.

    This reduces pressure and improves long-term stability.


    Final Thought

    Successful property investors don’t buy emotionally.

    They evaluate property like a banker evaluating risk.

    Before your next purchase, ask yourself:

    Does this property pass the banker’s test?

    When you start thinking like a banker, you don’t just buy property.

    You build a stronger and safer property portfolio.


    Miichael Yeoh
    Property Strategist | Developer Consultant | Investment & Mortgage Expert
    Author of Think Like a Banker, Act Like a Player

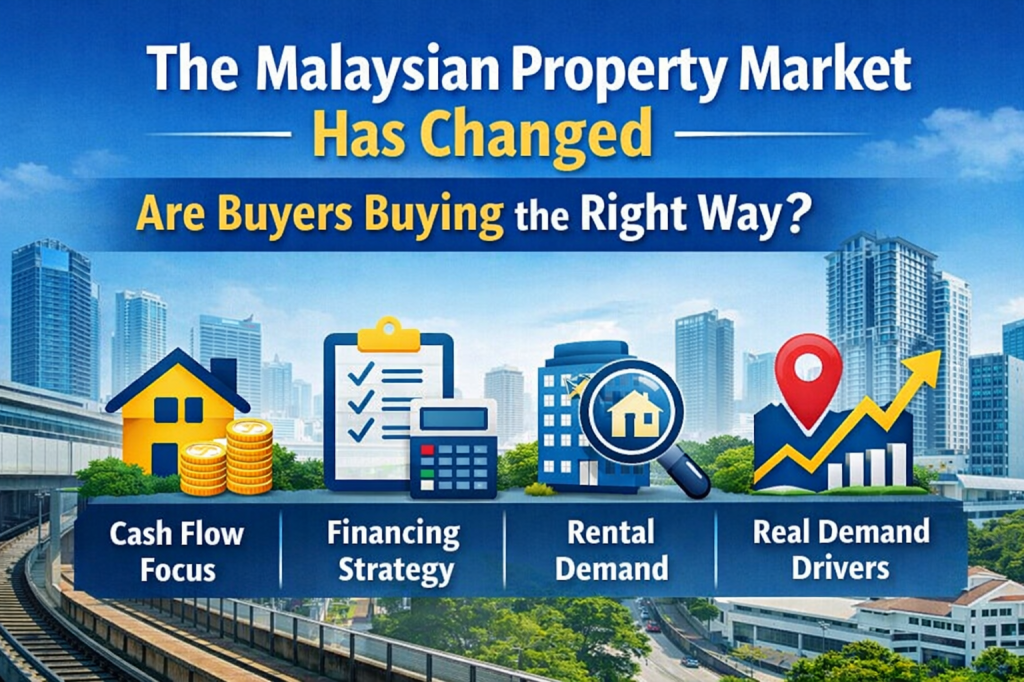
  • The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?

    The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?

    The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?

    For many years, property investing in Malaysia followed a familiar formula.

    Buy a new launch, wait a few years, and hope the price goes up.

    This strategy worked reasonably well during earlier property cycles when prices were rising quickly, financing was easier, and supply was more limited. Many investors entered the market believing that capital appreciation alone would justify the purchase.

    But today, the Malaysian property market has entered a different phase.

    The question buyers should now ask is no longer “Will the price go up?”
    The more important question is “Can this property sustain itself financially?”


    The Shift From Speculation to Sustainability

    Over the past decade, the mindset of property buyers has gradually evolved.

    Today’s buyers are more cautious, more analytical, and more focused on cash flow and long-term holding power.

    Instead of relying purely on future price appreciation, investors are increasingly asking questions such as:

    • What is the rental demand in this area?
    • Can the rental cover most of the loan instalment?
    • What happens if interest rates increase?
    • Who is the actual tenant profile for this property?

    These questions reflect a more mature approach to property investing.

    The reality is simple: not every property will appreciate significantly in the short term. When appreciation slows, the ability of the property to generate rental income becomes far more important.


    Financing Strategy Now Matters More Than Ever

    Another major shift in the market is the growing importance of financing structure.

    Many buyers focus heavily on the purchase price but pay little attention to how the property is financed. Yet the financing strategy can determine whether an investment becomes manageable or financially stressful.

    Buyers today need to consider:

    • Loan margin and interest rates
    • Monthly instalment affordability
    • Holding power during market slowdowns
    • Overall debt exposure

    A well-structured loan can give investors time and flexibility, while poor financial planning can force them to sell prematurely.

    Thinking about financing before buying is no longer optional — it is essential.


    Rental Demand Is Becoming a Key Decision Factor

    One of the biggest mistakes many investors made in the past was buying properties without considering who would actually rent the unit.

    Today, buyers are beginning to look more closely at demand drivers such as:

    • Proximity to employment hubs
    • Accessibility and transportation infrastructure
    • Nearby universities or hospitals
    • Tourism demand and short-term rental potential

    In markets like Penang, Kuala Lumpur, and Johor Bahru, rental demand is increasingly shaping investment decisions.

    For example, areas with strong tourism activity or major infrastructure developments may offer better rental prospects compared to purely speculative locations.

    The key question investors should ask is:

    “Who is my tenant?”

    If there is no clear answer, the investment may not perform as expected.


    The Role of Infrastructure and Economic Drivers

    Another important factor influencing property performance today is real economic activity.

    Infrastructure projects, transportation connectivity, employment centres, and tourism growth can significantly impact both rental demand and long-term property value.

    For instance, upcoming transportation developments and urban revitalisation projects in cities such as Georgetown could change demand patterns in the coming years.

    However, infrastructure alone does not guarantee success. The surrounding ecosystem — population growth, business activity, and lifestyle demand — must also support the property market.


    Buying Property Today Requires a Different Mindset

    The Malaysian property market has not disappeared. But the way buyers approach property must evolve.

    Successful investors today tend to follow a more balanced approach:

    • Evaluate rental yield and cash flow
    • Structure financing carefully
    • Understand real demand drivers
    • Focus on long-term sustainability

    In other words, the focus has shifted from short-term speculation to long-term investment discipline.


    A Final Thought

    Property has always been a long-term asset class.

    But in today’s market environment, buying property requires more than just optimism about future price growth.

    It requires careful thinking, realistic financial planning, and a clear understanding of market demand.

    The Malaysian property market has changed.

    The real question is — have buyers changed with it?


    Miichael Yeoh
    Property Strategist | Developer Consultant | HRD Corp Trainer

    Miichael Yeoh has more than 28 years of experience spanning banking, mortgage advisory, property investment, and developer consultancy. He is also the author of Think Like a Banker, Act Like a Player, Property Investment BLT, and Buying Property Like A Pro.

  • What Is OPR in Malaysia and How Does It Affect Housing Loan Interest Rates?

    What Is OPR in Malaysia and How Does It Affect Housing Loan Interest Rates?

    By Miichael Yeoh

    As someone who has spent nearly three decades in banking, mortgage advisory and property strategy, one question I get repeatedly from investors and homebuyers is:

    “Why did my bank increase (or educe) my interest rate when I didn’t change anything?”

    The answer almost always traces back to one key number — the Overnight Policy Rate (OPR).

    Let’s break down how OPR is derived, who decides it, and how it directly affects your housing loan, business financing, and even fixed deposits.


    What Is OPR?

    Bank Negara Malaysia (BNM) uses the Overnight Policy Rate (OPR) as its main monetary policy tool.

    The OPR is the interest rate at which banks lend money to one another overnight. It serves as the benchmark rate that influences all other interest rates in the country.

    Think of it as the “master switch” of Malaysia’s financial system.


    How Is OPR Derived?

    OPR is not randomly adjusted. It is decided by BNM’s Monetary Policy Committee (MPC) based on several key economic indicators:

    1️⃣ Inflation (Price Stability)

    If inflation is rising too quickly, BNM may increase OPR to slow down spending and borrowing.
    If inflation is low or the economy is weak, BNM may reduce OPR to stimulate growth.

    2️⃣ Economic Growth (GDP)

    Strong economic growth may lead to higher OPR to prevent overheating.
    Weak GDP growth may lead to lower OPR to encourage borrowing and investment.

    3️⃣ Employment & Consumer Spending

    High unemployment? Lower OPR to boost activity.
    Strong consumer demand? Possibly tighten policy.

    4️⃣ Global Economic Conditions

    US Federal Reserve rates, global trade trends, currency strength, and geopolitical risks all influence Malaysia’s monetary decisions.

    5️⃣ Financial System Stability

    BNM ensures banks remain liquid and stable. OPR adjustments help manage systemic risk.

    In simple terms:

    OPR balances growth and inflation.


    How OPR Affects Banks’ Interest Rates

    When OPR changes, banks adjust their benchmark rates such as:

    • BR (Base Rate)
    • SBR (Standardised Base Rate)

    Most housing loans today are priced as:

    SBR + Spread (e.g., SBR + 1.5%)

    When OPR increases:

    • SBR increases
    • Monthly instalments increase
    • Loan affordability reduces

    When OPR decreases:

    • SBR decreases
    • Monthly instalments reduce
    • Borrowing becomes cheaper

    Example: How It Impacts a Housing Loan

    Let’s say:

    • Loan: RM500,000
    • Tenure: 35 years
    • Rate: SBR 3.00% + 1.50% = 4.50%

    If OPR increases by 0.25%:

    • SBR may rise to 3.25%
    • New rate becomes 4.75%
    • Monthly instalment increases

    Even a 0.25% increase can mean thousands of ringgit extra over the loan tenure.

    This is why property investors must monitor OPR closely.


    Impact on Different Groups

    🏠 Homeowners

    Higher OPR = higher instalments (if on floating rate).

    🏢 Property Investors

    Rental yield may be squeezed if instalments rise but rental cannot increase proportionally.

    💼 Businesses

    Cost of financing increases, affecting expansion decisions.

    💰 Savers

    Good news — Fixed deposit rates usually improve when OPR rises.


    Why OPR Matters in Property Strategy

    As a developer consultant and property strategist, I always advise clients:

    Don’t only calculate today’s instalment. Stress-test at +1% or +2%.

    Markets move in cycles. OPR will not stay low forever.

    Smart investors:

    • Lock in good spreads during low-rate environments
    • Structure debt efficiently
    • Maintain cash flow buffers

    Final Thoughts

    OPR is not just a technical banking term.

    It is the heartbeat of the financial system, influencing property prices, loan affordability, rental yields, and overall market sentiment.

    Understanding how it works allows you to:

    • Make better borrowing decisions
    • Time property acquisitions strategically
    • Structure financing intelligently

    If you are planning your next property move, always ask:

    “What is the interest rate cycle telling me?”

    Because in property investing,
    Timing and financing strategy often matter more than price.

  • LHDN Just Released the 2025 Tax Relief List

    LHDN Just Released the 2025 Tax Relief List

    LHDN Just Released the 2025 Tax Relief List

    Here’s What You Can Claim Before the Year Ends

    LHDN has officially released the 2025 Income Tax Relief List, and this is one update every Malaysian taxpayer should pay attention to — especially employees, business owners, and property investors.

    Why?
    Because tax reliefs are legal ways to reduce your tax payable, yet many Malaysians either under-claim or miss them entirely due to poor planning or last-minute filing.

    Let’s break down what this means and how you can optimise your tax position before the year ends.


    What Is the LHDN Tax Relief List?

    The LHDN Tax Relief List outlines approved expenses that taxpayers can deduct from their chargeable income when filing their annual income tax return.

    Simply put:
    👉 The more legitimate reliefs you claim, the less tax you pay — legally.

    This list is updated periodically to reflect:

    • Rising cost of living
    • Education and healthcare needs
    • Retirement and family responsibilities
    • Digital and lifestyle expenses

    Key Tax Reliefs Malaysians Can Claim in 2025

    Below are some of the most commonly used — yet often under-claimed — tax reliefs for YA 2025.


    1. Individual & Dependent Relief

    • Individual relief: RM9,000
    • Spouse (no income): RM4,000
    • Child relief: up to RM8,000 per child (higher for education level)

    👉 Ensure your spouse and children details are properly declared.


    2. Lifestyle Expenses (Up to RM2,500)

    This remains one of the most popular reliefs, covering:

    • Books, journals, magazines
    • Sports equipment
    • Computer, smartphone, tablet
    • Internet subscription

    ⚠ Keep receipts — LHDN may request proof.


    3. Medical Expenses (Self, Spouse & Parents)

    You can claim medical expenses for:

    • Serious diseases
    • Medical check-ups
    • Dental treatment
    • Special needs and disabilities

    Claims can go up to RM8,000, depending on category.


    4. EPF, Insurance & Retirement Planning

    One of the most powerful tax-saving tools:

    • EPF contributions: up to RM4,000
    • Life insurance: up to RM3,000
    • PRS contributions: additional relief available

    👉 Smart retirement planning = lower tax + future security.


    5. Education & Skill Development

    You may claim:

    • Self-education fees (recognised courses)
    • Professional certifications
    • Postgraduate studies

    This is especially relevant for professionals and business owners upgrading their skills.


    6. Housing-Related Reliefs (If Applicable)

    Depending on eligibility:

    • Housing loan interest relief (subject to conditions)
    • First-time homebuyer incentives (if applicable)

    ⚠ These are often misunderstood — get proper advice before claiming.


    Common Mistakes Taxpayers Make

    From my experience, many taxpayers:

    • Rush to file without reviewing reliefs
    • Lose receipts and documentation
    • Assume certain expenses are “not claimable”
    • Follow advice from unverified online sources
    • Claim incorrectly and risk penalties later

    Remember:
    ❌ Under-claiming = paying more tax than necessary
    ❌ Wrong claiming = penalties and audit risk


    What You Should Do Before Year End

    Here’s a simple checklist:

    ✔ Review the 2025 relief list early
    ✔ Plan major expenses before 31 December
    ✔ Organise receipts digitally
    ✔ Review EPF, insurance, and PRS contributions
    ✔ Seek advice if you have rental or business income

    Tax planning is not done in April — it’s done before December ends.


    Final Thoughts from Miichael

    Tax reliefs are not loopholes — they are government-approved incentives meant to ease financial burden.

    Those who benefit most are not the highest earners —
    but those who plan early and claim correctly.

    If you’re unsure what you can claim, especially as a property investor, freelancer, or business owner, get clarity before filing.

    From the desk of

    Miichael Yeoh
  • Residential Property & Mortgage Trends in Malaysia (2026 and beyond)

    Residential Property & Mortgage Trends in Malaysia (2026 and beyond)

    By Miichael Yeoh

    The Malaysian property market has been through a lot in the last few years — pandemic, inflation, rising construction costs, slow wage growth, and changing buyer behaviour. But as we step into 2025, one thing is clear:

    Property is still moving… but the market is no longer the same.
    Buyers are more cautious, banks are more selective, and affordability remains a major issue.

    Here’s my take on what’s really happening in the residential property and mortgage landscape, and what you should pay attention to — especially if you’re planning to buy, invest, or restructure your loans.


    📈 Long-Term Price Trend: Property Still Moves Up

    Whether the market is “good” or “bad”, one fact remains consistent:

    Property prices in Malaysia have been rising steadily for the last 20+ years.

    Urban areas like Klang Valley, Penang and Johor consistently show appreciation because of:

    • population growth
    • job concentration
    • infrastructure development
    • scarcity of prime land

    But here’s the catch:
    House prices have risen much faster than income, making affordability the No.1 challenge for Malaysians today.

    This explains why many young buyers are stuck deciding between renting longer… or compromising on location and size.


    🏘️ What’s Happening in the Market Now?

    1. Transaction volume is rising — but buyers are choosy

    2024 recorded strong growth in overall property transactions, and 2025 is projected to see single-digit positive growth.
    People are buying — but not blindly.

    Buyers today compare:

    • price per sq ft
    • rental potential
    • exit value
    • access to MRT / LRT
    • developer reputation

    Gone are the days when anything “new launch” can sell out.
    Today, value matters more than hype.


    💰 Mortgage & Financing Trend: Here’s the Real Story

    The biggest shift recently is OPR dropping to 2.75%, making borrowing cheaper.

    This directly means:

    • Lower monthly instalments
    • Higher loan eligibility
    • Better cashflow for investors

    But with great news comes reality…
    Banks are approving loans more carefully than ever.

    Your CCRIS, CTOS, commitments and even gig-income consistency matter.
    If your financial health is not clean, even a low OPR won’t help you.

    For many Malaysians, the challenge isn’t interest rate — it’s getting the loan approved.


    🧱 Supply vs Demand: The Affordable Gap

    You’re hearing this everywhere:

    “So many houses unsold!”
    —but at the same time—
    “I can’t find any home I can afford!”

    Why?
    Because the overhang is mainly:

    • too expensive for the mass market
    • too big (1,000 sq ft and above)
    • wrong location

    This mismatch will continue unless developers pivot more aggressively into the mid-market segment.


    🧭 What Buyers & Investors Should Look At Now

    ✔️ If you’re a first-time buyer

    This is a golden window.
    Low OPR + many choices + developers offering incentives = value for money.

    Look for:

    • good location > big size
    • future MRT/LRT corridors
    • reputable developers
    • high rental demand areas

    ✔️ If you’re an investor

    Capital gain will still happen — but don’t expect overnight appreciation.
    Focus on:

    • rental yield
    • undervalued areas
    • distress or motivated sellers
    • T.O.P. projects with ready tenants

    The smart investors in 2025 are not speculating.
    They’re buying below market value, or in growth corridors, or early in new infrastructure zones.

    ✔️ If you own multiple properties with loans

    This is the best time to:

    • refinance
    • consolidate debts
    • reset your cashflow
    • restructure your portfolio

    A small adjustment in interest rate can save thousands per year.


    🧩 Conclusion: The Market Isn’t Booming, But It’s Moving

    Malaysia’s residential market today is stable, resilient, and buyer-driven.
    We’re not in a bubble.
    We’re not in a crash.

    We’re in a value-driven market, where the winners are:
    ✔️ informed buyers
    ✔️ strategic investors
    ✔️ those who manage their loans wisely

    If you understand the trends — and you know how to analyse value correctly — 2025-2026 can be a very profitable year for you.

  • Boost Your Loan Approval Chances in Malaysia

    Boost Your Loan Approval Chances in Malaysia

    Malaysian bank lending (especially for property purchases) is currently shaped by several key monetary, regulatory, and market-demand factors. Rates have been easing somewhat, but approval conditions remain cautious. Below are the latest numbers and trends.


    Current Figures & Trends

    1. Overnight Policy Rate (OPR) & Reference Rates
      • In July 2025, Bank Negara Malaysia (BNM) cut the OPR from 3.00% to 2.75% – the first cut in five years.
      • Major banks have adjusted their Standardised Base Rate (SBR) to 2.75% per annum following the OPR cut.
      • Base Rate (BR) has also been adjusted (for many banks) in line with this, though BR tends to be higher than SBR. For example, Alliance Bank’s BR is about 3.57%.
    2. Base Lending Rate / Base Financing Rate (BLR/BFR)
      • The BLR or BFR (for Islamic financings) for many banks remains in the ~6.35% to ~6.65% range. For example, Maybank’s BLR is 6.40%, Hong Leong Bank’s is ~6.64%, etc. baserate.my+3Maybank2u+3NewPages+3
    3. Effective Housing Loan Rates
      • While the base/reference rates give a starting point, effective lending rates (what borrowers actually pay) tend to be higher because banks add a margin/spread depending on risk, loan amount, tenure, etc.
      • Recent reports suggest effective rates for housing loans are in many cases 4.15% to 5.7% p.a. depending on bank, borrower profile, loan value, promotion, etc. Property Genie
    4. Loan Approval & Volume
      • There was a 25.7% month-on-month increase in approvals of housing-loan applications in July 2025 after a slump in June. Focus Malaysia – Business & Beyond
      • The approval ratio (i.e. approved vs applied) in July 2025 was about 44.8%, up from ~42.6% in June 2025. Focus Malaysia – Business & Beyond
      • On a year-on-year basis, total approved loan volume declined by ~5.1% for that month; cumulatively over the first 7 months of 2025, approved property loans were ~RM 161.4 billion, about -1.5% relative to same period in previous year. Focus Malaysia – Business & Beyond
    5. Outlook
      • With lower OPR and more competitive base/reference rates, there is optimism that loan approvals (both volume and ratio) may improve in the remaining months of 2025. Government’s likely to include incentives in Budget 2026 to support first-time buyers, low-to-middle income groups. Focus Malaysia – Business & Beyond

    Steps Borrowers Can Take to Increase Chances of Loan Approval

    Given the current environment, borrowers can do several things to strengthen their applications and improve likelihood of approval. Here are practical steps, both before and during application.

    StepWhat to DoWhy It Helps
    1. Check & Clean Up Your Credit HistoryObtain your credit report (e.g. through CTOS, CCRIS, Experian) ahead of time. Ensure there are no outstanding defaults, ensure credit card/HP payments are on time.Banks check creditworthiness; a clean credit history reduces risk and may allow you to access better rates.
    2. Assess Debt Service Ratio (DSR) / Total CommitmentsKnow your monthly obligations: other loans, credit cards, etc. Make sure your net income minus all obligations leaves enough room for loan instalments. Try to reduce existing liabilities if possible.Banks often reject or charge higher margins if your debts relative to income are too high. Lower commitments improves affordability assessment.
    3. Have Stable & Adequate IncomeDemonstrate consistent employment or business income; have documentation (pay slips, tax returns, EPF contributions). If self-employed or commission-based, provide past 2-3 years’ income statements, audited if possible.Stability & predictability of income give banks confidence in your ability to repay.
    4. Make Reasonable Down Payment / EquityThe more you put down (lower loan-to-value ratio), the less risk for the bank. If you’re first-time buyer programs exist (often requiring only 10% payment), check eligibility, but be aware these may still have stricter conditions.Less loan amount relative to property value helps bank exposure and reduces margin required.
    5. Choose Appropriate Loan TenureLonger tenure reduces monthly instalments but increases total interest paid; very long tenure may raise risk from bank’s perspective (future rate changes, income changes). Balance payroll constraints with ability to service.A manageable monthly repayment improves approval chances; less risk of default.
    6. Prepare All Supporting Documents ProperlyHave ready: identity documents, employment letters, income proof, EPF statements, tax returns (if applicable), bank statements, any other asset documentation. Ensure documents are current.It speeds up processing and reduces grounds for rejection due to missing information.
    7. Shop Around & Compare OffersDifferent banks have different margins, promotions, and underwriting criteria. Get multiple quotes. Negotiate (sometimes banks reduce spread or offer incentives).May get better rate, lower fees, more favorable terms.
    8. Provide Clear Purpose & Property DetailsHave the Sale & Purchase Agreement (SPA), valuation report (if needed), title deed, property details, etc. If property is new or under construction, ensure developer’s track record and required approvals are in order.Banks assess property risk as well: location, title, developer credibility affect approval.
    9. Maintain Good Savings / ReservesHaving savings or avoid fully depleting your accounts helps; having reserves gives cushion in case of rate increases or unexpected expenses.Shows financial discipline and lowers risk from bank’s viewpoint.
    10. Understand Bank Fees & RequirementsBe aware of legal fees, valuation fees, stamp duties, insurance (MRTA/MRTT), and any bank-specific requirements (e.g. guarantor, joint-applicant). Make sure to budget for them.Unexpected costs can derail the process; being well-prepared ensures smoother approval.

    Challenges & What Borrowers Should Watch Out For

    • Even with OPR at 2.75% and SBR adjusted, banks’ margins/spreads can still be high depending on borrower risk. So effective rates may still be less favourable for some.
    • Approval ratios (~44-47%) show that over half of applications still get declined. That means it’s not just about rates; credit & affordability are being closely scrutinized. Focus Malaysia – Business & Beyond
    • Rising costs for legal fees, valuation, and sometimes hidden fees can make total cost of financing higher than expected.
    • Inflation, future rate rises, economic uncertainties mean banks may reserve right to tighten conditions suddenly.


    Conclusion

    Bank lending is currently becoming somewhat more favourable in Malaysia thanks to the OPR cut and adjusted reference rates. However, borrowers must still present strong, well-prepared loan applications. Cleaning up credit, reducing existing obligations, having stable income and proper documentation, and choosing appropriate loan terms are all crucial.

  • 💰 Household Debt in Malaysia – Should We Be Worried?

    💰 Household Debt in Malaysia – Should We Be Worried?

    If you’ve been hearing about household debt in the news and wondering what it means for us Malaysians, here’s the lowdown—without the boring jargon.

    Historical Context

    • 2008 marked a low point in household debt relative to GDP, at 60.4%, showing moderate borrowing during that period. CEIC Data
    • In 2020, debt peaked during the pandemic, reaching a record 93.1% of GDP. CEIC Data
    • As of 2023, debt remained elevated at 84.2% of GDP, up from 80.9% in 2022. CEIC Data

    These figures indicate that while debt declined from its 2020 high, it remains higher than pre-pandemic levels—an ongoing concern.

    The Latest Numbers (2024–2025)

    • In June 2024, household debt stood at around RM1.57 trillion, accounting for 83.8% of GDP. Housing loans comprised 61%, followed by vehicle loans (13.5%) and personal financing (12.4%).
    • By March 2025, debt rose to RM1.65 trillion, or 84.3% of GDP.

    Interestingly, household financial assets were reported to exceed debt by a factor of 2.1, suggesting Malaysians as a whole still have a substantial financial cushion. Additionally, prudent lending practices are maintained, with median debt service ratios (DSR) remaining at 34% for existing loans and 41% for newly approved loans (2024).


    What This Means for Malaysians

    Risks

    1. Sustained High Debt Load
      With debt hovering around 84% of GDP, many households must allocate a significant portion of income toward repayments—possibly limiting spending on essentials.
    2. Rising Youth Bankruptcy
      Between 2020 and early 2025, over 5,272 youths under 34 were declared bankrupt, with nearly 877 cases in 2024 alone. Personal loans accounted for 46.4% of these filings.
    3. Potential for Over-Leveraging via BNPL
      Growing use of “Buy Now, Pay Later” (BNPL) services (e.g., Atome, Grab PayLater) raises concerns, as they operate outside traditional credit tracking like CCRIS and may enable unmonitored debt accumulation.
    4. Lenient Lending to Young Graduates
      Experts warn that easy credit access for fresh graduates—especially via credit cards—could foster poor financial habits without proper income checks or financial literacy.

    Positive Offsets

    1. Healthy Asset Buffer
      Households’ financial assets outpacing their debts by over double implies a buffer that could cushion against economic shocks.
    2. Responsible Lending Frameworks
      With the Responsible Financing guidelines and relatively moderate DSRs, household borrowing still aligns with regulatory safety standards.
    3. Support Services Available
      Agencies like AKPK have helped over 64,000 borrowers settle loans, while nearly 270,000 others continue to receive support through debt management programs.

    Balancing Act: Looking Forward

    • Economic Growth vs. Debt Sustainability
      While household debt has eased somewhat from its pandemic-era peak, it remains elevated, and spikes in personal or BNPL borrowing could strain households—especially lower-income groups.
    • Youth Financial Health
      The rising bankruptcy trend among the young underscores the necessity of stronger financial education and tighter lending criteria for vulnerable demographics.
    • Policy Opportunities
      Strengthening regulation around new lending platforms like BNPL, embedding financial literacy into early education, and enforcing responsible credit access remain vital steps to prevent systemic vulnerabilities.

    In Summary

    Household debt in Malaysia has declined from its 2020 highs but remains elevated, hovering around 84% of GDP in 2024–2025. While household financial assets provide a buffer and regulatory frameworks offer some protection, rising personal debt—especially among youths and via emerging platforms like BNPL—pose risks. Continued focus on financial education, responsible lending policies, and inclusive support systems will be key to ensuring long-term household resilience.