Tag: investment

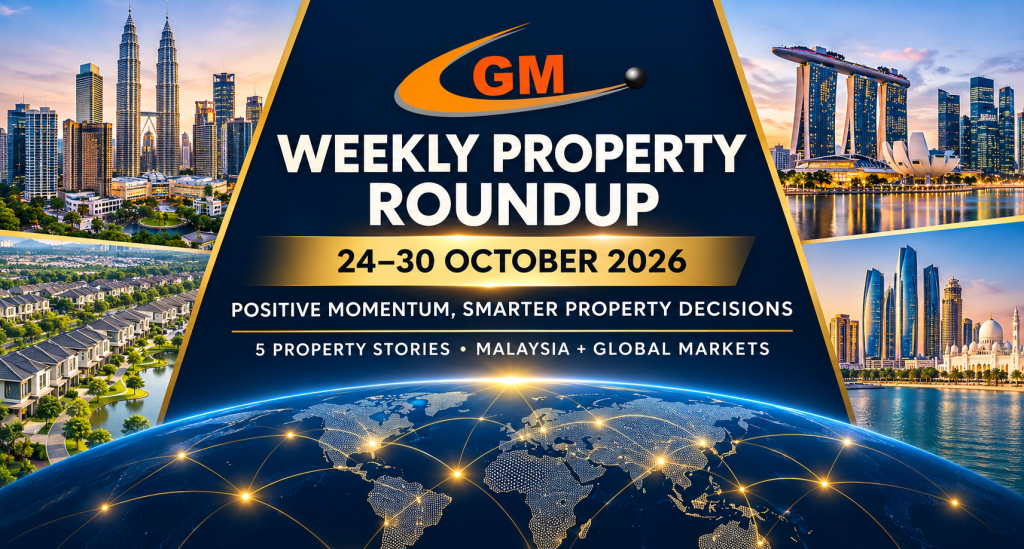
  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    24–30 October 2026

    Positive Momentum. Smarter Property Decisions.

    Five developments worth paying attention to this week — three from Malaysia and two from international markets.

    🇲🇾 MALAYSIA PROPERTY MARKET

    Story 1 — GDB Secures RM1.02 Billion Desa ParkCity Construction Contract
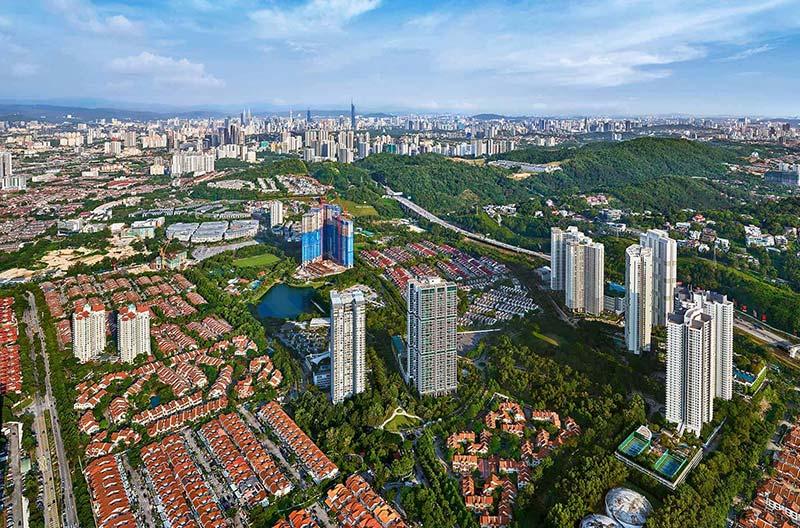
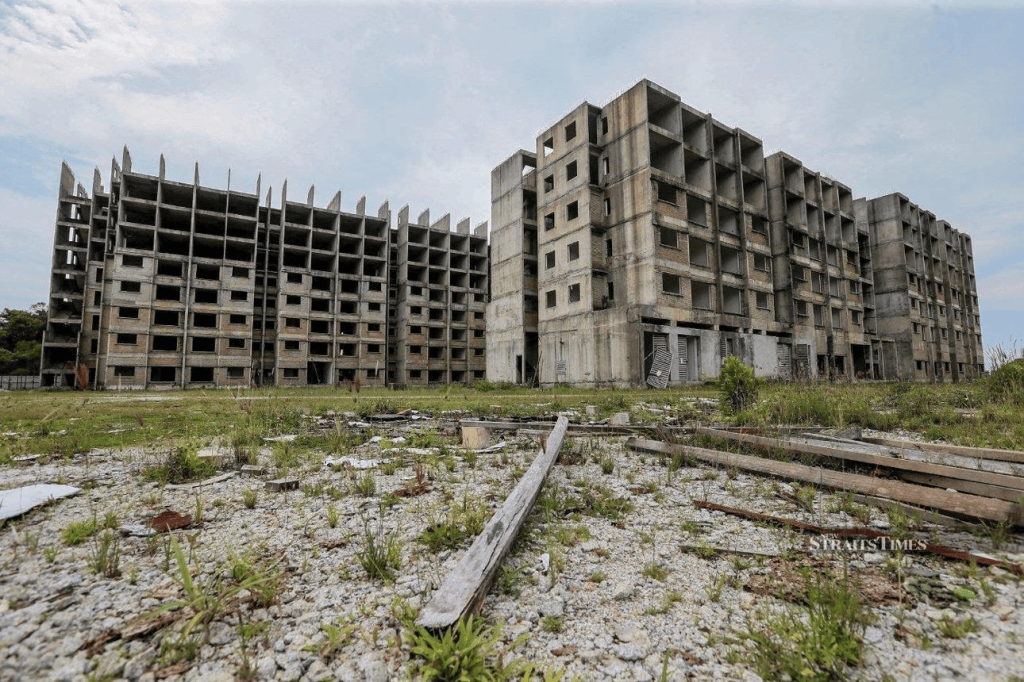
    South Brooks @ Desa ParkCity

    What Happened?

    Malaysian construction group GDB Holdings Berhad secured a RM1.02 billion construction contract from Perdana ParkCity to build ParkCity Residences in Desa ParkCity, Kuala Lumpur.

    The development comprises:

    • Two residential blocks.
    • 433 apartments.
    • A seven-storey podium with amenities and parking.
    • Two basement parking levels.

    Construction is scheduled to begin in November 2026, with completion targeted for August 2031.

    Following this award, GDB’s year-to-date contract wins increased to RM1.81 billion, while its outstanding order book reached approximately RM2.05 billion. EdgeProp

    Source: EdgeProp — GDB secures RM1.02b ParkCity Residences contract.

    Why It Matters

    This is a significant construction award that provides greater visibility over GDB’s future workload.

    It also reflects continued investment in established residential townships, where infrastructure, amenities and community planning have already helped create a recognised residential environment.

    However, a large contract value does not automatically translate into profit. Construction costs, project execution, payment schedules and delivery timelines remain important.

    Miichael’s Review

    I find this development interesting because it highlights the importance of the relationship between developers and experienced construction partners.

    A successful development requires more than good land and an attractive concept. Execution capability, cost management and timely delivery are equally important.

    For buyers, the track record of the developer and its delivery partners deserves attention.

    My view: A property’s value is influenced not only by its location and design, but also by the ability of the development team to deliver what was promised.
    Story 2 — Tropicana Launches Avisa Residences Phase 2 After Strong First-Phase Take-up

    What Happened?

    Tropicana Corporation Berhad introduced the second phase of Avisa Residences at Tropicana Alam, Puncak Alam, on 29 October.

    The launch follows reported sales take-up of more than 90% for Phase 1, which comprised 431 units. StarProperty

    Source: StarProperty — Tropicana unveils Avisa Residences Phase 2.

    Why It Matters

    The first-phase take-up is an encouraging indicator of buyer interest in the development.

    For developers, successful sales performance can provide confidence to proceed with subsequent phases.

    However, sales take-up should be interpreted carefully. It is important to distinguish between bookings, signed sale and purchase agreements and completed transactions.

    We should also consider the profile of buyers, cancellation rates and the actual affordability of the units.

    Miichael’s Review

    This is a useful example of why we should look beyond the launch itself.

    A development that achieves strong take-up may indicate that its product positioning, pricing and target market are aligned.

    But I would still ask:

    • Who are the actual buyers?
    • Are they buying for own occupation or investment?
    • Is the pricing supported by comparable transactions?
    • What is the surrounding supply pipeline?
    • Can the location support long-term demand?

    My view: Strong sales are encouraging, but sustainable demand is what ultimately matters. A successful first phase is a positive starting point, not a guarantee of future performance.

    Story 3 — Matrix Concepts Proposes RM169.3 Million Kulai Land Acquisition

    What Happened?

    Matrix Concepts Holdings Berhad proposed acquiring 57 parcels of vacant agricultural land in Kulai, Johor, for approximately RM169.31 million.

    The combined land area is approximately:

    • 431.88 acres.
    • 174.77 hectares.
    • 57 separate parcels.

    Matrix’s preliminary feasibility assessment estimates a potential gross development value of approximately RM2.1 billion for a mixed development.

    The proposed acquisition is subject to conditions including title rectifications, transfer approvals and estate documentation. The agreements are interconditional, meaning the parcels must complete together. EdgeProp

    Source: EdgeProp — Matrix proposes RM169.3m Kulai land buy.

    Why It Matters

    Johor continues to attract attention from property developers looking to expand their landbanks.

    A large land acquisition gives a developer the opportunity to plan a development over multiple phases, potentially responding to changing demand and infrastructure improvements.

    But the estimated RM2.1 billion GDV is a feasibility projection, not guaranteed revenue or profit.

    The ultimate success will depend on approvals, development costs, infrastructure, market demand and the timing of future launches.

    Miichael’s Review

    Landbank expansion is an important part of a developer’s long-term strategy.

    However, acquiring land is only the first step. The more important question is whether the developer can transform that land into a viable development that meets the needs of the surrounding population.

    I would pay particular attention to employment growth, accessibility, competing supply and the affordability of the eventual products.

    My view: The best landbank opportunities are not necessarily the cheapest. They are the ones where location, planning, infrastructure and genuine future demand come together.

    🌏 INTERNATIONAL PROPERTY WATCH
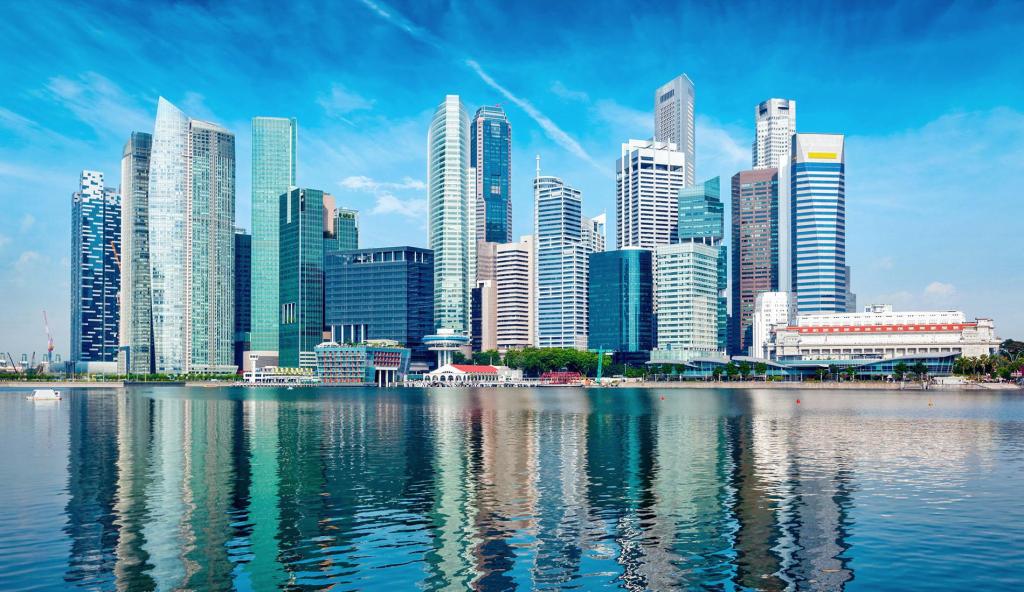
    This week we’re looking at Singapore and the United Arab Emirates — two markets showing encouraging investment activity.

    🇸🇬 Story 4 — Asia-Pacific Property Investment Reaches US$65.6 Billion in Q3

    What Happened?

    Knight Frank reported that Asia-Pacific commercial real estate investment reached US$65.6 billion in Q3 2026, representing:

    • 17.9% growth quarter-on-quarter.
    • 7.3% growth year-on-year.
    • Second-highest quarterly investment volume on record.

    Year-to-date investment reached US$183.4 billion, up 29.3% year-on-year.

    Singapore was the region’s second-largest destination for cross-border investment, attracting US$3.4 billion, an increase of 75.9% year-on-year.

    Major transactions involving Paragon and Wheelock Place reflected investor interest in prime retail and commercial properties. Global

    Source: Knight Frank — Asia-Pacific Q3 2026 investment report, 30 October.

    Why It Matters

    This is an encouraging signal for the regional commercial property sector.

    Investors are returning to selected markets, particularly established gateway cities with strong tenant demand and limited supply of quality assets.

    Singapore’s performance demonstrates the continued appeal of well-located commercial properties.

    However, Knight Frank also cautioned that higher borrowing costs are putting pressure on investment returns and liquidity.

    Miichael’s Review

    What interests me most is the type of properties attracting capital.

    Investors are not simply buying property because the market is growing. They are looking for assets that can generate reliable income.

    This is an important distinction.

    A prime commercial building with strong occupancy and quality tenants may offer a more attractive risk profile than an asset with uncertain rental demand.

    My view: Property investment is increasingly about income quality, asset fundamentals and financial discipline. The ability to generate sustainable rental income remains a major consideration.

    🇦🇪 Story 5 — Aldar Reports 19% Growth in Nine-Month Net Profit

    What Happened?

    Abu Dhabi-based developer Aldar Properties reported strong financial performance for the first nine months of 2026.

    Key figures include:

    Financial measure9M 2026
    RevenueAED26.2 billion
    Revenue growth+11%
    Net profitAED7.1 billion
    Net profit growth+19%
    Development salesAED18.9 billion
    Development backlogAED71.6 billion

    The company also reported that its UAE sales to overseas and expatriate resident buyers reached AED11.3 billion, representing 78% of total UAE sales.

    Its investment business recorded adjusted EBITDA growth of 21% to AED2.8 billion, supported by high occupancy and rental growth. Aldar

    Source: Aldar — Q3 2026 financial results, 27 October.

    Why It Matters

    Aldar’s results show how a property group can build its business through a combination of development sales and recurring rental income.

    Its development backlog of AED71.6 billion also provides a degree of revenue visibility over the coming years, although actual conversion depends on project delivery and market conditions.

    The strong contribution from overseas and expatriate resident buyers also highlights the international dimension of Abu Dhabi’s property market.

    Miichael’s Review

    I find Aldar’s business model particularly interesting because it combines two important areas:

    1. Property development, which generates revenue through project sales.
    2. Investment properties, which provide recurring rental income.

    These two activities can complement each other and help diversify a property group’s earnings.

    For developers, it is a reminder that long-term business resilience should not depend entirely on launching and selling new projects.

    My view: A strong property company needs more than sales momentum. It needs a balanced portfolio, disciplined financial management and the ability to generate recurring income.

    WORTH WATCHING

    MarketDevelopment to monitorWhy it matters
    MalaysiaGDB’s ParkCity Residences construction progressDelivery execution and construction pipeline
    MalaysiaTropicana Avisa Phase 2Whether first-phase demand carries into the next phase
    JohorMatrix Concepts’ Kulai land acquisitionApproval, land assembly and future development plans
    SingaporeCommercial property investment activityWhether investor confidence remains strong
    UAEAldar’s development backlog and recurring incomeWhether current growth translates into sustainable earnings

    MY TAKEAWAY THIS WEEK

    This week’s roundup gives us several encouraging signals.

    Malaysia continues to see development activity, with a major construction award in Kuala Lumpur, strong reported take-up for a residential project in Selangor and further landbank expansion in Johor.

    Internationally, Singapore continues to attract commercial property investment, while Aldar’s results demonstrate the potential of combining development sales with recurring property income.

    But there is one common lesson across all five stories.

    A property opportunity should always be evaluated beyond its headline numbers.

    A large construction contract, high sales take-up, attractive GDV or strong corporate earnings can be encouraging. However, we still need to understand the underlying fundamentals.

    For buyers, it is affordability and genuine housing needs.

    For investors, it is rental income, asset quality and financial sustainability.

    For developers, it is the ability to match product, location and pricing with actual market demand.

    That is why I continue to believe that better property decisions begin with better property understanding.

    Look beyond the price. Discover better. Decide smarter.

    Miichael Yeoh
    PROPERTY STRATEGIST
    http://www.miichaelyeoh.com
  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    10–16 October 2026

    LOOK BEYOND THE PRICE

    Five stories. Three Malaysian developments. Two international markets. One objective: helping buyers and investors make better-informed property decisions.

    🇲🇾 MALAYSIA PROPERTY MARKET

    STORY 1 — Why Are Malaysian Property Developers Becoming More Cautious?

    What Happened?

    A property industry survey reported by The Edge Malaysia on 15 October revealed that 63% of surveyed developers had no plans to launch residential projects in the second half of 2026.

    The survey by the Real Estate and Housing Developers’ Association Malaysia (REHDA) covered 181 respondents in Peninsular Malaysia.

    Key findings included:

    • 114 of 181 respondents had no plans for residential launches in the second half of 2026.
    • The remaining respondents planned to launch 18,696 units.
    • 77% of respondents reported financing difficulties during the first half of 2026.
    • 59% of respondents with relevant data reported unsold completed residential units as at 30 June 2026.
    • Among respondents who reported unsold completed units, 32% said some of their stock had remained unsold for more than three years.

    Developers cited market conditions, approval delays and existing unsold inventory as reasons for their cautious approach. The Edge Malaysia

    Source: The Edge Malaysia — REHDA property industry survey, 15 October 2026

    Why It Matters

    This is an important signal for Malaysia’s property market.

    A high number of new launches does not automatically mean a healthy market. What matters is whether homes are priced appropriately, buyers can obtain financing and completed units find genuine occupants.

    The financing figures are particularly noteworthy. Demand for housing may exist, but prospective buyers still need to qualify for loans and manage their financial commitments.

    Developers must also balance construction costs against what their target customers can realistically afford.

    Miichael’s Review

    I see this as a reminder that property development must follow real demand, not simply market excitement.

    When developers become more cautious, buyers should look beyond promotional campaigns and ask some practical questions:

    1. How many comparable properties are already available?
    2. Are existing developments attracting genuine buyers?
    3. Are asking prices supported by recent transactions?
    4. Can the intended buyers realistically obtain financing?
    5. Is the development designed for actual occupants or mainly for investors hoping to resell?

    The survey also suggests that different property categories are performing differently. Buyers should therefore avoid treating the entire Malaysian market as one uniform market.

    My view: A more selective market can reward careful research. Buyers need to distinguish between a property that is attractively marketed and one that is genuinely well positioned.


    STORY 2 — Malaysia Reports 1,726 Revived Housing Projects: What Does This Mean for Buyers?

    What Happened?

    On 14 October, EdgeProp Malaysia reported on the Housing and Local Government Ministry’s update that 1,726 sick or abandoned private housing projects had been revived since 2023.

    The projects involved approximately:

    • 199,643 housing units
    • RM158 billion in gross development value
    • 1,542 sick projects completed with Certificates of Completion and Compliance
    • 147 projects restored to smooth status
    • 37 abandoned projects resolved through physical completion or arrangements benefiting buyers

    The ministry also reported that, as at 31 August 2026, Kuala Lumpur still had seven projects classified as abandoned and another 12 classified as sick.

    The government has set a target of eliminating sick and abandoned housing projects by 2030. EdgeProp

    Source: EdgeProp Malaysia — Housing project rehabilitation update, 14 October 2026

    Why It Matters

    A stalled housing project can create serious financial and emotional difficulties for buyers.

    They may have paid deposits and progressive payments, committed to housing loans and continued paying rent while waiting for their homes.

    The reported rehabilitation figures are encouraging, but one distinction matters: a project being revived does not necessarily mean every unit has been completed and handed over.

    The different outcomes must be examined individually.

    For prospective buyers, this is also a reminder to assess the delivery record of a developer and the actual status of a project before committing.

    Miichael’s Review

    I welcome efforts to protect homebuyers and resolve problematic developments.

    However, I would assess a project’s progress using evidence rather than announcements alone.

    Before buying into an ongoing development, I would want to understand:

    • The developer’s financial and delivery track record.
    • The project’s construction progress.
    • Whether the required approvals and legal arrangements are in place.
    • Whether there are known disputes or rehabilitation issues.
    • The expected completion date and the evidence supporting it.

    For buyers already affected by a stalled project, the available rehabilitation route and legal position are particularly important.

    My view: The real measure of success is not simply how many projects have been declared revived. It is how many affected buyers ultimately receive the homes or appropriate resolutions they were promised.


    STORY 3 — IOI Properties Advances Its Proposed RM7.66 Billion REIT Listing

    What Happened?

    IOI Properties Group Berhad advanced its proposed Malaysian real estate investment trust (REIT) listing after signing an underwriting agreement with six financial institutions.

    According to EdgeProp Malaysia on 12 October:

    • The proposed REIT has nine initial assets.
    • The portfolio was valued at approximately RM7.66 billion as at 31 May 2026.
    • The proposed offering could involve up to 2.2 billion units.
    • The underwriting agreement covers 165 million offer units, subject to the offering’s allocation provisions.
    • The prospectus was targeted for the fourth quarter of 2026, with listing targeted by year-end.

    The initial portfolio includes IOI City Mall, six hotels and two office properties.

    These are proposed listing arrangements; the announcement did not mean the IPO had already been completed. EdgeProp

    Source: EdgeProp Malaysia — IOI Properties advances proposed REIT IPO, 12 October 2026

    Why It Matters

    A REIT provides a way for investors to gain exposure to income-generating property through a listed investment vehicle rather than purchasing an entire property themselves.

    For the property sector, a listing can provide another route for capital management and potentially broaden investor participation.

    However, a large property portfolio does not automatically make a REIT an attractive investment.

    Investors still need to examine rental income, occupancy, financing costs, debt levels, asset valuations and the proposed distribution policy.

    Miichael’s Review

    This is worth watching because it connects property ownership with capital markets.

    For individual investors, a REIT may offer a different way to participate in commercial property, hotels and retail assets without directly managing a building.

    But the decision should be based on the investment’s fundamentals.

    I would look carefully at:

    1. The quality and location of the underlying assets.
    2. The sustainability of rental income.
    3. Financing costs and gearing.
    4. The proposed distribution yield and how it is calculated.
    5. Whether the offering valuation is reasonable relative to comparable investments.

    My view: The important question is not merely how much the portfolio is worth. It is whether its assets can generate sustainable income at a valuation that makes sense for investors.


    🌏 INTERNATIONAL PROPERTY WATCH

    🇦🇪 STORY 4 — Dubai Buyers Shift Towards Completed Homes as the Market Becomes More Selective

    What Happened?

    A third-quarter 2026 residential market report from betterhomes, reported by Khaleej Times on 15 October, showed a shift towards completed homes in Dubai.

    Key findings included:

    • Sales of ready residential properties rose 16% quarter-on-quarter.
    • Secondary-market transactions reached 10,055, with a total value of Dh27.1 billion.
    • Secondary-market transactions accounted for 29% of total residential sales, up from 24% in the second quarter.
    • Overall residential sales totalled 34,615 transactions during the quarter, broadly unchanged from the previous quarter.
    • Median apartment prices declined 2.4% between June and September, while villa and townhouse prices fell 2.3%.

    Despite the quarterly price declines, prices remained higher than a year earlier. Rental enquiries also rose sharply, although median rents eased in several market segments. Khaleej Times

    Source: Khaleej Times — Dubai ready-home sales jump 16%, 15 October 2026

    Why It Matters

    The figures suggest that buyers are becoming more selective about the type of property they purchase.

    Completed homes offer advantages that off-plan properties cannot immediately provide: buyers can inspect the actual unit, assess the surrounding community and potentially receive rental income sooner.

    However, the reported shift does not mean off-plan properties have become universally unattractive. Different buyers have different financial circumstances, objectives and risk tolerances.

    The decline in quarterly prices also highlights the importance of comparing actual transactions rather than relying exclusively on advertised prices.

    Miichael’s Review

    This is an interesting development for property investors.

    A completed property may provide greater visibility into its condition, rental demand and surrounding environment. An off-plan property may offer different advantages, but it also requires buyers to assess delivery risk and future market conditions.

    I would compare both options using the same criteria:

    • Total acquisition cost.
    • Expected rental income.
    • Maintenance and other holding expenses.
    • Financing commitments.
    • Comparable transaction prices.
    • Exit options if market conditions change.

    My view: A completed property is not automatically a better investment, just as an off-plan property is not automatically a better bargain. The right choice depends on the numbers, the risks and the buyer’s objectives.


    🇨🇦 STORY 5 — Canadian Home Sales Fall Again as Mortgage Rates Weigh on Buyers

    What Happened?

    On 16 October, Reuters reported that Canadian home sales declined again in September as higher mortgage rates and expectations of a possible interest-rate increase weighed on market activity.

    According to the Canadian Real Estate Association (CREA):

    • National home sales fell 2.3% month-on-month in September, following a 0.7% decline in August.
    • Sales were down 7.7% year-on-year on an unadjusted basis.
    • The Home Price Index declined 0.4% month-on-month and 3.4% year-on-year.
    • New property listings fell 1.8% from August.
    • The seasonally adjusted sales-to-new-listings ratio slipped to 48.8%, below its long-term average of 54.7%.

    At the time of the report, financial markets were pricing in the possibility of a 25-basis-point Bank of Canada rate increase in December. This was a market expectation, not a confirmed policy decision. Reuters

    Source: Reuters — Canadian home sales fall in September as mortgage rates increase, 16 October 2026

    Why It Matters

    The Canadian market demonstrates how financing conditions can affect property transactions.

    Even when prospective buyers want to purchase homes, higher mortgage costs can reduce borrowing capacity or make buyers more cautious about committing.

    A slower market may give some buyers more time to negotiate. However, it does not automatically mean that every property is attractively priced.

    Local conditions also matter: national figures can conceal significant differences between cities, neighbourhoods and property types.

    Miichael’s Review

    For me, the main lesson is the relationship between financing and affordability.

    When interest rates rise, a buyer may qualify for a smaller loan or face a higher monthly repayment. That can change which properties are financially sensible.

    Before committing, I would ask:

    1. Can I afford the repayments if borrowing costs increase?
    2. Does the property remain affordable after taxes, insurance and maintenance?
    3. Is the asking price supported by recent comparable transactions?
    4. Can I sustain ownership if resale takes longer than expected?
    5. Am I buying because the property suits my needs, or because I expect prices to rise?

    My view: A property purchase should be financially sustainable even when market conditions become less favourable. Buyers who understand their financing limits are better placed to make measured decisions.


    WORTH WATCHING

    Here are five developments I would monitor over the coming weeks.

    AreaWhat to watchWhy it matters
    MalaysiaDeveloper launch plans and sales performanceShows whether supply is responding to genuine demand.
    MalaysiaRehabilitation of sick and abandoned housing projectsBuyers need evidence of actual progress and resolution.
    MalaysiaIOI Properties’ proposed REIT prospectusProvides details for evaluating the portfolio, pricing and distribution policy.
    UAECompleted-home prices, rents and transaction activityHelps investors assess whether market conditions support their objectives.
    CanadaMortgage rates, sales activity and home-price trendsProvides an indication of how financing conditions affect affordability and demand.

    MY TAKEAWAY THIS WEEK

    This week’s property news reinforces a principle that applies across markets:

    Property decisions should be based on fundamentals, not headlines.

    In Malaysia, developers are becoming more cautious, housing-project rehabilitation remains important, and a proposed REIT listing offers another way to participate in property investment.

    In Dubai, buyers are showing greater interest in completed homes, while prices and rents are becoming more competitive in some segments.

    In Canada, higher borrowing costs are weighing on transactions.

    These markets have different conditions, but the underlying questions are similar.

    • Is the property priced reasonably?
    • Is there genuine demand?
    • Can the buyer afford to own it comfortably?
    • Does the investment generate sustainable income?
    • Are the risks manageable if the market changes?

    A property can look attractive on paper but still be unsuitable for a particular buyer.

    Look beyond the price. Understand the fundamentals before making the decision.

    Miichael Yeoh
    PROPERTY STRATEGIST
    miichaelyeoh.com

  • Malaysia Budget 2027: What Property Buyers, Investors and Developers Need to Know

    Malaysia Budget 2027: What Property Buyers, Investors and Developers Need to Know

    By Miichael Yeoh | Property Discovery System(PDS)

    Malaysia’s Budget 2027 has introduced several measures that could influence the country’s property market, from first-home ownership and housing financing to the rehabilitation of abandoned housing projects.

    But what do these announcements actually mean for Malaysians considering a property purchase?

    A stamp duty exemption may reduce the upfront cost of buying a home. A housing loan guarantee may help certain buyers access financing. Public housing and infrastructure investments may create opportunities in selected locations.

    Yet none of these measures automatically makes a property affordable, a development attractive or an investment profitable.

    For homebuyers, investors and developers, the more important question is how these policies affect real property decisions.

    Here is my assessment of the key property-related measures in Malaysia Budget 2027 and what they could mean for the market, including Penang.

    1. First-home buyers: Stamp duty relief expands up to RM750,000

    One of the most significant property announcements in Budget 2027 is the proposed expansion of stamp duty exemptions for first-home purchases.

    According to the Budget speech delivered by Prime Minister and Finance Minister Datuk Seri Anwar Ibrahim on 9 October 2026, the proposed relief will apply to sale and purchase agreements executed from 1 January 2027 to 31 December 2030.

    The proposed structure is:

    • First homes priced up to RM500,000: Full stamp duty exemption on the instrument of transfer and housing loan agreement.
    • First homes priced above RM500,000 and up to RM750,000: Full exemption on the first RM500,000, with a 50% exemption on the remaining amount.

    The proposal is intended to reduce the upfront costs of purchasing a first home.

    Source: Prime Minister’s Office — Budget 2027 speech

    What does this mean for homebuyers?

    For eligible buyers, lower stamp duty can reduce the cash required at the point of purchase.

    The expanded price range is also relevant to buyers who have been looking at homes above RM500,000 but below RM750,000. However, the actual savings will depend on the final implementation rules, the transaction value and the applicable loan terms.

    Buyers should also distinguish between a reduction in transaction costs and an improvement in long-term affordability.

    A home that qualifies for stamp duty relief may still be financially unsuitable if the monthly instalment, maintenance charges, insurance and other commitments stretch the household budget.

    My view: Treat stamp duty relief as a financial advantage, not the main reason to buy a property.

    2. RM20 billion in housing financing guarantees for first-time buyers

    Budget 2027 also provides for up to RM20 billion in housing financing guarantees through the Housing Credit Guarantee Scheme, known as SJKP.

    The scheme is expected to assist approximately 80,000 first-time homebuyers, with particular attention to self-employed individuals and people without fixed monthly incomes.

    This is important because not every prospective buyer has a conventional salary structure.

    Business owners, freelancers and other self-employed individuals may have sufficient earning capacity but face difficulties meeting standard income-documentation requirements.

    SJKP is intended to improve access to housing financing for eligible applicants.

    Source: BERNAMA — Budget 2027 housing financing guarantees

    Does a housing guarantee mean everyone can obtain a loan?

    No. A guarantee does not automatically mean loan approval.

    Applicants must still meet the scheme’s eligibility conditions and the relevant lender’s assessment requirements. Buyers should confirm the applicable financing limits, documentation requirements and repayment obligations before committing to a purchase.

    The key consideration is not simply whether financing is available, but whether the buyer can comfortably sustain the repayments.

    My view: Better financing access is useful when it connects eligible buyers with homes they can genuinely afford. It becomes risky if buyers interpret easier access to financing as a reason to borrow beyond their means.

    3. Can Budget 2027 help revive abandoned housing projects?

    Another significant proposal is the full stamp duty exemption for qualifying transactions involving the rehabilitation of abandoned housing projects.

    The proposed relief covers loan agreements and instruments of transfer executed by contractors or developers rescuing abandoned projects, as well as by the original purchasers involved in those projects.

    The proposed effective period is 1 January 2027 to 31 December 2030.

    The measure forms part of the government’s stated ambition to achieve zero abandoned housing projects by 2030.

    Source: Prime Minister’s Office — Budget 2027 speech

    Will this solve the abandoned housing problem?

    Stamp duty relief can reduce transaction costs, but reviving an abandoned project is more complicated than reducing taxes.

    A successful rescue may depend on:

    • Whether the project is financially viable.
    • Whether a capable rescue developer can be appointed.
    • Whether land, financing and legal issues can be resolved.
    • Whether construction can be completed within a realistic timeframe.
    • Whether original purchasers can ultimately receive their homes.

    For affected buyers, the priority remains understanding the legal and financial status of the project and the conditions under which completion can proceed.

    My view: The incentive is a useful part of the solution, but actual project rehabilitation and delivery will be the real test.

    4. Nearly RM1 billion for housing programmes

    Budget 2027 provides nearly RM1 billion for programmes including Rumah Mesra Rakyat and Program Residensi Rakyat.

    Four new housing projects are identified in Kulai, Johor; Nilai, Negeri Sembilan; Paya Rumput, Melaka; and Pertang Valley, Terengganu.

    The Budget also identifies Bandar MADANI Bukit Jalil as a residential development with supporting amenities, including a vertical school.

    These initiatives reflect the continuing role of government-supported housing in addressing housing needs.

    Source: Prime Minister’s Office — Budget 2027 speech

    For buyers, however, the announcement of a housing programme is only the beginning.

    Eligibility, location, unit pricing, delivery schedules and access to public amenities all affect whether a particular development meets a household’s needs.

    Affordable housing should not be assessed by price alone. Accessibility to employment, transport, schools and essential services also matters.

    5. What could Budget 2027 mean for Penang property?

    Penang’s property market has its own economic drivers. Its manufacturing base, semiconductor ecosystem, employment opportunities, infrastructure and limited availability of certain types of land all influence property demand.

    Budget 2027 includes a RM100 million Strategic Investment Fund involving Khazanah and InvestPenang to support early-stage semiconductor and advanced manufacturing companies.

    The Budget also identifies transport-related infrastructure investment involving roads in port areas and airports, including Penang International Airport.

    These announcements could have indirect implications for property demand if they translate into business expansion, job creation and improved connectivity.

    Source: Prime Minister’s Office — Budget 2027 speech

    Which property segments could benefit?

    Industrial and logistics property

    Business expansion may create demand for suitable industrial facilities, warehouses and supporting commercial space. Actual demand will depend on investment commitments, company requirements and available supply.

    Residential property near employment centres

    If industrial investment generates additional jobs, it could support demand for housing in accessible locations. The effect will vary according to workers’ incomes, commuting patterns, rental budgets and the supply of competing homes.

    Commercial property

    Business growth may create opportunities for offices, retail services and other supporting uses. These opportunities should be assessed against occupancy, tenant demand and operating costs.

    Does this mean Penang property prices will rise?

    Not necessarily.

    Infrastructure and investment announcements are not guarantees of capital appreciation. The impact on individual developments depends on their location, purchase price, accessibility, competing supply, rental demand and the actual delivery of the announced projects.

    For buyers, the right question is not simply whether an area will benefit from economic growth. It is whether a particular property is priced reasonably relative to its likely demand and long-term usefulness.

    6. What should property investors watch?

    Budget 2027 creates several areas worth monitoring, but investors should distinguish between a policy announcement and a measurable investment opportunity.

    Follow employment and business expansion

    Industrial investment may support housing and commercial demand, but the most useful evidence will be actual investment commitments, completed facilities, employment growth and tenant activity.

    Assess rental demand rather than relying on capital appreciation

    A property near an expanding employment centre may attract tenants, but rental demand does not guarantee a satisfactory yield.

    Investors should calculate realistic rental income after vacancies, maintenance, management fees, financing costs and other expenses.

    Check competing supply

    Even a location with strong economic activity can experience weak rental performance if too many similar units compete for tenants.

    Evaluate the purchase price

    Government incentives can influence demand, but buyers still need to assess whether the asking price is supported by comparable transactions, rental evidence and the property’s fundamentals.

    My view: Investors should follow the economic effects of the Budget, not simply the headlines. A good investment still requires a sound entry price and a clear understanding of risk.

    7. What does Budget 2027 mean for property developers?

    The Budget’s housing measures may help reduce some barriers to homeownership. However, developers continue to face the practical challenges of land, construction, financing, regulatory compliance and buyer affordability.

    The Real Estate and Housing Developers’ Association Malaysia (REHDA) welcomed the proposed homeownership measures and housing financing guarantees. It also called for a review of development-related charges and highlighted construction costs and the need to address completed but unsold residential properties.

    Source: EdgeProp — REHDA’s response to Budget 2027

    For developers, three questions deserve attention.

    First, does the product match the buyer’s budget?

    A property may have attractive facilities and branding, but the target buyer must still be able to afford the purchase and ongoing ownership costs.

    Second, does the project offer a clear reason to buy?

    Location, accessibility, layout, price, surrounding amenities and realistic future demand matter more than marketing claims alone.

    Third, is the sales process helping buyers make confident decisions?

    Buyers need clear information about costs, financing, project delivery, ownership obligations and relevant risks.

    The Budget may improve some aspects of the purchasing environment, but it cannot replace sound product positioning, credible communication and responsible sales practices.

    8. Five questions every homebuyer should ask before purchasing

    Regardless of government incentives, I encourage buyers to work through five questions before making a commitment.

    1. Can I afford this property comfortably? Calculate the deposit, transaction costs, monthly instalment, maintenance and a realistic contingency reserve.
    2. Does the location fit my needs? Consider employment, transport, schools, amenities and daily travel requirements.
    3. Is the price supported by evidence? Compare similar properties, recent transactions and realistic rental values where relevant.
    4. What risks am I taking? Understand the developer’s track record, construction status, legal terms, competing supply and likely holding costs.
    5. Does this property fit my long-term plan? A home for own occupation and an investment property may require different priorities.

    These questions are especially important when an incentive makes a purchase appear more attractive. A lower upfront cost does not necessarily make a property the right choice.

    9. My takeaway: Policy support is useful, but property decisions still matter

    Malaysia Budget 2027 proposes meaningful support for first-home buyers through expanded stamp duty relief, housing financing guarantees and measures intended to facilitate the rehabilitation of abandoned projects.

    It also identifies housing programmes and investment initiatives that could influence economic activity in selected locations, including Penang.

    The eventual impact will depend on implementation, financing access, actual investment and the underlying supply and demand for property.

    For homebuyers, the opportunity is to understand the assistance available without losing sight of affordability.

    For investors, it is to identify genuine demand rather than assume every policy announcement will increase property values.

    For developers, it is to understand what buyers need and communicate the value of a project clearly and responsibly.

    At the Property Discovery System™ (PDS), our approach is straightforward: understand the market, evaluate the options, identify the risks and make decisions based on evidence.

    Because buying property should never be about following a headline alone.

    Discover Better. Decide Smarter.

    This article is for general property education and information. Budget 2027 measures described as proposed remain subject to the relevant legislation, implementation guidelines and eligibility requirements. Readers should confirm their individual circumstances with the relevant authorities and professional advisers before making financial or property decisions.

  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    26 September – 2 October 2026

    Malaysia + International Property Insights

    This week’s market is interesting for one reason: the headlines are not telling one single story.

    Malaysia has pockets of resilience in retail and construction, but residential developers are still dealing with affordability and unsold stock. Overseas, Australia is going through a much sharper housing correction, while Singapore continues to reposition mature assets through redevelopment.

    For buyers and investors, the lesson is simple: look beneath the headline number.


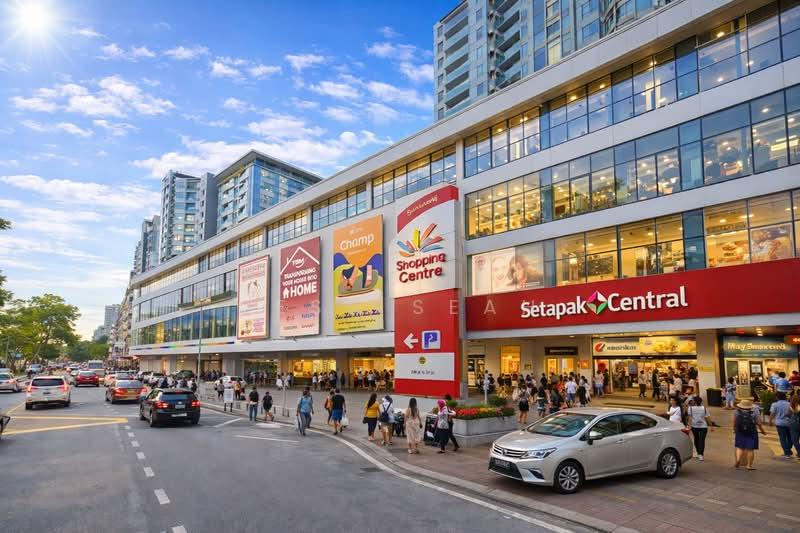
    🇲🇾 1. KIP REIT Completes RM435 Million Setapak Central Mall Acquisition

    What Happened

    KIP REIT completed its RM435 million acquisition of Setapak Central Mall on 30 September.

    The three-storey mall has approximately 514,777 sq ft of net lettable area and 1,090 parking bays. Occupancy had previously been reported at 99.89%.

    The acquisition brings KIP REIT’s portfolio to 20 properties, with the enlarged portfolio previously assessed at around RM2.1 billion. EdgeProp

    Why It Matters

    This isn’t simply about buying another shopping mall.

    A mature, highly occupied retail asset can provide something very different from a new development:

    existing tenants + existing footfall + existing income.

    For investors, that distinction matters.

    The question isn’t simply whether a property is “good”.

    It is:

    How predictable is the income after I buy it?

    Miichael’s Review

    I like looking at transactions like this because they demonstrate another side of property investment.

    A developer creates value through development.

    A REIT investor is often looking for income-producing assets with established operations.

    For individual investors, the same principle applies.

    Before getting excited about a property because of future appreciation, ask:

    What is producing the income today?

    Source: EdgeProp — KIP REIT completes RM435m Setapak Central acquisition


    🇲🇾 2. Gamuda Posts Record Profit — But Property Earnings Fall

    What Happened

    Gamuda reported record FY2026 net profit of RM1.05 billion, up 5%.

    But there is an interesting contrast underneath the headline.

    While the group’s overall performance was supported by stronger construction earnings, property sales fell 22% to RM3.2 billion, while property division net profit declined 18% to RM310.76 million. EdgeProp

    Why It Matters

    This is a useful reminder that a diversified property-related group can perform well overall even when its property division is under pressure.

    It also reinforces an important market principle:

    Construction demand and residential property demand are not necessarily moving together.

    Miichael’s Review

    For me, the interesting part isn’t simply that Gamuda made a record profit.

    It is the divergence between construction and property.

    When analysing a developer, I would not stop at the group’s headline earnings.

    I’d want to know:

    • How much comes from property?
    • What is the sales pipeline?
    • How much unsold inventory exists?
    • Where are the projects located?
    • What is the margin?
    • And how quickly can sales be converted into cash?

    A strong company does not automatically mean every property project is equally attractive.

    Source: EdgeProp — Gamuda posts record FY2026 profit


    🇲🇾 3. Government Calls for More “White Knights” to Rescue Abandoned Projects

    What Happened

    Malaysia’s Housing and Local Government Ministry has called on established developers to step in as “white knights” to revive stalled and abandoned housing developments.

    According to the report, the ministry’s task force has helped revive 1,647 distressed projects worth RM153 billion, affecting almost 200,000 homebuyers.

    The government is also pursuing legal reforms involving developer accountability, strata management and residential tenancy. The Star

    Why It Matters

    For a buyer, buying property isn’t simply about:

    location + price + size.

    There is another question that often gets overlooked:

    Who is behind the project — and what happens if things go wrong?

    A delayed or abandoned project can create years of financial and emotional stress for buyers.

    Miichael’s Review

    This is one area where I think buyer education is particularly important.

    Before buying a new development, buyers should investigate the developer’s track record, project delivery history, financial structure, development partners and surrounding ecosystem.

    We often spend hours comparing unit sizes and discounts.

    But sometimes the most important due diligence happens before we even choose the unit.

    Source: The Star — Malaysia needs more white knights


    🌏 4. Australia: Housing Prices Fall for a Sixth Straight Month

    What Happened

    Australia’s housing market continued to weaken in September.

    Cotality’s national Home Value Index fell 1.1% in September, the sixth consecutive monthly decline.

    Values are now 5.2% below the March 2026 peak.

    Sydney fell 1.4% in September and is nearly 9% below its February peak, while Melbourne fell 0.7%.

    Transaction activity has also weakened, with sales over the latest three-month period down around 19% year-on-year, according to Reuters. Reuters

    The Reserve Bank of Australia has also raised its cash rate to 4.6%, a 15-year high, adding further pressure to borrowing capacity. Investing.com
    Why It Matters

    Australia provides an excellent real-world example of the relationship between:

    interest rates → borrowing capacity → buyer demand → transactions → prices.

    And importantly, the impact is not identical across every city.

    Miichael’s Review

    For Malaysian buyers and investors looking overseas, this is a market worth watching carefully.

    A falling market doesn’t automatically mean:

    “Everything is cheap.”

    It means the risk-reward equation is changing.

    For anyone considering an overseas property purchase, I’d be asking:

    Has the price fallen because the market is correcting — or because the fundamentals have deteriorated?

    Those are two very different things.

    Source: Reuters — Australian home prices fall for sixth straight month; Cotality — September Home Value Index


    🌏 5. Singapore: Valley Point to Become a New Mixed-Use Development

    What Happened

    Frasers Property and Mitsubishi Estate announced plans to redevelop Valley Point and Frasers Suites Singapore along River Valley Road.

    The planned mixed-use development will include:

    • 407 luxury residential units and sky villas
    • 184 serviced-residence units
    • dining
    • retail
    • lifestyle components

    The project is planned for launch in 2027, with completion targeted for 2031. The existing properties are expected to cease operations in March 2027. The Business Times

    Why It Matters

    This is a classic example of urban land optimisation.

    Instead of simply maintaining an ageing asset, the owners are looking at the highest and best use of a prime site.

    The redevelopment also combines residential, serviced residences, retail and lifestyle components rather than relying on one single use.

    Miichael’s Review

    This is something developers everywhere can learn from.

    A property isn’t necessarily valuable because of what it is today.

    Sometimes its greatest value comes from what it could become.

    But that requires looking beyond the building itself:

    land value + location + planning potential + demand + surrounding ecosystem.

    For buyers, this also highlights why understanding a property’s future development context can be just as important as studying the existing building.

    Source: The Business Times — Frasers Property and Mitsubishi Estate redevelopment; Frasers Property — official announcement


    👀 WORTH WATCHING

    Malaysia

    1. Residential affordability

    The combination of unsold stock, financing constraints and developer margins remains an important issue.

    2. Retail investment

    The KIP REIT acquisition shows that mature, income-producing retail assets remain relevant when occupancy and cash flow are strong.

    3. Distressed projects

    The government’s push for more private-sector participation could change the landscape for abandoned and stalled developments.

    🌏 International

    4. Australia

    Watch whether the correction continues into 2027 and whether lower transaction volumes eventually create broader economic effects.

    5. Singapore

    Watch how redevelopment and land optimisation reshape mature neighbourhoods.


    💡 MY TAKEAWAY

    This week’s five stories are actually connected by one common theme:

    Property value is about more than price.

    A shopping mall’s value can come from income and occupancy.

    A developer’s value can come from the quality of its pipeline and balance sheet.

    A residential project’s value includes delivery risk.

    A housing market’s direction is influenced by financing and affordability.

    And an older property can sometimes create greater value through redevelopment.

    So when someone asks me:

    “Is this property a good buy?”

    I don’t think the first question should be:

    “How much is it?”

    I’d rather start with:

    Who is buying it?

    Why are they buying it?

    What creates the demand?

    What could go wrong?

    And what happens if the market doesn’t behave as expected?

    That is where proper property due diligence begins.

    From the desk of

    Miichael Yeoh

    Property Strategist

  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    Week in Review | 19–25 September 2026

    Malaysia • Regional Property • Global Insights

    The property market is not one market. Different assets, locations and economic forces are moving in very different directions.


    🇲🇾 1. Almost 60% of Developers Report Unsold Completed Homes

    https://images.openai.com/static-rsc-4/uJ1sXQYW8YNgLMcTGhfcD4h9AlGny1gVvYl0-3Z_UUWwYtxe0L-njDRK6hbq_nQHxshYIf8luumPsz7hwaFkeeFnY-h9INrh1M3Wsc166NXJCu6itg6Pu3naU9MIZA6kT81KGWzDrYNL-2laiMsgo-gFVvv0qAxul-Ei9rdVdXRqEG6ZpH0OrMh_BYhREWGV?purpose=fullsize

    What Happened

    A new REHDA Property Industry Survey found that 59% of 181 developers surveyed had unsold completed residential units as at 30 June 2026.

    The three main reasons cited were rejected end-financing applications, property prices and unreleased Bumiputera units.

    During the survey period, 54 respondents launched 15,834 units and sold 5,260 units, giving a take-up rate of 33.2%, only slightly higher than 32.2% previously.

    REHDA also highlighted rising construction costs, financing constraints and regulatory/compliance costs as pressures on housing affordability. An average 13% increase in construction costs was reported between March and June.

    Why It Matters

    This is an important distinction:

    A home can be “affordable” on paper but still unaffordable to the buyer.

    If financing is rejected, margins are lower or credit requirements become more difficult, the advertised selling price isn’t the whole affordability equation.

    For developers, unsold completed stock also ties up capital.

    Miichael’s Review

    This is exactly why I believe buyers should look beyond the headline price.

    Before deciding whether a property is affordable, ask:

    Can I actually obtain the financing?
    What is my monthly commitment?
    What happens if interest rates or my income situation changes?

    For developers, the lesson is equally important:

    Product pricing must match real purchasing power — not just construction cost plus desired margin.

    Source: EdgeProp — REHDA survey on unsold homes and EdgeProp — REHDA on housing costs


    🇲🇾 2. Johor: Paragon Globe Plans RM1.69 Billion Industrial Park

    What Happened

    Paragon Globe is pursuing additional land in Sedenak, Johor, for a proposed industrial park with an estimated gross development value of RM1.69 billion.

    The project sits within the Kulai-Sedenak zone of the Johor-Singapore Special Economic Zone (JS-SEZ) and is planned to include industrial factories, commercial components and worker accommodation.

    The group is also taking a more strategic approach to land development, looking at anchor occupiers and the ecosystems that can form around them, rather than simply developing land in isolation.

    Why It Matters

    This is bigger than another industrial-property announcement.

    The interesting part is the “anchor occupier” strategy.

    A major manufacturer can create demand for:

    • suppliers
    • logistics
    • warehouses
    • worker accommodation
    • retail
    • supporting services

    That can turn an industrial site into an economic ecosystem.

    Miichael’s Review

    This is the kind of development strategy I find interesting.

    The best land doesn’t necessarily have the highest GDV.

    Sometimes the real question is:

    “What economic activity will this land create around itself?”

    That is a much more powerful way to assess long-term land value.

    Source: The Star — Paragon Globe eyes RM1.69bil industrial park; EdgeProp — Paragon Globe landbank strategy


    🇲🇾 3. Klang: Maybulk Moves Into Industrial Property

    What Happened

    Maybulk has proposed acquiring an 8,346 sq m freehold industrial property in Bandar Bukit Raja, Klang, for RM35.5 million.

    The property includes an industrial building, warehouse and office facilities.

    Importantly, Maybulk said the move is part of a strategy to diversify its revenue streams and reduce reliance on its existing shipping and storage businesses.

    The acquisition would also immediately provide rental income once completed.

    Why It Matters

    This is a smaller transaction than the headline billion-ringgit deals — but strategically, it is very interesting.

    We’re seeing a company from outside traditional property development use industrial real estate as an income-producing asset.

    That reflects the growing attractiveness of industrial property as an investment class.

    Miichael’s Review

    I always find these transactions worth watching because they show how corporate investors think about property differently from individual buyers.

    For a corporate investor, property can be:

    An operating asset + rental income + capital preservation + diversification.

    That is very different from buying a property simply because “the area is going up.”

    Source: The Star — Maybulk proposes RM35.5mil Klang industrial acquisition


    🌏 4. Australia: The Housing Slowdown Is Hitting More Than Property Agents

    https://images.openai.com/static-rsc-4/Brs6pRtz5kYYyfE4NHjlwNYzDeZsQhdHN8Ay_xpJgbljRtmXqHfXrQ0ZJ7iHrrLLQKWOe0izOsryIQPmdtGfKgsZshly6_Y3bJOYhnrsCRXXrUXpoyniGMpBU6UiTg5U1rpeUgc7Zw_F7zL8TwPXur-FNtdpsHx7XF08Uo8dO-6FZFqw6SGoo2PIJCj64MzF?purpose=fullsize

    What Happened

    Australia’s housing slowdown is now affecting a much wider economic ecosystem.

    Reuters reported that Australian home sales volumes have fallen sharply, with turnover 15% below a year earlier in July/August and 10.5% below the five-year average.

    Reuters estimates that the reduction in housing activity could remove around A$2.8 billion to A$5.6 billion of annual spending from businesses connected to property transactions — including removalists, conveyancers, furniture retailers, tradespeople and renovation businesses.

    The important point is that prices themselves have not collapsed: Reuters reported prices were less than 4% below the March peak and still above year-ago levels. The bigger issue is fewer transactions.

    Why It Matters

    This is a fascinating distinction:

    Property prices can remain relatively resilient while the property economy slows dramatically.

    If fewer people buy and sell, many businesses around the property ecosystem suffer.

    Miichael’s Review

    This is a useful lesson for Malaysia too.

    When we analyse a property market, we shouldn’t look only at:

    “Are prices rising?”

    We should also watch:

    transaction volume, financing, turnover, inventory and buyer confidence.

    A market can look healthy from a price chart while becoming much less active underneath.

    Source: Reuters — Australia’s housing slowdown and wider economic impact


    🌏 5. UK Housing: Prices Bounce, But Buyers Remain Selective

    https://images.openai.com/static-rsc-4/AEe5M10FcR-kJRCayCQU6MvkhNhkoA3_xw2GGp_f6LLLxiydkqrUYPQL63QZdaCxQoINy6jL0mpDitHMoiolKW5iBFZCF_fbHycfkm-eMLNzJIn4oybRTkZ_P3qO1zOmbgx6hiVX8Ce5o71Tg2Q2XS9ZjNv5XPC_Gl731cYvpOuShOgWgt_lYJuEbdKNQVeu?purpose=fullsize

    What Happened

    UK asking prices rose 0.7% in September, equivalent to about £2,441, according to Rightmove data reported by The Times.

    The average asking price reached approximately £367,440.

    But the headline increase needs context: prices remained 0.8% below a year earlier, while housing supply was reported to be at a 12-year high.

    Why It Matters

    More supply gives buyers more choice — and therefore more negotiating power.

    A seller cannot simply assume that a higher asking price will translate into a higher achieved price.

    Miichael’s Review

    This is one of my favourite property lessons:

    The asking price is not necessarily the market value.

    When supply rises and buyers become more selective, pricing strategy becomes increasingly important.

    For investors, this also reinforces the need to distinguish between:

    headline price movement and actual market liquidity.

    Source: The Times — UK house prices rise for first time since May


    📊 PROPERTY NUMBER OF THE WEEK

    59%

    The percentage of surveyed Malaysian developers reporting unsold completed residential units.

    But the more interesting number may be:

    33.2%

    The reported take-up rate during the REHDA survey period.

    The lesson: demand exists — but buyers are becoming increasingly constrained by financing, affordability and product suitability.


    👀 WORTH WATCHING

    🇲🇾 Malaysia

    1. Housing affordability
    Will financing accessibility improve enough to reduce completed unsold stock?

    2. Johor industrial property
    Watch how the JS-SEZ develops around actual occupiers and employment rather than simply land speculation.

    3. Klang industrial assets
    Will more corporates diversify into income-producing industrial property?

    🌏 International

    4. Australia
    Whether weak transaction volumes persist even if prices remain relatively resilient.

    5. UK
    Whether increased housing supply eventually translates into more realistic pricing.


    💡 MIICHAEL’S TAKEAWAY

    This week gives us five very different property stories.

    Housing affordability.
    Industrial land strategy.
    Corporate property investment.
    Australia’s transaction slowdown.
    UK supply and pricing.

    And that’s exactly why I don’t believe we should talk about “the property market” as though it is one single thing.

    Different sectors behave differently.

    Different locations behave differently.

    And most importantly, different buyers have different problems.

    For someone buying a home, financing and affordability may matter most.

    For an investor, rental income and liquidity may matter more.

    For a developer, land cost, product positioning and absorption may determine success.

    And for a corporate investor, property may simply be another asset class for diversification.

    So perhaps the better question isn’t:

    “Is property a good investment?”

    It is:

    “Which property, in which location, for what purpose — and under what market conditions?”

    That is where better property decisions begin.

    Miichael Yeoh

    Property Strategist

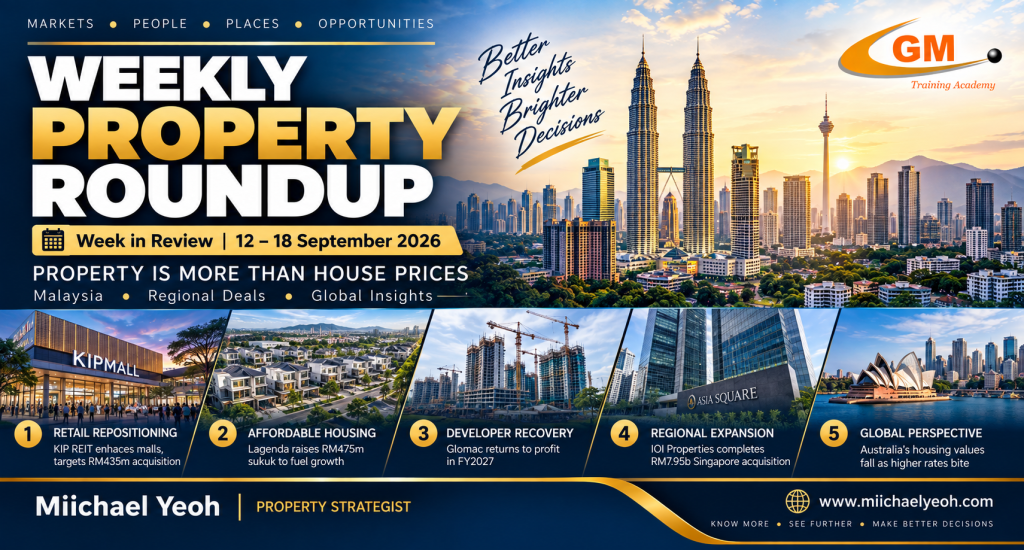
  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    Week in Review | 12–18 September 2026

    Malaysia • Regional Property • Global Insights

    The property market is bigger than house prices. Follow the money, the people and the assets.


    🇲🇾 1. KIP REIT: Retail Property Is Being Repositioned, Not Abandoned

    https://images.openai.com/static-rsc-4/FE3MJchSQotX9YuPbZPIptH2f3klwx57hOtiag2TrNWJqNoH_DJyzrHa7K8Vf0R5R59-cWO0p0wq2ag0mRP_tqj2NvEL8yA4sLbNgXWMvdynUaBGhfgMFI9IrOCiEMIe14OC3bExGI0mfAT00kd2GuHIlQ46ZNiGwPp00pgOSI0UV6qfJd8-Vrq6nlCryRjt?purpose=fullsize

    What Happened

    KIP REIT plans asset enhancement initiatives at three malls — KIPMall Masai, KIPMall Kota Warisan and AEON Mall Kinta City.

    The strategy is aimed at improving operational efficiency and supporting longer-term rental growth.

    There is another interesting move: KIP REIT is targeting completion of its RM435 million acquisition of Setapak Central Mall, which would be its largest acquisition to date and take assets under management to about RM2.2 billion.

    Why It Matters

    Retail property is often written off as “old economy”.

    But successful malls are increasingly becoming community infrastructure — food, services, groceries, healthcare, entertainment and daily necessities.

    The question isn’t simply:

    “Is shopping mall demand declining?”

    It should be:

    “Can the asset remain relevant to its surrounding population?”

    Miichael’s Review

    This is something I find particularly interesting.

    Property owners don’t always need to build something new to create value.

    Sometimes, repositioning an existing asset can be the smarter strategy.

    Source: EdgeProp, 18 September 2026.


    🇲🇾 2. RM475 Million Sukuk: Affordable Housing Needs Capital Too

    https://images.openai.com/static-rsc-4/qZnwyXfXtbssVeM0gJ0UyMNoQ_HOxzgGPPQ7VJoTwrJYrEoEtoVE5gdnAwYgBxswD2HlM1X_3PortDlviTMSly0x0BG3yPCgk_eCc2onB607e5S7XRRhYTpPkA6NO631rPH7rlBvpvcO_MY3VPoVQFihdmjB9NJu05BHNuIg-s-3xMn04WrPYYRufXekwqeN?purpose=fullsize

    What Happened

    Lagenda Properties has completed its first RM475 million sukuk issuance under a larger RM1.5 billion Sukuk Wakalah programme.

    The proceeds will be used for acquisitions, working capital and affordable housing developments.

    Why It Matters

    Affordable housing is sometimes discussed only from the buyer affordability perspective.

    But there is another side:

    How do developers finance affordable housing profitably and sustainably?

    If construction costs, land costs and financing costs continue rising, access to capital becomes critical.

    Miichael’s Review

    I like this story because it reminds us that property is not just about selling houses.

    There is an entire financial ecosystem behind every development:

    Land → Financing → Construction → Sales → Delivery → Exit

    Understanding that chain helps us understand why some developers can keep expanding while others struggle.

    Source: EdgeProp, 18 September 2026.


    🇲🇾 3. Glomac Returns to Profit — A Reminder to Watch Developer Health

    https://images.openai.com/static-rsc-4/hnQvi8sM8duuJGU7EE09eEA36eU0yr074Tx8dEJcKR2F7ILr4VKSjElTjjxtlcn3QJQdPXunhBy9_mroevHS0x5o-iUlk9xfvSJUPvTiezwh2azShtwakbqaJPSEYhlQSMnPyHSZwi8jbeYzgtp2Pd2xVk4516ALCQ8bw_BUs3zAVSohSS6Gl3imZ6u4dLlt?purpose=fullsize

    What Happened

    Glomac returned to the black in its first quarter of FY2027.

    Net profit attributable to owners reached RM7.6 million, compared with a RM1.42 million loss a year earlier.

    Revenue jumped 163% to RM68.53 million, with property-development revenue more than tripling to RM61.12 million.

    More encouragingly, borrowings fell from RM237.0 million at end-April to RM224.4 million at end-July, while cash and short-term placements stood at RM249.5 million.

    Why It Matters

    When considering a new development, buyers often focus on:

    • Location
    • Price
    • Facilities
    • Discounts

    But one question is frequently overlooked:

    Who is the developer and how financially healthy are they?

    Miichael’s Review

    A property doesn’t exist in isolation.

    The developer’s financial strength can influence construction progress, delivery, future phases and ultimately buyer confidence.

    For me, developer due diligence should be part of property due diligence.

    Source: EdgeProp, 18 September 2026.

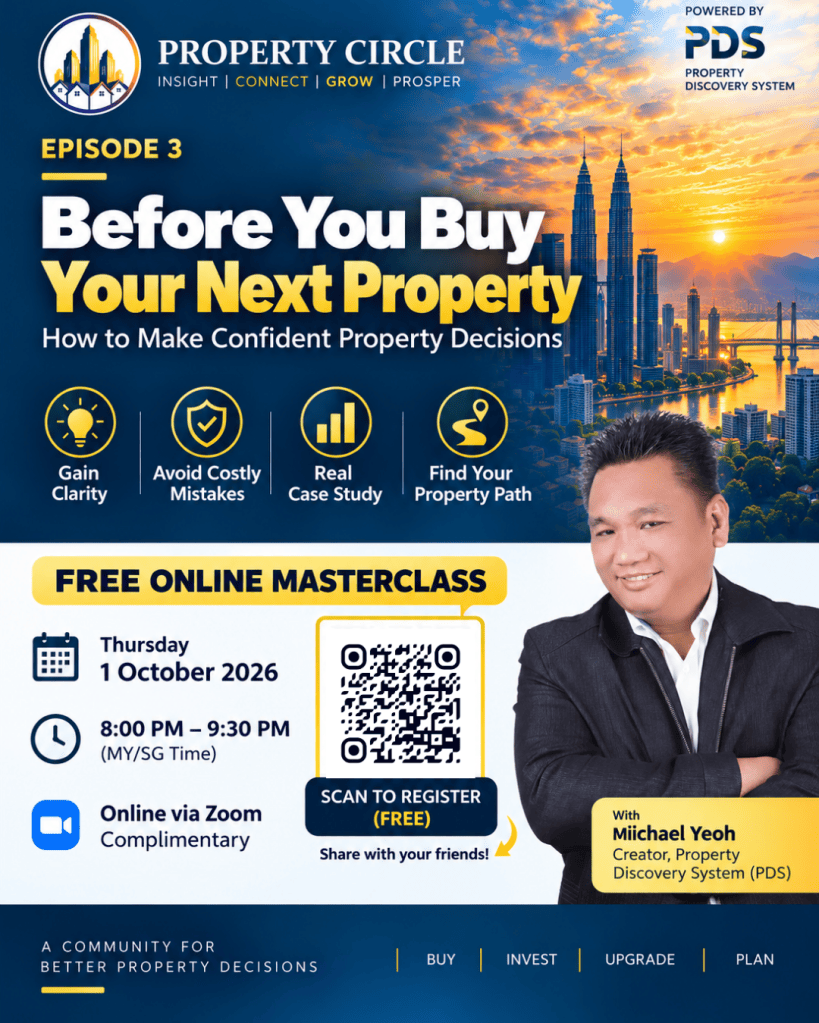
    Click to register for the event : Before You Buy The Next Property

    🌏 4. IOI Properties Completes RM7.95 Billion Singapore Acquisition

    https://images.openai.com/static-rsc-4/7j-qiqH5s-9fqzlWqqPjPu0gubzytRjTSa-z9FzFkzCY4JuXy0-_8k-YRET5NwzKFZN6ihhpa-hFs75TrZ0n0XmFNJRnsbK0aBT9ZmjBooxH-bObKpUK7VBqOT-zLJaczPypqBxU-ZY4TlMgtIESgNalyPHFs6aHOVdFgkBfSYiKWiNQwf0Tt04iqT_ynaPS?purpose=fullsize

    What Happened

    IOI Properties Group has completed its acquisition of the company owning Asia Square Tower 2 in Singapore.

    The total cash outlay was approximately S$2.47 billion — around RM7.95 billion.

    The 46-storey integrated development at Marina View includes Grade A offices, retail space and parking, with approximately 773,000 sq ft of net lettable area.

    Why It Matters

    This is much bigger than a Malaysian developer buying an overseas building.

    It demonstrates how Malaysian property groups are increasingly looking beyond Malaysia for income-producing assets and geographical diversification.

    Miichael’s Review

    I find this particularly relevant to Malaysian investors.

    The property industry is becoming increasingly global.

    A Malaysian developer today may have:

    Residential → Industrial → Retail → Office → REIT → Overseas Assets

    That diversification can create resilience — but only if the company understands the market it is entering.

    And there’s another lesson:

    Sometimes the best property opportunity isn’t a new development. It is an existing income-producing asset.

    Source: EdgeProp, 18 September 2026.


    🌏 5. Australia: Housing Values Fall as Higher Rates Bite

    https://images.openai.com/static-rsc-4/tVw9lLv91mbn3JLpF70gDBGvznn3NWOzDDSpHHWno1XnMJhtSsSSmf-BQol8V87QgZ7WSIZ_8xGAvFRUz-ycM2WgAIL7VSxDWKCgGczsTze7JQUh5mVe392M6oH6yBjG9Xz8_rGoRcdZf95cyiekidEuP5Q0jq0UdUbz2PjmSs0xGj_u8oooZcQj9QSwrd8d?purpose=fullsize

    What Happened

    Australia’s housing market is showing signs of meaningful weakness.

    The latest Australian Bureau of Statistics data showed the total value of residential dwellings fell A$34.1 billion, or 0.3%, in the June quarter to A$12.69 trillion.

    The mean dwelling price fell 0.7% to A$1.10 million.

    New South Wales saw the mean dwelling price fall 2.4%, while Victoria fell 2.1%.

    And this week, the Reserve Bank of Australia’s governor warned that inflation risks are returning, keeping the possibility of further interest-rate tightening alive.

    Why It Matters

    This is a useful reminder for Malaysian property investors who look overseas.

    A country can have:

    Strong population + housing shortage + high property prices

    …and still experience falling values when financing conditions change.

    Miichael’s Review

    This is exactly why I keep saying:

    Property is a long-term financial commitment, not just a location decision.

    Interest rates can change the affordability equation very quickly.

    Source: Australian Bureau of Statistics and Reuters, September 2026.


    📊 PROPERTY NUMBER OF THE WEEK

    RM7.95 BILLION

    The approximate cash outlay by IOI Properties for Asia Square Tower 2 in Singapore.

    That’s not just a property transaction.

    It’s a statement about where Malaysian property companies are looking for growth.


    👀 WORTH WATCHING

    1. Malaysian REITs

    Will more REITs reposition existing retail and commercial assets instead of simply acquiring new properties?

    2. Affordable Housing

    Can developers continue delivering affordable homes while land, construction and financing costs remain elevated?

    3. Johor

    Land banking and development activity around the Johor-Singapore economic corridor remain worth watching.

    4. Interest Rates

    Australia’s renewed inflation concerns show how quickly monetary policy can change property-market sentiment.

    5. Malaysian Developers Going Overseas

    Will more Malaysian developers follow IOI Properties into Singapore and other regional markets?


    💡 MIICHAEL’S TAKEAWAY THIS WEEK

    This week’s five stories are deliberately very different.

    And that’s exactly what makes the property market interesting.

    We have:

    Retail repositioning.
    Affordable housing finance.
    Developer financial health.
    A RM7.95 billion overseas acquisition.
    And a housing market reacting to interest rates.

    Put them together and one thing becomes clear:

    There is no single “property market”.

    Different property sectors behave differently.

    Different states behave differently.

    Different countries behave differently.

    And different investors have different objectives.

    So rather than asking:

    “Is property going up or down?”

    Perhaps the better question is:

    “Which property, in which location, for which purpose, under which economic conditions?”

    That’s where better property decisions begin.

    Miichael Yeoh

    Property Strategist

  • Am I buying the right property?

    Am I buying the right property?

    Why Some Penang Properties Generate Strong Rental Income While Others Struggle

    Over the years, I’ve met many property investors who ask me the same question:

    “Miichael, which property should I buy?”

    My answer is usually the same.

    The better question is:

    “Why do some properties perform better than others?”

    Today, Penang continues to be one of Malaysia’s most attractive destinations. People come here for the food, culture, medical tourism, business opportunities, education, and lifestyle.

    As tourism and visitor arrivals continue to grow, so does the demand for short-term accommodation.

    This has created exciting opportunities for property investors.

    However, here’s something many people overlook.

    Not every property benefits equally.

    I’ve seen investors buy properties in popular locations only to discover that rental demand wasn’t as strong as expected.

    I’ve also seen investors achieve impressive returns because they understood something others missed.

    The difference often comes down to understanding the numbers.

    Location matters.

    Demand matters.

    Timing matters.

    What do ADR (Average Daily Rate) and occupancy rates really tell us?

    But perhaps most importantly, understanding rental data matters.

    How do you identify an area before prices start moving?

    How do you distinguish between a property that looks good and a property that actually performs well?

    These are the questions every investor should be asking.

    Another common misconception is that you need a large amount of capital to invest successfully.

    While capital helps, I’ve seen many investors structure their purchases intelligently through financing strategies, proper planning, and understanding market opportunities.

    Sometimes it’s not about how much money you have.

    It’s about how well you use it.

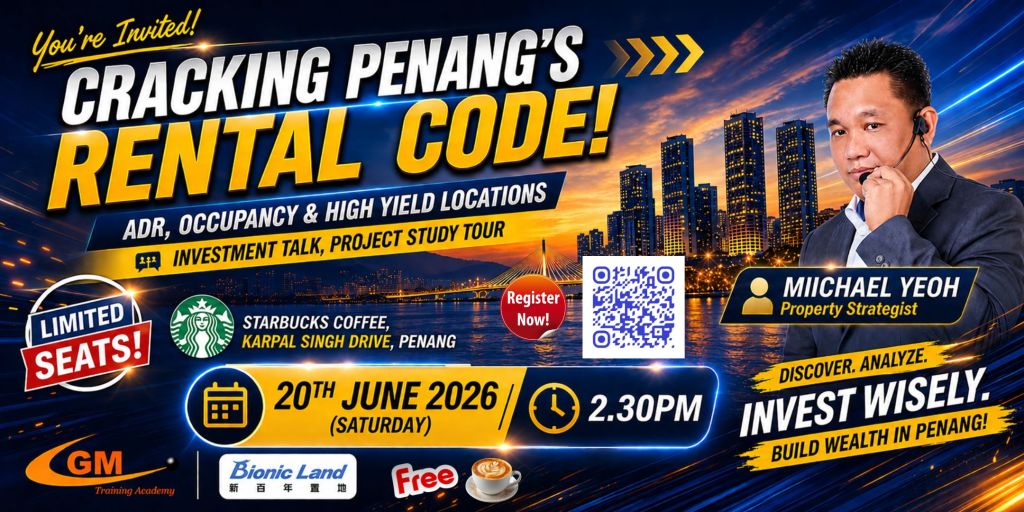
    That’s why I’ve decided to host a small-group sharing session in Penang where I’ll be revealing some of my latest research and observations on the rental market.

    We’ll discuss:

    ✔️ Insights from Penang’s Short-Term Rental Surge

    ✔️ How to identify high-yield property trends and focus areas

    ✔️ How to spot the right location before prices move

    ✔️ Understanding ADR, occupancy rates and real rental numbers

    ✔️ Building a profitable short-term rental strategy

    ✔️ Low-capital strategies that may help investors improve their returns

    Most importantly, this won’t be a typical seminar.

    We’ll be having discussions over coffee in a relaxed setting where you can ask questions and exchange ideas with fellow investors.

    Participants will also be invited to join an exclusive Property Study Tour to further enhance their understanding of location, demand drivers, and market opportunities.

    If you’re serious about understanding where Penang’s rental market is heading and how to position yourself for future opportunities, I believe you’ll find this session valuable.

    Event Details

    📅 Date: 20 June 2026 (Saturday)

    🕒 Time: 2:30 PM

    📍 Venue: Starbucks Coffee, Karpal Singh Drive, Penang

    ☕ Complimentary drink provided

    Seats are intentionally limited to ensure meaningful interaction and discussion.

    Register here: https://miichaelyeoh.com/event-page/

    I look forward to meeting you personally.

    — Miichael Yeoh

    Property Strategist | Developer Consultant | HRD Corp Certified Trainer

    Disclaimer: This reflects the author’s personal views based on market experience and current observations. It is not financial advice. Smart investors do their own research before making any move.

  • Before You Buy Property, Do This First — Or You’re Just Guessing

    Before You Buy Property, Do This First — Or You’re Just Guessing

    Smart Investors Don’t Start With Property — They Start With Demand

    Most people think property investment starts with:

    Location.
    Price.
    Developer.

    It doesn’t.

    It starts with a much more fundamental question:

    Are you buying for own use… or for investment?

    Because if you get this wrong, everything else becomes noise.


    Step 1: Define Your Purpose (No Grey Area)

    I’ve seen buyers say they are investing…

    But make decisions based on:

    • Design
    • Lifestyle
    • Personal preference

    That’s not investing.

    That’s emotion.

    If it’s own stay, you follow your lifestyle.

    If it’s investment, you follow demand and numbers.


    Step 2: Know Your Budget (This Sets Your Playing Field)

    Before anything else:

    • What is your true affordability?
    • What is your financing capacity?
    • What is your holding strength?

    Because in property:

    You don’t lose money when you buy wrong.
    You lose money when you can’t hold.

    Especially for investors—cash flow and holding power are everything.


    Step 3: Real Investors Do One Thing Differently — They RESEARCH

    This is the biggest gap in the market.

    Most buyers rely on:

    • Marketing materials
    • Sales narratives
    • “Good location” claims

    But experienced investors?

    They study the market before they commit.


    What Do You Actually Research?

    1. Demand & Demographics (The Real Starting Point)

    Forget the building first.

    Ask:

    Who is the end user of this property?

    • Young professionals?
    • Families?
    • Tourists?
    • Businesses?

    If you don’t understand demand,
    you’re not investing—you’re guessing.


    And This Is Where Industrial Property Becomes Interesting

    For big-budget investors, the shift is already happening.

    Demand is no longer driven by lifestyle.

    It’s driven by business movement and capital flow.

    Look at what’s happening:

    • Manufacturing relocation into Malaysia
    • Growth in logistics and warehousing
    • E-commerce expansion
    • Supply chain restructuring across ASEAN

    This creates a different type of demand:

    • Larger space requirements
    • Functional layouts over aesthetics
    • Accessibility to ports, highways, and labour
    • Long-term tenancy from businesses (not individuals)

    In other words:

    Industrial demand is economic-driven, not sentiment-driven.

    And that’s exactly what sophisticated investors are looking for.


    2. Price Per Square Foot (Entry Determines Exit)

    You make money when you buy right.

    Compare:

    • Nearby transactions
    • Competing projects
    • Replacement cost

    If you enter too high, your upside is already limited.


    3. Surrounding Supply (The Silent Risk)

    Most investors ignore this.

    But supply determines:

    • Rental pressure
    • Vacancy risk
    • Exit liquidity

    Too much incoming supply?

    Even a “good project” can underperform.


    4. Infrastructure & Connectivity (Follow the Growth)

    No area grows randomly.

    Growth follows:

    • Highways
    • Ports
    • Rail (LRT / MRT / logistics links)
    • Industrial corridors

    If infrastructure is expanding, demand usually follows.


    5. Rental & Yield Reality Check

    At the end of the day:

    Can it generate income?

    • What is the realistic rental?
    • Who is the tenant profile?
    • What is the occupancy expectation?

    If the numbers don’t work on paper,
    don’t rely on hope.


    What I’ve Learned From the Ground

    After evaluating multiple projects and markets, one thing is clear:

    The winners are not those who buy the most.
    The winners are those who understand demand the best.

    Every property I consider goes through:

    • Demand validation
    • Market comparison
    • Supply analysis
    • Financial assessment

    Because once you commit,
    you’re not just buying property…

    You’re locking in a decision for years.


    Final Thought

    Property investment has evolved.

    It’s no longer about chasing what’s popular.

    It’s about understanding why demand exists—and where it’s going next.

    Those who do the work will always have an edge.

    Those who don’t…

    Will always be reacting.


    Disclaimer: This reflects the author’s personal views based on market experience and current observations. It is not financial advice. Smart investors do their own research before making any move.

    From the Desk of

    Miichael Yeoh

  • Property Is Still Alive — But the Game Has Changed

    Property Is Still Alive — But the Game Has Changed

    Buying a property today is very different compared to 10 or 20 years ago.

    Back then, property could sell very easily.
    Developers launched, buyers queued, and decisions were made quickly.

    Today, the world has changed.

    The way people buy property has changed.
    The way markets behave has changed.
    And more importantly, the way buyers think has changed.

    Buyers today are far more informed.

    Before even paying a booking fee, many would have already:

    • Compared multiple projects
    • Studied pricing trends
    • Checked developer track record
    • Analysed location fundamentals
    • Calculated loan eligibility and cash flow

    In other words, today’s buyers are not just buyers — they are researchers.


    At the same time, the global environment is not exactly calm.

    We are seeing ongoing geopolitical tensions — from the US–Iran situation to instability in parts of the Middle East.
    Interest rates, inflation, and currency movements continue to shift.

    All these create one thing: uncertainty.

    And when uncertainty comes in, market behaviour changes.

    From what I observe in today’s property market:

    • Investors are waiting — not exiting
    • Sellers are holding — not reducing
    • Buyers are selective — not absent

    Let that sink in.

    The market is not dead.
    It is simply… more cautious.


    And here is something many people miss:

    👉 When the market is not stable, that is where the opportunity lies.

    Why?

    Because:

    • Less emotional buying
    • More rational pricing
    • More room for negotiation
    • More time to analyse properly

    In a hot market, people chase.
    In a cautious market, people choose.

    And those who choose well, win.


    This is exactly why I started focusing on Property Market Intelligence.

    Not just looking at property as a product,
    but understanding:

    • Market timing
    • Buyer psychology
    • Financing structure
    • Exit strategy
    • Risk positioning

    This approach is built from more than 25 years in the property and banking industry.

    I have gone through multiple market cycles:

    • Asian Financial Crisis
    • Global Financial Crisis
    • Property slowdowns
    • Policy changes
    • And shifting buyer behaviours across decades

    Every cycle teaches one thing:

    👉 The market will always move — but not everyone moves with it.


    Today, success in property is no longer about:
    “Buy and wait.”

    It is about:
    “Buy with clarity.”

    Because in today’s market:

    • Information is everywhere
    • But insight is rare

    If you are buying today, don’t just ask:

    “Is this a good property?”

    Ask instead:

    • Who will buy from me later?
    • What is the demand driver here?
    • How does financing affect my holding power?
    • What happens if the market stays slow for 3–5 years?

    That is how professionals think.


    The market has not disappeared.

    It has simply matured.

    And in a mature market,
    strategy will always beat impulse.


    Miichael Yeoh
    Property Strategist | Author

    Author of:
    Think Like a Banker, Act Like a Player
    Property Investment BLT
    Buying Property Like a Pro (MPH Bestseller)

  • Think Like a Banker Before You Buy Property

    Think Like a Banker Before You Buy Property

    One thing I learned from working closely with banks is this:

    Banks are extremely careful before approving a property loan.

    They analyse risks, stress-test your finances, and study whether you can survive difficult situations.

    But here’s the irony.

    Many property buyers don’t analyse their purchase the same way.

    They look at the show unit.
    They listen to marketing promises.
    They follow what others are buying.

    But they rarely ask the same questions a banker would ask.

    If you want to invest in property wisely, start by thinking like a banker.

    Here are three things bankers always analyse.


    1️⃣ Debt Ratio – Are You Stretching Yourself Too Thin?

    Banks look closely at your Debt Service Ratio (DSR).

    This measures how much of your income is used to pay debts.

    Even if a bank approves your loan, you should still ask yourself:

    • What happens if interest rates increase?
    • What if my income drops temporarily?
    • Will I still feel comfortable servicing the loan?

    A property might look affordable today.

    But bankers always plan for tomorrow’s risks.


    2️⃣ Holding Power – Can You Hold Through Market Cycles?

    Property markets don’t always go up.

    There will be slow periods.

    Bankers evaluate whether a borrower has the financial strength to continue paying during tough times.

    Smart investors should ask:

    • Can I hold this property for 5–10 years if needed?
    • Do I have cash reserves?
    • What if the market takes longer to recover?

    Many investors fail not because they bought the wrong property…

    They fail because they cannot hold it long enough.


    3️⃣ Rental Sustainability – Can the Property Support Itself?

    Another banker mindset is income sustainability.

    Before buying, ask:

    • Is there real rental demand here?
    • Who are the potential tenants?
    • Can the rental help support the loan?

    A strong investment property should ideally generate rental income that supports part of the financing.

    This reduces pressure and improves long-term stability.


    Final Thought

    Successful property investors don’t buy emotionally.

    They evaluate property like a banker evaluating risk.

    Before your next purchase, ask yourself:

    Does this property pass the banker’s test?

    When you start thinking like a banker, you don’t just buy property.

    You build a stronger and safer property portfolio.


    Miichael Yeoh
    Property Strategist | Developer Consultant | Investment & Mortgage Expert
    Author of Think Like a Banker, Act Like a Player

  • The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?

    The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?

    The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?

    For many years, property investing in Malaysia followed a familiar formula.

    Buy a new launch, wait a few years, and hope the price goes up.

    This strategy worked reasonably well during earlier property cycles when prices were rising quickly, financing was easier, and supply was more limited. Many investors entered the market believing that capital appreciation alone would justify the purchase.

    But today, the Malaysian property market has entered a different phase.

    The question buyers should now ask is no longer “Will the price go up?”
    The more important question is “Can this property sustain itself financially?”


    The Shift From Speculation to Sustainability

    Over the past decade, the mindset of property buyers has gradually evolved.

    Today’s buyers are more cautious, more analytical, and more focused on cash flow and long-term holding power.

    Instead of relying purely on future price appreciation, investors are increasingly asking questions such as:

    • What is the rental demand in this area?
    • Can the rental cover most of the loan instalment?
    • What happens if interest rates increase?
    • Who is the actual tenant profile for this property?

    These questions reflect a more mature approach to property investing.

    The reality is simple: not every property will appreciate significantly in the short term. When appreciation slows, the ability of the property to generate rental income becomes far more important.


    Financing Strategy Now Matters More Than Ever

    Another major shift in the market is the growing importance of financing structure.

    Many buyers focus heavily on the purchase price but pay little attention to how the property is financed. Yet the financing strategy can determine whether an investment becomes manageable or financially stressful.

    Buyers today need to consider:

    • Loan margin and interest rates
    • Monthly instalment affordability
    • Holding power during market slowdowns
    • Overall debt exposure

    A well-structured loan can give investors time and flexibility, while poor financial planning can force them to sell prematurely.

    Thinking about financing before buying is no longer optional — it is essential.


    Rental Demand Is Becoming a Key Decision Factor

    One of the biggest mistakes many investors made in the past was buying properties without considering who would actually rent the unit.

    Today, buyers are beginning to look more closely at demand drivers such as:

    • Proximity to employment hubs
    • Accessibility and transportation infrastructure
    • Nearby universities or hospitals
    • Tourism demand and short-term rental potential

    In markets like Penang, Kuala Lumpur, and Johor Bahru, rental demand is increasingly shaping investment decisions.

    For example, areas with strong tourism activity or major infrastructure developments may offer better rental prospects compared to purely speculative locations.

    The key question investors should ask is:

    “Who is my tenant?”

    If there is no clear answer, the investment may not perform as expected.


    The Role of Infrastructure and Economic Drivers

    Another important factor influencing property performance today is real economic activity.

    Infrastructure projects, transportation connectivity, employment centres, and tourism growth can significantly impact both rental demand and long-term property value.

    For instance, upcoming transportation developments and urban revitalisation projects in cities such as Georgetown could change demand patterns in the coming years.

    However, infrastructure alone does not guarantee success. The surrounding ecosystem — population growth, business activity, and lifestyle demand — must also support the property market.


    Buying Property Today Requires a Different Mindset

    The Malaysian property market has not disappeared. But the way buyers approach property must evolve.

    Successful investors today tend to follow a more balanced approach:

    • Evaluate rental yield and cash flow
    • Structure financing carefully
    • Understand real demand drivers
    • Focus on long-term sustainability

    In other words, the focus has shifted from short-term speculation to long-term investment discipline.


    A Final Thought

    Property has always been a long-term asset class.

    But in today’s market environment, buying property requires more than just optimism about future price growth.

    It requires careful thinking, realistic financial planning, and a clear understanding of market demand.

    The Malaysian property market has changed.

    The real question is — have buyers changed with it?


    Miichael Yeoh
    Property Strategist | Developer Consultant | HRD Corp Trainer

    Miichael Yeoh has more than 28 years of experience spanning banking, mortgage advisory, property investment, and developer consultancy. He is also the author of Think Like a Banker, Act Like a Player, Property Investment BLT, and Buying Property Like A Pro.

  • Residential Property & Mortgage Trends in Malaysia (2026 and beyond)

    Residential Property & Mortgage Trends in Malaysia (2026 and beyond)

    By Miichael Yeoh

    The Malaysian property market has been through a lot in the last few years — pandemic, inflation, rising construction costs, slow wage growth, and changing buyer behaviour. But as we step into 2025, one thing is clear:

    Property is still moving… but the market is no longer the same.
    Buyers are more cautious, banks are more selective, and affordability remains a major issue.

    Here’s my take on what’s really happening in the residential property and mortgage landscape, and what you should pay attention to — especially if you’re planning to buy, invest, or restructure your loans.


    📈 Long-Term Price Trend: Property Still Moves Up

    Whether the market is “good” or “bad”, one fact remains consistent:

    Property prices in Malaysia have been rising steadily for the last 20+ years.

    Urban areas like Klang Valley, Penang and Johor consistently show appreciation because of:

    • population growth
    • job concentration
    • infrastructure development
    • scarcity of prime land

    But here’s the catch:
    House prices have risen much faster than income, making affordability the No.1 challenge for Malaysians today.

    This explains why many young buyers are stuck deciding between renting longer… or compromising on location and size.


    🏘️ What’s Happening in the Market Now?

    1. Transaction volume is rising — but buyers are choosy

    2024 recorded strong growth in overall property transactions, and 2025 is projected to see single-digit positive growth.
    People are buying — but not blindly.

    Buyers today compare:

    • price per sq ft
    • rental potential
    • exit value
    • access to MRT / LRT
    • developer reputation

    Gone are the days when anything “new launch” can sell out.
    Today, value matters more than hype.


    💰 Mortgage & Financing Trend: Here’s the Real Story

    The biggest shift recently is OPR dropping to 2.75%, making borrowing cheaper.

    This directly means:

    • Lower monthly instalments
    • Higher loan eligibility
    • Better cashflow for investors

    But with great news comes reality…
    Banks are approving loans more carefully than ever.

    Your CCRIS, CTOS, commitments and even gig-income consistency matter.
    If your financial health is not clean, even a low OPR won’t help you.

    For many Malaysians, the challenge isn’t interest rate — it’s getting the loan approved.


    🧱 Supply vs Demand: The Affordable Gap

    You’re hearing this everywhere:

    “So many houses unsold!”
    —but at the same time—
    “I can’t find any home I can afford!”

    Why?
    Because the overhang is mainly:

    • too expensive for the mass market
    • too big (1,000 sq ft and above)
    • wrong location

    This mismatch will continue unless developers pivot more aggressively into the mid-market segment.


    🧭 What Buyers & Investors Should Look At Now

    ✔️ If you’re a first-time buyer

    This is a golden window.
    Low OPR + many choices + developers offering incentives = value for money.

    Look for:

    • good location > big size
    • future MRT/LRT corridors
    • reputable developers
    • high rental demand areas

    ✔️ If you’re an investor

    Capital gain will still happen — but don’t expect overnight appreciation.
    Focus on:

    • rental yield
    • undervalued areas
    • distress or motivated sellers
    • T.O.P. projects with ready tenants

    The smart investors in 2025 are not speculating.
    They’re buying below market value, or in growth corridors, or early in new infrastructure zones.

    ✔️ If you own multiple properties with loans

    This is the best time to:

    • refinance
    • consolidate debts
    • reset your cashflow
    • restructure your portfolio

    A small adjustment in interest rate can save thousands per year.


    🧩 Conclusion: The Market Isn’t Booming, But It’s Moving

    Malaysia’s residential market today is stable, resilient, and buyer-driven.
    We’re not in a bubble.
    We’re not in a crash.

    We’re in a value-driven market, where the winners are:
    ✔️ informed buyers
    ✔️ strategic investors
    ✔️ those who manage their loans wisely

    If you understand the trends — and you know how to analyse value correctly — 2025-2026 can be a very profitable year for you.