Tag: investing

  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    Week in Review | 12–18 September 2026

    Malaysia • Regional Property • Global Insights
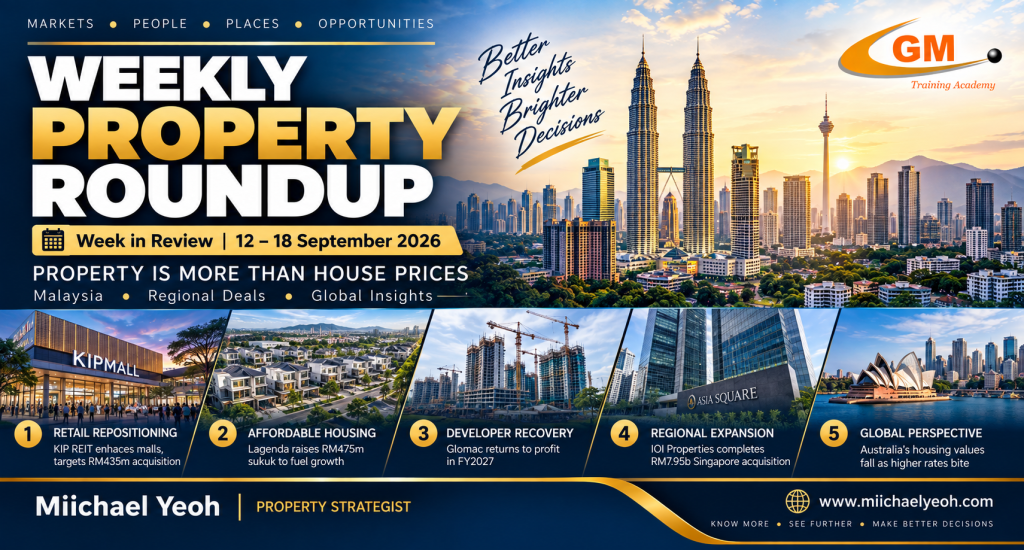
    The property market is bigger than house prices. Follow the money, the people and the assets.


    🇲🇾 1. KIP REIT: Retail Property Is Being Repositioned, Not Abandoned

    https://images.openai.com/static-rsc-4/FE3MJchSQotX9YuPbZPIptH2f3klwx57hOtiag2TrNWJqNoH_DJyzrHa7K8Vf0R5R59-cWO0p0wq2ag0mRP_tqj2NvEL8yA4sLbNgXWMvdynUaBGhfgMFI9IrOCiEMIe14OC3bExGI0mfAT00kd2GuHIlQ46ZNiGwPp00pgOSI0UV6qfJd8-Vrq6nlCryRjt?purpose=fullsize

    What Happened

    KIP REIT plans asset enhancement initiatives at three malls — KIPMall Masai, KIPMall Kota Warisan and AEON Mall Kinta City.

    The strategy is aimed at improving operational efficiency and supporting longer-term rental growth.

    There is another interesting move: KIP REIT is targeting completion of its RM435 million acquisition of Setapak Central Mall, which would be its largest acquisition to date and take assets under management to about RM2.2 billion.

    Why It Matters

    Retail property is often written off as “old economy”.

    But successful malls are increasingly becoming community infrastructure — food, services, groceries, healthcare, entertainment and daily necessities.

    The question isn’t simply:

    “Is shopping mall demand declining?”

    It should be:

    “Can the asset remain relevant to its surrounding population?”

    Miichael’s Review

    This is something I find particularly interesting.

    Property owners don’t always need to build something new to create value.

    Sometimes, repositioning an existing asset can be the smarter strategy.

    Source: EdgeProp, 18 September 2026.


    🇲🇾 2. RM475 Million Sukuk: Affordable Housing Needs Capital Too

    https://images.openai.com/static-rsc-4/qZnwyXfXtbssVeM0gJ0UyMNoQ_HOxzgGPPQ7VJoTwrJYrEoEtoVE5gdnAwYgBxswD2HlM1X_3PortDlviTMSly0x0BG3yPCgk_eCc2onB607e5S7XRRhYTpPkA6NO631rPH7rlBvpvcO_MY3VPoVQFihdmjB9NJu05BHNuIg-s-3xMn04WrPYYRufXekwqeN?purpose=fullsize

    What Happened

    Lagenda Properties has completed its first RM475 million sukuk issuance under a larger RM1.5 billion Sukuk Wakalah programme.

    The proceeds will be used for acquisitions, working capital and affordable housing developments.

    Why It Matters

    Affordable housing is sometimes discussed only from the buyer affordability perspective.

    But there is another side:

    How do developers finance affordable housing profitably and sustainably?

    If construction costs, land costs and financing costs continue rising, access to capital becomes critical.

    Miichael’s Review

    I like this story because it reminds us that property is not just about selling houses.

    There is an entire financial ecosystem behind every development:

    Land → Financing → Construction → Sales → Delivery → Exit

    Understanding that chain helps us understand why some developers can keep expanding while others struggle.

    Source: EdgeProp, 18 September 2026.


    🇲🇾 3. Glomac Returns to Profit — A Reminder to Watch Developer Health

    https://images.openai.com/static-rsc-4/hnQvi8sM8duuJGU7EE09eEA36eU0yr074Tx8dEJcKR2F7ILr4VKSjElTjjxtlcn3QJQdPXunhBy9_mroevHS0x5o-iUlk9xfvSJUPvTiezwh2azShtwakbqaJPSEYhlQSMnPyHSZwi8jbeYzgtp2Pd2xVk4516ALCQ8bw_BUs3zAVSohSS6Gl3imZ6u4dLlt?purpose=fullsize

    What Happened

    Glomac returned to the black in its first quarter of FY2027.

    Net profit attributable to owners reached RM7.6 million, compared with a RM1.42 million loss a year earlier.

    Revenue jumped 163% to RM68.53 million, with property-development revenue more than tripling to RM61.12 million.

    More encouragingly, borrowings fell from RM237.0 million at end-April to RM224.4 million at end-July, while cash and short-term placements stood at RM249.5 million.

    Why It Matters

    When considering a new development, buyers often focus on:

    • Location
    • Price
    • Facilities
    • Discounts

    But one question is frequently overlooked:

    Who is the developer and how financially healthy are they?

    Miichael’s Review

    A property doesn’t exist in isolation.

    The developer’s financial strength can influence construction progress, delivery, future phases and ultimately buyer confidence.

    For me, developer due diligence should be part of property due diligence.

    Source: EdgeProp, 18 September 2026.
    Click to register for the event : Before You Buy The Next Property

    🌏 4. IOI Properties Completes RM7.95 Billion Singapore Acquisition

    https://images.openai.com/static-rsc-4/7j-qiqH5s-9fqzlWqqPjPu0gubzytRjTSa-z9FzFkzCY4JuXy0-_8k-YRET5NwzKFZN6ihhpa-hFs75TrZ0n0XmFNJRnsbK0aBT9ZmjBooxH-bObKpUK7VBqOT-zLJaczPypqBxU-ZY4TlMgtIESgNalyPHFs6aHOVdFgkBfSYiKWiNQwf0Tt04iqT_ynaPS?purpose=fullsize

    What Happened

    IOI Properties Group has completed its acquisition of the company owning Asia Square Tower 2 in Singapore.

    The total cash outlay was approximately S$2.47 billion — around RM7.95 billion.

    The 46-storey integrated development at Marina View includes Grade A offices, retail space and parking, with approximately 773,000 sq ft of net lettable area.

    Why It Matters

    This is much bigger than a Malaysian developer buying an overseas building.

    It demonstrates how Malaysian property groups are increasingly looking beyond Malaysia for income-producing assets and geographical diversification.

    Miichael’s Review

    I find this particularly relevant to Malaysian investors.

    The property industry is becoming increasingly global.

    A Malaysian developer today may have:

    Residential → Industrial → Retail → Office → REIT → Overseas Assets

    That diversification can create resilience — but only if the company understands the market it is entering.

    And there’s another lesson:

    Sometimes the best property opportunity isn’t a new development. It is an existing income-producing asset.

    Source: EdgeProp, 18 September 2026.


    🌏 5. Australia: Housing Values Fall as Higher Rates Bite

    https://images.openai.com/static-rsc-4/tVw9lLv91mbn3JLpF70gDBGvznn3NWOzDDSpHHWno1XnMJhtSsSSmf-BQol8V87QgZ7WSIZ_8xGAvFRUz-ycM2WgAIL7VSxDWKCgGczsTze7JQUh5mVe392M6oH6yBjG9Xz8_rGoRcdZf95cyiekidEuP5Q0jq0UdUbz2PjmSs0xGj_u8oooZcQj9QSwrd8d?purpose=fullsize

    What Happened

    Australia’s housing market is showing signs of meaningful weakness.

    The latest Australian Bureau of Statistics data showed the total value of residential dwellings fell A$34.1 billion, or 0.3%, in the June quarter to A$12.69 trillion.

    The mean dwelling price fell 0.7% to A$1.10 million.

    New South Wales saw the mean dwelling price fall 2.4%, while Victoria fell 2.1%.

    And this week, the Reserve Bank of Australia’s governor warned that inflation risks are returning, keeping the possibility of further interest-rate tightening alive.

    Why It Matters

    This is a useful reminder for Malaysian property investors who look overseas.

    A country can have:

    Strong population + housing shortage + high property prices

    …and still experience falling values when financing conditions change.

    Miichael’s Review

    This is exactly why I keep saying:

    Property is a long-term financial commitment, not just a location decision.

    Interest rates can change the affordability equation very quickly.

    Source: Australian Bureau of Statistics and Reuters, September 2026.


    📊 PROPERTY NUMBER OF THE WEEK

    RM7.95 BILLION

    The approximate cash outlay by IOI Properties for Asia Square Tower 2 in Singapore.

    That’s not just a property transaction.

    It’s a statement about where Malaysian property companies are looking for growth.


    👀 WORTH WATCHING

    1. Malaysian REITs

    Will more REITs reposition existing retail and commercial assets instead of simply acquiring new properties?

    2. Affordable Housing

    Can developers continue delivering affordable homes while land, construction and financing costs remain elevated?

    3. Johor

    Land banking and development activity around the Johor-Singapore economic corridor remain worth watching.

    4. Interest Rates

    Australia’s renewed inflation concerns show how quickly monetary policy can change property-market sentiment.

    5. Malaysian Developers Going Overseas

    Will more Malaysian developers follow IOI Properties into Singapore and other regional markets?


    💡 MIICHAEL’S TAKEAWAY THIS WEEK

    This week’s five stories are deliberately very different.

    And that’s exactly what makes the property market interesting.

    We have:

    Retail repositioning.
    Affordable housing finance.
    Developer financial health.
    A RM7.95 billion overseas acquisition.
    And a housing market reacting to interest rates.

    Put them together and one thing becomes clear:

    There is no single “property market”.

    Different property sectors behave differently.

    Different states behave differently.

    Different countries behave differently.

    And different investors have different objectives.

    So rather than asking:

    “Is property going up or down?”

    Perhaps the better question is:

    “Which property, in which location, for which purpose, under which economic conditions?”

    That’s where better property decisions begin.

    Miichael Yeoh

    Property Strategist
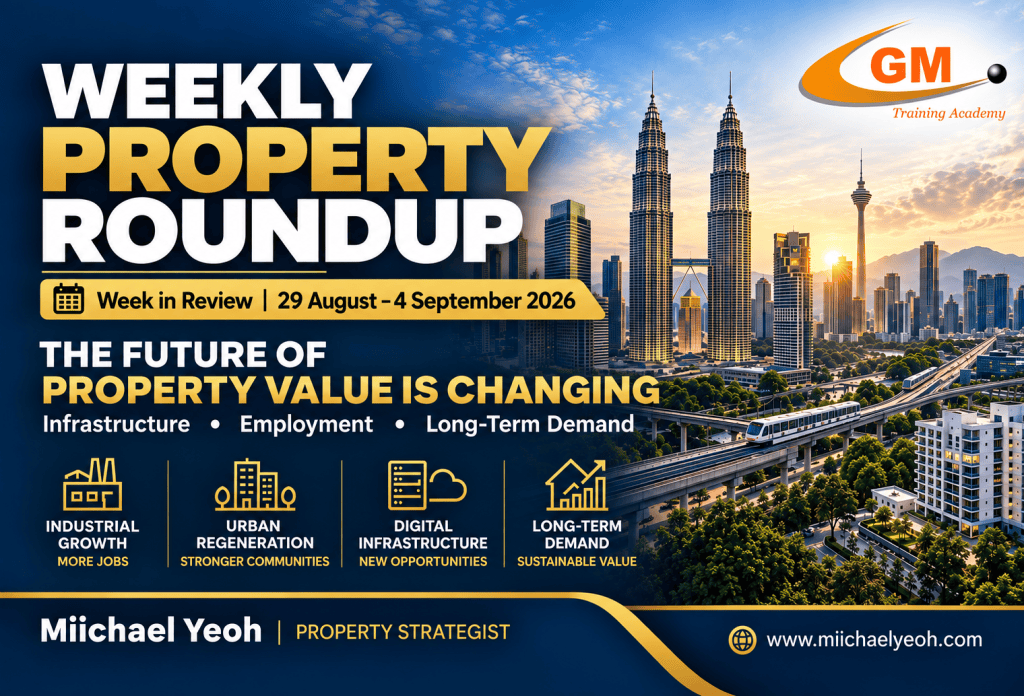
  • WEEKLY PROPERTY ROUNDUP | Week in Review (29 August – 4 September 2026)

    WEEKLY PROPERTY ROUNDUP | Week in Review (29 August – 4 September 2026)

    Top 3 developments I believe every buyer and investor should know

    Good morning everyone,

    Every week, I try to answer one simple question:

    What really matters in Malaysia’s property market?

    The biggest lesson from the past week is this: property value is increasingly created by infrastructure, employment and the quality of the surrounding ecosystem—not just by the building itself.

    Here are the Top 3 developments I believe every buyer and investor should know.

    1. Malaysia’s Industrial Growth Continues to Drive Property Demand

    Malaysia's semiconductor industry development strategy

    What happened?

    Malaysia’s advanced manufacturing and semiconductor sectors continued attracting new investment, with Penang remaining one of the country’s strongest industrial growth regions. Industry reports show industrial investment remains concentrated in high-value manufacturing, electronics and supply-chain expansion.

    Why it matters

    Industrial growth doesn’t just create factories—it creates jobs, talent, housing demand, logistics, retail and commercial activity. Historically, areas experiencing sustained employment growth tend to enjoy healthier long-term property demand than areas driven purely by speculation.

    Miichael’s Review

    Many buyers ask me:

    “Which project will appreciate the most?”

    I think the better question is:

    “Where will people still be working five to ten years from now?”

    Follow employment before following property prices.

    Source: Industrial investment & manufacturing reports.

    2. Urban Regeneration Is Becoming the New Growth Story

    Malaysia Real Estate & Property in Seremban | Bandar Sri Sendayan

    What happened?

    Developers continue investing in mixed-use regeneration projects within mature townships rather than expanding endlessly into new suburbs. Projects like PJ Quarter demonstrate a growing focus on integrating residential, retail, public spaces and community facilities into established neighbourhoods.

    Source: EdgeProp

    Why it matters

    Today’s buyers increasingly value:

    • Walkability
    • Public transport
    • Healthcare & education
    • Lifestyle convenience
    • Community spaces

    These factors often contribute more to sustainable demand than simply having a prestigious address.

    Miichael’s Review

    A property’s postcode is important.

    But its ecosystem is even more valuable.

    That’s where long-term liveability and resale demand are created.

    Source: Developer announcement & urban regeneration reports.

    3. Digital Infrastructure Is Quietly Changing Land Value

    支持AI算力部署!万国数据马来西亚努沙再也科技园数据中心园区(二期)正式投运 - 万国数据服务有限公司

    What happened?

    Malaysia’s digital infrastructure momentum continues as developers and institutional investors increasingly recognise the strategic value of land supported by power capacity, fibre connectivity and industrial infrastructure. Data centres remain one of the strongest emerging land-demand drivers across several Malaysian states.

    Why it matters

    The next property growth story may not begin with another condominium launch.

    It may begin with:

    • Power infrastructure
    • Data connectivity
    • AI & cloud investment
    • Industrial ecosystem
    • Business expansion

    Miichael’s Review

    The opportunity isn’t owning a data centre.

    The opportunity is identifying the surrounding locations that benefit from the jobs, businesses and services that follow.

    That’s where long-term property value is often created.

    Source: Digital infrastructure & property investment reports.

    📊 Property Snapshot This Week

    Industrial Investment

    Strong

    Advanced manufacturing continues supporting property demand.

    Growth Focus

    Mature Townships

    Urban regeneration is attracting developer investment.

    Emerging Driver

    Data Centres

    Power & connectivity are becoming strategic land assets.

    Buyer Trend

    More Selective

    Buyers are placing greater emphasis on long-term value.

    👀 Worth Watching

    Over the coming weeks, I’ll be watching four areas closely:

    • Expansion of Malaysia’s semiconductor ecosystem
    • New mixed-use regeneration projects
    • Data-centre related land acquisitions
    • Locations where employment growth translates into genuine housing demand

    These will likely become the next wave of meaningful property stories.

    🎯 My Takeaway This Week

    Three different stories.

    Industrial growth. Urban regeneration. Digital infrastructure.

    But they all point to one conclusion:

    Don’t evaluate the property in isolation. Evaluate the ecosystem that supports it.

    Before buying, I would always ask:

    • Where will the jobs come from?
    • Is infrastructure improving?
    • Will people genuinely want to live or work here?
    • What creates demand five years from today?

    That’s where better property decisions begin.

    Miichael Yeoh

    PROPERTY STRATEGIST

    🌐 http://www.miichaelyeoh.com

    Thank you for subscribing!

    Please check your email to confirming your subscription.

  • Am I buying the right property?

    Am I buying the right property?

    Why Some Penang Properties Generate Strong Rental Income While Others Struggle

    Over the years, I’ve met many property investors who ask me the same question:

    “Miichael, which property should I buy?”

    My answer is usually the same.

    The better question is:

    “Why do some properties perform better than others?”

    Today, Penang continues to be one of Malaysia’s most attractive destinations. People come here for the food, culture, medical tourism, business opportunities, education, and lifestyle.

    As tourism and visitor arrivals continue to grow, so does the demand for short-term accommodation.

    This has created exciting opportunities for property investors.

    However, here’s something many people overlook.

    Not every property benefits equally.

    I’ve seen investors buy properties in popular locations only to discover that rental demand wasn’t as strong as expected.

    I’ve also seen investors achieve impressive returns because they understood something others missed.

    The difference often comes down to understanding the numbers.

    Location matters.

    Demand matters.

    Timing matters.

    What do ADR (Average Daily Rate) and occupancy rates really tell us?

    But perhaps most importantly, understanding rental data matters.

    How do you identify an area before prices start moving?

    How do you distinguish between a property that looks good and a property that actually performs well?

    These are the questions every investor should be asking.

    Another common misconception is that you need a large amount of capital to invest successfully.

    While capital helps, I’ve seen many investors structure their purchases intelligently through financing strategies, proper planning, and understanding market opportunities.

    Sometimes it’s not about how much money you have.

    It’s about how well you use it.

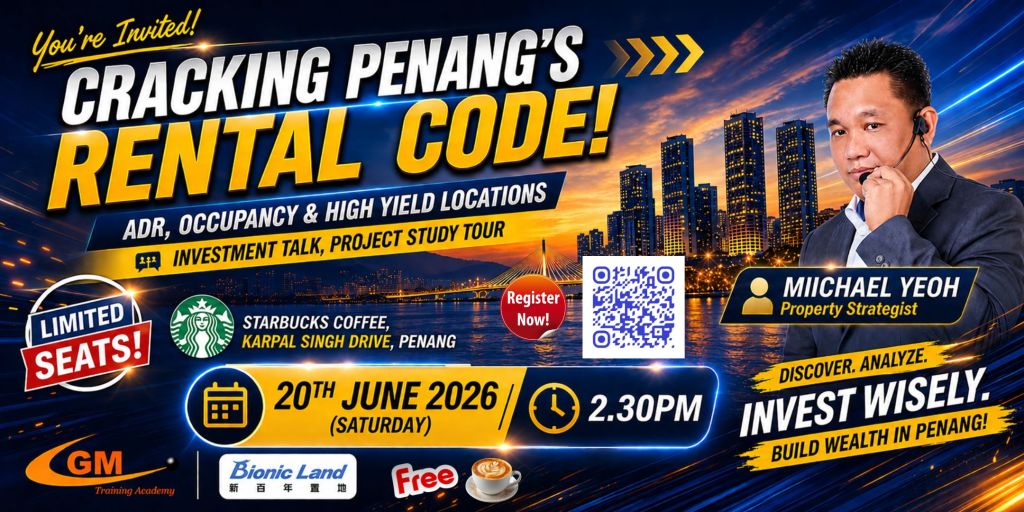
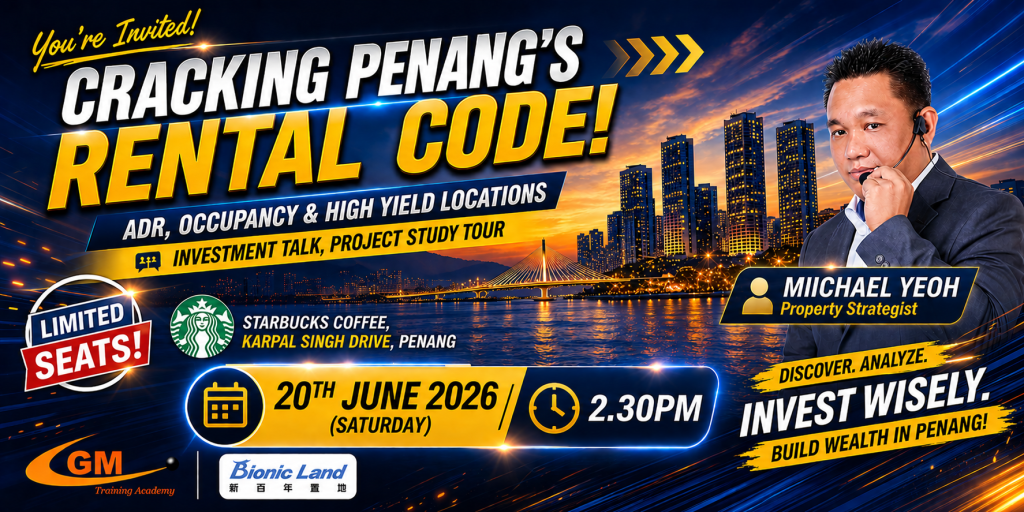
    That’s why I’ve decided to host a small-group sharing session in Penang where I’ll be revealing some of my latest research and observations on the rental market.

    We’ll discuss:

    ✔️ Insights from Penang’s Short-Term Rental Surge

    ✔️ How to identify high-yield property trends and focus areas

    ✔️ How to spot the right location before prices move

    ✔️ Understanding ADR, occupancy rates and real rental numbers

    ✔️ Building a profitable short-term rental strategy

    ✔️ Low-capital strategies that may help investors improve their returns

    Most importantly, this won’t be a typical seminar.

    We’ll be having discussions over coffee in a relaxed setting where you can ask questions and exchange ideas with fellow investors.

    Participants will also be invited to join an exclusive Property Study Tour to further enhance their understanding of location, demand drivers, and market opportunities.

    If you’re serious about understanding where Penang’s rental market is heading and how to position yourself for future opportunities, I believe you’ll find this session valuable.

    Event Details

    📅 Date: 20 June 2026 (Saturday)

    🕒 Time: 2:30 PM

    📍 Venue: Starbucks Coffee, Karpal Singh Drive, Penang

    ☕ Complimentary drink provided

    Seats are intentionally limited to ensure meaningful interaction and discussion.

    Register here: https://miichaelyeoh.com/event-page/

    I look forward to meeting you personally.

    — Miichael Yeoh

    Property Strategist | Developer Consultant | HRD Corp Certified Trainer

    Disclaimer: This reflects the author’s personal views based on market experience and current observations. It is not financial advice. Smart investors do their own research before making any move.

  • Is the Property Market Slowing Down… Or Are Buyers Becoming More Picky?

    Is the Property Market Slowing Down… Or Are Buyers Becoming More Picky?

    Lately, many people have been asking:

    “Is the property market slowing down?”

    Some projects are taking longer to sell.
    Some launches are seeing slower take-up.
    Buyers seem to be hesitating more before committing.

    At first glance, it may appear that the market is becoming weak.

    But when we look deeper into the numbers and buyer behaviour, the story may actually be different.

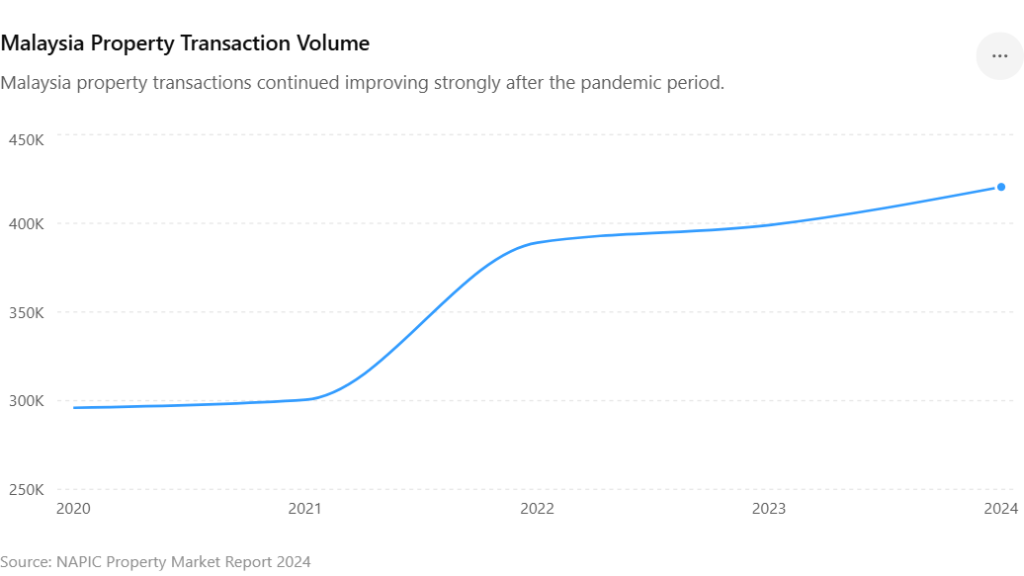
    According to the National Property Information Centre (NAPIC), Malaysia recorded more than 420,000 property transactions in 2024 — one of the strongest performances in the past decade.

    This tells us something important:
    The market still has buyers.

    However, today’s buyers are no longer buying property the same way they did years ago.

    Buyers today are becoming more informed, more cautious, and more selective before making decisions.

    In the past, some buyers purchased based on emotions, marketing hype, showroom designs, rebates, or fear of missing out (FOMO).

    Today, buyers are asking more questions:

    • Is the pricing reasonable?
    • Is there real demand in the area?
    • Can the property generate rental income?
    • Is the developer reliable?
    • Is there oversupply nearby?
    • Will the property still hold value in the future?

    In short — buyers today are becoming more picky.

    And honestly, that is not necessarily a bad thing.

    A property purchase is one of the biggest financial commitments for most people. Buyers today are thinking carefully about:

    • Monthly instalments
    • Interest rates
    • Maintenance fees
    • Cash flow commitments
    • Rental demand
    • Future resale value
    • Lifestyle suitability
    • Long-term financial stability

    This explains why some projects continue to perform well while others struggle with slower take-up.

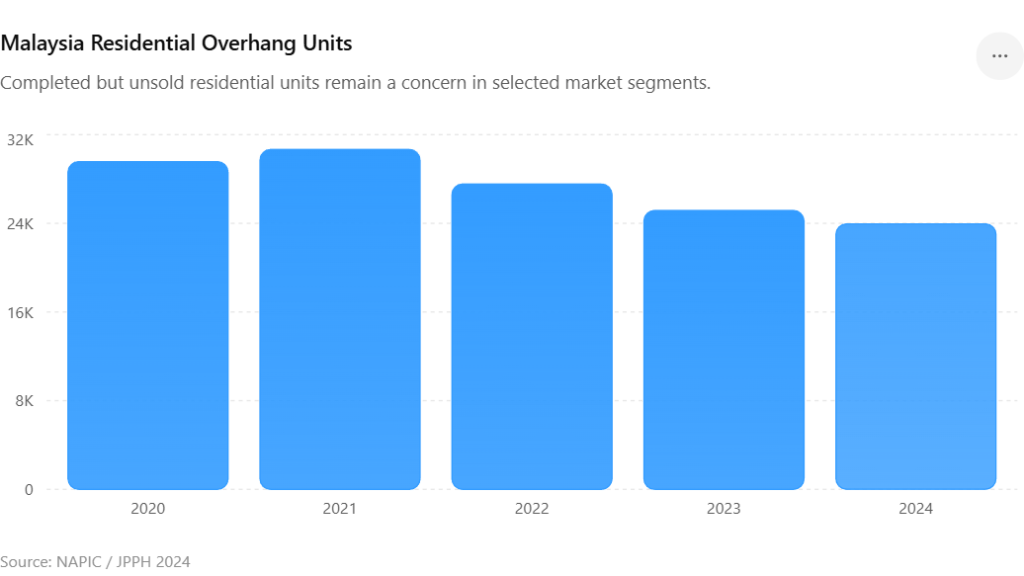
    In fact, NAPIC data also shows that Malaysia continues to face residential overhang issues in certain market segments. This means completed units remain unsold due to factors such as pricing mismatch, oversupply, poor accessibility, weak product positioning, or changing buyer preferences.

    This does not mean there are no buyers in the market.
    It simply means buyers are becoming more selective about where they place their money.

    Before buying any property project, buyers should spend time understanding:

    • The actual market demand
    • Existing and future supply in the area
    • Nearby competing developments
    • Developer track record and credibility
    • Connectivity and infrastructure plans
    • Market pricing compared to surrounding projects
    • Rental and resale potential
    • Their own financial holding power
    • Whether the property truly fits their long-term goals

    Many people still buy emotionally.
    But smart buyers buy strategically.

    A beautiful showroom alone should never be the reason to purchase a property.

    One thing I always encourage buyers to do before committing is to attend property seminars, educational talks, and market-sharing sessions.

    Why?

    Because knowledge reduces expensive mistakes.

    A good seminar can help buyers:

    • Understand current market trends
    • Learn from real case studies
    • Compare projects more objectively
    • Understand buyer psychology and market cycles
    • Avoid common investment mistakes
    • Gain confidence before making a large commitment

    In today’s market, education is becoming one of the most important tools for property buyers.

    The market may not necessarily be weak.
    It may simply be that buyers today are smarter, more informed, and more selective than before.

    And personally, I believe that is a healthy direction for the property market.

    From the Desk of,

    Miichael Yeoh

    Property Strategist

    Disclaimer: This reflects the author’s personal views based on market experience and current observations. It is not financial advice. Smart investors do their own research before making any move.

  • Before You Buy Property, Do This First — Or You’re Just Guessing

    Before You Buy Property, Do This First — Or You’re Just Guessing

    Smart Investors Don’t Start With Property — They Start With Demand

    Most people think property investment starts with:

    Location.
    Price.
    Developer.

    It doesn’t.

    It starts with a much more fundamental question:

    Are you buying for own use… or for investment?

    Because if you get this wrong, everything else becomes noise.


    Step 1: Define Your Purpose (No Grey Area)

    I’ve seen buyers say they are investing…

    But make decisions based on:

    • Design
    • Lifestyle
    • Personal preference

    That’s not investing.

    That’s emotion.

    If it’s own stay, you follow your lifestyle.

    If it’s investment, you follow demand and numbers.


    Step 2: Know Your Budget (This Sets Your Playing Field)

    Before anything else:

    • What is your true affordability?
    • What is your financing capacity?
    • What is your holding strength?

    Because in property:

    You don’t lose money when you buy wrong.
    You lose money when you can’t hold.

    Especially for investors—cash flow and holding power are everything.


    Step 3: Real Investors Do One Thing Differently — They RESEARCH

    This is the biggest gap in the market.

    Most buyers rely on:

    • Marketing materials
    • Sales narratives
    • “Good location” claims

    But experienced investors?

    They study the market before they commit.


    What Do You Actually Research?

    1. Demand & Demographics (The Real Starting Point)

    Forget the building first.

    Ask:

    Who is the end user of this property?

    • Young professionals?
    • Families?
    • Tourists?
    • Businesses?

    If you don’t understand demand,
    you’re not investing—you’re guessing.


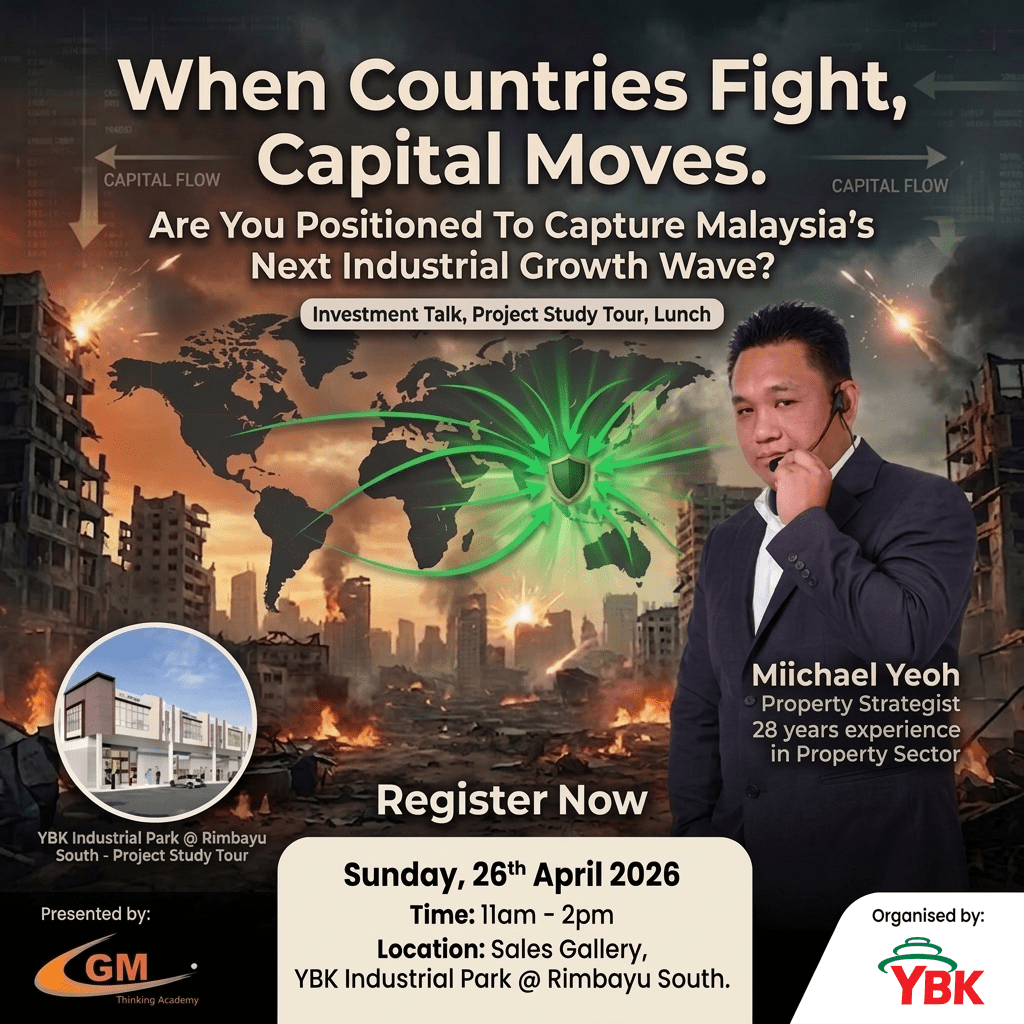
    And This Is Where Industrial Property Becomes Interesting

    For big-budget investors, the shift is already happening.

    Demand is no longer driven by lifestyle.

    It’s driven by business movement and capital flow.

    Look at what’s happening:

    • Manufacturing relocation into Malaysia
    • Growth in logistics and warehousing
    • E-commerce expansion
    • Supply chain restructuring across ASEAN

    This creates a different type of demand:

    • Larger space requirements
    • Functional layouts over aesthetics
    • Accessibility to ports, highways, and labour
    • Long-term tenancy from businesses (not individuals)

    In other words:

    Industrial demand is economic-driven, not sentiment-driven.

    And that’s exactly what sophisticated investors are looking for.


    2. Price Per Square Foot (Entry Determines Exit)

    You make money when you buy right.

    Compare:

    • Nearby transactions
    • Competing projects
    • Replacement cost

    If you enter too high, your upside is already limited.


    3. Surrounding Supply (The Silent Risk)

    Most investors ignore this.

    But supply determines:

    • Rental pressure
    • Vacancy risk
    • Exit liquidity

    Too much incoming supply?

    Even a “good project” can underperform.


    4. Infrastructure & Connectivity (Follow the Growth)

    No area grows randomly.

    Growth follows:

    • Highways
    • Ports
    • Rail (LRT / MRT / logistics links)
    • Industrial corridors

    If infrastructure is expanding, demand usually follows.


    5. Rental & Yield Reality Check

    At the end of the day:

    Can it generate income?

    • What is the realistic rental?
    • Who is the tenant profile?
    • What is the occupancy expectation?

    If the numbers don’t work on paper,
    don’t rely on hope.


    What I’ve Learned From the Ground

    After evaluating multiple projects and markets, one thing is clear:

    The winners are not those who buy the most.
    The winners are those who understand demand the best.

    Every property I consider goes through:

    • Demand validation
    • Market comparison
    • Supply analysis
    • Financial assessment

    Because once you commit,
    you’re not just buying property…

    You’re locking in a decision for years.


    Final Thought

    Property investment has evolved.

    It’s no longer about chasing what’s popular.

    It’s about understanding why demand exists—and where it’s going next.

    Those who do the work will always have an edge.

    Those who don’t…

    Will always be reacting.


    Disclaimer: This reflects the author’s personal views based on market experience and current observations. It is not financial advice. Smart investors do their own research before making any move.

    From the Desk of

    Miichael Yeoh

  • Property Is Still Alive — But the Game Has Changed

    Property Is Still Alive — But the Game Has Changed

    Buying a property today is very different compared to 10 or 20 years ago.

    Back then, property could sell very easily.
    Developers launched, buyers queued, and decisions were made quickly.

    Today, the world has changed.

    The way people buy property has changed.
    The way markets behave has changed.
    And more importantly, the way buyers think has changed.

    Buyers today are far more informed.

    Before even paying a booking fee, many would have already:

    • Compared multiple projects
    • Studied pricing trends
    • Checked developer track record
    • Analysed location fundamentals
    • Calculated loan eligibility and cash flow

    In other words, today’s buyers are not just buyers — they are researchers.


    At the same time, the global environment is not exactly calm.

    We are seeing ongoing geopolitical tensions — from the US–Iran situation to instability in parts of the Middle East.
    Interest rates, inflation, and currency movements continue to shift.

    All these create one thing: uncertainty.

    And when uncertainty comes in, market behaviour changes.

    From what I observe in today’s property market:

    • Investors are waiting — not exiting
    • Sellers are holding — not reducing
    • Buyers are selective — not absent

    Let that sink in.

    The market is not dead.
    It is simply… more cautious.


    And here is something many people miss:

    👉 When the market is not stable, that is where the opportunity lies.

    Why?

    Because:

    • Less emotional buying
    • More rational pricing
    • More room for negotiation
    • More time to analyse properly

    In a hot market, people chase.
    In a cautious market, people choose.

    And those who choose well, win.


    This is exactly why I started focusing on Property Market Intelligence.

    Not just looking at property as a product,
    but understanding:

    • Market timing
    • Buyer psychology
    • Financing structure
    • Exit strategy
    • Risk positioning

    This approach is built from more than 25 years in the property and banking industry.

    I have gone through multiple market cycles:

    • Asian Financial Crisis
    • Global Financial Crisis
    • Property slowdowns
    • Policy changes
    • And shifting buyer behaviours across decades

    Every cycle teaches one thing:

    👉 The market will always move — but not everyone moves with it.


    Today, success in property is no longer about:
    “Buy and wait.”

    It is about:
    “Buy with clarity.”

    Because in today’s market:

    • Information is everywhere
    • But insight is rare

    If you are buying today, don’t just ask:

    “Is this a good property?”

    Ask instead:

    • Who will buy from me later?
    • What is the demand driver here?
    • How does financing affect my holding power?
    • What happens if the market stays slow for 3–5 years?

    That is how professionals think.


    The market has not disappeared.

    It has simply matured.

    And in a mature market,
    strategy will always beat impulse.


    Miichael Yeoh
    Property Strategist | Author

    Author of:
    Think Like a Banker, Act Like a Player
    Property Investment BLT
    Buying Property Like a Pro (MPH Bestseller)

  • Think Like a Banker Before You Buy Property

    Think Like a Banker Before You Buy Property

    One thing I learned from working closely with banks is this:

    Banks are extremely careful before approving a property loan.

    They analyse risks, stress-test your finances, and study whether you can survive difficult situations.

    But here’s the irony.

    Many property buyers don’t analyse their purchase the same way.

    They look at the show unit.
    They listen to marketing promises.
    They follow what others are buying.

    But they rarely ask the same questions a banker would ask.

    If you want to invest in property wisely, start by thinking like a banker.

    Here are three things bankers always analyse.


    1️⃣ Debt Ratio – Are You Stretching Yourself Too Thin?

    Banks look closely at your Debt Service Ratio (DSR).

    This measures how much of your income is used to pay debts.

    Even if a bank approves your loan, you should still ask yourself:

    • What happens if interest rates increase?
    • What if my income drops temporarily?
    • Will I still feel comfortable servicing the loan?

    A property might look affordable today.

    But bankers always plan for tomorrow’s risks.


    2️⃣ Holding Power – Can You Hold Through Market Cycles?

    Property markets don’t always go up.

    There will be slow periods.

    Bankers evaluate whether a borrower has the financial strength to continue paying during tough times.

    Smart investors should ask:

    • Can I hold this property for 5–10 years if needed?
    • Do I have cash reserves?
    • What if the market takes longer to recover?

    Many investors fail not because they bought the wrong property…

    They fail because they cannot hold it long enough.


    3️⃣ Rental Sustainability – Can the Property Support Itself?

    Another banker mindset is income sustainability.

    Before buying, ask:

    • Is there real rental demand here?
    • Who are the potential tenants?
    • Can the rental help support the loan?

    A strong investment property should ideally generate rental income that supports part of the financing.

    This reduces pressure and improves long-term stability.


    Final Thought

    Successful property investors don’t buy emotionally.

    They evaluate property like a banker evaluating risk.

    Before your next purchase, ask yourself:

    Does this property pass the banker’s test?

    When you start thinking like a banker, you don’t just buy property.

    You build a stronger and safer property portfolio.


    Miichael Yeoh
    Property Strategist | Developer Consultant | Investment & Mortgage Expert
    Author of Think Like a Banker, Act Like a Player

  • The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?

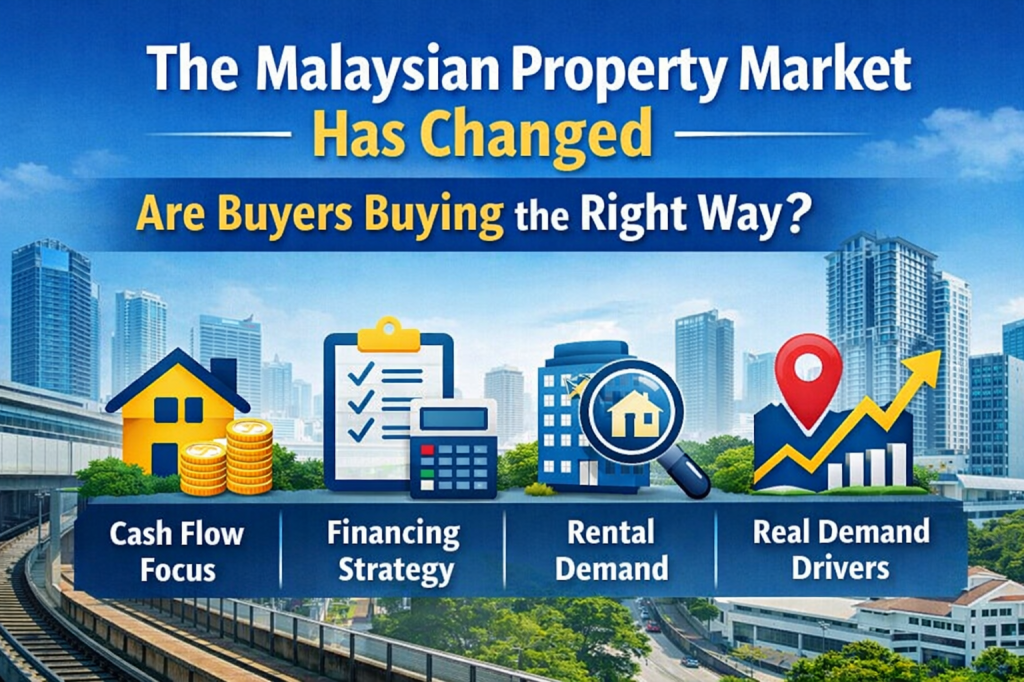
    The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?

    The Malaysian Property Market Has Changed — Are Buyers Buying the Right Way?

    For many years, property investing in Malaysia followed a familiar formula.

    Buy a new launch, wait a few years, and hope the price goes up.

    This strategy worked reasonably well during earlier property cycles when prices were rising quickly, financing was easier, and supply was more limited. Many investors entered the market believing that capital appreciation alone would justify the purchase.

    But today, the Malaysian property market has entered a different phase.

    The question buyers should now ask is no longer “Will the price go up?”
    The more important question is “Can this property sustain itself financially?”


    The Shift From Speculation to Sustainability

    Over the past decade, the mindset of property buyers has gradually evolved.

    Today’s buyers are more cautious, more analytical, and more focused on cash flow and long-term holding power.

    Instead of relying purely on future price appreciation, investors are increasingly asking questions such as:

    • What is the rental demand in this area?
    • Can the rental cover most of the loan instalment?
    • What happens if interest rates increase?
    • Who is the actual tenant profile for this property?

    These questions reflect a more mature approach to property investing.

    The reality is simple: not every property will appreciate significantly in the short term. When appreciation slows, the ability of the property to generate rental income becomes far more important.


    Financing Strategy Now Matters More Than Ever

    Another major shift in the market is the growing importance of financing structure.

    Many buyers focus heavily on the purchase price but pay little attention to how the property is financed. Yet the financing strategy can determine whether an investment becomes manageable or financially stressful.

    Buyers today need to consider:

    • Loan margin and interest rates
    • Monthly instalment affordability
    • Holding power during market slowdowns
    • Overall debt exposure

    A well-structured loan can give investors time and flexibility, while poor financial planning can force them to sell prematurely.

    Thinking about financing before buying is no longer optional — it is essential.


    Rental Demand Is Becoming a Key Decision Factor

    One of the biggest mistakes many investors made in the past was buying properties without considering who would actually rent the unit.

    Today, buyers are beginning to look more closely at demand drivers such as:

    • Proximity to employment hubs
    • Accessibility and transportation infrastructure
    • Nearby universities or hospitals
    • Tourism demand and short-term rental potential

    In markets like Penang, Kuala Lumpur, and Johor Bahru, rental demand is increasingly shaping investment decisions.

    For example, areas with strong tourism activity or major infrastructure developments may offer better rental prospects compared to purely speculative locations.

    The key question investors should ask is:

    “Who is my tenant?”

    If there is no clear answer, the investment may not perform as expected.


    The Role of Infrastructure and Economic Drivers

    Another important factor influencing property performance today is real economic activity.

    Infrastructure projects, transportation connectivity, employment centres, and tourism growth can significantly impact both rental demand and long-term property value.

    For instance, upcoming transportation developments and urban revitalisation projects in cities such as Georgetown could change demand patterns in the coming years.

    However, infrastructure alone does not guarantee success. The surrounding ecosystem — population growth, business activity, and lifestyle demand — must also support the property market.


    Buying Property Today Requires a Different Mindset

    The Malaysian property market has not disappeared. But the way buyers approach property must evolve.

    Successful investors today tend to follow a more balanced approach:

    • Evaluate rental yield and cash flow
    • Structure financing carefully
    • Understand real demand drivers
    • Focus on long-term sustainability

    In other words, the focus has shifted from short-term speculation to long-term investment discipline.


    A Final Thought

    Property has always been a long-term asset class.

    But in today’s market environment, buying property requires more than just optimism about future price growth.

    It requires careful thinking, realistic financial planning, and a clear understanding of market demand.

    The Malaysian property market has changed.

    The real question is — have buyers changed with it?


    Miichael Yeoh
    Property Strategist | Developer Consultant | HRD Corp Trainer

    Miichael Yeoh has more than 28 years of experience spanning banking, mortgage advisory, property investment, and developer consultancy. He is also the author of Think Like a Banker, Act Like a Player, Property Investment BLT, and Buying Property Like A Pro.

  • What Is OPR in Malaysia and How Does It Affect Housing Loan Interest Rates?

    What Is OPR in Malaysia and How Does It Affect Housing Loan Interest Rates?

    By Miichael Yeoh

    As someone who has spent nearly three decades in banking, mortgage advisory and property strategy, one question I get repeatedly from investors and homebuyers is:

    “Why did my bank increase (or educe) my interest rate when I didn’t change anything?”

    The answer almost always traces back to one key number — the Overnight Policy Rate (OPR).

    Let’s break down how OPR is derived, who decides it, and how it directly affects your housing loan, business financing, and even fixed deposits.


    What Is OPR?

    Bank Negara Malaysia (BNM) uses the Overnight Policy Rate (OPR) as its main monetary policy tool.

    The OPR is the interest rate at which banks lend money to one another overnight. It serves as the benchmark rate that influences all other interest rates in the country.

    Think of it as the “master switch” of Malaysia’s financial system.


    How Is OPR Derived?

    OPR is not randomly adjusted. It is decided by BNM’s Monetary Policy Committee (MPC) based on several key economic indicators:

    1️⃣ Inflation (Price Stability)

    If inflation is rising too quickly, BNM may increase OPR to slow down spending and borrowing.
    If inflation is low or the economy is weak, BNM may reduce OPR to stimulate growth.

    2️⃣ Economic Growth (GDP)

    Strong economic growth may lead to higher OPR to prevent overheating.
    Weak GDP growth may lead to lower OPR to encourage borrowing and investment.

    3️⃣ Employment & Consumer Spending

    High unemployment? Lower OPR to boost activity.
    Strong consumer demand? Possibly tighten policy.

    4️⃣ Global Economic Conditions

    US Federal Reserve rates, global trade trends, currency strength, and geopolitical risks all influence Malaysia’s monetary decisions.

    5️⃣ Financial System Stability

    BNM ensures banks remain liquid and stable. OPR adjustments help manage systemic risk.

    In simple terms:

    OPR balances growth and inflation.


    How OPR Affects Banks’ Interest Rates

    When OPR changes, banks adjust their benchmark rates such as:

    • BR (Base Rate)
    • SBR (Standardised Base Rate)

    Most housing loans today are priced as:

    SBR + Spread (e.g., SBR + 1.5%)

    When OPR increases:

    • SBR increases
    • Monthly instalments increase
    • Loan affordability reduces

    When OPR decreases:

    • SBR decreases
    • Monthly instalments reduce
    • Borrowing becomes cheaper

    Example: How It Impacts a Housing Loan

    Let’s say:

    • Loan: RM500,000
    • Tenure: 35 years
    • Rate: SBR 3.00% + 1.50% = 4.50%

    If OPR increases by 0.25%:

    • SBR may rise to 3.25%
    • New rate becomes 4.75%
    • Monthly instalment increases

    Even a 0.25% increase can mean thousands of ringgit extra over the loan tenure.

    This is why property investors must monitor OPR closely.


    Impact on Different Groups

    🏠 Homeowners

    Higher OPR = higher instalments (if on floating rate).

    🏢 Property Investors

    Rental yield may be squeezed if instalments rise but rental cannot increase proportionally.

    💼 Businesses

    Cost of financing increases, affecting expansion decisions.

    💰 Savers

    Good news — Fixed deposit rates usually improve when OPR rises.


    Why OPR Matters in Property Strategy

    As a developer consultant and property strategist, I always advise clients:

    Don’t only calculate today’s instalment. Stress-test at +1% or +2%.

    Markets move in cycles. OPR will not stay low forever.

    Smart investors:

    • Lock in good spreads during low-rate environments
    • Structure debt efficiently
    • Maintain cash flow buffers

    Final Thoughts

    OPR is not just a technical banking term.

    It is the heartbeat of the financial system, influencing property prices, loan affordability, rental yields, and overall market sentiment.

    Understanding how it works allows you to:

    • Make better borrowing decisions
    • Time property acquisitions strategically
    • Structure financing intelligently

    If you are planning your next property move, always ask:

    “What is the interest rate cycle telling me?”

    Because in property investing,
    Timing and financing strategy often matter more than price.

  • Residential Property & Mortgage Trends in Malaysia (2026 and beyond)

    Residential Property & Mortgage Trends in Malaysia (2026 and beyond)

    By Miichael Yeoh

    The Malaysian property market has been through a lot in the last few years — pandemic, inflation, rising construction costs, slow wage growth, and changing buyer behaviour. But as we step into 2025, one thing is clear:

    Property is still moving… but the market is no longer the same.
    Buyers are more cautious, banks are more selective, and affordability remains a major issue.

    Here’s my take on what’s really happening in the residential property and mortgage landscape, and what you should pay attention to — especially if you’re planning to buy, invest, or restructure your loans.


    📈 Long-Term Price Trend: Property Still Moves Up

    Whether the market is “good” or “bad”, one fact remains consistent:

    Property prices in Malaysia have been rising steadily for the last 20+ years.

    Urban areas like Klang Valley, Penang and Johor consistently show appreciation because of:

    • population growth
    • job concentration
    • infrastructure development
    • scarcity of prime land

    But here’s the catch:
    House prices have risen much faster than income, making affordability the No.1 challenge for Malaysians today.

    This explains why many young buyers are stuck deciding between renting longer… or compromising on location and size.


    🏘️ What’s Happening in the Market Now?

    1. Transaction volume is rising — but buyers are choosy

    2024 recorded strong growth in overall property transactions, and 2025 is projected to see single-digit positive growth.
    People are buying — but not blindly.

    Buyers today compare:

    • price per sq ft
    • rental potential
    • exit value
    • access to MRT / LRT
    • developer reputation

    Gone are the days when anything “new launch” can sell out.
    Today, value matters more than hype.


    💰 Mortgage & Financing Trend: Here’s the Real Story

    The biggest shift recently is OPR dropping to 2.75%, making borrowing cheaper.

    This directly means:

    • Lower monthly instalments
    • Higher loan eligibility
    • Better cashflow for investors

    But with great news comes reality…
    Banks are approving loans more carefully than ever.

    Your CCRIS, CTOS, commitments and even gig-income consistency matter.
    If your financial health is not clean, even a low OPR won’t help you.

    For many Malaysians, the challenge isn’t interest rate — it’s getting the loan approved.


    🧱 Supply vs Demand: The Affordable Gap

    You’re hearing this everywhere:

    “So many houses unsold!”
    —but at the same time—
    “I can’t find any home I can afford!”

    Why?
    Because the overhang is mainly:

    • too expensive for the mass market
    • too big (1,000 sq ft and above)
    • wrong location

    This mismatch will continue unless developers pivot more aggressively into the mid-market segment.


    🧭 What Buyers & Investors Should Look At Now

    ✔️ If you’re a first-time buyer

    This is a golden window.
    Low OPR + many choices + developers offering incentives = value for money.

    Look for:

    • good location > big size
    • future MRT/LRT corridors
    • reputable developers
    • high rental demand areas

    ✔️ If you’re an investor

    Capital gain will still happen — but don’t expect overnight appreciation.
    Focus on:

    • rental yield
    • undervalued areas
    • distress or motivated sellers
    • T.O.P. projects with ready tenants

    The smart investors in 2025 are not speculating.
    They’re buying below market value, or in growth corridors, or early in new infrastructure zones.

    ✔️ If you own multiple properties with loans

    This is the best time to:

    • refinance
    • consolidate debts
    • reset your cashflow
    • restructure your portfolio

    A small adjustment in interest rate can save thousands per year.


    🧩 Conclusion: The Market Isn’t Booming, But It’s Moving

    Malaysia’s residential market today is stable, resilient, and buyer-driven.
    We’re not in a bubble.
    We’re not in a crash.

    We’re in a value-driven market, where the winners are:
    ✔️ informed buyers
    ✔️ strategic investors
    ✔️ those who manage their loans wisely

    If you understand the trends — and you know how to analyse value correctly — 2025-2026 can be a very profitable year for you.

  • 🇲🇾 Malaysia Budget 2026: What Property Buyers and Investors Need to Know

    🇲🇾 Malaysia Budget 2026: What Property Buyers and Investors Need to Know

    By Miichael Yeoh | October 11, 2025

    The Malaysian Budget 2026 was tabled yesterday by Prime Minister and Finance Minister Dato’ Seri Anwar Ibrahim, themed “Memacu Ekonomi MADANI: Memperkasa Rakyat.”

    With a total allocation of RM470 billion, this budget continues the government’s commitment to building a fair and inclusive economy — with property and housing once again taking center stage.

    Here’s my summary and insight on what Budget 2026 means for property buyers, developers, and investors.


    🏡 1. Stamp Duty Exemption Extended for First-Time Buyers

    Good news — the full stamp duty exemption on both the instrument of transfer and loan agreement for first-time buyers remains in place until 31 December 2027.

    This applies to residential properties priced up to RM 500,000.

    👉 What this means:
    If you’re planning to buy your first home, your upfront costs remain much lower. For many young Malaysians, this can be the difference between “maybe later” and “buy now.”


    💰 2. Bigger Housing Loan Guarantee (SJKP Doubled to RM 20 Billion)

    The Housing Credit Guarantee Scheme (SJKP) is being expanded from RM 10 billion to RM 20 billion, expected to help over 80,000 first-time buyers — including self-employed, gig workers, and informal earners.

    👉 What this means:
    Loan approvals should become easier. This is crucial for those who may not have formal payslips but have consistent income — a growing segment of today’s workforce.


    🌍 3. Higher Stamp Duty for Foreign Buyers

    To cool speculative buying, stamp duty for non-citizens and foreign companies buying residential properties will rise from 4% to 8%.

    Permanent residents (PRs) are not affected.

    👉 What this means:
    Foreign investors will likely focus only on premium areas like KLCC, Mont Kiara, and Penang island. For locals, this could mean less competition — and potentially better entry prices.


    🏢 4. Tax Deduction for Converting Commercial Buildings into Homes

    A forward-thinking move — developers who convert old commercial buildings into residential use can now claim a 10% tax deduction (up to RM 10 million) on eligible renovation costs.

    👉 What this means:
    Expect more adaptive reuse projects — turning old offices or malls into apartments or co-living units. This could help rejuvenate urban centers while reducing idle property stock.


    🏠 5. Support for Rent-to-Own (RTO) and Build-Then-Sell (BTS) Schemes

    Banks are encouraged to support RTO and BTS housing models to make ownership easier and reduce project abandonment.

    👉 What this means:
    More flexibility for buyers who can’t yet afford a traditional down payment, and stronger assurance that projects are completed before full payment.


    👨‍💼 6. Higher LPPSA Loan Limit for Civil Servants

    The Public Sector Home Financing Board (LPPSA) limit will increase to RM 1 million in 2026.

    👉 What this means:
    Civil servants can now afford better homes in urban areas without needing multiple loans.


    🧱 7. RM 672 Million for Affordable Housing and Repairs

    The government is allocating RM 672 million for:

    • Affordable homes (Residensi Rakyat, Rumah Mesra Rakyat)
    • Refurbishing old or dilapidated houses
    • Maintenance for low- and medium-cost flats (e.g. lift replacements)

    👉 What this means:
    Positive for social stability and overall living quality. Also good news for contractors and local developers involved in affordable housing.


    ⚙️ 8. Construction and Tax Updates

    • SST on construction services will apply for new contracts from 1 Jan 2026.
    • Carbon tax will begin in stages, affecting material costs (cement, steel).
    • These may slightly raise overall building costs — developers should factor this into pricing.

    🔎 My Insights: What to Watch in 2026

    1. Affordable and Mid-Range Housing
      Remains the government’s priority. Buyers in this segment have strong support — expect steady demand.
    2. Conversion Projects = Hidden Opportunity
      Old commercial spaces could become the next hot residential spots. Developers who act early may gain an edge.
    3. Foreign Demand Softens, Local Focus Strengthens
      With higher duties, foreign demand may dip — but this creates more room for local owner-occupiers and long-term investors.
    4. Construction Cost Pressure
      SST and carbon-related costs might raise project expenses by 3–5%. Efficient developers with strong cash flow will manage better.
    5. Financing Still Key
      Even with incentives, loan approval remains the biggest hurdle. Buyers should prepare documentation properly (income proof, CCRIS record, existing commitments).

    📈 Final Thoughts

    Budget 2026 shows that Malaysia is moving toward a more sustainable and inclusive housing market — one that balances affordability with innovation.

    For homebuyers, it’s a window of opportunity to act while incentives are strong.
    For investors, it’s time to look beyond traditional launches and explore conversion, rental, and co-living strategies.
    And for developers, the message is clear — adapt fast, innovate smart.

    The property market in 2026 will favor those who understand trends early and act strategically.

  • Hot Topics in Malaysia’s 2025 Property Market: What You Need to Know

    Hot Topics in Malaysia’s 2025 Property Market: What You Need to Know

    The Malaysian property market is buzzing with conversations in 2025 as investors, developers, and buyers respond to new trends, policy shifts, and emerging opportunities. From cooling measures to infrastructure-driven growth corridors, the landscape is evolving rapidly. Rising construction costs, industrial and logistics demand, and the spotlight on data centres are just some of the themes shaping discussions today.

    The following are the current hot topics in Malaysia’s property market that every buyer and investor should be aware of:

    1. Residential Market Performance & Price Dynamics

    • House Price Growth Moderating
      Malaysia’s housing price index has been rising, but growth is slowing. For Q4 2024, the national average house price was ~ MYR 483,879, with year-on-year (YoY) growth modest. Global Property Guide
      There were quarter-on-quarter declines in Q4 2024 in many property types (terraced, high-rise, detached, semi-detached) — showing possible short-term corrections or softening. Global Property Guide
    • Regional Price Variations
      • In Penang, average house price remains well above MYR 400,000: about MYR 475,037 in Q4 2024. Global Property Guide
      • Kuala Lumpur is the most expensive, with average ~ MYR 794,467 in Q4 2024. Global Property Guide
      • Other states (e.g. Johor, Selangor) are in between; more affordable housing tends to be further out or in less central locations. Global Property Guide+1
    • Transaction Volume & Supply
      Residential transaction count rose ~4% in 2024 to about 260,516 units; transaction value grew ~5.9 % to ~MYR 106.92 billion. Global Property Guide
      The number of new housing starts rose ~20.6 % in 2024 (for both landed + high-rise) to ~106,236 units; completions rose ~9.7% to ~82,135 units. Global Property Guide
      Also, new planned supply was rising— ~100,461 units in 2024, up ~24.1%. Global Property Guide
    • Overhang / Unsold Stock
      Overhang remains a concern, especially in less premium or lower-value housing. The number of unsold affordable homes has increased. According to Rehda, in 1Q 2025 affordable homes accounted for ~20.7% of unsold residential units. EdgeProp.my
      In Penang, overhang has been showing improvement (decrease in unsold stock) but still persists, especially in certain price bands. Scoop

    2. Developer Sentiment & New Launches

    • Reduced Developer Confidence
      The Rehda survey (1H 2025) shows confidence among developers fell sharply. Only ~19% were optimistic about market prospects mid-2025, down from ~51% six months earlier. EdgeProp.my
      Many developers are being more cautious: ~41% plan new launches in 2H 2025, versus higher rates earlier. Some are not looking to acquire new land because of cost and risk. EdgeProp.my
    • Mismatch of Supply vs Demand (especially “affordable” units)
      A big issue flagged by developers is that many affordable units are being built in locations or at price levels that are not aligned with what local buyers can afford / prefer. Even though lower-priced units tend to have higher demand, their take-up depends heavily on location, amenities, connectivity. EdgeProp.my+1
    • Prime / High-end / Branded Projects Doing Better
      In KL, new launches in “prime” segments are seeing 30-50% take-up rates. Buyers of premium / branded residences (or units in strong locations) are more willing to pay for quality, service, amenities. JLL
      Branded residences are more visible in Penang too (e.g. Marriott Residences at Gurney Drive) reflecting demand (or at least supply) for high-end product. Wikipedia

    3. Commercial, Industrial & Office Sectors

    • Office Vacancy / Demand
      Kuala Lumpur’s office market is recovering: vacancy falling, net absorption positive. For example, KL City saw ~231,392 sq ft net absorption in Q2 2025. Vacancy in KL fell from ~23.6% (Q2 2024) to ~19.2% (Q2 2025). JLL
      Grade A office spaces (those with superior amenities, good location) are better placed; tenants are shifting to better quality buildings. JLL+1
    • Industrial / Logistics / Data Centres Growing Strong
      Demand for industrial space is strong — especially in prime logistics, e-commerce, and supply chain related sectors. In KL / Klang Valley, new supply is being absorbed, and vacancy rates are very low for good quality assets. JLL+1
      The data centre pipeline is large: Malaysia has about 638 MW of capacity completed, ~1,300 MW under construction, and an even larger future pipeline. Investment in this space is seen as strategic. JLL

    4. Government Policy, Taxation & Regulation

    • Budget 2025 Measures
      Budget 2025 includes support for infrastructure, sustainable development, and trying to attract investment in high-value sectors. Real estate/spatial planning tied to ESG / green building is emphasized. JLL
      There’s also focus on more efficient use of land, perhaps more mixed-use zoning or strategic zones. JLL
    • Tax / Fees / Local Levies
      In Penang, for instance, there is proposed quit rent increase (2026) — between ~29% to 200% increase for various land categories. For residential urban land, a hike is less steep; commercial / industrial parcels are more affected. Strata properties may face increases later (from 2027). The Vibes
    • Affordable Housing Policy Pressures
      Developers are required to allocate certain proportions of new developments to affordable housing, but this has led to some unintended consequences: in some cases, these units are in less attractive locations or are priced above what locals can realistically afford. This mismatch leads to slower sales/unsold inventory. EdgeProp.my

    5. Regional Focus: Penang (and Selected States)

    • Overhang Glut Gradually Easing in Penang
      Penang had been among the states with large unsold property inventory. In recent years, unsold units in Penang have reduced (e.g. from ~5,493 in 2021 to ~2,796 in 2024). Scoop
      However, there are still mismatches: properties priced between RM 300,000–500,000 and below are struggling more; high-end (>RM1 million) do better. Location, amenities, connectivity remain critical. Scoop
    • Infrastructure & Transport Matters More
      Projects like the Penang Transport Master Plan (including the Mutiara LRT) are expected to impact property values / demand in areas served. Wikipedia
      Also, improvements like Gurney Bay / Gurney Bay waterfront park are enhancing appeal of coastal / beachfront / high-view precincts in George Town. Wikipedia
    • Local Revenue / Cost Pressures
      The quit rent hike in Penang is being discussed: residents are reacting, especially for commercial / industrial land. This adds to holding costs and might shift developers’ cost calculations. The Vibes
    • High-end / Branded Residences Becoming More Common
      Examples in Penang: Marriott Residences Penang is a new branded residential tower at Gurney Drive. Wikipedia
      The Muze @ PICC is also a large mixed residential project in Bayan Baru with tall towers. Wikipedia

    6. Risks, Headwinds & Constraints

    • Cost Inflation, Construction / Input Costs
      Rising costs for materials, labour shortfalls, logistical challenges (supply chain) are squeezing margins. Developers have less flexibility on pricing vs cost. This trend is being widely reported. EdgeProp.my
    • Financing / Interest Rates
      Borrowing costs, stricter lending criteria, risk of loan rejection are issues especially for buyers of affordable homes. Developer access to finance is also more cautious. EdgeProp.my
    • Unsold Affordable Units Risk
      If many affordable units stay unsold, there is risk of overhang, lower returns for developers, possible depreciation in certain segments. Also risk of price stagnation in non-prime locations. EdgeProp.my+1
    • Regulatory Uncertainty / Local Policy Changes
      Increases in quit rent, possible changes in tax / service tax / sales tax, land use zoning, requirements for affordable housing quotas, etc., create uncertainty. Developers and investors are watching local councils, state governments.
    • Macro / External Risks
      Global supply chain disruptions (especially for industrial / data centre / electronics sectors), geopolitical tensions, input cost volatility, and currency / inflation risk. Also, any downturn in global trade could affect Malaysia’s manufacturing / export sectors (with knock-on effects on property demand, especially for worker housing, industrial real estate).

    7. Opportunities & What to Watch

    • Strategically Located High-Quality / Branded Projects
      Projects with strong amenities, good connectivity (esp. to transit / highways / LRT etc.), high build quality, smart / green features, branded residences — these are likely to command premium pricing and maintain demand.
    • Industrial, Logistics & Data Centres
      Given the global trends (e-commerce, supply chain reshoring, semiconductor investment), Malaysia (especially Penang, Johor, Klang Valley) is seeing growing investor interest in industrial / logistics parks, warehouses, data centre space. These are viewed as relatively defensive assets.
    • Mixed-Use Development & Transit-Oriented Development (TOD)
      Areas around transport infrastructure (LRT, MRT, light rail, major highway nodes) are likely to benefit. Mixed-use developments (residential + retail + office or amenity) that offer a lifestyle component will be attractive.
    • Green / ESG / Sustainability Features
      Buyers / tenants increasingly consider energy efficiency, green certifications, smart home features, environmental impact. Developers incorporating these will have competitive advantage.
    • Government Incentives & Zone Designations
      Investment zones, special economic zones, incentives in Budget 2025, tax breaks (where available), and government infrastructure spending (transport, utilities) are going to influence property hot spots.
    • Price Correction / Buyer Power
      For savvy buyers, there might be opportunities: slower demand in non-prime sectors, more incentive packages by developers, better negotiations (price, furnishing, perks) especially in properties that are not moving quickly.

    Conclusion

    Malaysia’s property market in 2025 is at a turning point, balancing between growth opportunities and structural challenges. While affordability and regulatory changes continue to test both developers and buyers, new catalysts such as data centres, logistics demand, and large-scale infrastructure projects are reshaping the landscape.

    For investors, the key lies in identifying which segments offer long-term resilience and value. For homeowners, understanding how policies, costs, and location trends play out will make all the difference. Ultimately, the hot topics of today are shaping the strategies, risks, and rewards of tomorrow’s property market.

    From the Desk of

    Miichael Yeoh