Tag: RealEstateMalaysia

  • Is Now a Good Time to Buy Property in Malaysia ?

    Is Now a Good Time to Buy Property in Malaysia ?

    Everyone wants to know whether property prices will rise or fall.

    But that’s not the question I would ask before buying a property.

    The better question is:

    “Is this the right property, at the right price, with the right financing, for my situation?”

    Because even if the market rises next year, you can still make a bad property decision today.

    And even if prices fall, waiting doesn’t automatically mean you will get a better deal.

    So, is 2026 a good time to buy property in Malaysia?

    My answer: It can be — but only if you stop trying to predict the market and start discovering the numbers behind the decision.


    What Is Actually Happening in the Malaysian Property Market?

    Let’s start with the facts.

    Malaysia’s property market remained resilient in the first half of 2026, recording 187,320 transactions worth RM105.12 billion. The market was supported by relatively stable transaction activity, prices and construction activity.

    At the same time, the market isn’t booming across every segment.

    Residential transactions in H1 2026 were 110,998, accounting for 59.3% of total property transactions. Completed unsold residential units increased to 33,094 units, worth about RM17.78 billion.

    That tells us something important.

    The market isn’t simply “good” or “bad”.

    There are areas of strength.

    There are areas of oversupply.

    There are properties with genuine demand.

    And there are properties that developers are struggling to sell.

    This is exactly why buyers need to become more selective.

    What About Interest Rates?

    This is probably one of the first things buyers look at.

    And understandably so.

    Bank Negara Malaysia has maintained the Overnight Policy Rate (OPR) at 2.75% throughout 2026, including its latest decision on 3 September 2026.

    That provides a relatively stable financing environment compared with periods of rapidly changing interest rates.

    But here’s where I think many buyers make a mistake.

    They see a stable or lower interest-rate environment and immediately think:

    “Good. Time to buy.”

    Not necessarily.

    The interest rate is one variable in your property decision.

    It is not the decision.

    A property that is overpriced by RM100,000 doesn’t suddenly become a good investment because your mortgage rate is slightly lower.


    Should You Wait for Property Prices to Fall?
    This is probably the question I hear most often.

    And it sounds logical.

    “If prices are going to fall, I’ll wait.”

    But there are two problems with this strategy.

    First, nobody knows exactly when prices will fall.

    And more importantly:

    Second, even if prices fall, you may not benefit.

    Why?

    Because the property you want may not fall.

    The bank may tighten lending.

    Your income may change.

    Interest rates may move.

    The developer may remove incentives.

    Another buyer may take the unit you wanted.

    Or the market may simply remain stable for several years.

    Waiting is not a neutral decision.

    Waiting is also a property decision.


    The Bigger Question: What Are You Actually Buying?

    This is where I believe buyers need to change their thinking.

    Don’t ask only:

    “Will property prices go up?”

    Ask:

    “What is creating the demand for this property?”

    Is it:

    • population growth?
    • new jobs?
    • infrastructure?
    • universities?
    • industrial development?
    • tourism?
    • rental demand?
    • limited land supply?
    • better connectivity?
    • genuine owner-occupier demand?

    Or is the main attraction simply:

    “The developer says prices will increase.”

    Those are very different things.


    5 Things I Would Check Before Buying Property
    1. Can You Actually Afford It?

    This sounds obvious.

    But affordability isn’t simply:

    “The bank approved my loan.”

    A bank’s approval tells you what the bank is prepared to lend.

    It doesn’t tell you what you should comfortably borrow.

    Before buying, calculate the full monthly cost:

    • mortgage instalment
    • maintenance fee
    • sinking fund
    • assessment
    • quit rent
    • insurance
    • utilities
    • repairs
    • furnishing
    • parking
    • transportation
    • other existing commitments

    Then ask:

    “If my income stays the same for the next three years, will this property still feel comfortable?”

    That’s a much better question than:

    “How much can the bank approve?”


    2. Is the Price Supported by the Market?

    Don’t fall in love with the launch price.

    Find out what similar properties are actually transacting for.

    NAPIC provides transaction, price, rental and property-market data, including state and district-level information.

    Compare:

    Asking price vs actual transaction price.

    Then compare:

    RM per sq ft vs comparable properties.

    Then ask:

    “What am I paying a premium for?”

    If the answer is simply:

    “Because this is a new launch.”

    That’s not enough.


    3. Is There Real Demand?

    A beautiful building isn’t demand.

    A famous developer isn’t demand.

    A fantastic showroom isn’t demand.

    Demand comes from people who genuinely want to live, work, rent or invest in that location.

    Ask:

    • Who is going to live here?
    • Who is going to rent here?
    • Where do these people work?
    • Why would they choose this location?
    • What alternatives do they have?
    • What competing projects are coming?

    This becomes particularly important when a market has significant unsold stock.

    Malaysia’s completed unsold residential inventory rose to 33,094 units in H1 2026.

    That doesn’t mean all property is bad.

    It means product selection matters.


    4. What Happens When More Supply Arrives?

    This is one of the most overlooked questions in property investing.

    Imagine you buy a condominium because the current rental demand looks excellent.

    But three years later, five more projects are completed nearby.

    Now you have thousands of competing units.

    Your tenant has choices.

    Your rental growth may slow.

    Your vacancy risk may increase.

    And when you eventually want to sell, you’re no longer competing only against today’s properties.

    You’re competing against tomorrow’s properties.

    That’s why I always tell buyers:

    Don’t just study the property. Study what is coming around the property.


    5. What’s Your Exit Strategy?

    This is perhaps the biggest difference between a home purchase and an investment purchase.

    A homeowner may be happy because:

    “I love the location.”

    An investor needs another question:

    “Who will buy this from me later?”

    Think about your exit before your entry.

    If you need to sell in five or ten years:

    • Who is your future buyer?
    • What will they be looking for?
    • What competing supply will exist?
    • Will your property still be relevant?
    • Will your price be affordable to the next buyer?
    • Will the rental market support your valuation?

    You don’t realise your investment return when you buy.

    You realise it when you eventually exit.


    So… Is 2026/2027 a Good Time to Buy Property?

    Here’s my answer.

    Yes — if you’re buying based on fundamentals.

    No — if you’re buying simply because you believe prices must go up.

    The Malaysian property market in 2026 is resilient, but the data also shows why buyers cannot treat the entire market as one big opportunity.

    Transaction activity remains substantial.

    Interest rates are relatively stable.

    But residential demand is uneven, completed unsold stock has increased, and affordability remains an important constraint.

    That creates an interesting environment.

    It may actually be a better time to be a selective buyer than an emotional buyer.

    You don’t necessarily need to wait for a market crash.

    You need to find the property where:

    Price + Location + Demand + Financing + Supply + Exit

    all make sense together.


    The PDS 7-Question Property Test

    Before I buy any property, I would want to answer these seven questions:

    1. Why this property?

    What problem does it solve?

    2. Why this location?

    What is creating sustainable demand?

    3. Why this price?

    What evidence supports the valuation?

    4. Who is the future buyer or tenant?

    Where does the demand come from?

    5. What competition is coming?

    What could affect rental and resale demand?

    6. Can I comfortably hold it?

    Not just today — but through different market conditions.

    7. How do I eventually exit?

    Who will buy it from me?

    If you can’t answer these questions, perhaps you are not ready to buy.

    And that’s okay.

    Not buying is sometimes a better decision than buying the wrong property.


    The Real Question Isn’t “When Should I Buy?”

    After more than two decades around banking, mortgages, property and investment decisions, I’ve learned that buyers often spend too much time trying to predict the market.

    The smarter approach is to understand the decision.

    You don’t need to know exactly where property prices will be five years from now.

    You need to understand why the property you’re considering should still have demand five years from now.

    That’s a very different way of looking at property.

    And it is the philosophy behind the Property Discovery System™.

    Don’t just ask whether now is a good time to buy.

    Discover whether this is the right property for you.

    Discover Better. Decide Smarter.

    Miichael Yeoh

    Property Strategist
  • Before You Buy Property, Do This First — Or You’re Just Guessing

    Before You Buy Property, Do This First — Or You’re Just Guessing

    Smart Investors Don’t Start With Property — They Start With Demand

    Most people think property investment starts with:

    Location.
    Price.
    Developer.

    It doesn’t.

    It starts with a much more fundamental question:

    Are you buying for own use… or for investment?

    Because if you get this wrong, everything else becomes noise.


    Step 1: Define Your Purpose (No Grey Area)

    I’ve seen buyers say they are investing…

    But make decisions based on:

    • Design
    • Lifestyle
    • Personal preference

    That’s not investing.

    That’s emotion.

    If it’s own stay, you follow your lifestyle.

    If it’s investment, you follow demand and numbers.


    Step 2: Know Your Budget (This Sets Your Playing Field)

    Before anything else:

    • What is your true affordability?
    • What is your financing capacity?
    • What is your holding strength?

    Because in property:

    You don’t lose money when you buy wrong.
    You lose money when you can’t hold.

    Especially for investors—cash flow and holding power are everything.


    Step 3: Real Investors Do One Thing Differently — They RESEARCH

    This is the biggest gap in the market.

    Most buyers rely on:

    • Marketing materials
    • Sales narratives
    • “Good location” claims

    But experienced investors?

    They study the market before they commit.


    What Do You Actually Research?

    1. Demand & Demographics (The Real Starting Point)

    Forget the building first.

    Ask:

    Who is the end user of this property?

    • Young professionals?
    • Families?
    • Tourists?
    • Businesses?

    If you don’t understand demand,
    you’re not investing—you’re guessing.


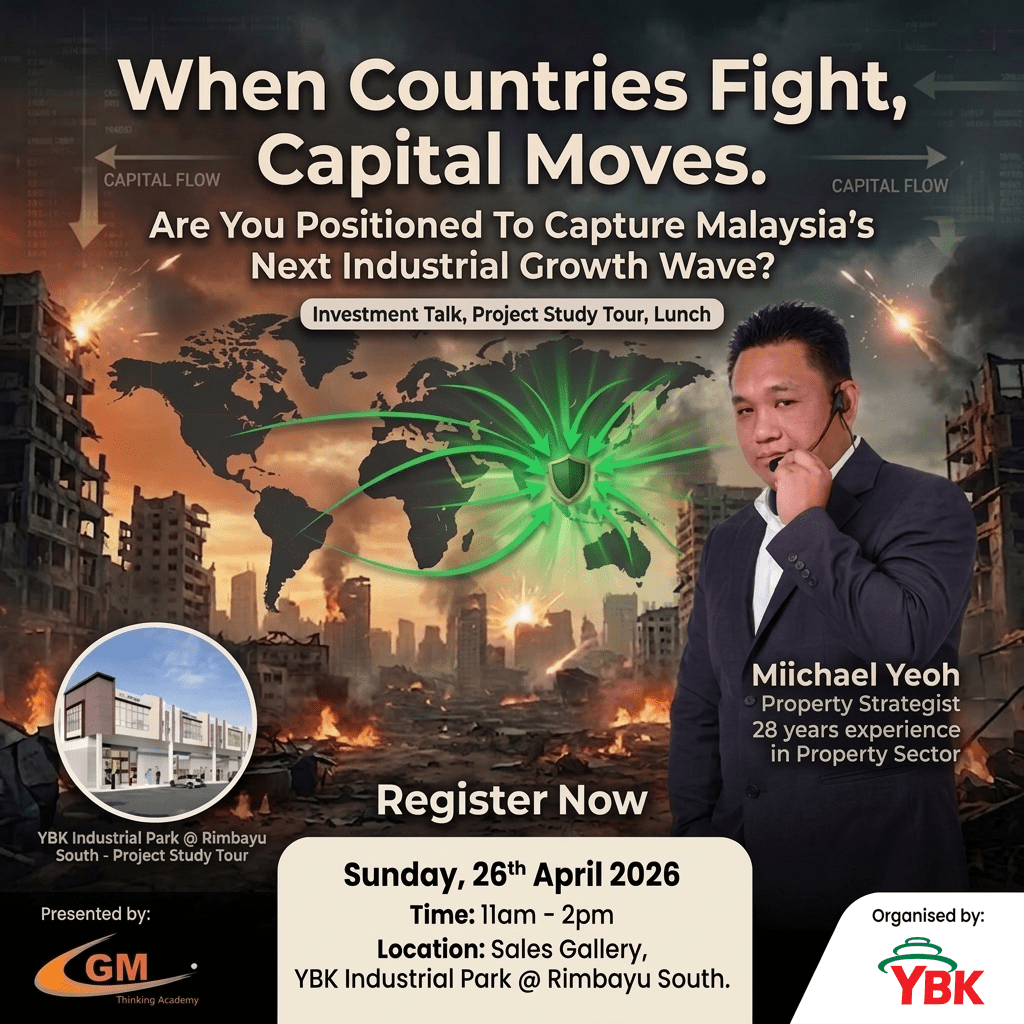
    And This Is Where Industrial Property Becomes Interesting

    For big-budget investors, the shift is already happening.

    Demand is no longer driven by lifestyle.

    It’s driven by business movement and capital flow.

    Look at what’s happening:

    • Manufacturing relocation into Malaysia
    • Growth in logistics and warehousing
    • E-commerce expansion
    • Supply chain restructuring across ASEAN

    This creates a different type of demand:

    • Larger space requirements
    • Functional layouts over aesthetics
    • Accessibility to ports, highways, and labour
    • Long-term tenancy from businesses (not individuals)

    In other words:

    Industrial demand is economic-driven, not sentiment-driven.

    And that’s exactly what sophisticated investors are looking for.


    2. Price Per Square Foot (Entry Determines Exit)

    You make money when you buy right.

    Compare:

    • Nearby transactions
    • Competing projects
    • Replacement cost

    If you enter too high, your upside is already limited.


    3. Surrounding Supply (The Silent Risk)

    Most investors ignore this.

    But supply determines:

    • Rental pressure
    • Vacancy risk
    • Exit liquidity

    Too much incoming supply?

    Even a “good project” can underperform.


    4. Infrastructure & Connectivity (Follow the Growth)

    No area grows randomly.

    Growth follows:

    • Highways
    • Ports
    • Rail (LRT / MRT / logistics links)
    • Industrial corridors

    If infrastructure is expanding, demand usually follows.


    5. Rental & Yield Reality Check

    At the end of the day:

    Can it generate income?

    • What is the realistic rental?
    • Who is the tenant profile?
    • What is the occupancy expectation?

    If the numbers don’t work on paper,
    don’t rely on hope.


    What I’ve Learned From the Ground

    After evaluating multiple projects and markets, one thing is clear:

    The winners are not those who buy the most.
    The winners are those who understand demand the best.

    Every property I consider goes through:

    • Demand validation
    • Market comparison
    • Supply analysis
    • Financial assessment

    Because once you commit,
    you’re not just buying property…

    You’re locking in a decision for years.


    Final Thought

    Property investment has evolved.

    It’s no longer about chasing what’s popular.

    It’s about understanding why demand exists—and where it’s going next.

    Those who do the work will always have an edge.

    Those who don’t…

    Will always be reacting.


    Disclaimer: This reflects the author’s personal views based on market experience and current observations. It is not financial advice. Smart investors do their own research before making any move.

    From the Desk of

    Miichael Yeoh

  • How AI Is Reshaping the Way We Buy Property

    How AI Is Reshaping the Way We Buy Property

    In today’s digital world, buying property is no longer just about location, price, and site visits. Artificial Intelligence (AI) is quietly influencing how buyers think, search, and eventually make decisions.

    Whether you realize it or not, AI is already part of your property journey.


    1. How AI Affects Our Buying Decisions

    AI has changed the way we consume information.

    In the past, buyers relied on agents, brochures, and physical visits. Today, what you see online is curated based on your behavior:

    • What you search
    • What you click
    • What you watch

    Over time, AI builds a profile of your preferences and starts feeding you properties that match your interest.

    Many buyers feel like they “found” the property themselves.

    But in reality, AI has already filtered the options for you.


    2. Property Marketing vs Other Products — Same Model, Different Weight

    From my experience, property marketing is not very different from other products.

    It follows a similar digital marketing structure.

    But the difference is this:

    👉 Property is a high-value, long-term commitment

    You are not buying something for RM1. You are committing hundreds of thousands or even millions.

    Because of that, the marketing is designed to:

    • Build trust
    • Educate
    • Reassure
    • Reduce risk

    It is less about pushing a sale, and more about guiding a decision.


    3. The Sales Funnel Is Always There

    Every product follows a sales funnel.

    Some marketers execute it well. Some only do part of it. Some only focus on getting attention.

    In property, you will typically go through stages like:

    • Seeing ads
    • Clicking to learn more
    • Registering interest
    • Communicating with salespeople
    • Visiting or evaluating

    Whether you notice it or not, you are being guided step by step.


    4. “Why Am I Suddenly Seeing Property Ads Everywhere?”

    This is something many people experience.

    You talk to a friend about buying property… You search a few listings…

    Next thing you know, when you open Facebook or Instagram:

    👉 Property ads start appearing everywhere.

    This is how AI and digital tracking work.

    It picks up signals from your behavior and starts showing you more relevant content.

    It is not magic — it is data.


    5. The Moment You Click, Your Journey Changes

    Once you click on an ad, your journey becomes more intentional.

    You may start seeing:

    • More related ads
    • Follow-up messages
    • Invitations to previews
    • Additional information and content

    This is how modern property marketing works today.


    6. Not All Campaigns Are the Same

    The experience you get depends on the developer or salesperson.

    Some are very basic. Some are more structured and consistent.

    But regardless of how advanced the system is, one thing remains the same:

    👉 The final decision is still yours.


    7. My Perspective as a Property Buyer

    From my own experience in property, one thing is very clear:

    👉 We cannot avoid AI.

    It is already part of how information is delivered to us.

    But here is the part many people overlook:

    AI can influence your interest, but it should not replace your judgment.

    At the end of the day:

    • You are not buying a cheap product
    • You are committing significant capital
    • You are making a long-term financial decision

    Because of that, buyers must still:

    ✔ Do proper research ✔ Understand the numbers ✔ Assess their holding power ✔ Evaluate the location and fundamentals

    And most importantly:

    👉 Listen to people who have real experience in property

    Not everything online tells the full story.


    Final Thoughts

    AI is a powerful tool.

    It can help you discover opportunities faster. It can guide you through options you may not have seen before.

    But it should never replace:

    • Due diligence
    • Critical thinking
    • Experience-based advice

    In property, the difference between a good decision and a bad one is not the advertisement you saw…

    It is the quality of the decision you make after that.

    At the end of the day, AI may influence what you see…

    But it should never replace how you think.

    Property is not a small purchase.
    It’s a long-term financial commitment.

    The difference is not in the advertisement you saw —
    It’s in the decision you make after that.

    Make sure it’s a well-informed one

    From the Desk of

    Miichael Yeoh

    Property Strategist | Author

    Author of:

    Think Like a Banker, Act Like a Player

    Property Investment BLT Buying

    Property Like a Pro (MPH Bestseller)

    P.S. Follow for consistent, experience-based property insights — beyond what marketing tells you.

  • Penang LRT Update: What Property Buyers and Investors Should Know

    Penang LRT Update: What Property Buyers and Investors Should Know

    For years, the lack of rail transit has been one of the biggest infrastructure gaps in Penang. While cities like Kuala Lumpur have extensive rail networks, Penang has relied heavily on cars and buses.

    That is now changing.

    The Penang Light Rail Transit (LRT) project — known as the Mutiara Line — is officially underway, marking one of the largest infrastructure developments in northern Malaysia. For property buyers and investors, this project will reshape accessibility, mobility, and potentially property values across key corridors in Penang.

    In this article, we explore the latest updates on the Penang LRT and what it means for the property market.


    1. Overview of the Penang LRT (Mutiara Line)

    The Mutiara Line will be Penang’s first urban rail system and the first LRT outside the Klang Valley. It forms a key component of the Penang Transport Master Plan (PTMP) aimed at improving connectivity across the island and mainland.

    Key facts about the project:

    • Length: approximately 29.5 km
    • Stations: about 21 stations
    • Type: elevated light rail system
    • Estimated cost: about RM16–17 billion
    • Target completion: around 2031

    The line will connect Silicon Island / Penang South Reclamation area to Penang Sentral, passing through major areas such as:

    • Bayan Lepas
    • Sungai Tiram
    • Gelugor
    • Jelutong
    • George Town (Komtar)

    It will also link with Penang Sentral, providing connections to ETS, KTM Komuter and ferry services.

    This integration is designed to create a seamless transport system between Penang Island and Seberang Perai.


    2. Latest Construction Updates (2025–2026)

    Recent developments show that the project has moved from planning into active implementation.

    Penang projects powering ahead

    Important milestones include:

    Construction has begun
    The first phase of works started in 2025, with contractors appointed and preliminary works such as soil investigations and site preparation underway.

    Major works expanding in 2026
    Construction activity is expected to intensify throughout 2026, including elevated track construction and station development.

    Traffic diversions already in place
    Road diversions along areas such as Jalan Sultan Azlan Shah near Bayan Lepas have begun to accommodate construction works that may last up to 38 months.

    Public inspection of revised rail scheme
    Authorities have also opened a public inspection period for revised plans, including a proposed cross-sea link to Penang Sentral, which will strengthen connectivity between the island and mainland.


    3. Why the LRT Matters for the Property Market

    Infrastructure has always played a major role in shaping property values.

    Based on experiences in Kuala Lumpur, rail transit typically creates three types of property impact.

    1️⃣ Transit-Oriented Development (TOD)

    Properties located near LRT stations tend to see increased demand due to convenience and connectivity.

    Areas expected to benefit include:

    • Bayan Lepas
    • Sungai Nibong
    • Gelugor
    • Jelutong
    • Komtar / George Town

    These areas could evolve into future TOD zones, attracting both residential and commercial developments.


    2️⃣ Improved Accessibility

    Currently, travelling from Bayan Lepas to George Town during peak hours can take more than an hour.

    With the LRT:

    • Travel time could be significantly reduced
    • Workers in the Bayan Lepas industrial zone gain easier access to the city
    • Tourism and business mobility improve

    Better connectivity often leads to stronger rental demand.


    3️⃣ Long-Term Economic Growth

    The LRT is not just a transport project. It is also a strategic economic infrastructure designed to support:

    • Silicon Island development
    • the Bayan Lepas industrial hub
    • tourism in George Town
    • cross-strait connectivity with mainland Penang

    Large infrastructure projects tend to stimulate surrounding investments and commercial activity.


    4. A Strategic Perspective for Property Buyers

    However, buying property purely because it is near an LRT station is not enough.

    From an investment perspective, buyers should still analyse:

    • Rental demand around the station
    • Employment nodes nearby
    • Supply of new developments
    • Holding power during construction years

    The Penang LRT is expected to complete around 2031, meaning property investors must adopt a long-term view rather than short-term speculation.


    Final Thoughts

    The Penang LRT has been discussed for more than a decade. Now that construction has begun, the project is moving from concept to reality.

    For Penang, the LRT represents more than just a transport system — it is a structural shift in how the city grows and how people move.

    For property buyers and investors, the key question is no longer whether the LRT will happen.

    The real question is:

    Are you positioning your property decisions ahead of this infrastructure transformation?


    Written by:
    Miichael Yeoh
    Property Strategist | Developer Consultant | Investment & Mortgage


    References

    1. MRT Corp – Mutiara Line Project Information
    2. Bernama – Penang LRT construction update
    3. The Star / Penang infrastructure updates
    4. Malay Mail / Infrastructure reports on LRT cost and timeline
    5. Wikipedia – Mutiara Line LRT project overview
  • Think Like a Banker Before You Buy Property

    Think Like a Banker Before You Buy Property

    One thing I learned from working closely with banks is this:

    Banks are extremely careful before approving a property loan.

    They analyse risks, stress-test your finances, and study whether you can survive difficult situations.

    But here’s the irony.

    Many property buyers don’t analyse their purchase the same way.

    They look at the show unit.
    They listen to marketing promises.
    They follow what others are buying.

    But they rarely ask the same questions a banker would ask.

    If you want to invest in property wisely, start by thinking like a banker.

    Here are three things bankers always analyse.


    1️⃣ Debt Ratio – Are You Stretching Yourself Too Thin?

    Banks look closely at your Debt Service Ratio (DSR).

    This measures how much of your income is used to pay debts.

    Even if a bank approves your loan, you should still ask yourself:

    • What happens if interest rates increase?
    • What if my income drops temporarily?
    • Will I still feel comfortable servicing the loan?

    A property might look affordable today.

    But bankers always plan for tomorrow’s risks.


    2️⃣ Holding Power – Can You Hold Through Market Cycles?

    Property markets don’t always go up.

    There will be slow periods.

    Bankers evaluate whether a borrower has the financial strength to continue paying during tough times.

    Smart investors should ask:

    • Can I hold this property for 5–10 years if needed?
    • Do I have cash reserves?
    • What if the market takes longer to recover?

    Many investors fail not because they bought the wrong property…

    They fail because they cannot hold it long enough.


    3️⃣ Rental Sustainability – Can the Property Support Itself?

    Another banker mindset is income sustainability.

    Before buying, ask:

    • Is there real rental demand here?
    • Who are the potential tenants?
    • Can the rental help support the loan?

    A strong investment property should ideally generate rental income that supports part of the financing.

    This reduces pressure and improves long-term stability.


    Final Thought

    Successful property investors don’t buy emotionally.

    They evaluate property like a banker evaluating risk.

    Before your next purchase, ask yourself:

    Does this property pass the banker’s test?

    When you start thinking like a banker, you don’t just buy property.

    You build a stronger and safer property portfolio.


    Miichael Yeoh
    Property Strategist | Developer Consultant | Investment & Mortgage Expert
    Author of Think Like a Banker, Act Like a Player

  • Before You Buy Any Property, Run It Through This Simple Checklist

    Before You Buy Any Property, Run It Through This Simple Checklist

    Most property mistakes don’t happen after you buy.
    They happen before you sign.

    Over the years — working in banks, speaking on stages, and educating buyers and investors — I’ve noticed one consistent pattern:

    People buy property based on emotion, marketing, or price,
    instead of structure, numbers, and risk.

    Good property decisions are rarely accidental.
    They are the result of asking the right questions early.

    Let me show you the checklist I personally use — and teach — before anyone commits to a property purchase.


    1. Start With the Right Question (Not “Can I Buy?”)

    The wrong question is:

    “Can I get a loan?”

    The better question is:

    “Is this property right for me?”

    Before you look at projects, promotions, or discounts, be clear on your purpose:

    • Are you buying for own stay, rental income, or long-term growth?
    • Do you want monthly stability, future upside, or both?
    • How long are you prepared to hold this property?

    A good property for someone else can be a bad property for you.

    Clarity always comes before commitment.


    2. Understand Your Financial Comfort Zone

    Many buyers confuse approval with affordability.

    Just because you can commit, doesn’t mean you should.

    Before buying, be honest about:

    • Your monthly commitments after purchase
    • Your buffer if interest rates rise or income changes
    • Whether the property adds pressure or flexibility to your life

    A simple rule I often share:

    If a property causes stress from Day One, it’s already a bad decision.

    Property should support your long-term plan — not trap you in it.


    3. Protect Yourself Before You Celebrate

    Buying property is not just about price and location.
    It’s about rights, responsibilities, and clarity.

    Before you sign anything, make sure you understand:

    • What you truly own
    • Any conditions or restrictions attached to the property
    • Your obligations now and in the future
    • What happens if things don’t go according to plan

    Many buyers only realise what they signed after problems arise.
    By then, it’s often too late.

    Confidence comes from understanding — not assumptions.


    4. Look at the Real Cost, Not Just the Purchase Price

    The purchase price is only the beginning.

    You need to consider:

    • All upfront costs
    • Ongoing holding expenses
    • The impact of rental income on your overall finances
    • What you walk away with — not just what comes in

    A property that looks attractive on paper can disappoint once all costs are considered.

    Smart buyers focus on net outcome, not headline numbers.


    5. Evaluate the Property Like an Investor, Even If You’re Not One

    Even if you’re buying for own stay, think ahead.

    Ask yourself:

    • Who else would want this property in the future?
    • Is supply increasing in this area?
    • Are rental expectations realistic?
    • If you needed to sell, who would be your buyer?

    Hope is not a strategy.
    Every property should have a clear future story.


    6. A Simple Yes / No Filter I Personally Use

    Before I say yes to any property, I run through this:

    • ✅ Does this make sense financially over time?
    • ✅ Do I fully understand what I’m committing to?
    • ✅ Am I comfortable holding this through different market cycles?
    • ✅ Does this fit my life plan — not just today, but later?
    • ✅ Do I have flexibility if things change?

    If any answer is No, I pause.

    Property rewards patience far more than pressure.


    Final Thought: Learn First, Buy Second

    Property is not about buying fast or buying early.
    It’s about buying wisely.

    Too many people buy first — and learn later.
    The cost of that mistake can last decades.

    That’s why I believe education must always come before action.

    When you understand the decision fully, confidence follows naturally.

    And confident buyers make better property decisions — every time.

    From the desk of

    Miichael Yeoh

  • Hot Topics in Malaysia’s 2025 Property Market: What You Need to Know

    Hot Topics in Malaysia’s 2025 Property Market: What You Need to Know

    The Malaysian property market is buzzing with conversations in 2025 as investors, developers, and buyers respond to new trends, policy shifts, and emerging opportunities. From cooling measures to infrastructure-driven growth corridors, the landscape is evolving rapidly. Rising construction costs, industrial and logistics demand, and the spotlight on data centres are just some of the themes shaping discussions today.

    The following are the current hot topics in Malaysia’s property market that every buyer and investor should be aware of:

    1. Residential Market Performance & Price Dynamics

    • House Price Growth Moderating
      Malaysia’s housing price index has been rising, but growth is slowing. For Q4 2024, the national average house price was ~ MYR 483,879, with year-on-year (YoY) growth modest. Global Property Guide
      There were quarter-on-quarter declines in Q4 2024 in many property types (terraced, high-rise, detached, semi-detached) — showing possible short-term corrections or softening. Global Property Guide
    • Regional Price Variations
      • In Penang, average house price remains well above MYR 400,000: about MYR 475,037 in Q4 2024. Global Property Guide
      • Kuala Lumpur is the most expensive, with average ~ MYR 794,467 in Q4 2024. Global Property Guide
      • Other states (e.g. Johor, Selangor) are in between; more affordable housing tends to be further out or in less central locations. Global Property Guide+1
    • Transaction Volume & Supply
      Residential transaction count rose ~4% in 2024 to about 260,516 units; transaction value grew ~5.9 % to ~MYR 106.92 billion. Global Property Guide
      The number of new housing starts rose ~20.6 % in 2024 (for both landed + high-rise) to ~106,236 units; completions rose ~9.7% to ~82,135 units. Global Property Guide
      Also, new planned supply was rising— ~100,461 units in 2024, up ~24.1%. Global Property Guide
    • Overhang / Unsold Stock
      Overhang remains a concern, especially in less premium or lower-value housing. The number of unsold affordable homes has increased. According to Rehda, in 1Q 2025 affordable homes accounted for ~20.7% of unsold residential units. EdgeProp.my
      In Penang, overhang has been showing improvement (decrease in unsold stock) but still persists, especially in certain price bands. Scoop

    2. Developer Sentiment & New Launches

    • Reduced Developer Confidence
      The Rehda survey (1H 2025) shows confidence among developers fell sharply. Only ~19% were optimistic about market prospects mid-2025, down from ~51% six months earlier. EdgeProp.my
      Many developers are being more cautious: ~41% plan new launches in 2H 2025, versus higher rates earlier. Some are not looking to acquire new land because of cost and risk. EdgeProp.my
    • Mismatch of Supply vs Demand (especially “affordable” units)
      A big issue flagged by developers is that many affordable units are being built in locations or at price levels that are not aligned with what local buyers can afford / prefer. Even though lower-priced units tend to have higher demand, their take-up depends heavily on location, amenities, connectivity. EdgeProp.my+1
    • Prime / High-end / Branded Projects Doing Better
      In KL, new launches in “prime” segments are seeing 30-50% take-up rates. Buyers of premium / branded residences (or units in strong locations) are more willing to pay for quality, service, amenities. JLL
      Branded residences are more visible in Penang too (e.g. Marriott Residences at Gurney Drive) reflecting demand (or at least supply) for high-end product. Wikipedia

    3. Commercial, Industrial & Office Sectors

    • Office Vacancy / Demand
      Kuala Lumpur’s office market is recovering: vacancy falling, net absorption positive. For example, KL City saw ~231,392 sq ft net absorption in Q2 2025. Vacancy in KL fell from ~23.6% (Q2 2024) to ~19.2% (Q2 2025). JLL
      Grade A office spaces (those with superior amenities, good location) are better placed; tenants are shifting to better quality buildings. JLL+1
    • Industrial / Logistics / Data Centres Growing Strong
      Demand for industrial space is strong — especially in prime logistics, e-commerce, and supply chain related sectors. In KL / Klang Valley, new supply is being absorbed, and vacancy rates are very low for good quality assets. JLL+1
      The data centre pipeline is large: Malaysia has about 638 MW of capacity completed, ~1,300 MW under construction, and an even larger future pipeline. Investment in this space is seen as strategic. JLL

    4. Government Policy, Taxation & Regulation

    • Budget 2025 Measures
      Budget 2025 includes support for infrastructure, sustainable development, and trying to attract investment in high-value sectors. Real estate/spatial planning tied to ESG / green building is emphasized. JLL
      There’s also focus on more efficient use of land, perhaps more mixed-use zoning or strategic zones. JLL
    • Tax / Fees / Local Levies
      In Penang, for instance, there is proposed quit rent increase (2026) — between ~29% to 200% increase for various land categories. For residential urban land, a hike is less steep; commercial / industrial parcels are more affected. Strata properties may face increases later (from 2027). The Vibes
    • Affordable Housing Policy Pressures
      Developers are required to allocate certain proportions of new developments to affordable housing, but this has led to some unintended consequences: in some cases, these units are in less attractive locations or are priced above what locals can realistically afford. This mismatch leads to slower sales/unsold inventory. EdgeProp.my

    5. Regional Focus: Penang (and Selected States)

    • Overhang Glut Gradually Easing in Penang
      Penang had been among the states with large unsold property inventory. In recent years, unsold units in Penang have reduced (e.g. from ~5,493 in 2021 to ~2,796 in 2024). Scoop
      However, there are still mismatches: properties priced between RM 300,000–500,000 and below are struggling more; high-end (>RM1 million) do better. Location, amenities, connectivity remain critical. Scoop
    • Infrastructure & Transport Matters More
      Projects like the Penang Transport Master Plan (including the Mutiara LRT) are expected to impact property values / demand in areas served. Wikipedia
      Also, improvements like Gurney Bay / Gurney Bay waterfront park are enhancing appeal of coastal / beachfront / high-view precincts in George Town. Wikipedia
    • Local Revenue / Cost Pressures
      The quit rent hike in Penang is being discussed: residents are reacting, especially for commercial / industrial land. This adds to holding costs and might shift developers’ cost calculations. The Vibes
    • High-end / Branded Residences Becoming More Common
      Examples in Penang: Marriott Residences Penang is a new branded residential tower at Gurney Drive. Wikipedia
      The Muze @ PICC is also a large mixed residential project in Bayan Baru with tall towers. Wikipedia

    6. Risks, Headwinds & Constraints

    • Cost Inflation, Construction / Input Costs
      Rising costs for materials, labour shortfalls, logistical challenges (supply chain) are squeezing margins. Developers have less flexibility on pricing vs cost. This trend is being widely reported. EdgeProp.my
    • Financing / Interest Rates
      Borrowing costs, stricter lending criteria, risk of loan rejection are issues especially for buyers of affordable homes. Developer access to finance is also more cautious. EdgeProp.my
    • Unsold Affordable Units Risk
      If many affordable units stay unsold, there is risk of overhang, lower returns for developers, possible depreciation in certain segments. Also risk of price stagnation in non-prime locations. EdgeProp.my+1
    • Regulatory Uncertainty / Local Policy Changes
      Increases in quit rent, possible changes in tax / service tax / sales tax, land use zoning, requirements for affordable housing quotas, etc., create uncertainty. Developers and investors are watching local councils, state governments.
    • Macro / External Risks
      Global supply chain disruptions (especially for industrial / data centre / electronics sectors), geopolitical tensions, input cost volatility, and currency / inflation risk. Also, any downturn in global trade could affect Malaysia’s manufacturing / export sectors (with knock-on effects on property demand, especially for worker housing, industrial real estate).

    7. Opportunities & What to Watch

    • Strategically Located High-Quality / Branded Projects
      Projects with strong amenities, good connectivity (esp. to transit / highways / LRT etc.), high build quality, smart / green features, branded residences — these are likely to command premium pricing and maintain demand.
    • Industrial, Logistics & Data Centres
      Given the global trends (e-commerce, supply chain reshoring, semiconductor investment), Malaysia (especially Penang, Johor, Klang Valley) is seeing growing investor interest in industrial / logistics parks, warehouses, data centre space. These are viewed as relatively defensive assets.
    • Mixed-Use Development & Transit-Oriented Development (TOD)
      Areas around transport infrastructure (LRT, MRT, light rail, major highway nodes) are likely to benefit. Mixed-use developments (residential + retail + office or amenity) that offer a lifestyle component will be attractive.
    • Green / ESG / Sustainability Features
      Buyers / tenants increasingly consider energy efficiency, green certifications, smart home features, environmental impact. Developers incorporating these will have competitive advantage.
    • Government Incentives & Zone Designations
      Investment zones, special economic zones, incentives in Budget 2025, tax breaks (where available), and government infrastructure spending (transport, utilities) are going to influence property hot spots.
    • Price Correction / Buyer Power
      For savvy buyers, there might be opportunities: slower demand in non-prime sectors, more incentive packages by developers, better negotiations (price, furnishing, perks) especially in properties that are not moving quickly.

    Conclusion

    Malaysia’s property market in 2025 is at a turning point, balancing between growth opportunities and structural challenges. While affordability and regulatory changes continue to test both developers and buyers, new catalysts such as data centres, logistics demand, and large-scale infrastructure projects are reshaping the landscape.

    For investors, the key lies in identifying which segments offer long-term resilience and value. For homeowners, understanding how policies, costs, and location trends play out will make all the difference. Ultimately, the hot topics of today are shaping the strategies, risks, and rewards of tomorrow’s property market.

    From the Desk of

    Miichael Yeoh