Tag: real-estate

  • 🇲🇾 Malaysia Budget 2026: What Property Buyers and Investors Need to Know

    🇲🇾 Malaysia Budget 2026: What Property Buyers and Investors Need to Know

    By Miichael Yeoh | October 11, 2025

    The Malaysian Budget 2026 was tabled yesterday by Prime Minister and Finance Minister Dato’ Seri Anwar Ibrahim, themed “Memacu Ekonomi MADANI: Memperkasa Rakyat.”

    With a total allocation of RM470 billion, this budget continues the government’s commitment to building a fair and inclusive economy — with property and housing once again taking center stage.

    Here’s my summary and insight on what Budget 2026 means for property buyers, developers, and investors.


    🏡 1. Stamp Duty Exemption Extended for First-Time Buyers

    Good news — the full stamp duty exemption on both the instrument of transfer and loan agreement for first-time buyers remains in place until 31 December 2027.

    This applies to residential properties priced up to RM 500,000.

    👉 What this means:
    If you’re planning to buy your first home, your upfront costs remain much lower. For many young Malaysians, this can be the difference between “maybe later” and “buy now.”

    💰 2. Bigger Housing Loan Guarantee (SJKP Doubled to RM 20 Billion)

    The Housing Credit Guarantee Scheme (SJKP) is being expanded from RM 10 billion to RM 20 billion, expected to help over 80,000 first-time buyers — including self-employed, gig workers, and informal earners.

    👉 What this means:
    Loan approvals should become easier. This is crucial for those who may not have formal payslips but have consistent income — a growing segment of today’s workforce.


    🌍 3. Higher Stamp Duty for Foreign Buyers

    To cool speculative buying, stamp duty for non-citizens and foreign companies buying residential properties will rise from 4% to 8%.

    Permanent residents (PRs) are not affected.

    👉 What this means:
    Foreign investors will likely focus only on premium areas like KLCC, Mont Kiara, and Penang island. For locals, this could mean less competition — and potentially better entry prices.


    🏢 4. Tax Deduction for Converting Commercial Buildings into Homes

    A forward-thinking move — developers who convert old commercial buildings into residential use can now claim a 10% tax deduction (up to RM 10 million) on eligible renovation costs.

    👉 What this means:
    Expect more adaptive reuse projects — turning old offices or malls into apartments or co-living units. This could help rejuvenate urban centers while reducing idle property stock.


    🏠 5. Support for Rent-to-Own (RTO) and Build-Then-Sell (BTS) Schemes

    Banks are encouraged to support RTO and BTS housing models to make ownership easier and reduce project abandonment.

    👉 What this means:
    More flexibility for buyers who can’t yet afford a traditional down payment, and stronger assurance that projects are completed before full payment.


    👨‍💼 6. Higher LPPSA Loan Limit for Civil Servants

    The Public Sector Home Financing Board (LPPSA) limit will increase to RM 1 million in 2026.

    👉 What this means:
    Civil servants can now afford better homes in urban areas without needing multiple loans.


    🧱 7. RM 672 Million for Affordable Housing and Repairs

    The government is allocating RM 672 million for:

    • Affordable homes (Residensi Rakyat, Rumah Mesra Rakyat)
    • Refurbishing old or dilapidated houses
    • Maintenance for low- and medium-cost flats (e.g. lift replacements)

    👉 What this means:
    Positive for social stability and overall living quality. Also good news for contractors and local developers involved in affordable housing.


    ⚙️ 8. Construction and Tax Updates

    • SST on construction services will apply for new contracts from 1 Jan 2026.
    • Carbon tax will begin in stages, affecting material costs (cement, steel).
    • These may slightly raise overall building costs — developers should factor this into pricing.
    🔎 My Insights: What to Watch in 2026

    1. Affordable and Mid-Range Housing
      Remains the government’s priority. Buyers in this segment have strong support — expect steady demand.
    2. Conversion Projects = Hidden Opportunity
      Old commercial spaces could become the next hot residential spots. Developers who act early may gain an edge.
    3. Foreign Demand Softens, Local Focus Strengthens
      With higher duties, foreign demand may dip — but this creates more room for local owner-occupiers and long-term investors.
    4. Construction Cost Pressure
      SST and carbon-related costs might raise project expenses by 3–5%. Efficient developers with strong cash flow will manage better.
    5. Financing Still Key
      Even with incentives, loan approval remains the biggest hurdle. Buyers should prepare documentation properly (income proof, CCRIS record, existing commitments).

    📈 Final Thoughts

    Budget 2026 shows that Malaysia is moving toward a more sustainable and inclusive housing market — one that balances affordability with innovation.

    For homebuyers, it’s a window of opportunity to act while incentives are strong.
    For investors, it’s time to look beyond traditional launches and explore conversion, rental, and co-living strategies.
    And for developers, the message is clear — adapt fast, innovate smart.

    The property market in 2026 will favor those who understand trends early and act strategically.

  • Boost Your Loan Approval Chances in Malaysia

    Boost Your Loan Approval Chances in Malaysia

    Malaysian bank lending (especially for property purchases) is currently shaped by several key monetary, regulatory, and market-demand factors. Rates have been easing somewhat, but approval conditions remain cautious. Below are the latest numbers and trends.


    Current Figures & Trends

    1. Overnight Policy Rate (OPR) & Reference Rates
      • In July 2025, Bank Negara Malaysia (BNM) cut the OPR from 3.00% to 2.75% – the first cut in five years.
      • Major banks have adjusted their Standardised Base Rate (SBR) to 2.75% per annum following the OPR cut.
      • Base Rate (BR) has also been adjusted (for many banks) in line with this, though BR tends to be higher than SBR. For example, Alliance Bank’s BR is about 3.57%.
    2. Base Lending Rate / Base Financing Rate (BLR/BFR)
      • The BLR or BFR (for Islamic financings) for many banks remains in the ~6.35% to ~6.65% range. For example, Maybank’s BLR is 6.40%, Hong Leong Bank’s is ~6.64%, etc. baserate.my+3Maybank2u+3NewPages+3
    3. Effective Housing Loan Rates
      • While the base/reference rates give a starting point, effective lending rates (what borrowers actually pay) tend to be higher because banks add a margin/spread depending on risk, loan amount, tenure, etc.
      • Recent reports suggest effective rates for housing loans are in many cases 4.15% to 5.7% p.a. depending on bank, borrower profile, loan value, promotion, etc. Property Genie
    4. Loan Approval & Volume
      • There was a 25.7% month-on-month increase in approvals of housing-loan applications in July 2025 after a slump in June. Focus Malaysia – Business & Beyond
      • The approval ratio (i.e. approved vs applied) in July 2025 was about 44.8%, up from ~42.6% in June 2025. Focus Malaysia – Business & Beyond
      • On a year-on-year basis, total approved loan volume declined by ~5.1% for that month; cumulatively over the first 7 months of 2025, approved property loans were ~RM 161.4 billion, about -1.5% relative to same period in previous year. Focus Malaysia – Business & Beyond
    5. Outlook
      • With lower OPR and more competitive base/reference rates, there is optimism that loan approvals (both volume and ratio) may improve in the remaining months of 2025. Government’s likely to include incentives in Budget 2026 to support first-time buyers, low-to-middle income groups. Focus Malaysia – Business & Beyond

    Steps Borrowers Can Take to Increase Chances of Loan Approval

    Given the current environment, borrowers can do several things to strengthen their applications and improve likelihood of approval. Here are practical steps, both before and during application.

    StepWhat to DoWhy It Helps
    1. Check & Clean Up Your Credit HistoryObtain your credit report (e.g. through CTOS, CCRIS, Experian) ahead of time. Ensure there are no outstanding defaults, ensure credit card/HP payments are on time.Banks check creditworthiness; a clean credit history reduces risk and may allow you to access better rates.
    2. Assess Debt Service Ratio (DSR) / Total CommitmentsKnow your monthly obligations: other loans, credit cards, etc. Make sure your net income minus all obligations leaves enough room for loan instalments. Try to reduce existing liabilities if possible.Banks often reject or charge higher margins if your debts relative to income are too high. Lower commitments improves affordability assessment.
    3. Have Stable & Adequate IncomeDemonstrate consistent employment or business income; have documentation (pay slips, tax returns, EPF contributions). If self-employed or commission-based, provide past 2-3 years’ income statements, audited if possible.Stability & predictability of income give banks confidence in your ability to repay.
    4. Make Reasonable Down Payment / EquityThe more you put down (lower loan-to-value ratio), the less risk for the bank. If you’re first-time buyer programs exist (often requiring only 10% payment), check eligibility, but be aware these may still have stricter conditions.Less loan amount relative to property value helps bank exposure and reduces margin required.
    5. Choose Appropriate Loan TenureLonger tenure reduces monthly instalments but increases total interest paid; very long tenure may raise risk from bank’s perspective (future rate changes, income changes). Balance payroll constraints with ability to service.A manageable monthly repayment improves approval chances; less risk of default.
    6. Prepare All Supporting Documents ProperlyHave ready: identity documents, employment letters, income proof, EPF statements, tax returns (if applicable), bank statements, any other asset documentation. Ensure documents are current.It speeds up processing and reduces grounds for rejection due to missing information.
    7. Shop Around & Compare OffersDifferent banks have different margins, promotions, and underwriting criteria. Get multiple quotes. Negotiate (sometimes banks reduce spread or offer incentives).May get better rate, lower fees, more favorable terms.
    8. Provide Clear Purpose & Property DetailsHave the Sale & Purchase Agreement (SPA), valuation report (if needed), title deed, property details, etc. If property is new or under construction, ensure developer’s track record and required approvals are in order.Banks assess property risk as well: location, title, developer credibility affect approval.
    9. Maintain Good Savings / ReservesHaving savings or avoid fully depleting your accounts helps; having reserves gives cushion in case of rate increases or unexpected expenses.Shows financial discipline and lowers risk from bank’s viewpoint.
    10. Understand Bank Fees & RequirementsBe aware of legal fees, valuation fees, stamp duties, insurance (MRTA/MRTT), and any bank-specific requirements (e.g. guarantor, joint-applicant). Make sure to budget for them.Unexpected costs can derail the process; being well-prepared ensures smoother approval.

    Challenges & What Borrowers Should Watch Out For

    • Even with OPR at 2.75% and SBR adjusted, banks’ margins/spreads can still be high depending on borrower risk. So effective rates may still be less favourable for some.
    • Approval ratios (~44-47%) show that over half of applications still get declined. That means it’s not just about rates; credit & affordability are being closely scrutinized. Focus Malaysia – Business & Beyond
    • Rising costs for legal fees, valuation, and sometimes hidden fees can make total cost of financing higher than expected.
    • Inflation, future rate rises, economic uncertainties mean banks may reserve right to tighten conditions suddenly.


    Conclusion

    Bank lending is currently becoming somewhat more favourable in Malaysia thanks to the OPR cut and adjusted reference rates. However, borrowers must still present strong, well-prepared loan applications. Cleaning up credit, reducing existing obligations, having stable income and proper documentation, and choosing appropriate loan terms are all crucial.

  • Hot Topics in Malaysia’s 2025 Property Market: What You Need to Know

    Hot Topics in Malaysia’s 2025 Property Market: What You Need to Know

    The Malaysian property market is buzzing with conversations in 2025 as investors, developers, and buyers respond to new trends, policy shifts, and emerging opportunities. From cooling measures to infrastructure-driven growth corridors, the landscape is evolving rapidly. Rising construction costs, industrial and logistics demand, and the spotlight on data centres are just some of the themes shaping discussions today.

    The following are the current hot topics in Malaysia’s property market that every buyer and investor should be aware of:

    1. Residential Market Performance & Price Dynamics

    • House Price Growth Moderating
      Malaysia’s housing price index has been rising, but growth is slowing. For Q4 2024, the national average house price was ~ MYR 483,879, with year-on-year (YoY) growth modest. Global Property Guide
      There were quarter-on-quarter declines in Q4 2024 in many property types (terraced, high-rise, detached, semi-detached) — showing possible short-term corrections or softening. Global Property Guide
    • Regional Price Variations
      • In Penang, average house price remains well above MYR 400,000: about MYR 475,037 in Q4 2024. Global Property Guide
      • Kuala Lumpur is the most expensive, with average ~ MYR 794,467 in Q4 2024. Global Property Guide
      • Other states (e.g. Johor, Selangor) are in between; more affordable housing tends to be further out or in less central locations. Global Property Guide+1
    • Transaction Volume & Supply
      Residential transaction count rose ~4% in 2024 to about 260,516 units; transaction value grew ~5.9 % to ~MYR 106.92 billion. Global Property Guide
      The number of new housing starts rose ~20.6 % in 2024 (for both landed + high-rise) to ~106,236 units; completions rose ~9.7% to ~82,135 units. Global Property Guide
      Also, new planned supply was rising— ~100,461 units in 2024, up ~24.1%. Global Property Guide
    • Overhang / Unsold Stock
      Overhang remains a concern, especially in less premium or lower-value housing. The number of unsold affordable homes has increased. According to Rehda, in 1Q 2025 affordable homes accounted for ~20.7% of unsold residential units. EdgeProp.my
      In Penang, overhang has been showing improvement (decrease in unsold stock) but still persists, especially in certain price bands. Scoop

    2. Developer Sentiment & New Launches

    • Reduced Developer Confidence
      The Rehda survey (1H 2025) shows confidence among developers fell sharply. Only ~19% were optimistic about market prospects mid-2025, down from ~51% six months earlier. EdgeProp.my
      Many developers are being more cautious: ~41% plan new launches in 2H 2025, versus higher rates earlier. Some are not looking to acquire new land because of cost and risk. EdgeProp.my
    • Mismatch of Supply vs Demand (especially “affordable” units)
      A big issue flagged by developers is that many affordable units are being built in locations or at price levels that are not aligned with what local buyers can afford / prefer. Even though lower-priced units tend to have higher demand, their take-up depends heavily on location, amenities, connectivity. EdgeProp.my+1
    • Prime / High-end / Branded Projects Doing Better
      In KL, new launches in “prime” segments are seeing 30-50% take-up rates. Buyers of premium / branded residences (or units in strong locations) are more willing to pay for quality, service, amenities. JLL
      Branded residences are more visible in Penang too (e.g. Marriott Residences at Gurney Drive) reflecting demand (or at least supply) for high-end product. Wikipedia

    3. Commercial, Industrial & Office Sectors

    • Office Vacancy / Demand
      Kuala Lumpur’s office market is recovering: vacancy falling, net absorption positive. For example, KL City saw ~231,392 sq ft net absorption in Q2 2025. Vacancy in KL fell from ~23.6% (Q2 2024) to ~19.2% (Q2 2025). JLL
      Grade A office spaces (those with superior amenities, good location) are better placed; tenants are shifting to better quality buildings. JLL+1
    • Industrial / Logistics / Data Centres Growing Strong
      Demand for industrial space is strong — especially in prime logistics, e-commerce, and supply chain related sectors. In KL / Klang Valley, new supply is being absorbed, and vacancy rates are very low for good quality assets. JLL+1
      The data centre pipeline is large: Malaysia has about 638 MW of capacity completed, ~1,300 MW under construction, and an even larger future pipeline. Investment in this space is seen as strategic. JLL

    4. Government Policy, Taxation & Regulation

    • Budget 2025 Measures
      Budget 2025 includes support for infrastructure, sustainable development, and trying to attract investment in high-value sectors. Real estate/spatial planning tied to ESG / green building is emphasized. JLL
      There’s also focus on more efficient use of land, perhaps more mixed-use zoning or strategic zones. JLL
    • Tax / Fees / Local Levies
      In Penang, for instance, there is proposed quit rent increase (2026) — between ~29% to 200% increase for various land categories. For residential urban land, a hike is less steep; commercial / industrial parcels are more affected. Strata properties may face increases later (from 2027). The Vibes
    • Affordable Housing Policy Pressures
      Developers are required to allocate certain proportions of new developments to affordable housing, but this has led to some unintended consequences: in some cases, these units are in less attractive locations or are priced above what locals can realistically afford. This mismatch leads to slower sales/unsold inventory. EdgeProp.my

    5. Regional Focus: Penang (and Selected States)

    • Overhang Glut Gradually Easing in Penang
      Penang had been among the states with large unsold property inventory. In recent years, unsold units in Penang have reduced (e.g. from ~5,493 in 2021 to ~2,796 in 2024). Scoop
      However, there are still mismatches: properties priced between RM 300,000–500,000 and below are struggling more; high-end (>RM1 million) do better. Location, amenities, connectivity remain critical. Scoop
    • Infrastructure & Transport Matters More
      Projects like the Penang Transport Master Plan (including the Mutiara LRT) are expected to impact property values / demand in areas served. Wikipedia
      Also, improvements like Gurney Bay / Gurney Bay waterfront park are enhancing appeal of coastal / beachfront / high-view precincts in George Town. Wikipedia
    • Local Revenue / Cost Pressures
      The quit rent hike in Penang is being discussed: residents are reacting, especially for commercial / industrial land. This adds to holding costs and might shift developers’ cost calculations. The Vibes
    • High-end / Branded Residences Becoming More Common
      Examples in Penang: Marriott Residences Penang is a new branded residential tower at Gurney Drive. Wikipedia
      The Muze @ PICC is also a large mixed residential project in Bayan Baru with tall towers. Wikipedia

    6. Risks, Headwinds & Constraints

    • Cost Inflation, Construction / Input Costs
      Rising costs for materials, labour shortfalls, logistical challenges (supply chain) are squeezing margins. Developers have less flexibility on pricing vs cost. This trend is being widely reported. EdgeProp.my
    • Financing / Interest Rates
      Borrowing costs, stricter lending criteria, risk of loan rejection are issues especially for buyers of affordable homes. Developer access to finance is also more cautious. EdgeProp.my
    • Unsold Affordable Units Risk
      If many affordable units stay unsold, there is risk of overhang, lower returns for developers, possible depreciation in certain segments. Also risk of price stagnation in non-prime locations. EdgeProp.my+1
    • Regulatory Uncertainty / Local Policy Changes
      Increases in quit rent, possible changes in tax / service tax / sales tax, land use zoning, requirements for affordable housing quotas, etc., create uncertainty. Developers and investors are watching local councils, state governments.
    • Macro / External Risks
      Global supply chain disruptions (especially for industrial / data centre / electronics sectors), geopolitical tensions, input cost volatility, and currency / inflation risk. Also, any downturn in global trade could affect Malaysia’s manufacturing / export sectors (with knock-on effects on property demand, especially for worker housing, industrial real estate).

    7. Opportunities & What to Watch

    • Strategically Located High-Quality / Branded Projects
      Projects with strong amenities, good connectivity (esp. to transit / highways / LRT etc.), high build quality, smart / green features, branded residences — these are likely to command premium pricing and maintain demand.
    • Industrial, Logistics & Data Centres
      Given the global trends (e-commerce, supply chain reshoring, semiconductor investment), Malaysia (especially Penang, Johor, Klang Valley) is seeing growing investor interest in industrial / logistics parks, warehouses, data centre space. These are viewed as relatively defensive assets.
    • Mixed-Use Development & Transit-Oriented Development (TOD)
      Areas around transport infrastructure (LRT, MRT, light rail, major highway nodes) are likely to benefit. Mixed-use developments (residential + retail + office or amenity) that offer a lifestyle component will be attractive.
    • Green / ESG / Sustainability Features
      Buyers / tenants increasingly consider energy efficiency, green certifications, smart home features, environmental impact. Developers incorporating these will have competitive advantage.
    • Government Incentives & Zone Designations
      Investment zones, special economic zones, incentives in Budget 2025, tax breaks (where available), and government infrastructure spending (transport, utilities) are going to influence property hot spots.
    • Price Correction / Buyer Power
      For savvy buyers, there might be opportunities: slower demand in non-prime sectors, more incentive packages by developers, better negotiations (price, furnishing, perks) especially in properties that are not moving quickly.

    Conclusion

    Malaysia’s property market in 2025 is at a turning point, balancing between growth opportunities and structural challenges. While affordability and regulatory changes continue to test both developers and buyers, new catalysts such as data centres, logistics demand, and large-scale infrastructure projects are reshaping the landscape.

    For investors, the key lies in identifying which segments offer long-term resilience and value. For homeowners, understanding how policies, costs, and location trends play out will make all the difference. Ultimately, the hot topics of today are shaping the strategies, risks, and rewards of tomorrow’s property market.

    From the Desk of

    Miichael Yeoh

  • 💰 Household Debt in Malaysia – Should We Be Worried?

    💰 Household Debt in Malaysia – Should We Be Worried?

    If you’ve been hearing about household debt in the news and wondering what it means for us Malaysians, here’s the lowdown—without the boring jargon.

    Historical Context

    • 2008 marked a low point in household debt relative to GDP, at 60.4%, showing moderate borrowing during that period. CEIC Data
    • In 2020, debt peaked during the pandemic, reaching a record 93.1% of GDP. CEIC Data
    • As of 2023, debt remained elevated at 84.2% of GDP, up from 80.9% in 2022. CEIC Data

    These figures indicate that while debt declined from its 2020 high, it remains higher than pre-pandemic levels—an ongoing concern.

    The Latest Numbers (2024–2025)

    • In June 2024, household debt stood at around RM1.57 trillion, accounting for 83.8% of GDP. Housing loans comprised 61%, followed by vehicle loans (13.5%) and personal financing (12.4%).
    • By March 2025, debt rose to RM1.65 trillion, or 84.3% of GDP.

    Interestingly, household financial assets were reported to exceed debt by a factor of 2.1, suggesting Malaysians as a whole still have a substantial financial cushion. Additionally, prudent lending practices are maintained, with median debt service ratios (DSR) remaining at 34% for existing loans and 41% for newly approved loans (2024).


    What This Means for Malaysians

    Risks

    1. Sustained High Debt Load
      With debt hovering around 84% of GDP, many households must allocate a significant portion of income toward repayments—possibly limiting spending on essentials.
    2. Rising Youth Bankruptcy
      Between 2020 and early 2025, over 5,272 youths under 34 were declared bankrupt, with nearly 877 cases in 2024 alone. Personal loans accounted for 46.4% of these filings.
    3. Potential for Over-Leveraging via BNPL
      Growing use of “Buy Now, Pay Later” (BNPL) services (e.g., Atome, Grab PayLater) raises concerns, as they operate outside traditional credit tracking like CCRIS and may enable unmonitored debt accumulation.
    4. Lenient Lending to Young Graduates
      Experts warn that easy credit access for fresh graduates—especially via credit cards—could foster poor financial habits without proper income checks or financial literacy.

    Positive Offsets

    1. Healthy Asset Buffer
      Households’ financial assets outpacing their debts by over double implies a buffer that could cushion against economic shocks.
    2. Responsible Lending Frameworks
      With the Responsible Financing guidelines and relatively moderate DSRs, household borrowing still aligns with regulatory safety standards.
    3. Support Services Available
      Agencies like AKPK have helped over 64,000 borrowers settle loans, while nearly 270,000 others continue to receive support through debt management programs.

    Balancing Act: Looking Forward

    • Economic Growth vs. Debt Sustainability
      While household debt has eased somewhat from its pandemic-era peak, it remains elevated, and spikes in personal or BNPL borrowing could strain households—especially lower-income groups.
    • Youth Financial Health
      The rising bankruptcy trend among the young underscores the necessity of stronger financial education and tighter lending criteria for vulnerable demographics.
    • Policy Opportunities
      Strengthening regulation around new lending platforms like BNPL, embedding financial literacy into early education, and enforcing responsible credit access remain vital steps to prevent systemic vulnerabilities.

    In Summary

    Household debt in Malaysia has declined from its 2020 highs but remains elevated, hovering around 84% of GDP in 2024–2025. While household financial assets provide a buffer and regulatory frameworks offer some protection, rising personal debt—especially among youths and via emerging platforms like BNPL—pose risks. Continued focus on financial education, responsible lending policies, and inclusive support systems will be key to ensuring long-term household resilience.

  • Inheritance Law and Joint Ownership Explained

    Inheritance Law and Joint Ownership Explained

    Written by Jocelline Chee from Rightwill | Edited by Miichael Yeoh

    When it comes to inheritance, things can get complicated—and emotional—especially when property is involved. In Malaysia, many people assume that putting property under joint names (like with a spouse or child) will make things smoother when someone passes away. Unfortunately, it’s not always that simple.

    If you’re planning to leave a property behind for your loved ones, it’s important to understand how inheritance laws work in Malaysia and the potential problems that can pop up with joint ownership.


    🏛️ How Inheritance Works in Malaysia

    Inheritance laws in Malaysia depend on your religion:

    • For Muslims, faraid (Islamic inheritance law) applies. It has fixed rules on how the estate is divided among family members.
    • For non-Muslims, the Distribution Act 1958 (amended in 1997) applies. This Act lays out who gets what—based on whether the deceased leaves behind a spouse, children, or parents.

    If someone dies without a will, the law decides how the assets are shared. That’s why it’s so important to have a valid will—it ensures your wishes are followed.

    Example under the Distribution Act:

    If the deceased leaves behind…Parent(s) getSpouse getsChildren get
    Parents, spouse & children1/41/41/2

    🏠 Joint Name Properties – Not As Simple As You Think

    Many Malaysians put properties under joint names thinking it will automatically go to the other person when they pass away. But that’s not always true.

    There are two main types of joint ownership in property law:

    1. Joint Tenancy
      • Comes with the right of survivorship.
      • If one owner dies, the property automatically goes to the surviving owner.
      • This is common among married couples.
    2. Tenancy in Common
      • Each person owns a specific share.
      • When one dies, their share becomes part of their estate and is distributed according to their will or the law.
      • This is more common in Malaysia, even when it’s between family members.

    Here’s the catch: Most joint name properties in Malaysia are actually treated as tenancy in common, unless stated otherwise. That means—even if your name is on the title—the other person’s share doesn’t automatically go to you. It becomes part of their estate and is shared out according to their will or inheritance laws.


    ⚠️ Common Pitfalls to Watch Out For

    1. Unclear Ownership Type
      If it’s not clearly stated whether it’s joint tenancy or tenancy in common, it can lead to confusion—and disputes.
    2. Unequal Contributions
      One person may have paid more, but the property is split 50-50 on paper. This often leads to disagreements among family members.
    3. Family Conflicts
      Things can get messy with children from previous marriages, siblings, or estranged family members. Without clear planning, emotions can take over.
    4. Outdated or No Will
      A will that hasn’t been updated—or worse, no will at all—can cause contradictions and legal battles during probate.

    ✅ What You Should Do

    To protect your assets and your loved ones from future disputes:

    • ✅ Talk to a professional estate planner or lawyer
    • ✅ Make sure your will is valid, updated, and matches your current ownership structure
    • ✅ Clearly state the type of joint ownership on your property documents
    • ✅ Keep your family informed, so there are no surprises later

    Joint ownership may seem like the easy way, but without proper planning, it can create unnecessary complications. A little preparation now can give your family peace of mind in the future.

  • Why Every Condo Owner Must Pay Maintenance Fees

    Why Every Condo Owner Must Pay Maintenance Fees

    By Ken Teo | Edited by Miichael Yeoh

    Let’s Start with This: You’re Not Just Buying a Unit — You’re Buying Into a Community

    When you own a condo, apartment, or any kind of strata property, you’re not just buying four walls. You’re also sharing ownership of everything outside your unit — the lifts, the corridors, the lobby, the pool, the roof, the water tank, the whole building.

    That’s why every owner needs to pay maintenance fees and contribute to the sinking fund. It’s not a donation. It’s not optional. It’s your duty as a co-owner.

    Let’s break it down in plain language…


    1. These Are Not “Extra Charges” — They’re Your Legal Responsibility

    Under Malaysia’s Strata Management Act 2013 (Act 757):

    • Section 25(1) (for Joint Management Body or JMB), and
    • Section 50(1) (for Management Corporation or MC),

    …it clearly says: every unit owner must pay maintenance charges and sinking fund contributions.

    These are not surprise charges or “admin fees.” They’re meant to cover your share of keeping the building clean, safe, and in working condition. It’s the same as chipping in for house bills when you live with housemates — it’s only fair.


    2. “If Others Don’t Pay, Why Should I?”

    This is a common complaint — and hey, we get it. Why should you be the good guy when others are skipping out?

    But think about this:

    • If no one pays, who’s going to fix the lift?
    • Who’s going to pay the cleaners or security guards?
    • How will the broken tiles or leaking roof ever get fixed?

    When people stop paying, the whole building suffers. And soon, even those who were paying start asking: “Why should I continue?” — and that’s when things spiral downhill.

    You don’t just live in your unit. You share ownership of the entire building. So if everyone pays their part, everyone enjoys a better home.


    3. What Happens If You Don’t Pay?

    The law doesn’t just suggest — it enforces. If you don’t pay, the JMB or MC has the right to take action under Section 60(3) of the Strata Management Act.

    Here’s what they can legally do:

    • Send you demand letters
    • File a claim with the Strata Tribunal or even in court
    • Charge up to 10% interest per year on overdue amounts
    • Block your access to facilities (like pool, gym, function room), with proper notice

    So it’s not just about being fair to others — not paying could cost you more later, both in fees and reputation. And your outstanding dues? They’ll follow your unit, even if you try to sell.


    4. Think of It as an Investment — Not a Burden

    No one enjoys paying bills, we know that. But your maintenance charges are not “just another bill.” They’re an investment in your own home.

    The money goes into:

    • Repairs and upkeep
    • Security and cleanliness
    • Ensuring your home is safe and comfortable
    • Keeping your property value high

    Ever seen a badly maintained condo? Low resale value, fewer buyers, and complaints all around. Compare that to a well-managed building — units there sell faster and at better prices.


    5. You Have the Right to Know Where the Money Goes

    Worried that your money is being misused? The good news is: you have rights.

    By law, the JMB or MC must:

    • Hold Annual General Meetings (AGM)
    • Present audited accounts and budgets
    • Use the sinking fund for long-term repairs like repainting, roofing, waterproofing, and lift upgrades

    As an owner, you can (and should):

    • Ask for financial reports
    • Question how funds are being spent
    • Vote during AGMs

    This is your money. And you deserve to know how it’s used.


    In Summary: Don’t Just Own a Unit — Own the Responsibility

    Paying your maintenance fees and sinking fund isn’t just about following the law. It’s about doing your part.

    You’re not a tenant anymore. You’re an owner. You have a stake in the building — and your actions affect everyone else too.

    So instead of thinking “Why me?” — let’s think “Why not us?”

    Let’s build communities, not just condominiums.
    Let’s protect our investments, not neglect them.
    Let’s be the kind of owners who care.

    Because a well-maintained building isn’t just a nicer place to live — it’s something you can be proud to call home.

  • Should You Buy Property in Malaysia Now? Insights 2025

    Should You Buy Property in Malaysia Now? Insights 2025

    Published: July 17, 2025
    By: Miichael Yeoh


    After a strong run in 2023 and 2024, Malaysia’s residential property market is finally taking a breather. While some see this as a red flag, the data paints a more balanced picture—one of resilience and recalibration, not recession.

    So, what exactly is happening in 2025? And should you be worried or ready to buy?

    Let’s break it down.


    📉 Q1 2025: Slower But Still Solid

    Malaysia’s residential property transactions dropped 6.2% in Q1 2025 compared to Q4 2024. That’s the first notable slowdown after nearly two years of consistent growth.

    But here’s the catch: activity levels are still higher than in 2022, which means we’re not seeing a crash—just a cooling-off.

    “The slowdown is expected. It’s the market stabilizing after a hot streak,” said a property analyst from KL.


    📈 Prices Are Still Moving Up

    The national average house price reached RM483,879 in Q1, reflecting a +1.4% year-on-year increase. Areas like Klang Valley, Penang Island, and Johor Bahru continue to dominate in both value and volume.

    Here’s a quick snapshot:

    AreaAvg. Price (Q1 2025)YoY Price Growth
    Klang ValleyRM 550,000+2.1%
    Penang IslandRM 620,000+1.8%
    Johor BahruRM 460,000+1.2%

    🏗️ Developers Stay Selective with New Launches

    With rising construction costs and cautious sentiment, developers are choosing quality over quantity. Most new launches are in well-connected, lifestyle-oriented locations—think smart townships, mixed developments, and green-certified homes.

    Hot-selling projects like Elmina Ridge 2 and Avalon Cybersouth saw near 90% take-up rates, showing buyers are still ready to act—when the product is right.


    🔍 What’s Supporting the Market?

    Despite the slowdown in transactions, several key factors are helping the market stay afloat:

    • Stable interest rates (BNM kept the OPR steady).
    • Low unemployment rate (around 3.3%).
    • Young home-buying population (millennials & Gen Z entering the market).
    • MM2H visa tweaks requiring foreigners to purchase property.

    These are long-term positives that signal stability in the residential segment.


    ⚠️ What Buyers & Investors Should Watch

    While the fundamentals are strong, here are a few caution signs to keep in mind:

    1. Affordability gaps in cities like KL and Penang may limit demand in certain price segments.
    2. Oversupply risks in high-rise areas still exist, especially where demand isn’t organic.
    3. Policy changes—any adjustments to RPGT, stamp duties, or loan rules could shift the playing field fast.

    💡 Final Thoughts

    If you’re a buyer or investor waiting for a market crash—you might be waiting for a while. What we’re seeing now is not the end of growth, but a healthier, more stable market emerging after years of turbulence.

    This could actually be the perfect window to enter—especially if you’re eyeing the right locations, products, and long-term value.

    🗣 “The best time to buy property is when others hesitate—because real opportunity hides in uncertainty.”


    Need help identifying the right property in 2025?
    Join the Property EDU Club — get expert guidance, real-life case studies, and insider access to property deals most investors never see.

    👉 Click here to learn more and join now

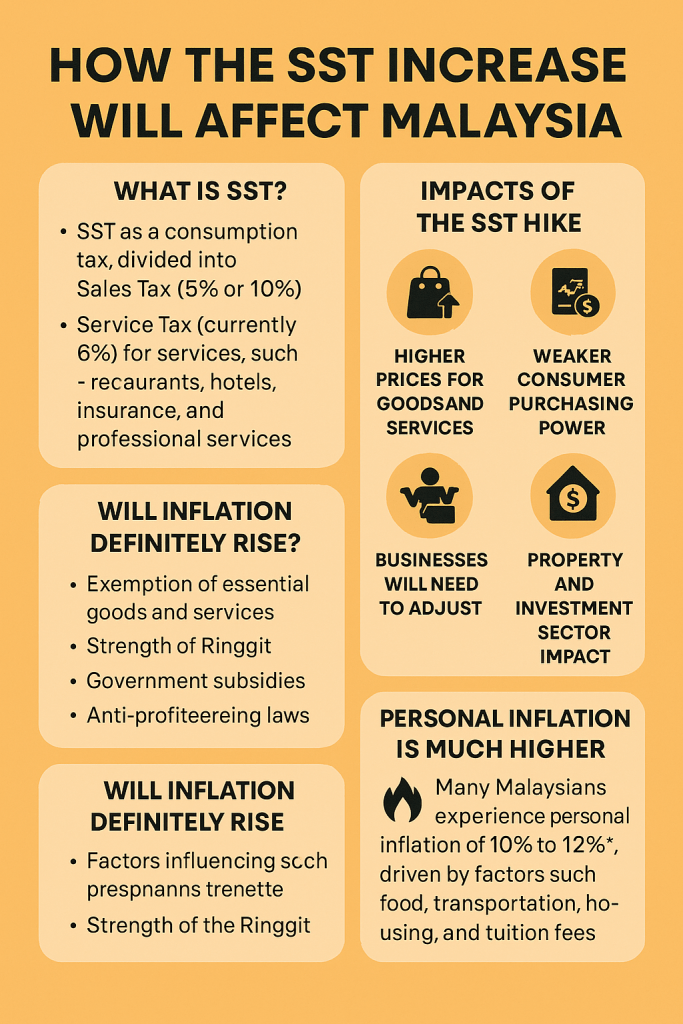
  • SST Increase from 6% to 8%: How It Will Impact Malaysia’s Property Industry

    SST Increase from 6% to 8%: How It Will Impact Malaysia’s Property Industry


    Introduction

    Starting July 1, 2025, the Malaysian government officially raised the Sales and Services Tax (SST) from 6% to 8%, aiming to increase national revenue and reduce fiscal deficits. While basic necessities and certain essential services remain exempt, many sectors — including construction, legal, professional, and property-related services — are now affected. This tax adjustment is expected to have ripple effects across various industries, especially the property market, which is already facing affordability challenges.

    This article examines how the SST hike impacts the property industry, giving practical examples and offering insights into how buyers, developers, and investors might respond.


    1. Scope of SST Increase in the Property Sector

    The SST increase does not apply directly to the sale of residential properties, which are exempt from SST. However, indirect costs will go up due to increased service charges in the construction, legal, and property management sectors. These cost increments will eventually be transferred to end buyers and tenants, especially in commercial and high-rise residential developments.


    2. Areas Affected in Property Development

    Here’s a breakdown of how the 2% SST increase affects the property ecosystem:

    Service TypeBaseOld SST (6%)New SST (8%)
    Architect/Engineer FeesRM100,000RM106,000RM108,000
    Legal/Stamping ServicesRM20,000RM21,200RM21,600
    Renovation/Interior Fit-OutRM150,000RM159,000RM162,000
    Property Management ServicesRM50,000RM53,000RM54,000
    Advertising & MarketingRM30,000RM31,800RM32,400

    Example:
    A developer constructing a new serviced apartment project incurs around RM5 million in professional and management fees. Under the previous 6% SST, the tax was RM300,000. Now, it’s RM400,000 — a 33% increase in SST cost, which could result in higher launch prices to maintain developer margins.


    3. Impact on Property Developers

    • Higher Development Cost: Most developers will face a 5–8% increase in overall project costs when combined with inflation and compliance costs.
    • Price Adjustment Pressure: Developers may either absorb the cost (lowering margins) or pass it to consumers — likely raising launch prices, especially in urban areas.
    • Delay in New Launches: Some developers may delay project launches until market conditions stabilize.

    4. Impact on Homebuyers

    Although SST is not directly charged on residential property purchases, buyers may feel the pinch in several ways:

    • Higher Property Prices: Due to rising development and marketing costs.
    • Increased Renovation Expenses: Renovation and interior design are service-based industries and are now charged 8% SST.
    • Increased Maintenance Fees: Management services in condos or commercial buildings may increase, translating to higher monthly maintenance charges for owners and tenants.

    5. Impact on Real Estate Investors

    Investors will also be affected indirectly:

    • Lower Rental Yield: If property prices go up but rental rates remain stagnant, net returns will shrink.
    • Higher Operational Costs: Especially for those managing short-term rentals or Airbnb units (cleaning, advertising, renovation services all now taxed at 8%).
    • Buyer Caution: Investors may delay purchases or switch to lower-risk assets like REITs or landed residential properties outside city centers.

    6. Outlook and Strategies

    Despite the challenges, the SST increase may drive some positive changes:

    • Developers may adopt cost-efficiency technologies to maintain affordability.
    • Buyers may turn to subsale markets, which are less affected by SST-related costs.
    • Investors may focus on cash-flow-positive properties, especially those with low operating costs.

    Conclusion

    The SST increase from 6% to 8% might seem modest on paper, but its cascading effect across the property value chain is real. While residential property sales remain tax-exempt, associated services — from construction to maintenance — will become costlier. As developers adjust pricing and investors reassess risk, Malaysia’s property market may experience a short-term slowdown but could stabilize as the market adapts.


    Final Thought
    For both buyers and investors, 2024–2025 will require careful financial planning and a close eye on property pricing trends. Understanding the real costs behind the price tag is more important than ever.

    From The Desk of Miichael Yeoh

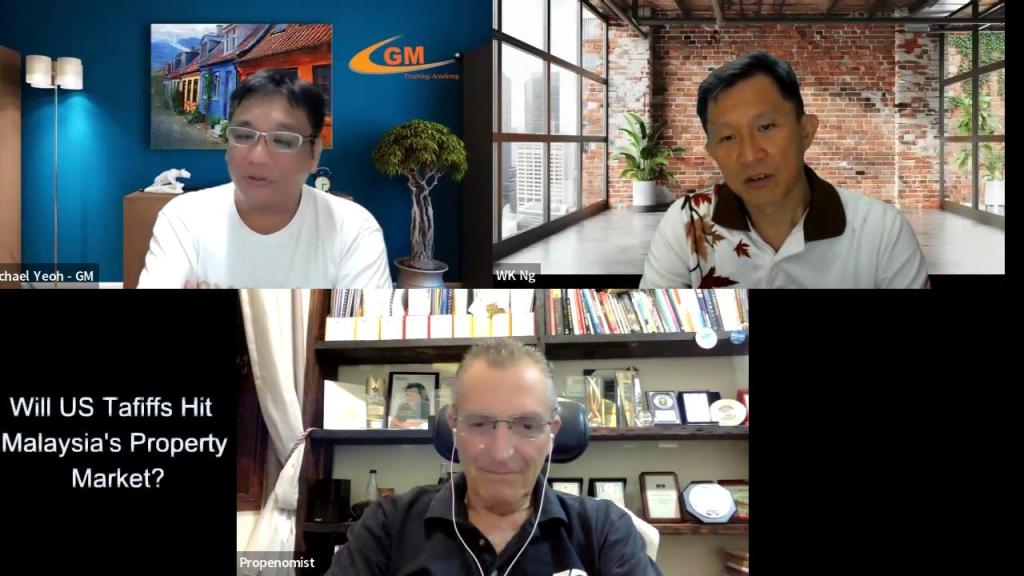
  • Will US Tariffs Hit Malaysia’s Market? Here’s What Experts Say

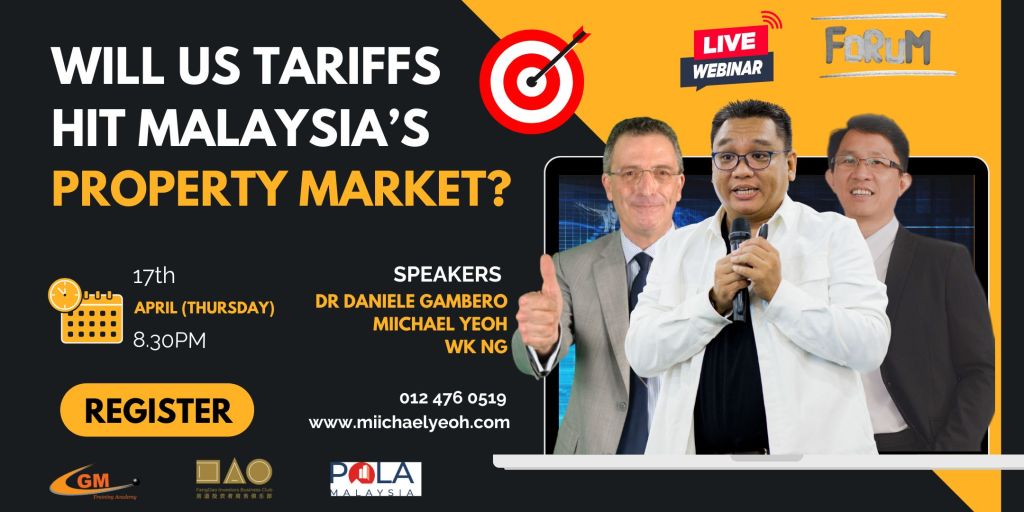
    Will US Tariffs Hit Malaysia’s Market? Here’s What Experts Say

    Over the past few weeks, the global economic community has been buzzing with concern: Will the U.S. impose new tariffs on Malaysia? And if so, what does it mean for our local economy — especially the property market?

    In response to growing public interest, I hosted a last-minute live Zoom forum on this critical issue, joined by three seasoned experts:

    🔹 Miichael Yeoh – CEO of GM Training Academy
    🔹 Dr. Daniele Gambero – economist and CEO of REI Group
    🔹 WK Ng – former Dell director turned full-time property investor

    View the recorded video for more information:

  • Guide to Minimum Foreign Property Purchase Prices in Malaysia

    Guide to Minimum Foreign Property Purchase Prices in Malaysia

    In Malaysia, each state has its own regulations and conditions for foreign property purchases, including minimum purchase prices and additional requirements. Here’s a breakdown of the key differences across states:

    Minimum Property Purchase Prices for Foreigners (2024)

    Foreigners are generally required to buy properties above a certain price threshold, which varies by state:

    StateMinimum Price (MYR)Additional Conditions
    Kuala LumpurRM 1,000,000None for most properties; some high-end condos may have lower thresholds.
    SelangorRM 2,000,000Foreigners can only buy properties ≥RM 2M (since 2024).
    PenangRM 1,000,000 (Island)RM 800,000 for mainland (Seberang Perai). Some exceptions for high-end projects.
    JohorRM 1,000,000RM 2M for landed properties in certain zones (e.g., Iskandar Malaysia).
    MalaccaRM 1,000,000 (urban)RM 500,000 for rural areas (subject to state approval).
    SabahRM 1,000,000Additional approval from state authorities required.
    SarawakRM 1,000,000 (urban)Foreigners need special approval from state government; higher scrutiny.
    PerakRM 1,000,000RM 500,000 for some agricultural/industrial properties.
    PahangRM 1,000,000Lower thresholds (RM 500,000) for certain tourism projects.
    KedahRM 1,000,000RM 500,000 for industrial/commercial properties.
    KelantanRM 1,000,000Additional state consent required.
    TerengganuRM 1,000,000Some exceptions for tourism-related properties.
    Negeri SembilanRM 1,000,000RM 500,000 for commercial/industrial properties.
    PerlisRM 1,000,000Fewer foreign buyers; state approval needed.

    Key Conditions for Foreign Buyers

    1. State Consent Approval
      • Some states (e.g., Sarawak, Sabah, Kelantan, Johor) require additional state approval.
      • In Penang, foreigners must apply for state consent for properties below RM 3M.
    2. Restrictions on Landed Property
      • Foreigners are generally restricted from buying low-cost and Malay Reserve land.
      • In Johor, foreigners can only buy landed properties ≥RM 2M in certain zones.
    3. Additional Taxes & Fees
      • Real Property Gains Tax (RPGT): 30% if sold within 3 years (reduces over time).
      • Foreigner Acquisition Tax: Some states impose extra fees (e.g., Johor charges 2-4% for foreign purchases).
    4. Leasehold vs. Freehold
      • Most states allow foreigners to buy freehold properties, but leasehold purchases may require state approval.
    5. Special Exemptions
      • Malaysia My Second Home (MM2H) participants may enjoy relaxed rules in some states.
      • High-value investments (e.g., RM 5M+) may qualify for exemptions in certain states.

    Recent Changes (2024)

    • Selangor increased the minimum purchase price to RM 2M for foreigners.
    • Johor tightened rules on foreign ownership in Iskandar Malaysia.
    • Penang maintains stricter controls on high-density foreign purchases.

    Conclusion

    Foreign buyers should check with the state land office and consult a local lawyer before purchasing property in Malaysia, as rules can change. Popular investment destinations like Kuala Lumpur, Penang, and Johor have stricter conditions compared to smaller states.

    From the Desk of

    Miichael Yeoh

  • 109 Developers Blacklisted: Safeguards for Malaysian Homebuyers

    109 Developers Blacklisted: Safeguards for Malaysian Homebuyers

    The recent announcement by Housing and Local Government Minister Nga Kor Ming regarding the blacklisting of 109 housing developers is a significant step toward enhancing transparency and protecting homebuyers in Malaysia. By making this list publicly accessible on the ministry’s website, potential buyers can now verify the credibility of developers before making purchasing decisions.

    This initiative is part of broader efforts to address issues related to abandoned projects and fraudulent practices in the housing sector. The proposed amendments to the Housing Development (Control and Licensing) Act 1966 aim to impose stricter penalties on errant developers, including potential travel bans and substantial fines. ​

    While these measures demonstrate the government’s commitment to safeguarding homebuyers, it’s crucial for individuals to conduct thorough due diligence. Beyond consulting the blacklist, prospective buyers should assess developers’ track records, financial stability, and past project completions. Engaging with real estate professionals and seeking legal advice can further ensure informed decisions.​

    In summary, the public disclosure of blacklisted developers is a commendable move toward greater accountability in Malaysia’s housing industry. However, a collaborative approach involving stringent enforcement, legislative reforms, and proactive consumer awareness is essential to foster a trustworthy and resilient housing market.

    Read related article by The Star

    Homebuyers beware: 109 housing developers blacklisted, says Nga | The Star

    From the Desk of

    Miichael Yeoh

  • Unlock Real Estate Success with Property Study Tours

    Unlock Real Estate Success with Property Study Tours

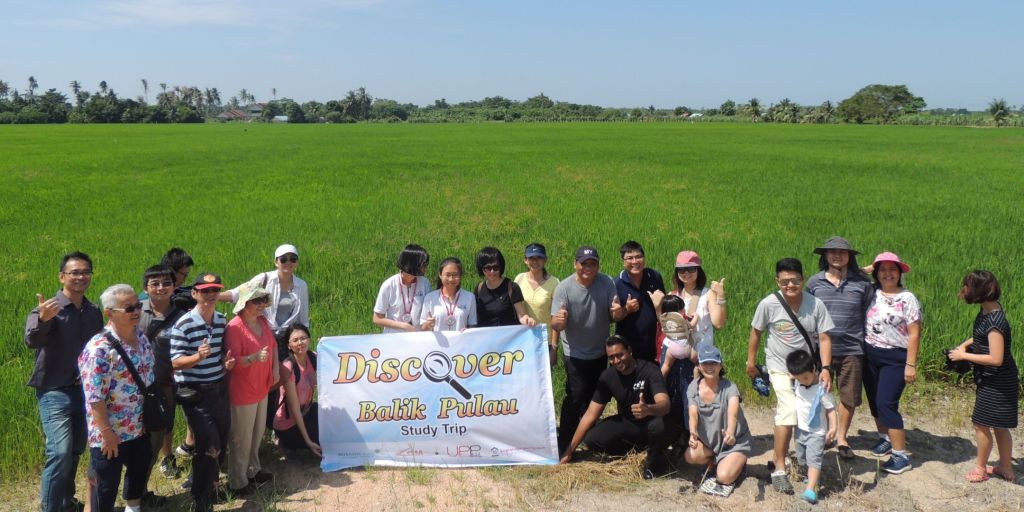
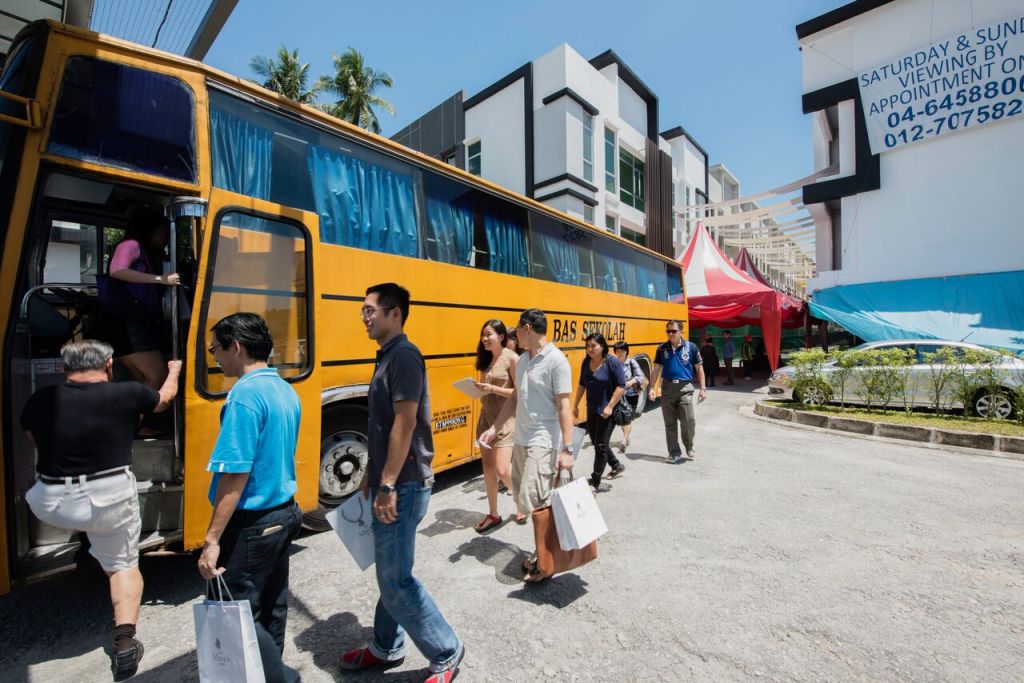
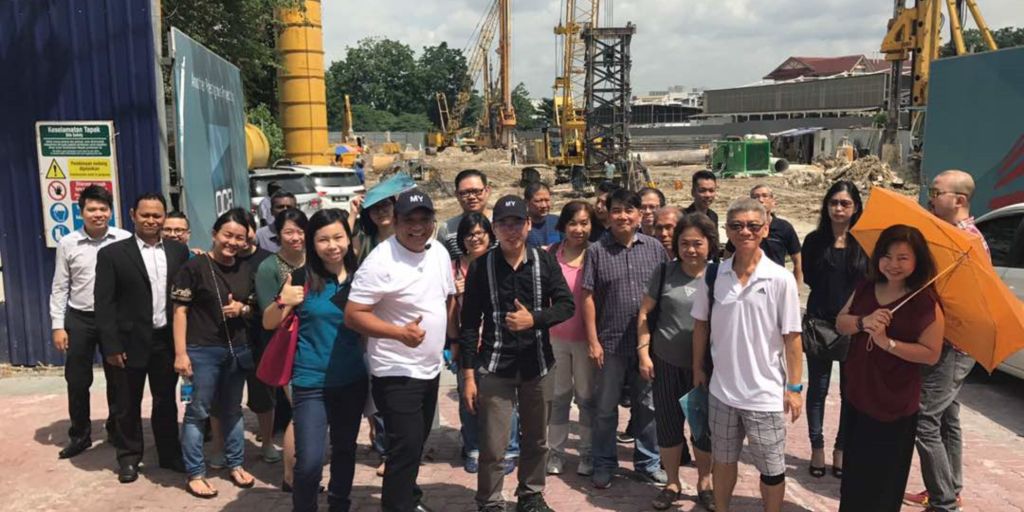
    As a property investment coach and mentor, I’ve seen firsthand how powerful a property study trip can be for investors at all levels. Whether you’re a seasoned investor or just starting out, nothing beats the experience of visiting properties in person, analyzing market trends, and networking with experts. That’s why I organize property study trips—to give you a competitive edge in the real estate market. Here’s why you should join me on this journey.

    1. Firsthand Property Inspection

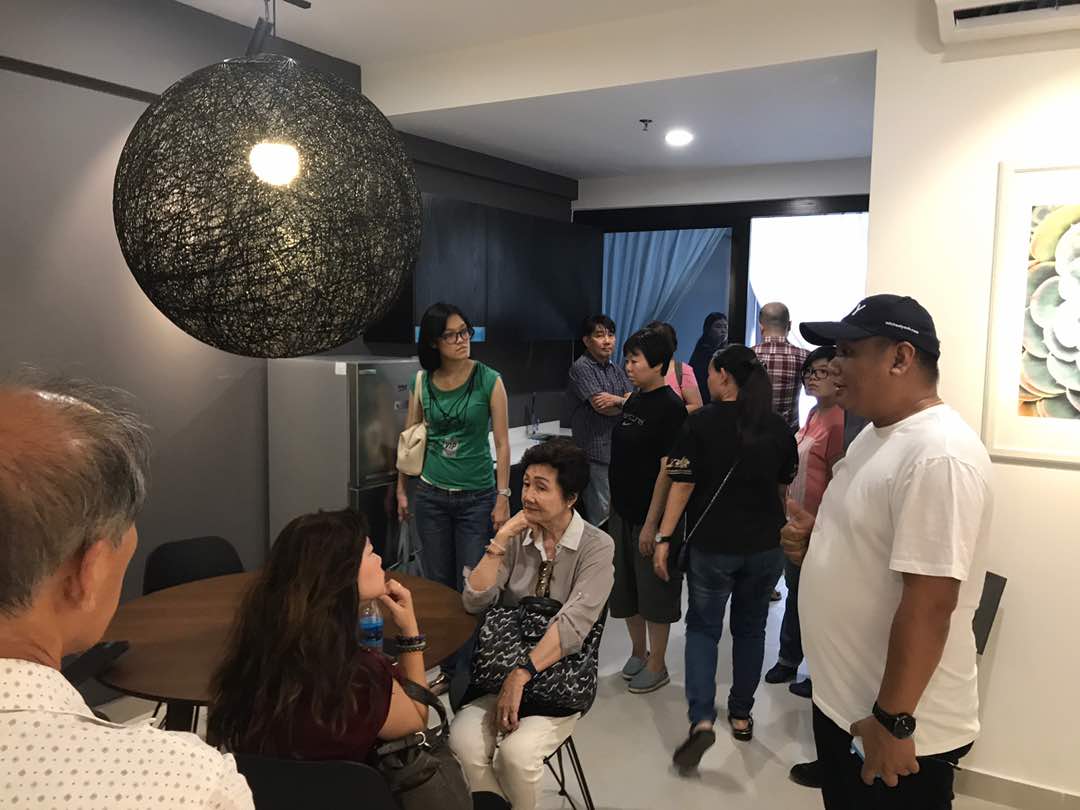
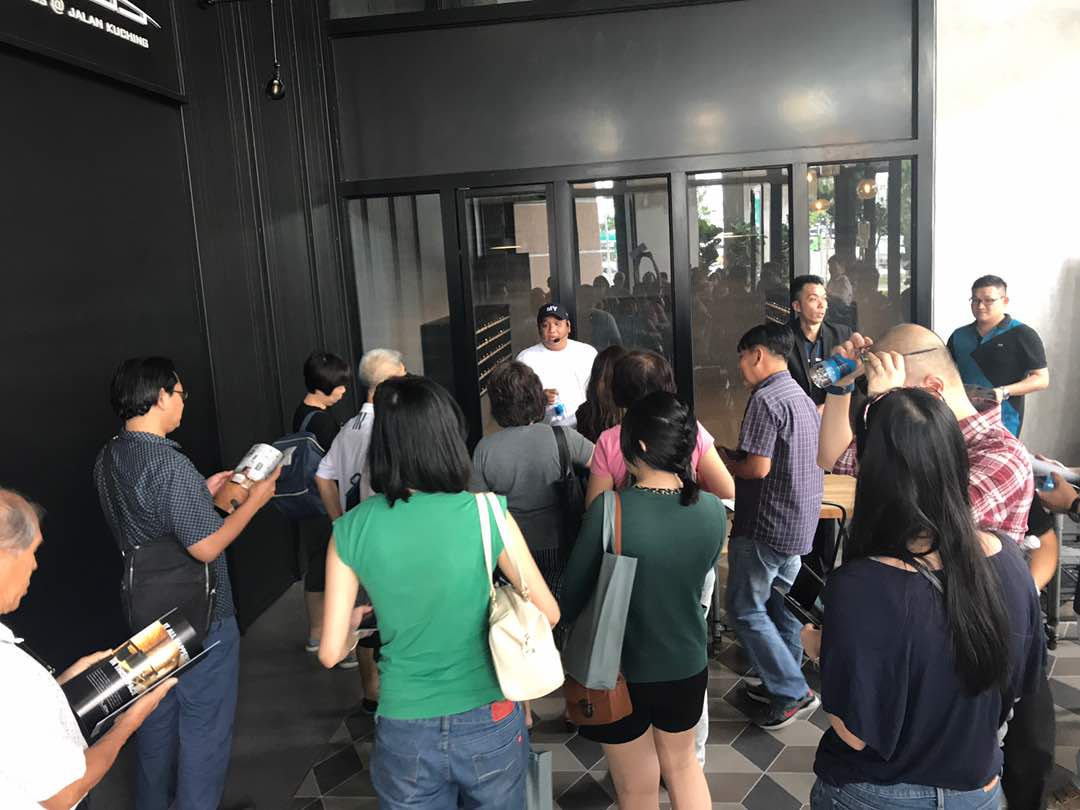
    Browsing online listings and reading brochures only tell part of the story. When you join my property study tour, you’ll get to walk through the properties, examine the surroundings, and see if they align with your investment goals. I’ll guide you in assessing crucial aspects like location, infrastructure, and future development plans so you can make a well-informed decision. Plus, I’ll share my insights on what to look for in a profitable property, helping you avoid costly mistakes.

    2. Understand Market Trends and Insights

    Every property market operates differently, and the key to successful investing is understanding these nuances. On my study tours, I provide in-depth briefings on market trends, pricing structures, and upcoming investment hotspots. You’ll also hear from local experts who can offer data-driven insights into property price movements and rental yields. I’ve spent years studying the market, and I’ll help you cut through the noise to identify real opportunities.

    3. Network with Like-Minded Investors

    One of the biggest advantages of joining my study trips is the opportunity to meet and network with like-minded investors. Many of my past participants have formed business partnerships, co-invested in properties, or simply found a supportive community to grow with. Learning from the experiences of others can be incredibly valuable, and I make sure to create an environment where everyone can share and learn together.

    4. Exclusive Access to Off-Market Deals

    Through my network and relationships with developers, I often get access to exclusive deals that aren’t available to the general public. This means you’ll have the chance to secure high-potential properties before they hit the open market. Developers also offer special discounts, incentives, and flexible payment plans to my study trip attendees—something you wouldn’t get if you were searching on your own.

    5. Expert Guidance and Analysis

    Investing in property isn’t just about buying a house or unit—it’s about making the right investment decisions. I provide expert guidance throughout the trip, helping you analyze risks, assess potential returns, and navigate financing options. You’ll also gain insights into legal requirements, taxation, and property management. With my years of experience in property investment and financial consulting, I’ll make sure you’re equipped with the knowledge you need to succeed.

    6. Experience the Local Lifestyle and Environment

    A great investment isn’t just about the property itself—it’s also about the surrounding lifestyle, infrastructure, and amenities. By visiting the location in person, you’ll get a feel for the area, check out nearby facilities, and determine whether it aligns with your personal or investment objectives. I’ll also share my insights on which neighborhoods have the most growth potential and what to watch out for when assessing an area’s long-term viability.

    7. Gain Confidence in Your Investment Decisions

    One of the biggest challenges new investors face is hesitation and uncertainty. I believe that seeing is believing, and by joining my study trip, you’ll gain the confidence to make informed investment decisions. I’ll help you weigh the pros and cons of different properties so you can make a calculated decision rather than relying on guesswork.

    8. Exposure to Different Property Investment Strategies

    Not all property investments are the same. During the tour, I’ll introduce you to different strategies such as buying for rental yield, flipping properties, or capital appreciation. You’ll also learn about new trends like co-living spaces and serviced apartments that can diversify your portfolio. By understanding these strategies, you’ll be able to choose an approach that aligns with your financial goals.

    9. Learn from Real-Life Case Studies

    I always include real-life case studies in my study trips, sharing stories of successful property investors who have built wealth through smart real estate decisions. These case studies provide valuable lessons, helping you understand what works and what doesn’t in property investment. You’ll hear from actual investors who share their journeys, challenges, and strategies.

    10. Potential for Immediate Action

    Unlike attending a seminar or watching an online course, a property study tour allows you to take action immediately. If you find a property that meets your criteria, you can reserve it on the spot—often with exclusive perks and discounts. Many of my past participants have successfully secured properties during the trip, giving them a head start in their investment journey.

    Conclusion

    I’ve designed my property study tours to be an immersive, hands-on learning experience that equips you with the knowledge, connections, and confidence to invest successfully. Whether you’re looking for your first property or expanding your portfolio, this tour will give you a significant advantage. Don’t miss out on this opportunity—join me on the next study trip and take your property investment journey to the next level!
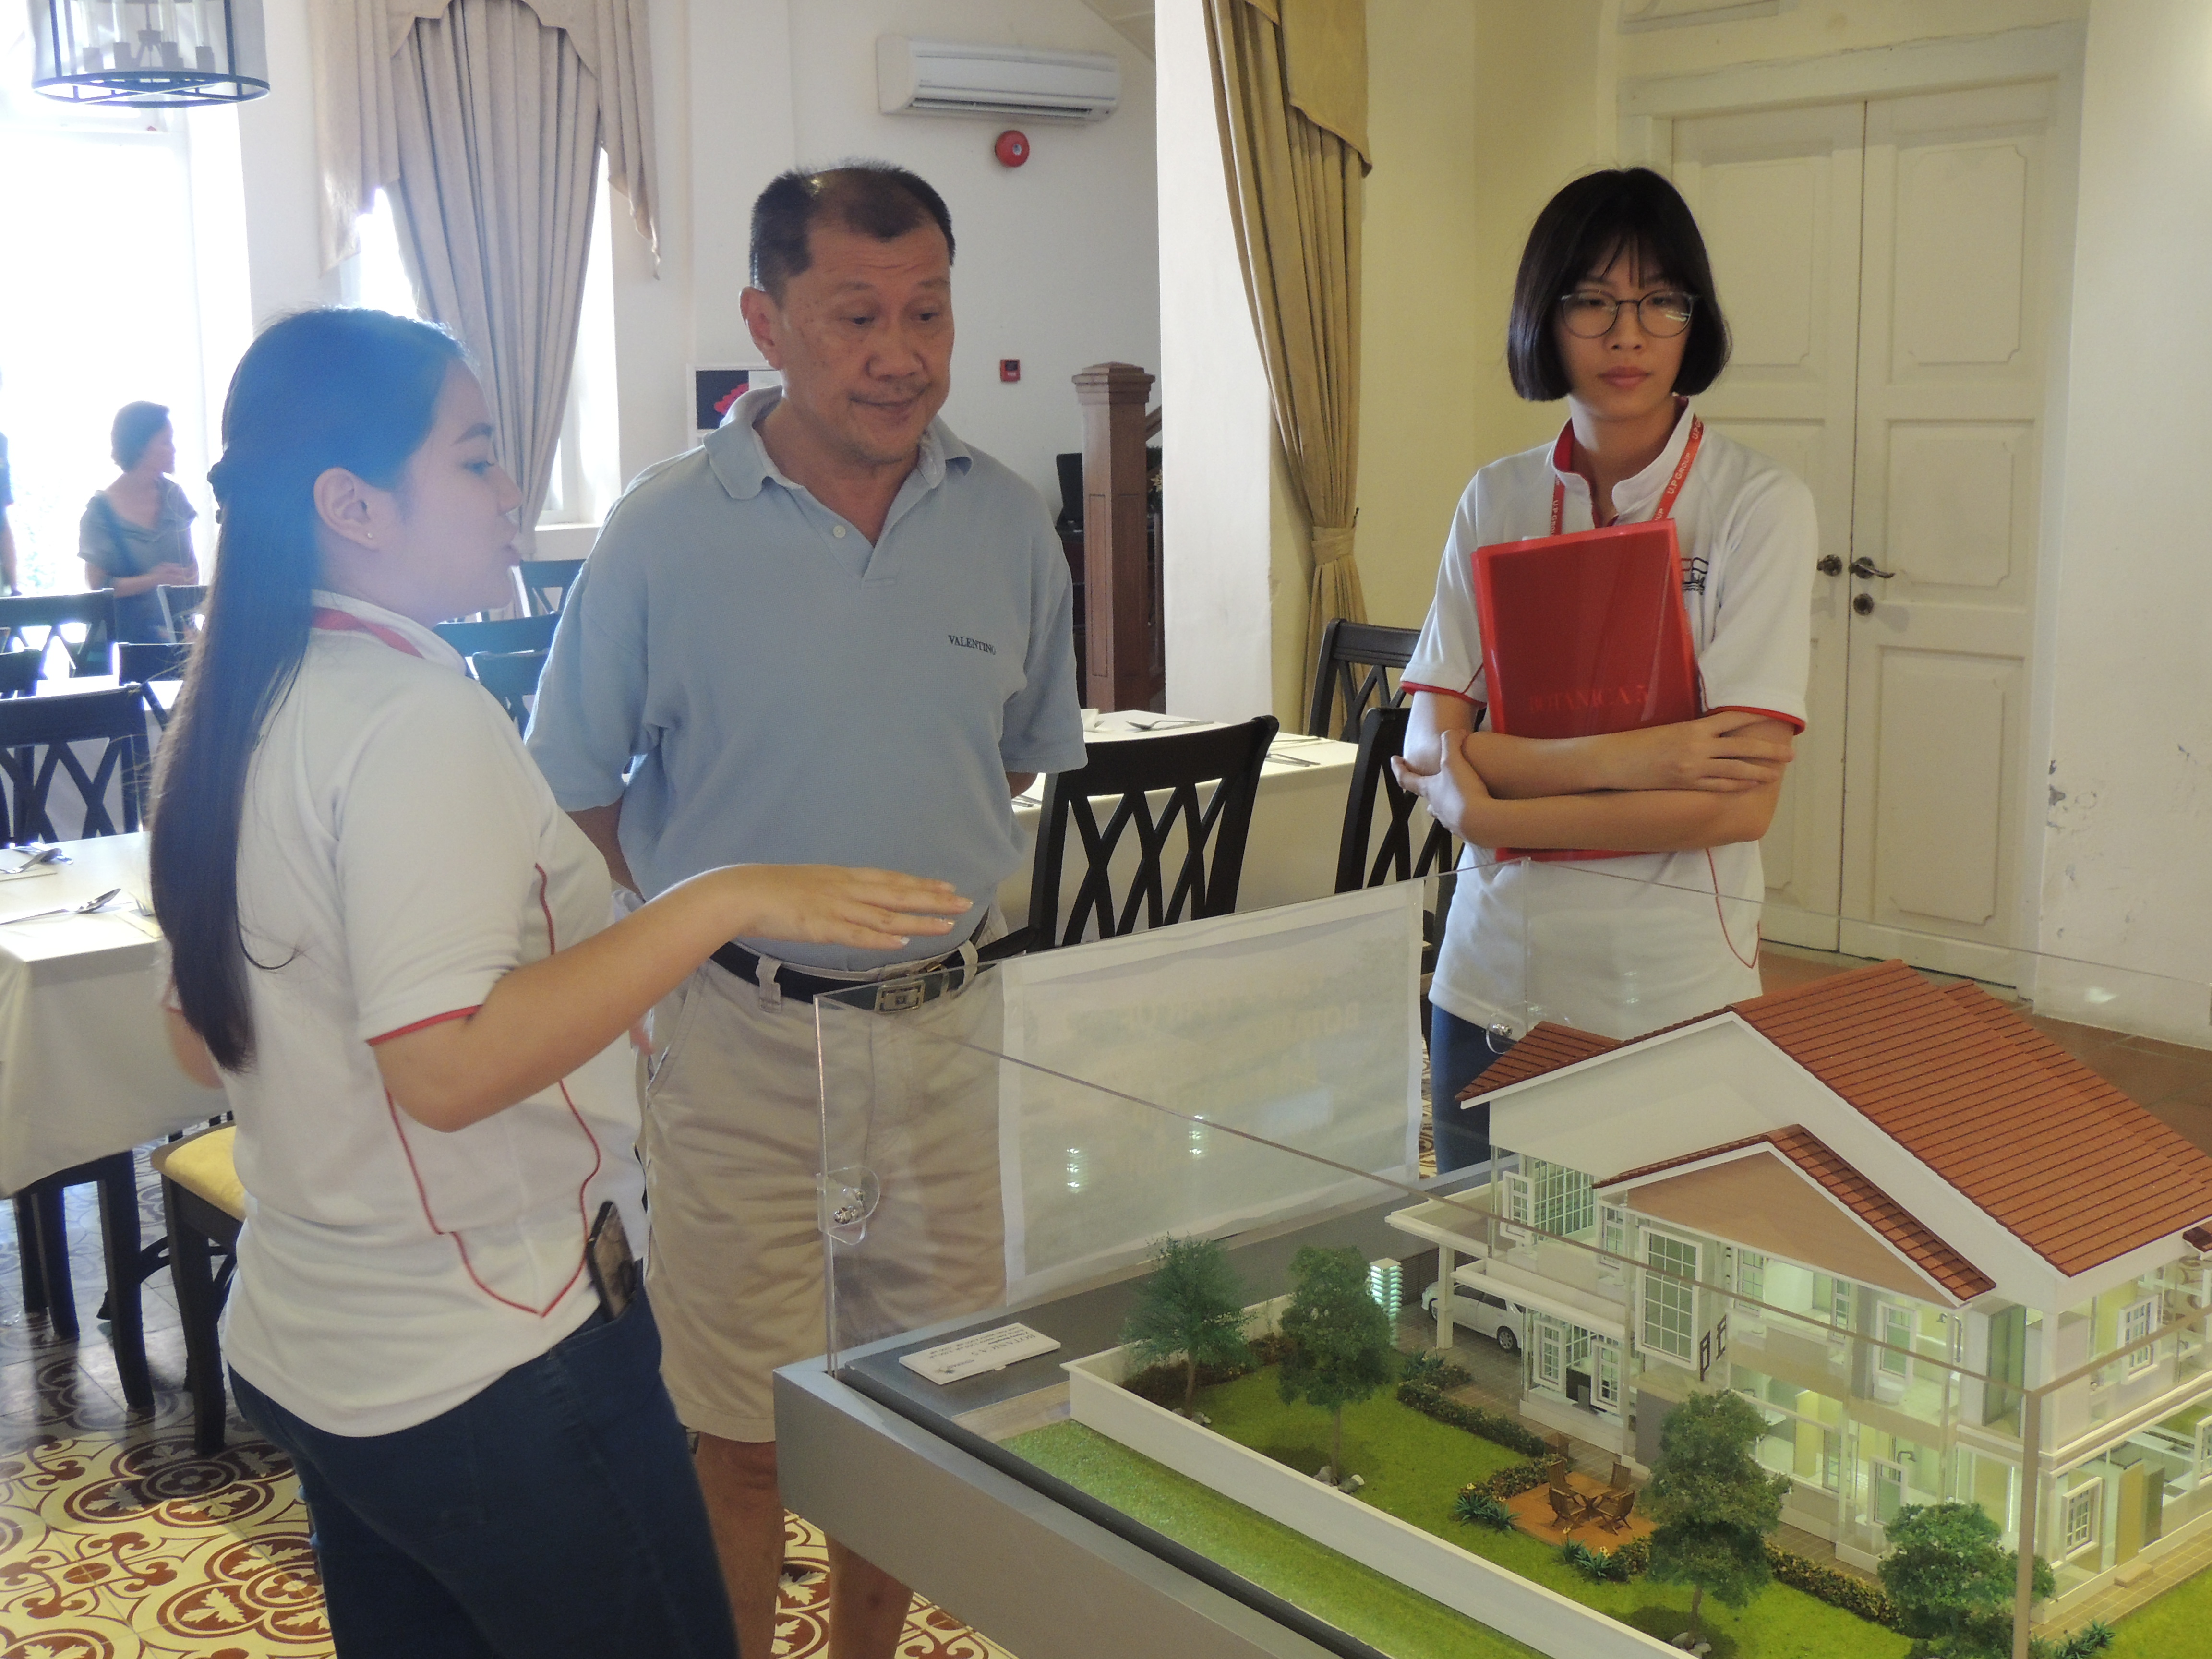
    Most importantly, my property study tours are not just about learning and investing—they’re also about having fun! You’ll get to travel, explore new locations, and enjoy meaningful conversations with fellow property enthusiasts. It’s a great way to bond with like-minded individuals, share experiences, and build lasting relationships in a relaxed and enjoyable setting. See you on the next trip!