Tag: property investment

  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    31 October – 6 November 2026

    MALAYSIA · PROPERTY · GLOBAL MARKETS

    This week’s roundup highlights an important message for the property industry: market activity does not automatically translate into successful property sales. Financing, affordability, product suitability and actual demand remain critical.

    Malaysia saw fresh foreign participation in residential development, a rebound in property loan applications and renewed attention on the country’s unsold housing stock. Internationally, Singapore’s REIT sector showed encouraging rental performance, while institutional capital continued flowing into Dublin’s prime office market.

    Malaysia – 3 stories

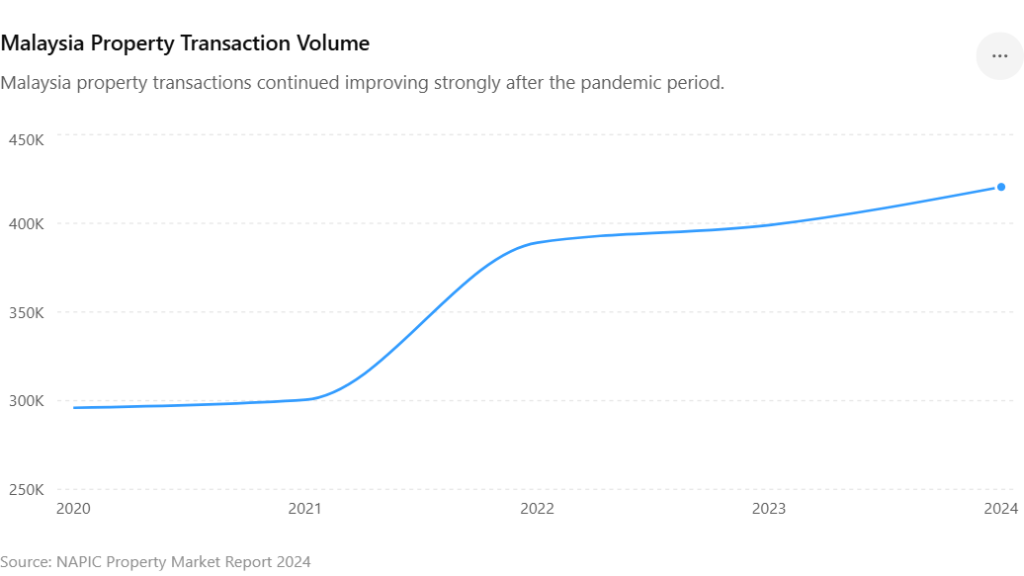
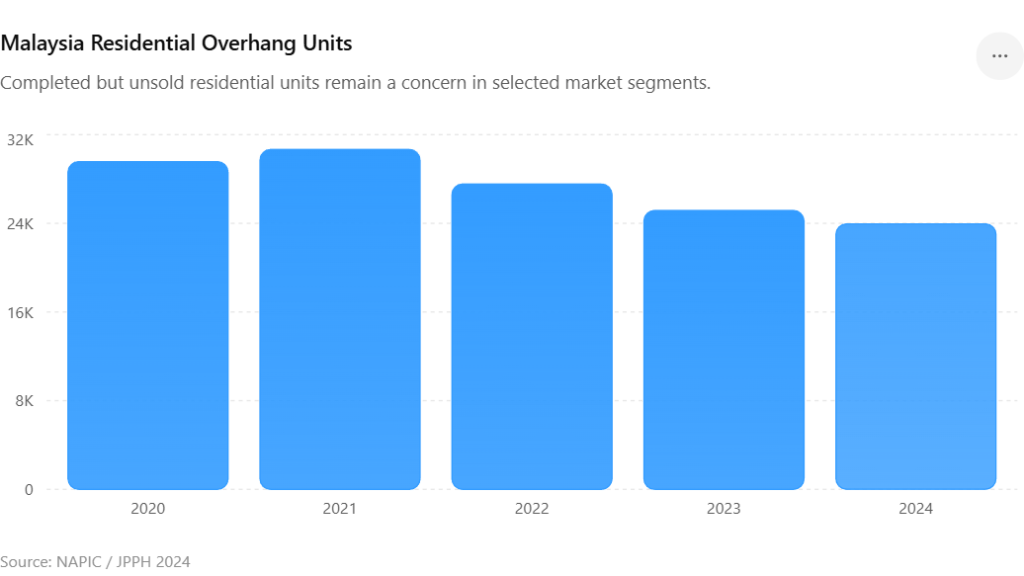
    1. Malaysia’s property overhang: Why unsold homes remain a concern
    What Happened

    A report published by The Star on 2 November highlighted the continuing challenge of unsold completed properties in Malaysia.

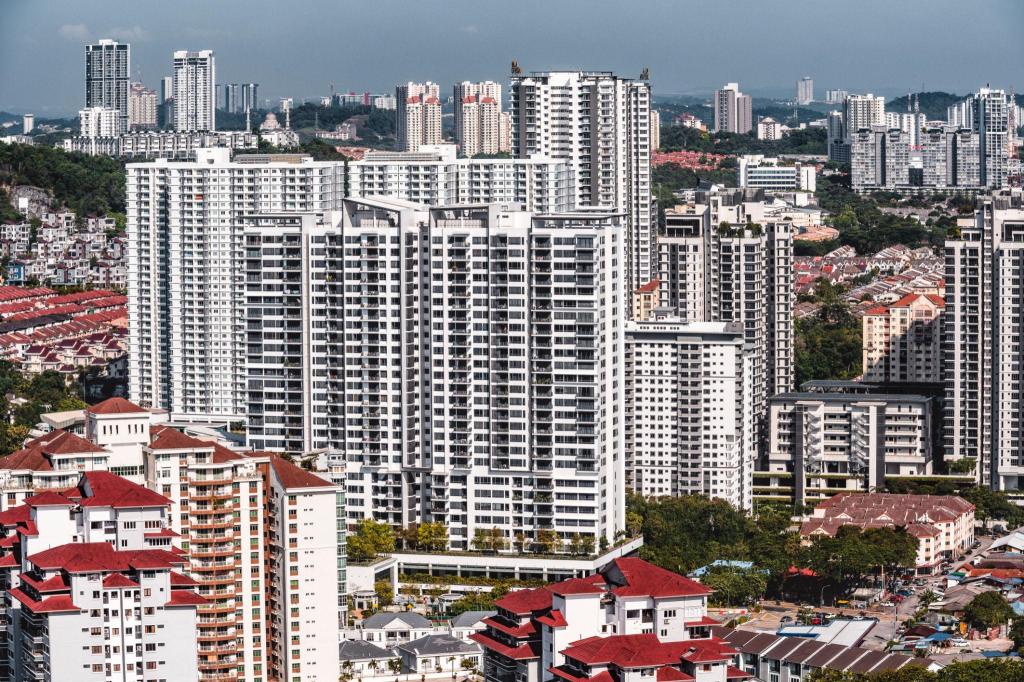
    According to JLL Malaysia, Kuala Lumpur had 6,343 completed, unsold serviced apartments valued at approximately RM6.41 billion, while Johor recorded 9,946 units valued at approximately RM6.29 billion.

    One concern is the mismatch between the type of homes being developed and the needs of potential buyers. Some serviced apartments, particularly smaller units of around 500 sq ft, were designed with short-term accommodation or investment demand in mind. They may not necessarily meet the needs of young families looking for practical homes close to their workplaces. The Star

    Why It Matters

    The overhang issue is not simply about having too many properties in the market. It is about whether the available properties match what buyers can afford and genuinely need.

    A development can have attractive facilities, a good marketing campaign and a prominent location, but still struggle if the product does not fit its target market.

    Miichael’s Review

    I have always believed that property development must begin with understanding the market, not simply identifying available land and deciding what to build.

    Before launching a project, developers need to understand the local population, household income, employment patterns, affordability and competing supply.

    The number of units sold during a launch is also not the only measure of success. We need to look at whether buyers can secure financing, whether the property meets their needs and whether there is genuine demand in the secondary and rental markets.

    This is precisely why buyer education and proper property assessment matter.

    Source: The Star – Targeted solutions to property overhang

    2. Japanese developer Mitsui Fudosan joins Paramount’s 458-unit Kuala Lumpur project

    What Happened

    Japanese real estate group Mitsui Fudosan announced on 4 November that it would participate in The Ashbourne, a residential development in Ampang, Kuala Lumpur, together with Malaysian developer Paramount Corporation.

    The project comprises:

    • 458 residential units.
    • A site area of approximately 161,179 sq ft.
    • Unit sizes of approximately 1,491 to 2,661 sq ft.
    • A 42-storey development.
    • Approximately six minutes’ walk from Ampang Park LRT and MRT stations.
    • Planned construction commencement in November 2026 and completion in 2030.
    • Sales scheduled to begin in December 2026.

    Mitsui Fudosan stated that its participation brings its Malaysian involvement to 12 projects in total, including residential, commercial, rental housing and logistics developments. News Releases

    Why It Matters

    This is a positive indication of continued foreign developer confidence in Malaysia’s property market.

    More importantly, the partnership combines an established international developer’s experience with a local developer’s market knowledge.

    The project’s location, proximity to public transport and relatively spacious unit sizes are also worth noting.

    However, foreign participation alone does not guarantee project success. Pricing, buyer profile, product positioning and market absorption will still determine its performance.

    Miichael’s Review

    I see this as an encouraging development for the Malaysian property industry.

    International developers bring different perspectives, capital, design approaches and operating experience. These partnerships can raise standards and introduce new ways of looking at residential development.

    But I would still ask the same questions that I ask about every project:

    Who is the intended buyer? Is the pricing supported by the surrounding market? Is there sufficient demand for the unit sizes being offered? And what will the resale and rental prospects look like?

    A good developer and a good location are important. But buyers still need to assess the property based on its fundamentals.

    Source: Mitsui Fudosan – Participation in The Ashbourne project

    3. Property loan applications rebound, but approvals tell a different story
    What Happened

    According to MBSB Research, Malaysia’s property loan applications increased by 2.6% year-on-year to RM502.7 billion in the first nine months of 2026.

    However, approved property loans declined by 0.6% to RM211.2 billion over the same period.

    September showed a stronger improvement:

    • Property loan applications increased 12.6% year-on-year.
    • Approved loans rose 7.2%, following a 13.3% decline in August.

    The figures suggest that buyer interest may be stabilising, but the overall approval trend remains a concern. EdgeProp.my

    Why It Matters

    This is an important distinction for both buyers and developers.

    Loan applications represent interest and intention. Loan approvals indicate how much of that interest has successfully progressed through the financing process.

    A buyer may like a property, submit an offer and even pay a booking fee. But if the financing is not approved, the transaction may not proceed.

    For developers, this means that sales performance should not be assessed only by bookings or expressions of interest.

    Miichael’s Review

    This is one area I believe the property industry needs to pay much more attention to.

    Understanding mortgage eligibility should be part of the buyer discovery process, not something buyers only start thinking about after selecting a property.

    Before committing, buyers should understand their credit profile, debt commitments, income documentation, financing eligibility and affordability.

    For developers and sales teams, educating buyers on financing can also help improve the quality of enquiries and reduce avoidable booking cancellations.

    A property purchase is not just about whether someone wants to buy. It is also about whether that person is financially ready and able to complete the purchase.

    Source: EdgeProp – Property loan rebound leaves developers facing mixed outlook

    International – 2 stories from 2 countries

    4. Singapore REITs: Positive rental reversions offer encouraging signs
    What Happened

    Singapore’s REIT sector reported encouraging rental trends during the latest reporting season.

    According to the Singapore Exchange, of the 20 trusts reporting numerical rental reversion figures, 19 recorded at least one positive portfolio, market or segment measure.

    The positive rental reversions were seen across several property categories, including:

    • Retail
    • Office
    • Industrial
    • Logistics
    • Data centres
    • Rental housing

    For example, Suntec REIT recorded third-quarter 2026 rental reversions of 7.3% for Singapore office space and 11.2% for Singapore retail.

    CapitaLand Integrated Commercial Trust reported 4.6% for retail and 7.1% for office over the first nine months of 2026. Singapore Exchange (SGX)

    Why It Matters

    Rental reversions indicate that landlords are securing higher rents when existing leases are renewed or new leases are signed.

    This is an encouraging sign of tenant demand and the ability of certain properties to maintain or improve their income-generating potential.

    However, positive rental reversions do not automatically mean higher distributions to investors. Occupancy, financing costs, currency movements and acquisitions also affect REIT performance.

    Miichael’s Review

    I find this particularly interesting because it reminds us that property investment is ultimately about income sustainability.

    When evaluating an investment property, we should not focus only on its purchase price or potential capital appreciation.

    We should also examine the rental market, tenant demand, occupancy levels, rental renewals and operating costs.

    A property that consistently attracts tenants and maintains rental income may have stronger fundamentals than one that relies heavily on future price appreciation.

    For investors, the quality of income matters.

    Source: Singapore Exchange – S-REITs: Positive Rental Reversions, Mixed Distributions

    5. Ireland: €100 million investment strengthens Dublin’s prime office development pipeline

    What Happened

    Irish property investment company IPUT Real Estate announced a further €100 million equity commitment from the Ireland Strategic Investment Fund (ISIF) on 2 November.

    The investment will support the development of 29 Earlsfort Terrace in Dublin, forming part of IPUT’s wider €500 million prime office development programme.

    Other highlights include:

    • IPUT raised more than €400 million in new equity during 2026.
    • It secured €300 million in new revolving credit facilities.
    • Its portfolio includes 30 prime assets totalling more than 2 million sq ft in Dublin city centre.
    • The development pipeline includes 350,000 sq ft of office space across two projects.

    The company said demand for high-quality, well-equipped office space in Dublin remains strong, with prime supply struggling to keep pace. IPUT

    Why It Matters

    This is a good example of institutional capital supporting property development where investors see a clear demand and supply opportunity.

    Rather than investing simply because a particular market is attractive, the funding is directed towards a specific type of asset: high-quality office space in a location where the developer believes demand exceeds available supply.

    Miichael’s Review

    What I find interesting is the emphasis on asset quality and actual occupier demand.

    The office market has changed significantly over the years. Not every office building will perform equally well.

    Businesses are increasingly selective about location, facilities, accessibility, sustainability and the overall working environment.

    This reinforces an important investment principle: not all properties within the same market have the same potential.

    The real opportunity often lies in identifying the right asset, in the right location, serving the right market.

    Source: IPUT Real Estate – €100 million investment commitment

    Worth Watching

    A few other developments deserve attention beyond our five main stories:

    1. Malaysia’s national planning direction: The Fifth National Physical Plan (RFN5) sets land-use priorities through 2040, while the Third National Urbanisation Policy (DPN3) sets out 90 actions through 2035. These frameworks cover housing, transport, climate resilience and urban development. EdgeProp

    2. Malaysia’s industrial property pipeline: Daiso opened its RM1.2 billion global distribution centre in Pulau Indah, expected to serve 27 countries and territories. This is a tangible example of industrial and logistics investment moving into operation. EdgeProp

    3. Penang’s cross-sea LRT connection: TRC Synergy confirmed a 30% participation interest in the RM2.69 billion contract for the Macallum–Penang Sentral extension. The proposed connection could improve island–mainland connectivity, although delivery remains subject to construction and commissioning. EdgeProp

    My Takeaway This Week

    There is a common thread running through this week’s property news.

    Property success is not determined by supply, launches or marketing activity alone. It depends on whether a property meets genuine market demand.

    Malaysia’s unsold housing stock reminds us that product-market mismatch can create long-term challenges. The mortgage figures show that buyer interest must be supported by financing ability. Meanwhile, the international stories demonstrate the importance of rental performance, asset quality and occupier demand.

    For developers, this means understanding the market before building.

    For investors, it means looking beyond projected returns.

    For buyers, it means doing proper research before committing.

    My approach remains simple:

    Discover Better. Decide Smarter.

    Disclaimer

    This article is intended for general information and educational purposes only. It does not constitute financial, investment, legal or property purchasing advice. Readers should conduct their own due diligence and seek advice from qualified professionals before making any property-related decisions.

    From the desk of

    Miichael Yeoh

    Property Strategist
  • Home Loan Rejected in Malaysia? 8 Steps to Improve Your Chances of Approval

    Home Loan Rejected in Malaysia? 8 Steps to Improve Your Chances of Approval

    You found the property. You worked out the monthly instalment. You submitted your documents. Then the bank said no. What went wrong?

    For many property buyers, getting a home loan approved is one of the most stressful parts of buying a property.

    Some applicants earn a reasonable salary but still struggle to obtain financing. Others have been working for years, have savings in the bank and believe they are financially ready, only to discover that their loan application does not meet the bank’s requirements.

    The first reaction is often frustration.

    Some blame the bank. Others immediately approach another bank, hoping for a different answer.

    But before submitting another application, there is a more important question to ask:

    What exactly made the bank uncomfortable with your application?

    A bank does not assess a property buyer based on salary alone. It considers repayment ability, existing financial commitments, credit history, income documentation, the property and its own lending criteria. Bank Negara Malaysia explains that CCRIS is one source of information used by financial institutions, not a blacklist or a credit approval decision by itself.

    The good news? A rejected application does not necessarily mean you can never obtain a home loan. But your next step should be based on the actual reason for the rejection, not guesswork.

    Here are eight steps every property buyer should understand.

    1. Find out why your loan was rejected

    This is where you should begin.

    Do not immediately submit applications to five other banks. If the underlying problem remains unresolved, you may end up with several unsuccessful applications without improving your financial position.

    Contact the bank or mortgage officer who handled your application. Ask for clarification on the main factor affecting the decision and whether there is anything you can address before applying again.

    The reason might involve:

    • Your monthly debt commitments being too high.
    • Late payments or arrears recorded in your credit history.
    • Income that the bank cannot adequately verify.
    • Incomplete or inconsistent documents.
    • Employment or business income that is considered uncertain.
    • The requested loan amount or tenure.
    • The property valuation or the bank’s assessment of the property.

    The bank may not disclose every detail of its internal assessment, but even a general explanation can help you identify your next move.

    The principle is simple: fix the reason for rejection before trying again.

    2. Check your CCRIS and CTOS reports

    Your credit record can influence how a bank assesses your application.

    CCRIS, operated by Bank Negara Malaysia, records credit information reported by participating financial institutions. This includes financing facilities, repayment conduct and relevant application information.

    You can access your CCRIS report through the official eCCRIS portal:

    https://eccris.bnm.gov.my

    You may also review your CTOS credit report through:

    https://ctoscredit.com.my

    Look for the following:

    • Late or missed repayments.
    • Outstanding arrears.
    • Credit facilities you may have overlooked.
    • Incorrect personal or account information.
    • Records that you do not recognise.
    • Existing or recently submitted credit applications.

    If you find an error, contact the relevant institution or credit reporting agency to dispute it. If you have genuine arrears, speak to the lender about bringing the account up to date and establishing a manageable repayment arrangement.

    Do not assume that paying an overdue amount today will immediately erase the previous repayment history. Updates take time, and historical information may remain visible for a period.

    One important point: CCRIS is not a blacklist. Bank Negara Malaysia also confirms that a rejection by one financial institution does not automatically mean every other bank will reject you. Different banks have different lending policies and risk assessments.

    3. Understand your Debt Service Ratio (DSR)

    One of the most important things to understand before applying for a home loan is your Debt Service Ratio, commonly known as DSR.

    In simple terms, DSR compares your monthly debt repayments with the income recognised by the bank.

    A simplified illustration is:

    DSR = Total monthly debt commitments ÷ Recognised monthly income × 100%

    Suppose your recognised monthly income is RM6,000.

    Your existing monthly commitments are:

    • Car loan: RM900
    • Personal loan: RM400
    • Other financing commitments: RM200

    Your total existing commitments are RM1,500.

    If the proposed housing loan instalment is RM1,800, your total monthly debt commitments would become RM3,300.

    Your illustrative DSR would be:

    RM3,300 ÷ RM6,000 × 100% = 55%

    This is only an illustration, not a universal approval threshold. Banks differ in how they recognise income, calculate commitments and determine acceptable DSR levels. They may also consider living expenses and other risk factors.

    The practical lesson is that a salary that looks sufficient on paper may not leave enough recognised repayment capacity for the proposed loan.

    What can you do?

    • Review all existing loans and financing commitments.
    • Avoid taking on unnecessary new debt before applying.
    • If appropriate and financially sensible, reduce outstanding commitments.
    • Reassess the property price and proposed loan amount.
    • Consider a longer tenure only if it is available and suitable for your circumstances, understanding that it can increase total interest or profit paid over time.

    Do not take a new personal loan just to make your down payment unless you have fully assessed the additional repayment burden. It may worsen the very problem you are trying to solve.

    4. Make your income easy for the bank to verify

    A bank needs evidence that your income is genuine, sufficient and reasonably sustainable.

    This is particularly important for commission earners, self-employed individuals, business owners and people whose income varies from month to month.

    If you are a salaried employee, prepare the documents requested by the bank, which may include:

    • Recent payslips.
    • Bank statements showing salary credits.
    • Employment confirmation or other employment records.
    • EPF statements.
    • Income tax documents, where required.

    If you are self-employed or run a business, the bank may request:

    • Personal and business bank statements.
    • Income tax returns and supporting tax documents.
    • Business registration documents.
    • Financial statements or management accounts.
    • Evidence of business income and its consistency.

    The exact requirements vary by bank and applicant profile.

    Here is a common mistake: an applicant declares a certain income, but the supporting documents do not clearly demonstrate where that income comes from or whether it is recurring.

    For example, a business owner may have substantial money flowing through a bank account. However, total deposits are not necessarily the same as personal income or business profit.

    Prepare a clear, consistent and truthful record of your income. Explain unusual deposits or variable earnings where necessary, and provide supporting evidence when requested.

    The objective is not merely to show that money enters your account. It is to demonstrate the income you can reasonably sustain.

    5. Reduce unnecessary financial commitments before applying

    Your existing commitments affect how much room you have for a new housing loan.

    Review your car financing, personal loans, credit card balances and other credit facilities. Understand how the bank will treat each commitment in its assessment.

    If you have outstanding credit card balances, reducing them may improve your overall financial position. However, do not assume that cancelling a card or paying down one facility will automatically produce a particular DSR or guarantee approval.

    Prioritise actions that genuinely improve your ability to repay.

    Also, avoid taking on a new car loan, personal financing or other major commitment just before applying for a mortgage unless it is necessary and you have assessed its impact.

    A property purchase is a long-term financial commitment. You should not have to make your entire financial life fragile just to qualify for the loan.

    6. Choose a property that fits your actual borrowing capacity

    This is where many buyers need to rethink their approach.

    They start by asking, “Which property do I want?”

    A better starting point is, “What property can I finance comfortably, while still managing my other financial responsibilities?”

    A bank’s approval is not the same as proof that a property is affordable for your household.

    Even if you qualify for a particular loan amount, you still need to account for expenses such as:

    • The down payment.
    • Legal fees and stamp duty, where applicable.
    • Valuation and financing-related costs.
    • Renovation, furnishing and moving expenses.
    • Maintenance charges and sinking fund contributions, where applicable.
    • Insurance or takaful.
    • Repairs, vacancies and other property-related costs if the property is intended for rental.

    Do not spend every ringgit of your savings on the purchase and leave yourself without a financial buffer.

    If the loan amount is too high, consider a less expensive property, a larger down payment if it does not deplete your emergency reserves, or delaying the purchase while you strengthen your finances.

    A more modest property that you can sustain may be a better decision than a larger property that leaves you financially stretched.

    7. Get your financing assessed before committing to the property

    One of the most expensive mistakes is assuming that a loan will be approved simply because the buyer has a stable job or has received an encouraging initial assessment.

    An initial eligibility check or preliminary indication is not necessarily a final loan approval.

    Before paying a booking fee or committing to a purchase, speak to a qualified mortgage officer or financing adviser. Provide accurate information about your income, existing commitments, credit record and intended property.

    Ask questions such as:

    • Based on my current financial position, what loan amount may be realistic?
    • How does the bank calculate my recognised income?
    • What commitments will affect my eligibility?
    • What documents do I need to prepare?
    • Are there any issues I should address before submitting a formal application?
    • What happens if the property valuation is lower than the purchase price?

    Remember that an eligibility estimate does not guarantee approval. Final approval remains subject to the bank’s assessment, verification and applicable conditions.

    It is also important to understand the purchase agreement and booking terms, including what happens if financing is unsuccessful. Do not assume that every booking fee is automatically refundable.

    8. If your loan is rejected, follow a recovery plan

    A rejection should prompt a review of your financial position, not a rushed attempt to obtain another loan.

    Use this sequence:

    Step 1 — Request clarification. Ask the bank what factors affected the decision.

    Step 2 — Review your credit reports. Check CCRIS and CTOS for repayment issues, outstanding facilities and errors.

    Step 3 — Recalculate your affordability. Review your income, debt commitments and proposed housing instalment.

    Step 4 — Strengthen your documentation. Resolve inconsistencies and prepare complete supporting records.

    Step 5 — Address the actual weakness. This may involve reducing commitments, regularising arrears, correcting an error, improving income documentation or reconsidering the property price.

    Step 6 — Seek a suitable financing assessment. Once you understand the issue, discuss your circumstances with an appropriate lender or qualified mortgage adviser. Different banks may assess a case differently, but no one can guarantee approval.

    Step 7 — Apply again when you are ready. Do not reapply simply because time has passed. Reapply when you have a clear reason to believe the application is stronger or better suited to the lender’s criteria.

    If you need more help, Bank Negara Malaysia’s MyKNP initiative provides a route for unsuccessful home-financing applicants to seek guidance through the relevant advisory channels, including AKPK for home financing.

    Find out more through Bank Negara Malaysia:

    https://www.bnm.gov.my/myknp

    If you are already struggling to manage existing debts, seek proper financial counselling before taking on further commitments. AKPK provides financial counselling and debt-management assistance for eligible individuals.

    The bigger lesson: prepare before you fall in love with a property

    Let us look at the problem from a different perspective.

    A home loan application is not simply a form to complete after you have chosen a property. It is an assessment of whether the proposed financing fits your financial circumstances and the lender’s requirements.

    That means the property discovery process should begin before the showroom visit.

    Before choosing a property, understand your finances. Before applying for a loan, review your credit record. Before making a commitment, assess whether the purchase remains manageable if your expenses rise, your income changes or the property takes longer than expected to generate rental income.

    At Property Discovery System™, we believe that buyers should be equipped to make informed decisions rather than relying on assumptions.

    The objective is not merely to obtain a loan.

    It is to obtain financing for a property you can afford, sustain and live with comfortably over the long term.

    Because getting a loan approved is only the beginning. Being able to manage it well is what matters next.

    Discover Better. Decide Smarter.

    From the desk of

    Miichael Yeoh

    Property Strategist

    Disclaimer: This article is for general educational purposes and does not constitute individual financial, credit or legal advice. Loan approval criteria and documentation requirements vary by financial institution and applicant. Approval is never guaranteed.

  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    17–23 October 2026

    🇲🇾 MALAYSIA PROPERTY MARKET

    STORY 1 — Sime Darby Property’s RM418.5 Million Kulai Land Deal: What Comes Next?

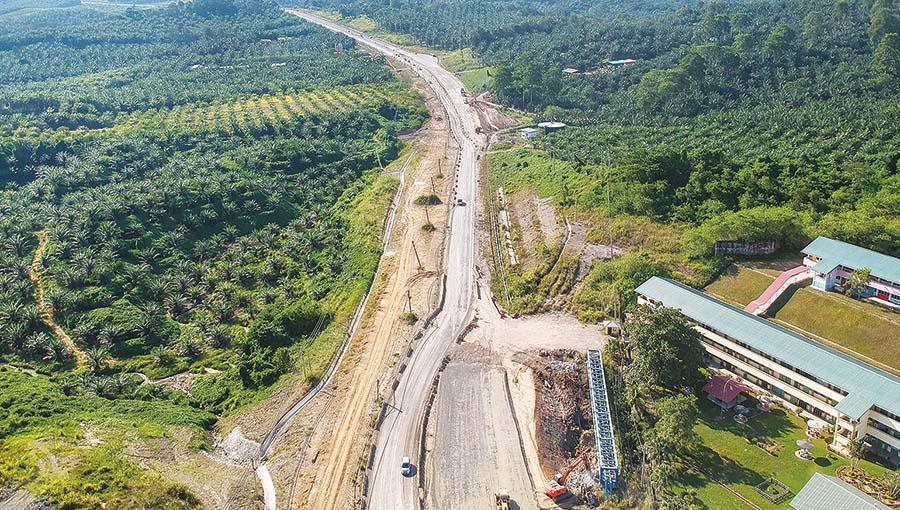
    Illustrative image of agricultural land in Kulai, Johor; not the exact acquisition parcel.

    What Happened?

    On 20 October, EdgeProp reported further details about the proposed land acquisition by Sime Darby Property Berhad, which is seeking shareholder approval for its purchase of approximately 556.96 acres of freehold land from SD Guthrie Berhad.

    The proposed transaction involves:

    • Purchase price: RM418.5 million.
    • Land area: Approximately 556.96 acres.
    • Estimated gross development value (GDV): RM3 billion.
    • Location: Kulai, within the Johor–Singapore Special Economic Zone growth corridor.
    • Planned development: A residential and commercial township.
    • First phase: Targeted for launch in 2028.
    • Development horizon: Approximately 10–15 years.

    The purchase price is approximately 4.23% below the RM437 million market valuation cited in the acquisition circular. Sime Darby Property’s extraordinary general meeting is scheduled for 3 November 2026 to seek approval from non-interested shareholders. The acquisition remains subject to the required approvals and other conditions. EdgeProp

    Sources: EdgeProp — Kulai land acquisition and shareholder approval; Sime Darby Property’s official announcement.

    Why It Matters

    This is a long-term landbank strategy, not an immediate housing launch.

    A developer acquiring a large parcel of land must consider more than the purchase price. Infrastructure, planning approvals, construction costs, future household demand and the pace of development all influence whether the investment ultimately creates value.

    The Johor–Singapore Special Economic Zone provides a potential economic growth context, but its existence does not guarantee that every development within the corridor will succeed.

    The estimated RM3 billion GDV is also not the same as profit. Development costs, financing, infrastructure obligations and the timing of sales still matter.

    Miichael’s Review

    I find this development interesting because it highlights the difference between buying land with potential and creating a successful township.

    A large landbank gives a developer flexibility to phase development according to market conditions. It can avoid bringing too many homes to market at once and adjust the product mix as the surrounding area develops.

    However, the ultimate question is whether the future township will meet genuine housing and commercial demand.

    I would examine:

    1. The employment and population growth expected in the surrounding area.
    2. Existing competing residential supply.
    3. Planned transport and infrastructure improvements.
    4. The affordability of the proposed homes.
    5. The developer’s ability to phase construction responsibly.

    My view: Land acquisition is the beginning of a property strategy, not proof of a successful investment. The real test will be how well the developer translates location potential into a sustainable community.


    STORY 2 — CapitaLand Malaysia Trust’s Distributable Income Rises 32.2%

    llustrative image of a logistics property relevant to Malaysia’s industrial and logistics real estate sector.

    What Happened?

    CapitaLand Malaysia Trust (CLMT) reported stronger third-quarter 2026 results, with distributable income increasing 32.2% year-on-year.

    For the quarter ended 30 September 2026, the trust reported:

    Financial measureQ3 2026Year-on-year change
    Distributable incomeRM46.3 million+32.2%
    Distribution per unit1.35 sen+21.6%
    RevenueRM126.5 million+9.1%
    Net property incomeRM79.4 million+14.9%
    Net profitRM47 million+35.5%

    CLMT attributed the stronger performance to contributions from industrial and logistics properties acquired in 2025, positive rental reversions, scheduled rent increases and lower financing costs.

    As at 30 September, overall portfolio occupancy stood at 94.3%, while committed retail occupancy was 93.1%. The trust’s gearing ratio was 38.3%. EdgeProp

    Sources: EdgeProp — CLMT’s third-quarter results, 22 October 2026; CLMT official website.

    Why It Matters

    This is a useful example of how a property investment trust can grow its income through a combination of acquisitions, rental performance and financing management.

    The result also demonstrates why investors should look beyond headline revenue.

    A REIT’s ability to generate distributable income depends on the performance of its properties, occupancy, operating expenses, financing costs and the capital required to maintain and expand its portfolio.

    However, one strong quarter does not establish that future distributions will grow at the same rate.

    Miichael’s Review

    For me, the important point is the relationship between property assets and the income they can sustainably generate.

    When evaluating a REIT, I would ask:

    • Are its properties attracting tenants?
    • Can rental income be maintained or improved?
    • Are acquisitions adding value after financing costs?
    • Is its debt manageable?
    • Are distributions supported by recurring property income?

    Industrial and logistics assets can also diversify a portfolio beyond conventional retail properties.

    But the quality of the underlying assets and the price paid for them remain important.

    My view: Property investment should be evaluated through both asset quality and income sustainability. A large property portfolio is valuable only when its assets can generate attractive returns relative to their costs and risks.


    STORY 3 — IHH Plans an 18-Acre Healthcare Campus in Medini, Johor

    What Happened?

    On 20 October, EdgeProp reported that IHH Healthcare Berhad was acquiring Afiniti Wellness in Iskandar Puteri, with plans to convert the property into an ambulatory care centre.

    The proposed facility will form part of an integrated healthcare campus spanning approximately 18 acres, bringing together the existing Gleneagles Hospital Johor, Afiniti Wellness and IHH’s existing landbank in Medini.

    The new centre is intended to provide consultations, diagnostic services, day surgery and other outpatient treatments.

    Retrofitting work was expected to begin shortly, with operations targeted for the second or third quarter of 2028. The purchase price for Afiniti Wellness was not disclosed. EdgeProp

    Sources: EdgeProp — IHH’s planned Medini healthcare campus, 20 October 2026; IHH Healthcare Malaysia’s official website.

    Why It Matters

    This development highlights the role that specialised facilities can play in shaping a property’s long-term use and value.

    Instead of constructing an entirely new building, IHH plans to adapt an existing property to support a wider healthcare ecosystem.

    The project also reflects how demand for healthcare services can influence commercial property use, particularly in locations where population, business activity and access to specialist services are expected to grow.

    However, the anticipated benefits will depend on actual demand, operating performance and the successful integration of the facilities.

    Miichael’s Review

    I see this as an example of property value being created through the right use, rather than simply through new construction.

    An existing building may become more useful when it is repositioned to meet a specific market need.

    For property developers and investors, the questions are:

    1. Is there sufficient demand for the intended use?
    2. Can the existing building be adapted efficiently?
    3. Will the location support the required customer or patient catchment?
    4. Does the new use create a sustainable operating model?
    5. Can the investment deliver long-term value without excessive capital expenditure?

    This is particularly relevant to commercial property owners considering how to reposition underutilised assets.

    My view: The strongest property strategies begin with understanding demand. Sometimes the opportunity is not to build more, but to make better use of what already exists.


    🌏 INTERNATIONAL PROPERTY WATCH

    🇯🇵 STORY 4 — Japan’s New Condo Market: Fewer Launches, but Prices Keep Rising

    Illustrative image of residential condominiums in Japan.

    What Happened?

    A market report published on 22 October by Japan Property Insight, based on data from the Real Estate Economic Institute, highlighted a striking contrast in the Kinki region, which includes the areas around Osaka, Kyoto and Kobe.

    For September 2026:

    • New condominium launches fell 49.6% year-on-year to 752 units.
    • The average unit price rose 37.6% to ¥70.75 million.
    • The average price per square metre increased 19.7% to ¥1.15 million.
    • The first-month contract rate was 62.6%.
    • Unsold inventory stood at 3,007 units.

    For the first half of Japan’s fiscal 2026, new launches in the region fell 8.6% to 6,557 units, while the average price rose 8.4% to ¥60.1 million. The first-month contract rate fell below 70% for the first time in four years. Japan Property Insight

    Source: Japan Property Insight — September 2026 condominium market report, published 22 October.

    Why It Matters

    The figures illustrate a situation where fewer new properties are being offered to buyers even as average prices rise.

    But an important distinction is necessary: the increase in average prices does not mean every existing property became 37.6% more valuable.

    When fewer units are launched, the mix of properties entering the market can change significantly. A smaller number of expensive projects can push up the overall average.

    At the same time, a lower contract rate suggests that sales absorption is not keeping pace with the higher price environment as comfortably as before.

    This is why property-market analysis needs to examine supply, prices and actual sales together.

    Miichael’s Review

    I find this an important lesson for buyers and investors.

    A market can report higher average prices while simultaneously experiencing weaker sales activity.

    That means we should not automatically interpret rising prices as evidence of stronger underlying demand.

    I would examine:

    • Whether the properties being launched are comparable with those launched previously.
    • Whether completed inventory is accumulating.
    • Whether buyers can afford the new price levels.
    • Whether transactions support the asking prices.
    • Whether the market is becoming increasingly divided between premium and more affordable properties.

    My view: Rising prices are only one part of the story. Understanding who can afford to buy, what is being supplied and how quickly units are selling gives us a much clearer picture of the market.


    🇺🇸 STORY 5 — US Homebuilding Weakens as Mortgage Costs Pressure Affordability

    Illustrative image of a US residential construction site.

    What Happened?

    On 20 October, Reuters reported that US single-family homebuilding fell in September as higher mortgage rates and elevated construction costs weighed on demand.

    According to the US Commerce Department’s Census Bureau:

    • Single-family housing starts fell 4.6% month-on-month to an annualised rate of 859,000 units, the lowest level since September 2025.
    • Single-family building permits fell 4.0% to an annualised rate of 845,000 units, the lowest since March 2023.
    • The average 30-year fixed mortgage rate was 7.40% in the preceding week, according to Freddie Mac data cited by Reuters.

    Separately, the National Association of Home Builders/Wells Fargo Housing Market Index fell three points to 29 in October, its lowest reading since June 2012.

    Builders were facing a combination of higher financing costs, elevated material and energy expenses, labour constraints and weak buyer demand. Reuters

    Sources: Reuters — US housing starts and permits weaken, 20 October 2026; The Wall Street Journal — US homebuilder confidence falls to a 14-year low.

    Why It Matters

    The US housing market illustrates how financing costs affect both sides of the property market.

    For buyers, higher mortgage rates reduce purchasing power and increase monthly repayments.

    For developers, weaker demand can make new projects more difficult to justify, particularly when construction costs remain elevated.

    There is also a longer-term concern: reducing new construction may ease immediate inventory pressure, but it does not automatically solve an underlying housing shortage.

    The challenge is to deliver homes at prices that buyers can afford while ensuring that developments remain financially viable.

    Miichael’s Review

    This reinforces a principle I have always considered important in property decisions: affordability is not determined by the asking price alone.

    A home may appear reasonably priced, but if financing costs push the monthly repayment beyond the buyer’s comfortable limit, demand can weaken.

    For developers, this means product planning must be connected to the actual purchasing capacity of the target market.

    For buyers, it means understanding the total cost of ownership rather than focusing only on the initial price.

    I would look at:

    1. Household income and debt commitments.
    2. Mortgage rates and repayment sensitivity.
    3. Construction costs and the supply of comparable homes.
    4. The relationship between asking prices and completed transactions.
    5. Whether a property remains affordable under less favourable conditions.

    My view: Sustainable property demand requires a realistic match between price, financing and household purchasing power. Without that balance, both buyers and developers can find themselves under pressure.


    WORTH WATCHING

    Here are the developments I would monitor over the next few weeks.

    MarketWhat to watchWhy it matters
    Malaysia — JohorShareholder approval and subsequent planning steps for the Kulai land acquisitionDetermines how the proposed township progresses from landbank strategy to implementation.
    Malaysia — REITsCLMT’s next results and distribution performanceHelps assess whether income growth is sustainable beyond one quarter.
    Malaysia — MediniProgress on the planned ambulatory care centreShows whether existing commercial property can be successfully repurposed for specialised demand.
    JapanNew condo launches, contract rates and unsold inventoryHelps distinguish price increases caused by supply composition from stronger underlying demand.
    United StatesMortgage rates, housing starts and builder confidenceIndicates whether financing pressure continues to affect homebuyers and future housing supply.

    MY TAKEAWAY THIS WEEK

    This week’s property news reinforces a common theme across different markets.

    In Malaysia, developers are positioning their landbanks for future growth, a REIT is reporting stronger income and an existing property is being repurposed for specialised healthcare use.

    In Japan, new condominium supply has contracted sharply even as average prices have risen. In the United States, higher mortgage costs are putting pressure on homebuilding and affordability.

    The circumstances differ, but the underlying questions remain similar.

    • Is there genuine demand for the property?
    • Is the asking price supported by market evidence?
    • Can the intended buyers afford the property?
    • Can the asset generate sustainable income?
    • Does the development create lasting value for its owners and surrounding community?

    A property can have a strong location, attractive design or impressive headline value and still be the wrong investment if the fundamentals do not support it.

    My approach remains simple: research first, evaluate objectively and make decisions based on the fundamentals.

    Look beyond the price. Understand the fundamentals before making the decision.

    Miichael Yeoh
    PROPERTY STRATEGIST

  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    10–16 October 2026

    LOOK BEYOND THE PRICE

    Five stories. Three Malaysian developments. Two international markets. One objective: helping buyers and investors make better-informed property decisions.

    🇲🇾 MALAYSIA PROPERTY MARKET

    STORY 1 — Why Are Malaysian Property Developers Becoming More Cautious?

    What Happened?

    A property industry survey reported by The Edge Malaysia on 15 October revealed that 63% of surveyed developers had no plans to launch residential projects in the second half of 2026.

    The survey by the Real Estate and Housing Developers’ Association Malaysia (REHDA) covered 181 respondents in Peninsular Malaysia.

    Key findings included:

    • 114 of 181 respondents had no plans for residential launches in the second half of 2026.
    • The remaining respondents planned to launch 18,696 units.
    • 77% of respondents reported financing difficulties during the first half of 2026.
    • 59% of respondents with relevant data reported unsold completed residential units as at 30 June 2026.
    • Among respondents who reported unsold completed units, 32% said some of their stock had remained unsold for more than three years.

    Developers cited market conditions, approval delays and existing unsold inventory as reasons for their cautious approach. The Edge Malaysia

    Source: The Edge Malaysia — REHDA property industry survey, 15 October 2026

    Why It Matters

    This is an important signal for Malaysia’s property market.

    A high number of new launches does not automatically mean a healthy market. What matters is whether homes are priced appropriately, buyers can obtain financing and completed units find genuine occupants.

    The financing figures are particularly noteworthy. Demand for housing may exist, but prospective buyers still need to qualify for loans and manage their financial commitments.

    Developers must also balance construction costs against what their target customers can realistically afford.

    Miichael’s Review

    I see this as a reminder that property development must follow real demand, not simply market excitement.

    When developers become more cautious, buyers should look beyond promotional campaigns and ask some practical questions:

    1. How many comparable properties are already available?
    2. Are existing developments attracting genuine buyers?
    3. Are asking prices supported by recent transactions?
    4. Can the intended buyers realistically obtain financing?
    5. Is the development designed for actual occupants or mainly for investors hoping to resell?

    The survey also suggests that different property categories are performing differently. Buyers should therefore avoid treating the entire Malaysian market as one uniform market.

    My view: A more selective market can reward careful research. Buyers need to distinguish between a property that is attractively marketed and one that is genuinely well positioned.


    STORY 2 — Malaysia Reports 1,726 Revived Housing Projects: What Does This Mean for Buyers?

    What Happened?

    On 14 October, EdgeProp Malaysia reported on the Housing and Local Government Ministry’s update that 1,726 sick or abandoned private housing projects had been revived since 2023.

    The projects involved approximately:

    • 199,643 housing units
    • RM158 billion in gross development value
    • 1,542 sick projects completed with Certificates of Completion and Compliance
    • 147 projects restored to smooth status
    • 37 abandoned projects resolved through physical completion or arrangements benefiting buyers

    The ministry also reported that, as at 31 August 2026, Kuala Lumpur still had seven projects classified as abandoned and another 12 classified as sick.

    The government has set a target of eliminating sick and abandoned housing projects by 2030. EdgeProp

    Source: EdgeProp Malaysia — Housing project rehabilitation update, 14 October 2026

    Why It Matters

    A stalled housing project can create serious financial and emotional difficulties for buyers.

    They may have paid deposits and progressive payments, committed to housing loans and continued paying rent while waiting for their homes.

    The reported rehabilitation figures are encouraging, but one distinction matters: a project being revived does not necessarily mean every unit has been completed and handed over.

    The different outcomes must be examined individually.

    For prospective buyers, this is also a reminder to assess the delivery record of a developer and the actual status of a project before committing.

    Miichael’s Review

    I welcome efforts to protect homebuyers and resolve problematic developments.

    However, I would assess a project’s progress using evidence rather than announcements alone.

    Before buying into an ongoing development, I would want to understand:

    • The developer’s financial and delivery track record.
    • The project’s construction progress.
    • Whether the required approvals and legal arrangements are in place.
    • Whether there are known disputes or rehabilitation issues.
    • The expected completion date and the evidence supporting it.

    For buyers already affected by a stalled project, the available rehabilitation route and legal position are particularly important.

    My view: The real measure of success is not simply how many projects have been declared revived. It is how many affected buyers ultimately receive the homes or appropriate resolutions they were promised.


    STORY 3 — IOI Properties Advances Its Proposed RM7.66 Billion REIT Listing

    What Happened?

    IOI Properties Group Berhad advanced its proposed Malaysian real estate investment trust (REIT) listing after signing an underwriting agreement with six financial institutions.

    According to EdgeProp Malaysia on 12 October:

    • The proposed REIT has nine initial assets.
    • The portfolio was valued at approximately RM7.66 billion as at 31 May 2026.
    • The proposed offering could involve up to 2.2 billion units.
    • The underwriting agreement covers 165 million offer units, subject to the offering’s allocation provisions.
    • The prospectus was targeted for the fourth quarter of 2026, with listing targeted by year-end.

    The initial portfolio includes IOI City Mall, six hotels and two office properties.

    These are proposed listing arrangements; the announcement did not mean the IPO had already been completed. EdgeProp

    Source: EdgeProp Malaysia — IOI Properties advances proposed REIT IPO, 12 October 2026

    Why It Matters

    A REIT provides a way for investors to gain exposure to income-generating property through a listed investment vehicle rather than purchasing an entire property themselves.

    For the property sector, a listing can provide another route for capital management and potentially broaden investor participation.

    However, a large property portfolio does not automatically make a REIT an attractive investment.

    Investors still need to examine rental income, occupancy, financing costs, debt levels, asset valuations and the proposed distribution policy.

    Miichael’s Review

    This is worth watching because it connects property ownership with capital markets.

    For individual investors, a REIT may offer a different way to participate in commercial property, hotels and retail assets without directly managing a building.

    But the decision should be based on the investment’s fundamentals.

    I would look carefully at:

    1. The quality and location of the underlying assets.
    2. The sustainability of rental income.
    3. Financing costs and gearing.
    4. The proposed distribution yield and how it is calculated.
    5. Whether the offering valuation is reasonable relative to comparable investments.

    My view: The important question is not merely how much the portfolio is worth. It is whether its assets can generate sustainable income at a valuation that makes sense for investors.


    🌏 INTERNATIONAL PROPERTY WATCH

    🇦🇪 STORY 4 — Dubai Buyers Shift Towards Completed Homes as the Market Becomes More Selective

    What Happened?

    A third-quarter 2026 residential market report from betterhomes, reported by Khaleej Times on 15 October, showed a shift towards completed homes in Dubai.

    Key findings included:

    • Sales of ready residential properties rose 16% quarter-on-quarter.
    • Secondary-market transactions reached 10,055, with a total value of Dh27.1 billion.
    • Secondary-market transactions accounted for 29% of total residential sales, up from 24% in the second quarter.
    • Overall residential sales totalled 34,615 transactions during the quarter, broadly unchanged from the previous quarter.
    • Median apartment prices declined 2.4% between June and September, while villa and townhouse prices fell 2.3%.

    Despite the quarterly price declines, prices remained higher than a year earlier. Rental enquiries also rose sharply, although median rents eased in several market segments. Khaleej Times

    Source: Khaleej Times — Dubai ready-home sales jump 16%, 15 October 2026

    Why It Matters

    The figures suggest that buyers are becoming more selective about the type of property they purchase.

    Completed homes offer advantages that off-plan properties cannot immediately provide: buyers can inspect the actual unit, assess the surrounding community and potentially receive rental income sooner.

    However, the reported shift does not mean off-plan properties have become universally unattractive. Different buyers have different financial circumstances, objectives and risk tolerances.

    The decline in quarterly prices also highlights the importance of comparing actual transactions rather than relying exclusively on advertised prices.

    Miichael’s Review

    This is an interesting development for property investors.

    A completed property may provide greater visibility into its condition, rental demand and surrounding environment. An off-plan property may offer different advantages, but it also requires buyers to assess delivery risk and future market conditions.

    I would compare both options using the same criteria:

    • Total acquisition cost.
    • Expected rental income.
    • Maintenance and other holding expenses.
    • Financing commitments.
    • Comparable transaction prices.
    • Exit options if market conditions change.

    My view: A completed property is not automatically a better investment, just as an off-plan property is not automatically a better bargain. The right choice depends on the numbers, the risks and the buyer’s objectives.


    🇨🇦 STORY 5 — Canadian Home Sales Fall Again as Mortgage Rates Weigh on Buyers

    What Happened?

    On 16 October, Reuters reported that Canadian home sales declined again in September as higher mortgage rates and expectations of a possible interest-rate increase weighed on market activity.

    According to the Canadian Real Estate Association (CREA):

    • National home sales fell 2.3% month-on-month in September, following a 0.7% decline in August.
    • Sales were down 7.7% year-on-year on an unadjusted basis.
    • The Home Price Index declined 0.4% month-on-month and 3.4% year-on-year.
    • New property listings fell 1.8% from August.
    • The seasonally adjusted sales-to-new-listings ratio slipped to 48.8%, below its long-term average of 54.7%.

    At the time of the report, financial markets were pricing in the possibility of a 25-basis-point Bank of Canada rate increase in December. This was a market expectation, not a confirmed policy decision. Reuters

    Source: Reuters — Canadian home sales fall in September as mortgage rates increase, 16 October 2026

    Why It Matters

    The Canadian market demonstrates how financing conditions can affect property transactions.

    Even when prospective buyers want to purchase homes, higher mortgage costs can reduce borrowing capacity or make buyers more cautious about committing.

    A slower market may give some buyers more time to negotiate. However, it does not automatically mean that every property is attractively priced.

    Local conditions also matter: national figures can conceal significant differences between cities, neighbourhoods and property types.

    Miichael’s Review

    For me, the main lesson is the relationship between financing and affordability.

    When interest rates rise, a buyer may qualify for a smaller loan or face a higher monthly repayment. That can change which properties are financially sensible.

    Before committing, I would ask:

    1. Can I afford the repayments if borrowing costs increase?
    2. Does the property remain affordable after taxes, insurance and maintenance?
    3. Is the asking price supported by recent comparable transactions?
    4. Can I sustain ownership if resale takes longer than expected?
    5. Am I buying because the property suits my needs, or because I expect prices to rise?

    My view: A property purchase should be financially sustainable even when market conditions become less favourable. Buyers who understand their financing limits are better placed to make measured decisions.


    WORTH WATCHING

    Here are five developments I would monitor over the coming weeks.

    AreaWhat to watchWhy it matters
    MalaysiaDeveloper launch plans and sales performanceShows whether supply is responding to genuine demand.
    MalaysiaRehabilitation of sick and abandoned housing projectsBuyers need evidence of actual progress and resolution.
    MalaysiaIOI Properties’ proposed REIT prospectusProvides details for evaluating the portfolio, pricing and distribution policy.
    UAECompleted-home prices, rents and transaction activityHelps investors assess whether market conditions support their objectives.
    CanadaMortgage rates, sales activity and home-price trendsProvides an indication of how financing conditions affect affordability and demand.

    MY TAKEAWAY THIS WEEK

    This week’s property news reinforces a principle that applies across markets:

    Property decisions should be based on fundamentals, not headlines.

    In Malaysia, developers are becoming more cautious, housing-project rehabilitation remains important, and a proposed REIT listing offers another way to participate in property investment.

    In Dubai, buyers are showing greater interest in completed homes, while prices and rents are becoming more competitive in some segments.

    In Canada, higher borrowing costs are weighing on transactions.

    These markets have different conditions, but the underlying questions are similar.

    • Is the property priced reasonably?
    • Is there genuine demand?
    • Can the buyer afford to own it comfortably?
    • Does the investment generate sustainable income?
    • Are the risks manageable if the market changes?

    A property can look attractive on paper but still be unsuitable for a particular buyer.

    Look beyond the price. Understand the fundamentals before making the decision.

    Miichael Yeoh
    PROPERTY STRATEGIST
    miichaelyeoh.com

  • New Launch vs Subsale: Which Property Should You Buy?

    New Launch vs Subsale: Which Property Should You Buy?

    Written by: Miichael Yeoh

    A new property feels safer. An existing property feels more predictable.

    But neither statement is necessarily true.

    A new launch may offer attractive incentives, modern facilities and a fresh building. A subsale property may allow you to inspect the actual unit, understand the surrounding neighbourhood and investigate existing rental demand.

    So, which should you buy?

    The answer depends on what you’re paying, what you’re getting, what risks you’re taking and what you expect the property to deliver.

    Let’s look beyond the showroom and examine the decision properly.

    1. The Malaysian Property Market Is Giving Buyers a Reason to Be Selective

    Malaysia’s property market remained active in the first half of 2026.

    The first-half property market report recorded 187,320 property transactions worth RM105.12 billion. At the same time, 33,094 completed residential units remained unsold, valued at approximately RM17.78 billion.

    Developers also launched 27,832 residential units during H1 2026, with reported sales performance of 16.6%.

    These figures don’t mean new launches are bad or that subsale properties are automatically better.

    They tell us something more useful.

    Buyers should not assume that a new launch is a good purchase simply because a developer has launched it, or that an existing property is good value simply because someone is reselling it.

    Every property needs to be evaluated on its own merits.

    And that brings us to the first important difference.

    2. New Launch vs Subsale: What Are You Actually Buying?

    Let’s start with the basic distinction.

    A new-launch property is generally purchased directly from a developer, often before construction is completed.

    A subsale property is an existing property purchased from its current owner.

    That difference affects much more than the age of the building.

    Property Condition

    New launch: The property may still be under construction, so the finished quality cannot yet be fully assessed.

    Subsale: You can inspect the actual unit and building before making your decision.

    Pricing

    New launch: The price is set by the developer, with incentives or rebates subject to the terms offered.

    Subsale: The price may be negotiable, depending on the seller and comparable market transactions.

    Rental Income

    New launch: Rental income generally begins only after completion, handover and preparation for tenants.

    Subsale: Rental income may begin sooner if the property is ready and suitable for tenants.

    Construction Risk

    New launch: An uncompleted project carries delivery and construction-related risks.

    Subsale: A completed property avoids the risk of waiting for construction completion, although other risks remain.

    Defects and Renovation

    New launch: You may need to furnish the unit and address defects identified at handover.

    Subsale: You may need to repair existing defects, renovate or replace ageing fittings.

    Facilities and Management

    New launch: The long-term quality of building management has yet to be demonstrated.

    Subsale: You can assess the existing facilities, maintenance and management standards.

    Rental Demand

    New launch: Future rental demand must be estimated using market evidence and competing supply.

    Subsale: Existing rental listings and tenancy evidence may help you assess demand, although future conditions can change.

    Main Uncertainty

    New launch: Completion, final quality, future supply and market conditions.

    Subsale: Hidden defects, maintenance costs, building condition and future resale demand.

    Neither option wins every category.

    The mistake is choosing based on the benefits of one option while ignoring its disadvantages.

    3. Is a New Launch Cheaper Than a Subsale?

    This is where many buyers need to slow down.

    Imagine two condominiums in a similar location.

    Property A: New launch

    • Developer’s selling price: RM600,000
    • Advertised rebate: 8%
    • Indicative price after the rebate: RM552,000

    Property B: Subsale

    • Seller’s asking price: RM530,000
    • Negotiated purchase price: RM515,000

    At first glance, the subsale property appears cheaper.

    But are we comparing the same thing?

    What is the actual transaction price of comparable units?

    Does the new launch include furnishing, parking or other items that would otherwise cost extra?

    Does the subsale unit require RM30,000 in renovation?

    Are the maintenance fees comparable?

    Are both properties equally attractive to future tenants?

    What are the legal, financing and other acquisition costs applicable to each transaction?

    Until you answer these questions, you don’t know which property offers better value.

    Look Beyond the Advertised Price

    Developer incentives can reduce the buyer’s effective cost, but their value depends on the actual terms and what is included.

    Similarly, a subsale seller’s asking price may not reflect the final negotiated price.

    Compare the complete acquisition cost rather than relying on the headline figure.

    And remember:

    A lower purchase price does not automatically mean a better investment.

    4. The Hidden Difference: When Can the Property Start Working for You?

    For investors, this may be one of the most important differences.

    Suppose you purchase a new-launch condominium that will take several years to complete.

    During that period, you may have construction-stage financing payments, depending on the loan structure. You also have to wait until the property is completed, handed over and ready before rental income can begin.

    Now consider a completed subsale condominium.

    If the unit is in good condition and the rental market is established, you may be able to rent it out after completing the purchase and preparing the unit.

    The difference is time.

    Let’s Use a Simple Illustration

    Assume the subsale property can generate RM2,000 per month in rent once it is ready and occupied.

    If the new launch takes three years to complete, the theoretical gross rental income forgone over those 36 months is:

    RM2,000 × 36 months = RM72,000.

    That is a significant amount.

    But don’t misunderstand the calculation.

    RM72,000 is not a guaranteed loss or a complete comparison of the two investments. It is an illustration of potential gross rental income over that period, assuming the subsale could have been rented continuously.

    Actual results would depend on vacancy, expenses, financing, tenant demand and the timing of rental readiness.

    The new launch might also appreciate during construction. The subsale might need substantial renovation or suffer from weak tenant demand.

    The lesson is not that subsale always wins. It’s that time has a financial value, and investors should calculate it.

    5. Can You Trust the Rental Demand for a New Launch?

    This is a question I would ask before purchasing either type of investment property.

    A developer might describe a project as ideal for young professionals, expatriates or students.

    That may be a reasonable target market.

    But a target market is not proof of rental demand.

    Before buying, investigate:

    • Who actually works or studies nearby?
    • What rents are comparable units achieving?
    • How many similar units are already available?
    • How long do comparable properties typically take to find tenants?
    • What facilities and transport options matter to the intended tenants?
    • How many competing developments are expected to be completed?
    • What will make your property more attractive than the alternatives?

    For a completed subsale unit, you may be able to examine existing rental listings, speak to property managers and investigate actual tenancy evidence.

    For an uncompleted new launch, you will have to make more assumptions about future conditions.

    That doesn’t make the new launch a poor investment.

    It simply means the further you are from observable evidence, the more carefully you need to test your assumptions.

    6. What About Building Quality and Defects?

    One advantage of buying a new residential property from a developer is that qualifying purchases under prescribed housing development agreements have statutory protections, including a defect liability period.

    For standard Schedule G and Schedule H agreements, the defect liability period is generally 24 months from vacant possession, subject to the applicable agreement and legal provisions.

    However, a new building is not necessarily a defect-free building.

    You still need to inspect the unit when it is handed over, document defects and follow the proper procedures for reporting them.

    A subsale property presents a different situation.

    You can inspect the actual unit before purchasing, but you may inherit problems such as:

    • Water leakage
    • Damaged flooring
    • Ageing electrical or plumbing systems
    • Poor renovation work
    • Lift or common-area maintenance issues
    • Inadequate sinking-fund reserves
    • Disputes or management problems

    Some problems are visible. Others may require professional inspection or further investigation.

    For a subsale condominium, I would want to understand the condition of both the individual unit and the overall building.

    A brand-new unit can have defects. An older unit can be well maintained. Age alone does not determine quality.

    Note: The applicable legal protections depend on the type of property, transaction and agreement. Buyers should confirm their position with a qualified property lawyer.

    7. Don’t Ignore the Building’s Management

    This is particularly important when comparing condominiums.

    A new launch may offer an impressive swimming pool, gym, landscaped garden and other facilities.

    But who will maintain them?

    Will the maintenance charges be sustainable for residents?

    Will the facilities remain attractive after several years?

    For a completed property, you have something valuable: evidence of how the building is actually being managed.

    Look at:

    • The condition of common areas
    • Lift maintenance
    • Cleanliness and security
    • Maintenance-charge collection
    • Sinking-fund position
    • Major repairs required
    • Management responsiveness
    • The overall resident experience

    A well-maintained older condominium may provide a better ownership experience than a newer building with poor management.

    Equally, an older building with serious maintenance problems may create expenses that a buyer has underestimated.

    Don’t just compare the units. Compare the buildings behind them.

    8. Which Is Better for First-Time Homebuyers?

    There is no universal answer, but the priorities are different from those of an investor.

    A first-time buyer should consider:

    Affordability: Can you comfortably manage the purchase and ongoing costs?

    Move-in timing: Do you need a home soon, or can you wait for construction to finish?

    Location: Does it work for your job, family, transport needs and daily routine?

    Condition: Are you prepared to manage renovation, repairs or defects?

    Certainty: Would you prefer to inspect an existing unit, or are you comfortable committing to a property that has not yet been completed?

    Future flexibility: If your job or family circumstances change, will the property be reasonably easy to rent out or sell?

    A new launch may suit someone who wants a new home and can wait for completion.

    A subsale may suit someone who wants to inspect the actual property and move in sooner.

    But neither option should stretch your finances to the point that a change in income becomes a crisis.

    Your first property should support your life, not make your life revolve around the mortgage.

    9. Which Is Better for Property Investors?

    For investors, I would focus less on whether the property is new or old and more on the investment case.

    Ask five questions.

    A. What Is My Total Investment?

    Include the purchase price, transaction costs, financing costs, renovation, furnishing and other relevant expenses.

    B. When Can I Realistically Earn Rental Income?

    Account for construction, completion, preparation, vacancy and tenant-finding time.

    C. What Is My Expected Net Return?

    Do not confuse gross rental yield with actual cash flow or net return. Include recurring expenses, vacancy, repairs and financing where relevant.

    D. What Competition Am I Facing?

    Consider both existing properties and future supply.

    E. How Will I Exit?

    Think about the future buyer, resale demand, likely competition and the price at which the property might realistically sell.

    A new launch could offer an attractive opportunity if the price, location, product and future demand justify the purchase.

    A subsale could be attractive if its price is supported by evidence, its condition is acceptable and its rental or owner-occupier demand is sustainable.

    Either could be a poor investment if the numbers don’t work.

    10. The PDS New Launch vs Subsale Decision Test

    Before making a decision, I would compare the two properties using the same framework.

    1. What is the true acquisition cost?

    Include the purchase price, incentives, legal costs, financing and necessary improvements.

    2. What evidence supports the price?

    Look at comparable transactions and the property’s actual features.

    3. What demand exists?

    Investigate owner-occupier demand, tenant demand and the reasons people choose the location.

    4. What are the holding costs?

    Calculate the mortgage, maintenance, repairs, insurance and other recurring expenses.

    5. What risks am I accepting?

    Consider construction, defects, renovation, vacancy, management and future supply.

    6. What is the realistic return?

    Assess net rental income, financing impact, potential capital appreciation and costs.

    7. How will I exit?

    Identify the likely future buyer, resale demand and competing properties.

    The most important point is to compare like with like.

    If the two properties are in different locations, serve different tenant markets or offer different layouts, a simple price comparison may be misleading.

    And if you’re comparing a completed property with one that won’t be ready for several years, timing needs to be part of the analysis.

    So, New Launch or Subsale?

    My answer is straightforward.

    Buy a new launch when the product, price, developer, location and future demand justify the commitment.

    Buy a subsale when the actual property, condition, market evidence and total cost make the purchase worthwhile.

    Don’t choose a new launch just because it is new.

    Don’t choose a subsale just because it appears cheaper.

    And don’t assume that developer incentives, a beautiful showroom or an existing tenant automatically make a property a good investment.

    The right decision comes from understanding what you are buying and why it should meet your needs.

    That is the difference between choosing a property and evaluating a property.

    The Final PDS Insight

    When buyers compare new launches and subsale properties, they often begin with the wrong question:

    “Which one is better?”

    I would start somewhere else.

    “Better for whom, at what price, for what purpose and over what period?”

    A property that suits a first-time homeowner may not suit a rental investor.

    A property that works for a ten-year holding period may not work for someone who needs flexibility within three years.

    And a property that looks attractive today may face very different competition tomorrow.

    There is no shortcut around the discovery process.

    There is only a better way to make the decision.

    Don’t just compare the properties. Discover the decision behind them.

    Property Discovery System™

    Discover Better. Decide Smarter.


  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    Week in Review | Saturday, 3 October – Friday, 9 October 2026

    Explore five property updates from Malaysia, Australia and the UK, covering Budget 2027 housing measures, infrastructure delivery and changing market conditions.


    🇲🇾 STORY 1 — Budget 2027: New Stamp Duty Relief for First-Time Homebuyers

    What Happened?

    On 9 October 2026, Prime Minister Anwar Ibrahim tabled Budget 2027, proposing stamp duty exemptions for eligible first-time homebuyers.

    The proposed measures are:

    • Homes priced up to RM500,000: Full stamp duty exemption on the loan agreement and instrument of transfer.
    • Homes priced up to RM750,000: Full exemption on the first RM500,000, with a 50% exemption on the remaining amount.
    • Proposed eligibility period: Sale and purchase agreements executed from 1 January 2027 to 31 December 2030.

    The government also proposed stamp duty relief for transactions involving the rehabilitation of abandoned housing projects. Prime Minister’s Office Malaysia

    Sources: Prime Minister’s Office of Malaysia — Budget 2027 speech · The Star — First-home stamp duty announcement

    Why It Matters

    Stamp duty can be a significant upfront expense for a homebuyer.

    Reducing this cost could make it easier for some first-time buyers to complete a purchase, particularly those already stretching their savings to cover the deposit, legal fees, moving expenses and basic furnishing.

    However, there is an important distinction between making a home cheaper to purchase and making it affordable to own.

    Monthly instalments, maintenance charges, insurance, repairs and emergency savings remain part of the equation.

    Miichael’s Review

    I welcome measures that reduce the barriers to homeownership.

    But I would not advise anyone to rush into buying a property simply because an incentive is available.

    Before making a decision, buyers should ask themselves three questions:

    1. Can I comfortably afford the monthly repayments?
    2. Will I still have sufficient cash reserves after completing the purchase?
    3. Is this the right property for my needs, location and long-term plans?

    The proposed exemption is useful, but the final eligibility rules and implementation details must also be checked.

    My view: A government incentive should improve a sound property decision, not become the reason for making one.


    🇲🇾 STORY 2 — RM20 Billion Housing Guarantee to Support 80,000 First-Time Buyers

    What Happened?

    Budget 2027 provides for housing financing guarantees of up to RM20 billion through the Housing Credit Guarantee Scheme (SJKP), with the aim of assisting 80,000 first-time buyers.

    The scheme particularly targets people who may struggle to obtain conventional housing financing because they are self-employed or do not receive a fixed monthly income.

    The government also announced nearly RM1 billion for housing initiatives, including Rumah Mesra Rakyat and Program Residensi Rakyat. Four new housing projects were announced for Kulai in Johor, Nilai in Negeri Sembilan, Paya Rumput in Melaka and Pertang Valley in Terengganu. Prime Minister’s Office Malaysia

    Sources: Prime Minister’s Office of Malaysia — Budget 2027 housing measures · The Star — RM20 billion SJKP guarantee

    Why It Matters

    This addresses one of the practical challenges facing Malaysian homebuyers: access to financing.

    Some self-employed individuals have sufficient income to meet repayments but find it difficult to satisfy conventional lending requirements because their earnings fluctuate or are documented differently.

    A financing guarantee can help eligible applicants access housing loans. However, it does not mean every applicant will automatically receive loan approval.

    There is also a wider issue to consider.

    Helping more people obtain financing is only part of the solution. The market must also provide homes that buyers can genuinely afford, in locations that suit their work, family needs and daily routines.

    Miichael’s Review

    This measure is particularly relevant to younger buyers, entrepreneurs and people with non-traditional income arrangements.

    However, I would like to see how the scheme works in practice.

    How accessible will it be? What are the eligibility conditions? Will the homes available to these buyers match their budgets?

    Financing access and housing affordability must work together.

    Otherwise, we may help people qualify for loans without necessarily helping them find suitable homes.


    🇲🇾 STORY 3 — Sabah Pan Borneo Highway: Infrastructure Delivery Matters More Than Announcements

    What Happened?

    The Auditor-General’s Report 2/2026, tabled on 5 October, highlighted cost increases and delivery problems affecting Sabah Pan Borneo Highway Phase 1.

    The report stated that contract costs had risen to RM18.96 billion, compared with the original RM17.91 billion.

    As at 31 March 2026, only 4 of the 35 work packages had been completed.

    The report also identified site-readiness and land-acquisition problems, RM513.99 million in variation orders approved beyond authorised limits, and RM41.37 million in delayed utility claims. These are figures reported in the audit, and the completion count relates to the position at the stated date. EdgeProp

    Source: EdgeProp Malaysia — 5 October property and infrastructure digest, reporting on the Auditor-General’s Report 2/2026.

    Why It Matters

    Infrastructure can influence property values by improving access to employment, commercial centres, tourism destinations and essential services.

    But there is a difference between a project being announced, a project being constructed and a project being completed and operational.

    Delays can postpone the economic benefits that were expected to support surrounding areas.

    For buyers and investors, this means that a property’s location should be evaluated against infrastructure that is actually available, as well as projects that remain under construction.

    Miichael’s Review

    When evaluating property near a major infrastructure project, I would not rely on a developer’s location map alone.

    I would examine:

    • Which sections of the road are already operational?
    • How much travel time will actually be saved?
    • Are employment opportunities and commercial activities growing nearby?
    • Will utilities and public services be sufficient for future development?
    • Is the property priced as though future improvements have already been delivered?

    Infrastructure creates potential, but execution determines when—and whether—that potential becomes real.

    This is an important lesson for property buyers in every state, not just Sabah.


    🌏 INTERNATIONAL PROPERTY WATCH

    🇦🇺 STORY 4 — Australia: Housing Prices Fall for a Sixth Consecutive Month

    What Happened?

    National Australia Bank’s October Housing Monitor, published on 7 October, reported that dwelling prices across Australia’s combined capital cities fell 1.2% month-on-month in September 2026.

    This marked the sixth consecutive monthly decline. Prices were 6.4% below their March 2026 peak.

    NAB also revised its forecast to an 8% decline in capital-city dwelling prices over 2026, with a possible peak-to-trough decline of 11%.

    The median time a property spent on the market increased to 41 days, the highest level since late 2020. These figures reflect NAB’s analysis and forecasts, not guaranteed future outcomes. NAB

    Source: National Australia Bank — October 2026 Housing Monitor

    Why It Matters

    The downturn has broadened beyond the markets that initially showed the greatest weakness.

    For buyers, falling prices and longer selling periods may create more room for negotiation. Sellers may need to be more realistic about pricing and the time required to secure a buyer.

    But a declining market does not automatically mean every property is a bargain.

    A property bought at a lower price can still be a poor investment if rental demand is weak, financing costs are high or the local economy deteriorates.

    Miichael’s Review

    I would not look at falling prices in isolation.

    For investors, the more important questions are:

    • Is the purchase price attractive relative to comparable properties?
    • Can rental income reasonably cover the holding costs?
    • Is the local employment base resilient?
    • Can the investment withstand a longer period of weak prices?
    • Would I still want to own this property if the market took several years to recover?

    The best buying opportunity is not necessarily when prices fall the most. It is when the price, risk and long-term fundamentals make sense together.


    🇬🇧 STORY 5 — United Kingdom: Buyer Confidence Weakens While Rental Demand Remains Firm

    What Happened?

    The Royal Institution of Chartered Surveyors (RICS) published its September UK Residential Market Survey on 6 October.

    The survey reported:

    • New buyer enquiries: Net balance of -22%, compared with -18% in August.
    • Agreed sales: Net balance of -18%, compared with -16% in August.
    • House-price sentiment: Net balance of -32%, compared with -28% in August.
    • Tenant demand: Net balance of +23%.
    • Expected rental growth: Net balance of +37% for the following three months.

    The figures suggest weaker buyer sentiment and sales activity alongside continued rental demand. RICS

    Source: RICS — UK Residential Survey, September 2026

    Why It Matters

    The sales and rental markets do not always move in the same direction.

    In the UK, buyers were becoming more cautious while rental demand remained comparatively strong.

    One important clarification: RICS net balances measure the difference between respondents reporting increases and those reporting decreases. A -32% house-price balance does not mean that actual house prices fell by 32%.

    For property investors, rental demand is only one part of the equation. Purchase price, mortgage costs, taxes, maintenance, regulation and net rental yield all matter.

    Miichael’s Review

    This is a good example of why property investors should separate capital-growth expectations from rental fundamentals.

    A market may offer rental opportunities even when transaction activity is weak. But strong rental demand alone does not guarantee a good investment.

    Investors need to understand what remains in their pocket after financing, maintenance, taxes and other expenses.

    Rental demand is a useful signal. Net returns and the ability to sustain ownership are what ultimately matter.


    WORTH WATCHING

    Over the coming weeks, I would pay particular attention to four developments.

    1. Malaysia’s Budget 2027 implementation

    The proposed stamp duty exemptions are encouraging, but the final eligibility conditions and implementation documents will be important. Buyers should not assume that every transaction automatically qualifies.

    2. Financing access for first-time buyers

    The RM20 billion SJKP guarantee is a substantial measure. The next question is how effectively it translates into approved financing and sustainable homeownership.

    3. Infrastructure execution in Malaysia

    The Pan Borneo audit highlights the importance of monitoring actual construction progress, costs and completion dates. Future property decisions should be based on realistic delivery expectations.

    4. International borrowing costs and market conditions

    Australia and the UK show why buyers and investors must continue to monitor financing costs, transaction activity, prices and rental conditions rather than relying on a single market headline.


    MY TAKEAWAY THIS WEEK

    This week reinforces a principle I have always believed in: a property decision should never be based on price alone.

    Malaysia is trying to reduce barriers to homeownership, but buyers still need sustainable financing and suitable homes.

    Australia reminds us that prices can continue falling longer than investors expect.

    The UK shows that sales and rental conditions can move in different directions.

    And the Pan Borneo audit reminds us that infrastructure announcements only create lasting value when projects are delivered.

    For buyers and investors, the questions remain the same:

    • Can I afford it comfortably?
    • Is there genuine demand?
    • Does the location have the infrastructure and economic activity to support it?
    • Do the numbers work under conservative assumptions?
    • Would this still be a sensible decision if the market did not rise as quickly as I hoped?

    Look beyond the price. Understand the fundamentals before making the decision.

    Miichael Yeoh
    PROPERTY STRATEGIST
    www.miichaelyeoh.com

    Thank you for subscribing!

    Please check your email to confirming your subscription.

  • Malaysia Budget 2027: What Property Buyers, Investors and Developers Need to Know

    Malaysia Budget 2027: What Property Buyers, Investors and Developers Need to Know

    By Miichael Yeoh | Property Discovery System(PDS)

    Malaysia’s Budget 2027 has introduced several measures that could influence the country’s property market, from first-home ownership and housing financing to the rehabilitation of abandoned housing projects.

    But what do these announcements actually mean for Malaysians considering a property purchase?

    A stamp duty exemption may reduce the upfront cost of buying a home. A housing loan guarantee may help certain buyers access financing. Public housing and infrastructure investments may create opportunities in selected locations.

    Yet none of these measures automatically makes a property affordable, a development attractive or an investment profitable.

    For homebuyers, investors and developers, the more important question is how these policies affect real property decisions.

    Here is my assessment of the key property-related measures in Malaysia Budget 2027 and what they could mean for the market, including Penang.

    1. First-home buyers: Stamp duty relief expands up to RM750,000

    One of the most significant property announcements in Budget 2027 is the proposed expansion of stamp duty exemptions for first-home purchases.

    According to the Budget speech delivered by Prime Minister and Finance Minister Datuk Seri Anwar Ibrahim on 9 October 2026, the proposed relief will apply to sale and purchase agreements executed from 1 January 2027 to 31 December 2030.

    The proposed structure is:

    • First homes priced up to RM500,000: Full stamp duty exemption on the instrument of transfer and housing loan agreement.
    • First homes priced above RM500,000 and up to RM750,000: Full exemption on the first RM500,000, with a 50% exemption on the remaining amount.

    The proposal is intended to reduce the upfront costs of purchasing a first home.

    Source: Prime Minister’s Office — Budget 2027 speech

    What does this mean for homebuyers?

    For eligible buyers, lower stamp duty can reduce the cash required at the point of purchase.

    The expanded price range is also relevant to buyers who have been looking at homes above RM500,000 but below RM750,000. However, the actual savings will depend on the final implementation rules, the transaction value and the applicable loan terms.

    Buyers should also distinguish between a reduction in transaction costs and an improvement in long-term affordability.

    A home that qualifies for stamp duty relief may still be financially unsuitable if the monthly instalment, maintenance charges, insurance and other commitments stretch the household budget.

    My view: Treat stamp duty relief as a financial advantage, not the main reason to buy a property.

    2. RM20 billion in housing financing guarantees for first-time buyers

    Budget 2027 also provides for up to RM20 billion in housing financing guarantees through the Housing Credit Guarantee Scheme, known as SJKP.

    The scheme is expected to assist approximately 80,000 first-time homebuyers, with particular attention to self-employed individuals and people without fixed monthly incomes.

    This is important because not every prospective buyer has a conventional salary structure.

    Business owners, freelancers and other self-employed individuals may have sufficient earning capacity but face difficulties meeting standard income-documentation requirements.

    SJKP is intended to improve access to housing financing for eligible applicants.

    Source: BERNAMA — Budget 2027 housing financing guarantees

    Does a housing guarantee mean everyone can obtain a loan?

    No. A guarantee does not automatically mean loan approval.

    Applicants must still meet the scheme’s eligibility conditions and the relevant lender’s assessment requirements. Buyers should confirm the applicable financing limits, documentation requirements and repayment obligations before committing to a purchase.

    The key consideration is not simply whether financing is available, but whether the buyer can comfortably sustain the repayments.

    My view: Better financing access is useful when it connects eligible buyers with homes they can genuinely afford. It becomes risky if buyers interpret easier access to financing as a reason to borrow beyond their means.

    3. Can Budget 2027 help revive abandoned housing projects?

    Another significant proposal is the full stamp duty exemption for qualifying transactions involving the rehabilitation of abandoned housing projects.

    The proposed relief covers loan agreements and instruments of transfer executed by contractors or developers rescuing abandoned projects, as well as by the original purchasers involved in those projects.

    The proposed effective period is 1 January 2027 to 31 December 2030.

    The measure forms part of the government’s stated ambition to achieve zero abandoned housing projects by 2030.

    Source: Prime Minister’s Office — Budget 2027 speech

    Will this solve the abandoned housing problem?

    Stamp duty relief can reduce transaction costs, but reviving an abandoned project is more complicated than reducing taxes.

    A successful rescue may depend on:

    • Whether the project is financially viable.
    • Whether a capable rescue developer can be appointed.
    • Whether land, financing and legal issues can be resolved.
    • Whether construction can be completed within a realistic timeframe.
    • Whether original purchasers can ultimately receive their homes.

    For affected buyers, the priority remains understanding the legal and financial status of the project and the conditions under which completion can proceed.

    My view: The incentive is a useful part of the solution, but actual project rehabilitation and delivery will be the real test.

    4. Nearly RM1 billion for housing programmes

    Budget 2027 provides nearly RM1 billion for programmes including Rumah Mesra Rakyat and Program Residensi Rakyat.

    Four new housing projects are identified in Kulai, Johor; Nilai, Negeri Sembilan; Paya Rumput, Melaka; and Pertang Valley, Terengganu.

    The Budget also identifies Bandar MADANI Bukit Jalil as a residential development with supporting amenities, including a vertical school.

    These initiatives reflect the continuing role of government-supported housing in addressing housing needs.

    Source: Prime Minister’s Office — Budget 2027 speech

    For buyers, however, the announcement of a housing programme is only the beginning.

    Eligibility, location, unit pricing, delivery schedules and access to public amenities all affect whether a particular development meets a household’s needs.

    Affordable housing should not be assessed by price alone. Accessibility to employment, transport, schools and essential services also matters.

    5. What could Budget 2027 mean for Penang property?

    Penang’s property market has its own economic drivers. Its manufacturing base, semiconductor ecosystem, employment opportunities, infrastructure and limited availability of certain types of land all influence property demand.

    Budget 2027 includes a RM100 million Strategic Investment Fund involving Khazanah and InvestPenang to support early-stage semiconductor and advanced manufacturing companies.

    The Budget also identifies transport-related infrastructure investment involving roads in port areas and airports, including Penang International Airport.

    These announcements could have indirect implications for property demand if they translate into business expansion, job creation and improved connectivity.

    Source: Prime Minister’s Office — Budget 2027 speech

    Which property segments could benefit?

    Industrial and logistics property

    Business expansion may create demand for suitable industrial facilities, warehouses and supporting commercial space. Actual demand will depend on investment commitments, company requirements and available supply.

    Residential property near employment centres

    If industrial investment generates additional jobs, it could support demand for housing in accessible locations. The effect will vary according to workers’ incomes, commuting patterns, rental budgets and the supply of competing homes.

    Commercial property

    Business growth may create opportunities for offices, retail services and other supporting uses. These opportunities should be assessed against occupancy, tenant demand and operating costs.

    Does this mean Penang property prices will rise?

    Not necessarily.

    Infrastructure and investment announcements are not guarantees of capital appreciation. The impact on individual developments depends on their location, purchase price, accessibility, competing supply, rental demand and the actual delivery of the announced projects.

    For buyers, the right question is not simply whether an area will benefit from economic growth. It is whether a particular property is priced reasonably relative to its likely demand and long-term usefulness.

    6. What should property investors watch?

    Budget 2027 creates several areas worth monitoring, but investors should distinguish between a policy announcement and a measurable investment opportunity.

    Follow employment and business expansion

    Industrial investment may support housing and commercial demand, but the most useful evidence will be actual investment commitments, completed facilities, employment growth and tenant activity.

    Assess rental demand rather than relying on capital appreciation

    A property near an expanding employment centre may attract tenants, but rental demand does not guarantee a satisfactory yield.

    Investors should calculate realistic rental income after vacancies, maintenance, management fees, financing costs and other expenses.

    Check competing supply

    Even a location with strong economic activity can experience weak rental performance if too many similar units compete for tenants.

    Evaluate the purchase price

    Government incentives can influence demand, but buyers still need to assess whether the asking price is supported by comparable transactions, rental evidence and the property’s fundamentals.

    My view: Investors should follow the economic effects of the Budget, not simply the headlines. A good investment still requires a sound entry price and a clear understanding of risk.

    7. What does Budget 2027 mean for property developers?

    The Budget’s housing measures may help reduce some barriers to homeownership. However, developers continue to face the practical challenges of land, construction, financing, regulatory compliance and buyer affordability.

    The Real Estate and Housing Developers’ Association Malaysia (REHDA) welcomed the proposed homeownership measures and housing financing guarantees. It also called for a review of development-related charges and highlighted construction costs and the need to address completed but unsold residential properties.

    Source: EdgeProp — REHDA’s response to Budget 2027

    For developers, three questions deserve attention.

    First, does the product match the buyer’s budget?

    A property may have attractive facilities and branding, but the target buyer must still be able to afford the purchase and ongoing ownership costs.

    Second, does the project offer a clear reason to buy?

    Location, accessibility, layout, price, surrounding amenities and realistic future demand matter more than marketing claims alone.

    Third, is the sales process helping buyers make confident decisions?

    Buyers need clear information about costs, financing, project delivery, ownership obligations and relevant risks.

    The Budget may improve some aspects of the purchasing environment, but it cannot replace sound product positioning, credible communication and responsible sales practices.

    8. Five questions every homebuyer should ask before purchasing

    Regardless of government incentives, I encourage buyers to work through five questions before making a commitment.

    1. Can I afford this property comfortably? Calculate the deposit, transaction costs, monthly instalment, maintenance and a realistic contingency reserve.
    2. Does the location fit my needs? Consider employment, transport, schools, amenities and daily travel requirements.
    3. Is the price supported by evidence? Compare similar properties, recent transactions and realistic rental values where relevant.
    4. What risks am I taking? Understand the developer’s track record, construction status, legal terms, competing supply and likely holding costs.
    5. Does this property fit my long-term plan? A home for own occupation and an investment property may require different priorities.

    These questions are especially important when an incentive makes a purchase appear more attractive. A lower upfront cost does not necessarily make a property the right choice.

    9. My takeaway: Policy support is useful, but property decisions still matter

    Malaysia Budget 2027 proposes meaningful support for first-home buyers through expanded stamp duty relief, housing financing guarantees and measures intended to facilitate the rehabilitation of abandoned projects.

    It also identifies housing programmes and investment initiatives that could influence economic activity in selected locations, including Penang.

    The eventual impact will depend on implementation, financing access, actual investment and the underlying supply and demand for property.

    For homebuyers, the opportunity is to understand the assistance available without losing sight of affordability.

    For investors, it is to identify genuine demand rather than assume every policy announcement will increase property values.

    For developers, it is to understand what buyers need and communicate the value of a project clearly and responsibly.

    At the Property Discovery System™ (PDS), our approach is straightforward: understand the market, evaluate the options, identify the risks and make decisions based on evidence.

    Because buying property should never be about following a headline alone.

    Discover Better. Decide Smarter.

    This article is for general property education and information. Budget 2027 measures described as proposed remain subject to the relevant legislation, implementation guidelines and eligibility requirements. Readers should confirm their individual circumstances with the relevant authorities and professional advisers before making financial or property decisions.

  • What If Buying Property Started With Questions, Not Projects?

    What If Buying Property Started With Questions, Not Projects?

    A different way to think about property buyers, developers and better decisions

    When people start looking for a property, the first question is often:

    “Which property should I buy?”

    Perhaps we should be asking a different question first:

    “What am I actually looking for?”

    It sounds like a small difference.

    It isn’t.

    Today, property buyers have access to more information than ever before. They can compare prices online, watch property tours, read reviews, study locations, look at transaction data and explore dozens of projects without leaving home.

    Yet having more information does not necessarily mean making better decisions.

    In fact, sometimes it creates another problem.

    Information overload.

    A buyer may know the price, size, facilities, tenure and estimated rental yield of a property — but still not know whether the property actually makes sense for them.

    And this is where I believe the property conversation needs to change.

    Start With the Buyer, Not the Project

    Most property journeys begin with a project.

    A buyer sees an advertisement.

    A friend recommends a development.

    A property consultant introduces a new launch.

    A developer presents an attractive package.

    The project becomes the starting point of the conversation.

    From there, the buyer begins asking:

    Is the price good?
    Is the location good?
    Will it appreciate?
    Can I rent it out?
    Is this a good investment?

    But there is an important question that often comes much earlier:

    Good for whom?

    A property can be an excellent project and still be the wrong property for a particular buyer.

    The location may be excellent, but unsuitable for the buyer’s lifestyle.

    The rental potential may look attractive, but the numbers may not work after financing costs and expenses.

    The future development potential may be strong, but the buyer may need liquidity much sooner.

    The property itself may be good.

    The decision may still be wrong.

    The Developer Sees the Property Differently

    This isn’t necessarily because developers are doing something wrong.

    Developers have a responsibility to present their projects — the location, design, facilities, specifications, pricing and value proposition.

    They need buyers to understand what they are offering.

    But buyers are looking at the same property through a completely different lens.

    They are asking:

    “What does this mean for me?”

    That is where the gap can appear.

    Developers communicate the value of the project.

    Buyers are trying to understand the value of the decision.

    Those two things are related — but they are not exactly the same.

    And perhaps there is an opportunity to bring them closer together.

    Better Questions Can Lead to Better Decisions

    I have spent many years working across banking, investment, property and education, and one thing has become increasingly clear to me:

    The quality of a property decision often depends on the quality of the questions being asked.

    Instead of immediately asking:

    “Is this a good property?”

    we could ask:

    • Does it fit the way I intend to live?
    • What opportunity does this location create?
    • Can I comfortably afford it?
    • What happens if my circumstances change?
    • What is the potential exit value?
    • What risks am I overlooking?
    • Am I buying because the property makes sense — or because I am being persuaded that it makes sense?

    These questions do not make the buying process more complicated.

    They make it more meaningful.

    This Is Where Property Discovery System™ Comes In

    This thinking was one of the reasons I developed the Property Discovery System™ (PDS).

    PDS is not designed to tell a buyer which property to buy.

    Instead, it provides a structured way to discover, evaluate and understand a property before making the decision.

    At the heart of the system is the HOME™ Property Assessment Framework:

    H — Habitability
    Does the property and its environment make sense for the way it will actually be used?

    O — Opportunity
    What does the location, market and surrounding environment potentially offer?

    M — Money
    Does the financial commitment make sense based on affordability, cash flow and overall financial considerations?

    E — Exit Value
    If circumstances change, what potential options and value does the property offer when the buyer eventually needs to exit?

    The objective is not to produce a magical number that says “buy” or “don’t buy.”

    Property decisions are rarely that simple.

    The objective is to help a buyer think more clearly before deciding.

    And What About Developers?

    This approach is not only useful for buyers.

    I believe it can also create value for developers.

    Imagine a buyer arriving at a project presentation already understanding:

    • what they are looking for;
    • what matters to them;
    • how the location fits their needs;
    • what financial considerations they need to evaluate;
    • and what questions they should be asking.

    The developer can then spend less time simply trying to convince the buyer that the project is attractive.

    Instead, the conversation can move towards:

    “Let us show you why this project may — or may not — fit what you are looking for.”

    That is a different kind of conversation.

    And I believe it is a healthier one.

    Perhaps Buyers and Developers Are Not Opposite Sides

    The property industry sometimes makes it appear as though buyers and developers sit on opposite sides of the table.

    I don’t see it that way.

    A responsible buyer wants to make a sound decision.

    A good developer wants its project to attract the right buyers and deliver what it promises.

    Both sides benefit when the buyer understands the decision better.

    That is why I see PDS not as another property sales tool, but as a bridge between property discovery and property decision-making.

    The developer still presents the project.

    The buyer still makes the decision.

    But the conversation starts from a more informed place.

    Maybe We Have Been Starting Too Late

    Perhaps the property buying journey should not begin when a buyer walks into a show gallery.

    Perhaps it should begin much earlier.

    Before the brochure.

    Before the show unit.

    Before the sales presentation.

    Before the question:

    “How much is it?”

    It should begin with:

    “What am I trying to achieve?”

    Then:

    “What should I be looking for?”

    And only after that:

    “Which property fits?”

    That is the thinking behind Property Discovery System™.

    Because I don’t believe people need more property projects to choose from.

    They need a better way to discover which properties deserve their attention in the first place.

    Discover Better. Decide Smarter.

    That, to me, is where a better property journey begins.

    From The Desk Of

    Miichael Yeoh

  • Is the Property Market Slowing Down… Or Are Buyers Becoming More Picky?

    Is the Property Market Slowing Down… Or Are Buyers Becoming More Picky?

    Lately, many people have been asking:

    “Is the property market slowing down?”

    Some projects are taking longer to sell.
    Some launches are seeing slower take-up.
    Buyers seem to be hesitating more before committing.

    At first glance, it may appear that the market is becoming weak.

    But when we look deeper into the numbers and buyer behaviour, the story may actually be different.

    According to the National Property Information Centre (NAPIC), Malaysia recorded more than 420,000 property transactions in 2024 — one of the strongest performances in the past decade.

    This tells us something important:
    The market still has buyers.

    However, today’s buyers are no longer buying property the same way they did years ago.

    Buyers today are becoming more informed, more cautious, and more selective before making decisions.

    In the past, some buyers purchased based on emotions, marketing hype, showroom designs, rebates, or fear of missing out (FOMO).

    Today, buyers are asking more questions:

    • Is the pricing reasonable?
    • Is there real demand in the area?
    • Can the property generate rental income?
    • Is the developer reliable?
    • Is there oversupply nearby?
    • Will the property still hold value in the future?

    In short — buyers today are becoming more picky.

    And honestly, that is not necessarily a bad thing.

    A property purchase is one of the biggest financial commitments for most people. Buyers today are thinking carefully about:

    • Monthly instalments
    • Interest rates
    • Maintenance fees
    • Cash flow commitments
    • Rental demand
    • Future resale value
    • Lifestyle suitability
    • Long-term financial stability

    This explains why some projects continue to perform well while others struggle with slower take-up.

    In fact, NAPIC data also shows that Malaysia continues to face residential overhang issues in certain market segments. This means completed units remain unsold due to factors such as pricing mismatch, oversupply, poor accessibility, weak product positioning, or changing buyer preferences.

    This does not mean there are no buyers in the market.
    It simply means buyers are becoming more selective about where they place their money.

    Before buying any property project, buyers should spend time understanding:

    • The actual market demand
    • Existing and future supply in the area
    • Nearby competing developments
    • Developer track record and credibility
    • Connectivity and infrastructure plans
    • Market pricing compared to surrounding projects
    • Rental and resale potential
    • Their own financial holding power
    • Whether the property truly fits their long-term goals

    Many people still buy emotionally.
    But smart buyers buy strategically.

    A beautiful showroom alone should never be the reason to purchase a property.

    One thing I always encourage buyers to do before committing is to attend property seminars, educational talks, and market-sharing sessions.

    Why?

    Because knowledge reduces expensive mistakes.

    A good seminar can help buyers:

    • Understand current market trends
    • Learn from real case studies
    • Compare projects more objectively
    • Understand buyer psychology and market cycles
    • Avoid common investment mistakes
    • Gain confidence before making a large commitment

    In today’s market, education is becoming one of the most important tools for property buyers.

    The market may not necessarily be weak.
    It may simply be that buyers today are smarter, more informed, and more selective than before.

    And personally, I believe that is a healthy direction for the property market.

    From the Desk of,

    Miichael Yeoh

    Property Strategist
    Disclaimer: This reflects the author’s personal views based on market experience and current observations. It is not financial advice. Smart investors do their own research before making any move.

  • Real Estate Summit 2025: A Resounding Success!

    Real Estate Summit 2025: A Resounding Success!

    After two days of insightful discussions, expert sharing, and valuable networking, the Real Estate Summit 2025 (RES2025) has officially concluded! This event brought together some of the most renowned experts in real estate, finance, and investment, providing participants with actionable insights into the property market, financial planning, and smart investment strategies for 2025.

    We were honored to welcome participants from Malaysia, the Philippines, Singapore, the USA, Germany, and many other countries. The diversity of attendees enriched discussions and created a vibrant learning environment.

    A Heartfelt Thank You to Our Participants & Speakers

    First and foremost, we extend our deepest gratitude to all participants for attending RES2025. Your enthusiasm and eagerness to learn made this event truly impactful.

    A special appreciation to our distinguished speakers, whose expertise and insights played a crucial role in the success of RES2025:

    🔹 Dato’ Sri Gavin Tee – A real estate expert who shared his forecast on the 2025 property market and upcoming investment opportunities.
    🔹 Richard Oon – A taxation and financial planning specialist who guided participants on tax-saving strategies and financial management for property investors.
    🔹 Dr. Daniele Gambero – A respected market analyst who discussed real estate trends, mortgage challenges, and investment potential in 2025.
    🔹 Dr. Elane Goh – A finance and investment strategist who shared her insights on wealth creation through property investments and financial planning.
    🔹 WK Ng – A seasoned property investor who transitioned from the corporate world to full-time investing, providing real-life success strategies.
    🔹 KW Wong – A PropTech innovator and Secretary-General of the Malaysia PropTech Association, who spoke about the digital transformation of the rental market.
    🔹 Charles Tan – A leading property market analyst who offered valuable perspectives on Malaysia’s evolving real estate landscape.
    🔹 Miichael Yeoh – A mortgage and financial expert, who emphasized the importance of planning before making any major investment decisions.

    Your dedication and willingness to share your knowledge made RES2025 a game-changing event for all attendees.

    Special thanks to our co-organiser POLA Malaysia and our media partners Property Hunter and kopiandproperty.

    Key Takeaways from RES2025

    Throughout the two-day summit, participants gained powerful insights into the property industry, with topics covering:

    ✔️ Where to Invest in 2025 – Discovering high-potential investment hotspots.
    ✔️ Real Estate Market Trends – Adapting to economic shifts and evolving regulations.
    ✔️ Financial Planning & Taxation – Understanding tax incentives, financial structures, and mortgage strategies.
    ✔️ Mortgage Market 2025 – The latest developments in home financing and lending policies.
    ✔️ PropTech Innovations – The rise of digital property platforms and the impact on buying, selling, and renting.
    ✔️ Investment Strategies – How to build a profitable real estate portfolio.

    As Miichael Yeoh emphasized in his session: “Plan first before making your next move.” Strategic financial and investment planning is essential to achieving long-term success in real estate.

    The Power of Networking & Knowledge Sharing

    Beyond expert talks, RES2025 provided an invaluable opportunity for participants to connect with industry leaders, experienced investors, and like-minded individuals. The event fostered an environment where attendees could exchange ideas, gain exclusive insights, and build meaningful professional relationships.

    Looking Forward: What’s Next?

    The success of RES2025 reaffirms GM Training Academy’s commitment to empowering individuals with property education and financial literacy. We believe that informed decisions lead to successful investments, and we are dedicated to helping investors, homeowners, and professionals navigate the ever-changing real estate market.

    🚀 Upcoming Initiatives:

    ✅ More masterclasses and training workshops
    ✅ Exclusive webinars featuring top industry experts
    ✅ Property investment study tours
    ✅ Advanced financial and mortgage planning courses

    Stay Connected & Keep Learning

    📢 Missed RES2025? No worries! Stay connected with us for upcoming programs that will continue to provide valuable industry insights and expert guidance.

    Once again, THANK YOU to all our participants and speakers for making RES2025 a grand success! We look forward to seeing you at our next event.

  • Avoid Costly Mistakes: 8 Reasons to Learn Before Investing in Real Estate

    Avoid Costly Mistakes: 8 Reasons to Learn Before Investing in Real Estate

    Purchasing or investing in property is one of the most significant financial decisions a person can make. While the prospect of owning a piece of real estate can be exciting, it’s also fraught with risks and complexities. Here are eight compelling reasons why educating yourself before taking the plunge is crucial:

    1. Understanding the Market

    The property market is dynamic, influenced by factors such as economic conditions, interest rates, and government policies. Without proper knowledge, you might buy at the wrong time or in the wrong location, potentially leading to financial losses. Education helps you grasp market cycles and trends, enabling informed decisions.

    2. Avoiding Costly Mistakes

    From overpaying for a property to falling victim to scams, the risks of making costly mistakes are high for uninformed buyers. Learning about property valuation, legal processes, and common pitfalls can save you from financial heartache.

    3. Maximizing Investment Returns

    Investing in property isn’t just about buying a house or apartment; it’s about choosing assets that will appreciate in value or generate steady rental income. Understanding key metrics such as ROI (Return on Investment) and cash flow can help you identify profitable opportunities.

    4. Navigating Legal and Financial Complexities

    Property transactions involve a maze of legal and financial considerations. From understanding loan agreements to navigating tax implications and zoning laws, there’s a lot to learn. A lack of knowledge could lead to delays or even legal troubles.

    5. Building Confidence

    The more you know, the more confident you’ll feel about your decisions. Knowledge reduces fear and uncertainty, empowering you to negotiate effectively, choose wisely, and stick to your long-term goals.

    6. Identifying Red Flags

    Not all properties are created equal. Structural issues, poor location, and hidden costs can turn a dream investment into a nightmare. Learning to conduct due diligence and property inspections ensures you spot potential problems early.

    7. Accessing Better Financing Options

    Understanding how mortgages and loans work can save you thousands of dollars over the life of your investment. Learning about different financing options and how to improve your creditworthiness can lead to better interest rates and loan terms.

    8. Planning for the Future

    Property investment is a long-term commitment. Learning helps you align your investment choices with your financial goals, whether it’s building wealth, securing passive income, or preparing for retirement. Knowledge enables strategic planning that benefits you in the long run.

    Conclusion

    Investing time and effort into learning before buying or investing in property is an investment in itself. It equips you with the tools and insights needed to make smart, informed decisions that align with your financial aspirations. Remember, in the world of property, knowledge isn’t just power; it’s profit.