Tag: PDSsystem

  • Is Now a Good Time to Buy Property in Malaysia ?

    Is Now a Good Time to Buy Property in Malaysia ?

    Everyone wants to know whether property prices will rise or fall.

    But that’s not the question I would ask before buying a property.

    The better question is:

    “Is this the right property, at the right price, with the right financing, for my situation?”

    Because even if the market rises next year, you can still make a bad property decision today.

    And even if prices fall, waiting doesn’t automatically mean you will get a better deal.

    So, is 2026 a good time to buy property in Malaysia?

    My answer: It can be — but only if you stop trying to predict the market and start discovering the numbers behind the decision.


    What Is Actually Happening in the Malaysian Property Market?

    Let’s start with the facts.

    Malaysia’s property market remained resilient in the first half of 2026, recording 187,320 transactions worth RM105.12 billion. The market was supported by relatively stable transaction activity, prices and construction activity.

    At the same time, the market isn’t booming across every segment.

    Residential transactions in H1 2026 were 110,998, accounting for 59.3% of total property transactions. Completed unsold residential units increased to 33,094 units, worth about RM17.78 billion.

    That tells us something important.

    The market isn’t simply “good” or “bad”.

    There are areas of strength.

    There are areas of oversupply.

    There are properties with genuine demand.

    And there are properties that developers are struggling to sell.

    This is exactly why buyers need to become more selective.

    What About Interest Rates?

    This is probably one of the first things buyers look at.

    And understandably so.

    Bank Negara Malaysia has maintained the Overnight Policy Rate (OPR) at 2.75% throughout 2026, including its latest decision on 3 September 2026.

    That provides a relatively stable financing environment compared with periods of rapidly changing interest rates.

    But here’s where I think many buyers make a mistake.

    They see a stable or lower interest-rate environment and immediately think:

    “Good. Time to buy.”

    Not necessarily.

    The interest rate is one variable in your property decision.

    It is not the decision.

    A property that is overpriced by RM100,000 doesn’t suddenly become a good investment because your mortgage rate is slightly lower.


    Should You Wait for Property Prices to Fall?
    This is probably the question I hear most often.

    And it sounds logical.

    “If prices are going to fall, I’ll wait.”

    But there are two problems with this strategy.

    First, nobody knows exactly when prices will fall.

    And more importantly:

    Second, even if prices fall, you may not benefit.

    Why?

    Because the property you want may not fall.

    The bank may tighten lending.

    Your income may change.

    Interest rates may move.

    The developer may remove incentives.

    Another buyer may take the unit you wanted.

    Or the market may simply remain stable for several years.

    Waiting is not a neutral decision.

    Waiting is also a property decision.


    The Bigger Question: What Are You Actually Buying?

    This is where I believe buyers need to change their thinking.

    Don’t ask only:

    “Will property prices go up?”

    Ask:

    “What is creating the demand for this property?”

    Is it:

    • population growth?
    • new jobs?
    • infrastructure?
    • universities?
    • industrial development?
    • tourism?
    • rental demand?
    • limited land supply?
    • better connectivity?
    • genuine owner-occupier demand?

    Or is the main attraction simply:

    “The developer says prices will increase.”

    Those are very different things.


    5 Things I Would Check Before Buying Property
    1. Can You Actually Afford It?

    This sounds obvious.

    But affordability isn’t simply:

    “The bank approved my loan.”

    A bank’s approval tells you what the bank is prepared to lend.

    It doesn’t tell you what you should comfortably borrow.

    Before buying, calculate the full monthly cost:

    • mortgage instalment
    • maintenance fee
    • sinking fund
    • assessment
    • quit rent
    • insurance
    • utilities
    • repairs
    • furnishing
    • parking
    • transportation
    • other existing commitments

    Then ask:

    “If my income stays the same for the next three years, will this property still feel comfortable?”

    That’s a much better question than:

    “How much can the bank approve?”


    2. Is the Price Supported by the Market?

    Don’t fall in love with the launch price.

    Find out what similar properties are actually transacting for.

    NAPIC provides transaction, price, rental and property-market data, including state and district-level information.

    Compare:

    Asking price vs actual transaction price.

    Then compare:

    RM per sq ft vs comparable properties.

    Then ask:

    “What am I paying a premium for?”

    If the answer is simply:

    “Because this is a new launch.”

    That’s not enough.


    3. Is There Real Demand?

    A beautiful building isn’t demand.

    A famous developer isn’t demand.

    A fantastic showroom isn’t demand.

    Demand comes from people who genuinely want to live, work, rent or invest in that location.

    Ask:

    • Who is going to live here?
    • Who is going to rent here?
    • Where do these people work?
    • Why would they choose this location?
    • What alternatives do they have?
    • What competing projects are coming?

    This becomes particularly important when a market has significant unsold stock.

    Malaysia’s completed unsold residential inventory rose to 33,094 units in H1 2026.

    That doesn’t mean all property is bad.

    It means product selection matters.


    4. What Happens When More Supply Arrives?

    This is one of the most overlooked questions in property investing.

    Imagine you buy a condominium because the current rental demand looks excellent.

    But three years later, five more projects are completed nearby.

    Now you have thousands of competing units.

    Your tenant has choices.

    Your rental growth may slow.

    Your vacancy risk may increase.

    And when you eventually want to sell, you’re no longer competing only against today’s properties.

    You’re competing against tomorrow’s properties.

    That’s why I always tell buyers:

    Don’t just study the property. Study what is coming around the property.


    5. What’s Your Exit Strategy?

    This is perhaps the biggest difference between a home purchase and an investment purchase.

    A homeowner may be happy because:

    “I love the location.”

    An investor needs another question:

    “Who will buy this from me later?”

    Think about your exit before your entry.

    If you need to sell in five or ten years:

    • Who is your future buyer?
    • What will they be looking for?
    • What competing supply will exist?
    • Will your property still be relevant?
    • Will your price be affordable to the next buyer?
    • Will the rental market support your valuation?

    You don’t realise your investment return when you buy.

    You realise it when you eventually exit.


    So… Is 2026/2027 a Good Time to Buy Property?

    Here’s my answer.

    Yes — if you’re buying based on fundamentals.

    No — if you’re buying simply because you believe prices must go up.

    The Malaysian property market in 2026 is resilient, but the data also shows why buyers cannot treat the entire market as one big opportunity.

    Transaction activity remains substantial.

    Interest rates are relatively stable.

    But residential demand is uneven, completed unsold stock has increased, and affordability remains an important constraint.

    That creates an interesting environment.

    It may actually be a better time to be a selective buyer than an emotional buyer.

    You don’t necessarily need to wait for a market crash.

    You need to find the property where:

    Price + Location + Demand + Financing + Supply + Exit

    all make sense together.


    The PDS 7-Question Property Test

    Before I buy any property, I would want to answer these seven questions:

    1. Why this property?

    What problem does it solve?

    2. Why this location?

    What is creating sustainable demand?

    3. Why this price?

    What evidence supports the valuation?

    4. Who is the future buyer or tenant?

    Where does the demand come from?

    5. What competition is coming?

    What could affect rental and resale demand?

    6. Can I comfortably hold it?

    Not just today — but through different market conditions.

    7. How do I eventually exit?

    Who will buy it from me?

    If you can’t answer these questions, perhaps you are not ready to buy.

    And that’s okay.

    Not buying is sometimes a better decision than buying the wrong property.


    The Real Question Isn’t “When Should I Buy?”

    After more than two decades around banking, mortgages, property and investment decisions, I’ve learned that buyers often spend too much time trying to predict the market.

    The smarter approach is to understand the decision.

    You don’t need to know exactly where property prices will be five years from now.

    You need to understand why the property you’re considering should still have demand five years from now.

    That’s a very different way of looking at property.

    And it is the philosophy behind the Property Discovery System™.

    Don’t just ask whether now is a good time to buy.

    Discover whether this is the right property for you.

    Discover Better. Decide Smarter.

    Miichael Yeoh

    Property Strategist
  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    26 September – 2 October 2026

    Malaysia + International Property Insights

    This week’s market is interesting for one reason: the headlines are not telling one single story.

    Malaysia has pockets of resilience in retail and construction, but residential developers are still dealing with affordability and unsold stock. Overseas, Australia is going through a much sharper housing correction, while Singapore continues to reposition mature assets through redevelopment.

    For buyers and investors, the lesson is simple: look beneath the headline number.


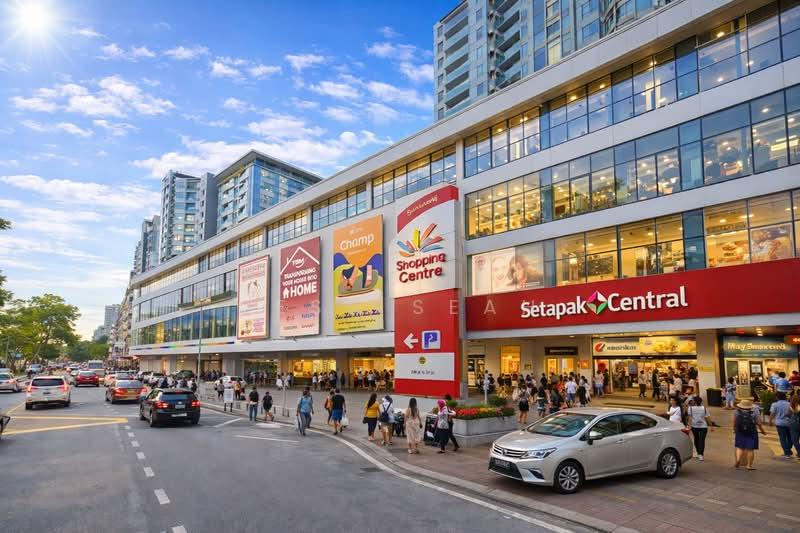
    🇲🇾 1. KIP REIT Completes RM435 Million Setapak Central Mall Acquisition

    What Happened

    KIP REIT completed its RM435 million acquisition of Setapak Central Mall on 30 September.

    The three-storey mall has approximately 514,777 sq ft of net lettable area and 1,090 parking bays. Occupancy had previously been reported at 99.89%.

    The acquisition brings KIP REIT’s portfolio to 20 properties, with the enlarged portfolio previously assessed at around RM2.1 billion. EdgeProp

    Why It Matters

    This isn’t simply about buying another shopping mall.

    A mature, highly occupied retail asset can provide something very different from a new development:

    existing tenants + existing footfall + existing income.

    For investors, that distinction matters.

    The question isn’t simply whether a property is “good”.

    It is:

    How predictable is the income after I buy it?

    Miichael’s Review

    I like looking at transactions like this because they demonstrate another side of property investment.

    A developer creates value through development.

    A REIT investor is often looking for income-producing assets with established operations.

    For individual investors, the same principle applies.

    Before getting excited about a property because of future appreciation, ask:

    What is producing the income today?

    Source: EdgeProp — KIP REIT completes RM435m Setapak Central acquisition


    🇲🇾 2. Gamuda Posts Record Profit — But Property Earnings Fall

    What Happened

    Gamuda reported record FY2026 net profit of RM1.05 billion, up 5%.

    But there is an interesting contrast underneath the headline.

    While the group’s overall performance was supported by stronger construction earnings, property sales fell 22% to RM3.2 billion, while property division net profit declined 18% to RM310.76 million. EdgeProp

    Why It Matters

    This is a useful reminder that a diversified property-related group can perform well overall even when its property division is under pressure.

    It also reinforces an important market principle:

    Construction demand and residential property demand are not necessarily moving together.

    Miichael’s Review

    For me, the interesting part isn’t simply that Gamuda made a record profit.

    It is the divergence between construction and property.

    When analysing a developer, I would not stop at the group’s headline earnings.

    I’d want to know:

    • How much comes from property?
    • What is the sales pipeline?
    • How much unsold inventory exists?
    • Where are the projects located?
    • What is the margin?
    • And how quickly can sales be converted into cash?

    A strong company does not automatically mean every property project is equally attractive.

    Source: EdgeProp — Gamuda posts record FY2026 profit


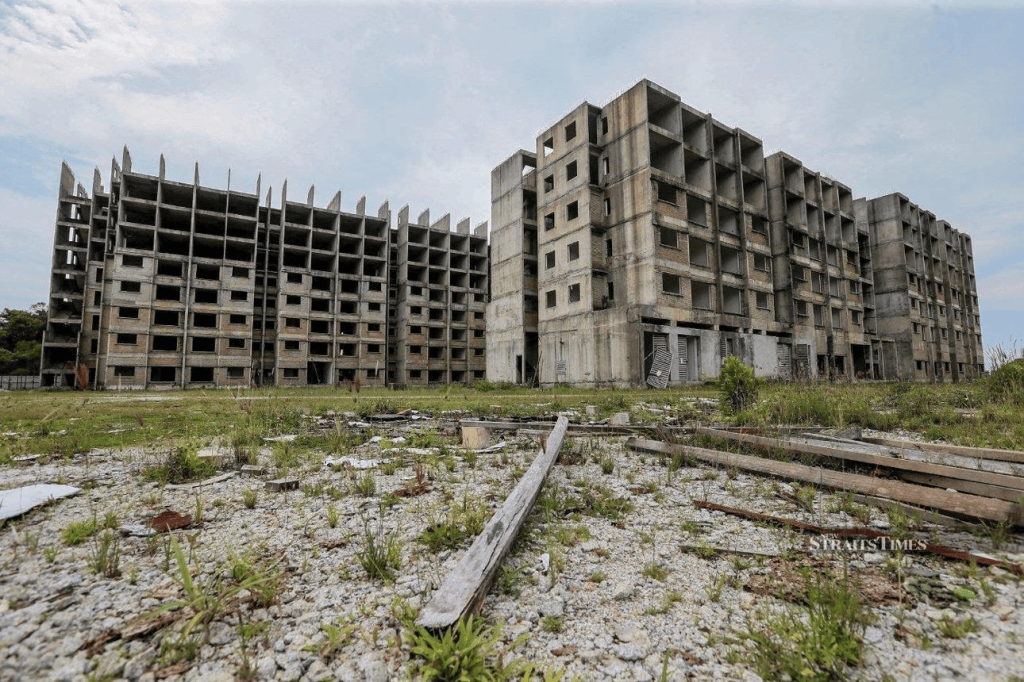
    🇲🇾 3. Government Calls for More “White Knights” to Rescue Abandoned Projects

    What Happened

    Malaysia’s Housing and Local Government Ministry has called on established developers to step in as “white knights” to revive stalled and abandoned housing developments.

    According to the report, the ministry’s task force has helped revive 1,647 distressed projects worth RM153 billion, affecting almost 200,000 homebuyers.

    The government is also pursuing legal reforms involving developer accountability, strata management and residential tenancy. The Star

    Why It Matters

    For a buyer, buying property isn’t simply about:

    location + price + size.

    There is another question that often gets overlooked:

    Who is behind the project — and what happens if things go wrong?

    A delayed or abandoned project can create years of financial and emotional stress for buyers.

    Miichael’s Review

    This is one area where I think buyer education is particularly important.

    Before buying a new development, buyers should investigate the developer’s track record, project delivery history, financial structure, development partners and surrounding ecosystem.

    We often spend hours comparing unit sizes and discounts.

    But sometimes the most important due diligence happens before we even choose the unit.

    Source: The Star — Malaysia needs more white knights


    🌏 4. Australia: Housing Prices Fall for a Sixth Straight Month

    What Happened

    Australia’s housing market continued to weaken in September.

    Cotality’s national Home Value Index fell 1.1% in September, the sixth consecutive monthly decline.

    Values are now 5.2% below the March 2026 peak.

    Sydney fell 1.4% in September and is nearly 9% below its February peak, while Melbourne fell 0.7%.

    Transaction activity has also weakened, with sales over the latest three-month period down around 19% year-on-year, according to Reuters. Reuters

    The Reserve Bank of Australia has also raised its cash rate to 4.6%, a 15-year high, adding further pressure to borrowing capacity. Investing.com

    Why It Matters

    Australia provides an excellent real-world example of the relationship between:

    interest rates → borrowing capacity → buyer demand → transactions → prices.

    And importantly, the impact is not identical across every city.

    Miichael’s Review

    For Malaysian buyers and investors looking overseas, this is a market worth watching carefully.

    A falling market doesn’t automatically mean:

    “Everything is cheap.”

    It means the risk-reward equation is changing.

    For anyone considering an overseas property purchase, I’d be asking:

    Has the price fallen because the market is correcting — or because the fundamentals have deteriorated?

    Those are two very different things.

    Source: Reuters — Australian home prices fall for sixth straight month; Cotality — September Home Value Index


    🌏 5. Singapore: Valley Point to Become a New Mixed-Use Development

    What Happened

    Frasers Property and Mitsubishi Estate announced plans to redevelop Valley Point and Frasers Suites Singapore along River Valley Road.

    The planned mixed-use development will include:

    • 407 luxury residential units and sky villas
    • 184 serviced-residence units
    • dining
    • retail
    • lifestyle components

    The project is planned for launch in 2027, with completion targeted for 2031. The existing properties are expected to cease operations in March 2027. The Business Times

    Why It Matters

    This is a classic example of urban land optimisation.

    Instead of simply maintaining an ageing asset, the owners are looking at the highest and best use of a prime site.

    The redevelopment also combines residential, serviced residences, retail and lifestyle components rather than relying on one single use.

    Miichael’s Review

    This is something developers everywhere can learn from.

    A property isn’t necessarily valuable because of what it is today.

    Sometimes its greatest value comes from what it could become.

    But that requires looking beyond the building itself:

    land value + location + planning potential + demand + surrounding ecosystem.

    For buyers, this also highlights why understanding a property’s future development context can be just as important as studying the existing building.

    Source: The Business Times — Frasers Property and Mitsubishi Estate redevelopment; Frasers Property — official announcement


    👀 WORTH WATCHING

    Malaysia

    1. Residential affordability

    The combination of unsold stock, financing constraints and developer margins remains an important issue.

    2. Retail investment

    The KIP REIT acquisition shows that mature, income-producing retail assets remain relevant when occupancy and cash flow are strong.

    3. Distressed projects

    The government’s push for more private-sector participation could change the landscape for abandoned and stalled developments.

    🌏 International

    4. Australia

    Watch whether the correction continues into 2027 and whether lower transaction volumes eventually create broader economic effects.

    5. Singapore

    Watch how redevelopment and land optimisation reshape mature neighbourhoods.


    💡 MY TAKEAWAY

    This week’s five stories are actually connected by one common theme:

    Property value is about more than price.

    A shopping mall’s value can come from income and occupancy.

    A developer’s value can come from the quality of its pipeline and balance sheet.

    A residential project’s value includes delivery risk.

    A housing market’s direction is influenced by financing and affordability.

    And an older property can sometimes create greater value through redevelopment.

    So when someone asks me:

    “Is this property a good buy?”

    I don’t think the first question should be:

    “How much is it?”

    I’d rather start with:

    Who is buying it?

    Why are they buying it?

    What creates the demand?

    What could go wrong?

    And what happens if the market doesn’t behave as expected?

    That is where proper property due diligence begins.

    From the desk of

    Miichael Yeoh

    Property Strategist