Tag: Malaysia property market

  • Why Are Homes Sitting Unsold When Malaysians Still Need Houses?

    Why Are Homes Sitting Unsold When Malaysians Still Need Houses?

    Malaysia’s property market faces an interesting contradiction. Many people are struggling to find homes they can afford, yet thousands of completed properties remain unsold. Perhaps the problem is not simply a lack of buyers — but a mismatch between what the market needs and what the industry is building.

    Malaysia’s property market has a question worth examining.

    On one hand, homeownership remains an important aspiration for many Malaysians. Young professionals are looking for their first homes. Growing families need more space. Some households are searching for affordable housing closer to their workplaces.

    On the other hand, completed residential properties remain unsold across the country.

    How can both situations exist at the same time?

    If people need homes, why are developers struggling to sell them?

    The answer may be more complicated than simply saying property prices are too high or buyers cannot afford to purchase.

    It may point to a deeper issue: the property market is not always building what the market actually needs.

    1. A property overhang is more than a supply problem

    When we hear about unsold properties, the immediate assumption is that Malaysia has too much housing supply.

    But this explanation does not tell the whole story.

    According to reported NAPIC figures, Malaysia recorded 33,094 completed unsold residential units in the first half of 2026, with a combined value of approximately RM17.78 billion.

    These are properties that have already been completed but remain unsold.

    The numbers deserve attention, but we should look beyond the national total.

    A property in Kuala Lumpur is not necessarily competing for the same buyer as one in Penang, Johor Bahru or a smaller township.

    A condominium priced at RM800,000 may appeal to a very different market from an affordable apartment priced at RM300,000.

    Even within the same location, a studio apartment, a two-bedroom unit and a family-sized home serve different needs.

    Therefore, the real question should not simply be:

    “How many properties are unsold?”

    It should be:

    “Which properties are unsold, where are they located, who were they designed for, and why are buyers not purchasing them?”

    That is a much more useful starting point.
    2. Are developers building for demand or for market assumptions?

    Property development involves considerable planning, investment and risk.

    Developers need to assess land costs, construction costs, financing, target selling prices, competition and expected market demand.

    However, there is a difference between identifying a market opportunity and understanding actual buyer demand.

    For example, a location may have strong economic activity, new infrastructure and an expanding population.

    On paper, it may look attractive for residential development.

    But does that automatically mean buyers will purchase every type of property launched there?

    Not necessarily.

    A young working professional may need a reasonably priced one-bedroom or two-bedroom apartment near employment opportunities.

    A family may prioritise space, schools, accessibility and daily convenience.

    An investor may be attracted by rental potential, but an owner-occupier may be more concerned about affordability and long-term liveability.

    These are different buyer profiles with different expectations.

    A development can be located in a promising area and still struggle if its product, pricing or unit configuration does not match the people most likely to purchase it.

    A good location does not automatically make every property in that location a good product.

    3. The affordability gap is becoming harder to ignore

    One of the biggest challenges facing property buyers is affordability.

    A property may be attractively designed and offer excellent facilities, but the asking price still needs to make sense for its intended market.

    Consider a simple example.

    A first-time buyer earning RM5,000 a month may be interested in purchasing a home near the workplace.

    However, once the buyer considers the monthly mortgage instalment, maintenance charges, insurance, utilities, transport and daily living expenses, the financial commitment may become too demanding.

    The buyer may like the property but decide not to proceed.

    This is an important distinction.

    Interest in a property does not necessarily translate into purchasing ability.

    There are also buyers who receive loan approval but decide that taking on the commitment would leave them financially stretched.

    Others may fail to secure financing because their income documentation, existing commitments or credit profile do not meet the bank’s requirements.

    For developers, this means the potential buyer pool may be smaller than expected.

    For buyers, it means that a property’s selling price should never be assessed independently of their actual financial capacity.

    A property is only affordable when the buyer can comfortably sustain the ownership commitment — not merely when the bank is willing to provide financing.

    4. The serviced apartment question: Who is the intended occupier?

    Another issue worth examining is the number of completed unsold serviced apartments.

    Recent market reporting has highlighted the concentration of completed unsold serviced apartments in Kuala Lumpur and Johor. It has also raised an important question: do some smaller units, originally designed with investment or short-term accommodation in mind, adequately meet the needs of people looking for permanent homes?

    This deserves closer attention.

    A compact studio may be suitable for a single professional, a certain rental market or a specific investment strategy.

    But it may not be suitable for a young family looking for a long-term home.

    Similarly, a development marketed around lifestyle facilities and investment potential may attract attention during its launch, but its long-term performance will depend on whether there is genuine demand from occupiers and tenants.

    The important lesson is that we should not confuse a property’s marketing appeal with its actual market suitability.

    Before developing or purchasing a property, we need to understand who will occupy it, why they would choose it and whether the surrounding location supports their daily needs.
    5. Developers need to think beyond the launch

    A successful property launch does not necessarily mean a successful development.

    Strong marketing, attractive showrooms, promotional packages and early-bird incentives can generate initial interest.

    However, the real test comes when the development is completed and buyers begin evaluating the actual product.

    Can the property attract genuine owner-occupiers?

    Is there sufficient rental demand?

    Does the selling price remain competitive against completed and secondary-market properties?

    Are the facilities, layout and unit sizes appropriate for the target market?

    Can buyers obtain financing?

    These questions should be considered well before a project reaches its launch stage.

    Developers need to recognise that buyers today have more information and more choices. They can compare prices, examine competing developments and assess whether a property offers genuine value.

    The development process should therefore begin with a clear understanding of the market — not simply with a decision to build because the location appears promising.

    6. What does this mean for property investors?

    For investors, an unsold property market should be a reminder that buying is only one part of an investment decision.

    A property may look attractive at launch, but investors should also consider what happens after completion.

    Will there be sufficient rental demand?

    Who are the likely tenants?

    How many competing units will be available?

    Will the property appeal to future buyers when the investor eventually decides to sell?

    A development with a large number of similar units may face considerable competition, particularly if many owners intend to rent out their properties at the same time.

    This can place pressure on rental rates and make it more difficult to secure tenants.

    The resale market may face a similar challenge if too many comparable properties are competing for a limited number of buyers.

    Investors should therefore look beyond the promised rental yield and projected capital appreciation.

    They need to understand the actual demand supporting those expectations.

    A property investment is not successful simply because the purchase price looks attractive. It must also have a realistic market to support its future rental and resale value.

    7. The property industry needs better market discovery

    Perhaps the biggest lesson from Malaysia’s property overhang is that the industry needs to improve how it understands demand.

    For buyers, this means evaluating properties based on personal needs, financial capacity and long-term suitability rather than being influenced solely by promotional campaigns.

    For investors, it means studying the actual rental and resale market before committing capital.

    For developers, it means investing more effort in understanding the people who will eventually occupy or purchase their products.

    Market research should go beyond population growth, infrastructure announcements and general economic indicators.

    It should examine the intended buyer profile, household income, affordability, competing supply, unit configuration, employment opportunities and actual purchasing behaviour.

    This is where a more structured property discovery process becomes important.

    At PDS — Property Discovery System™, we believe that better property decisions begin with better questions.

    Before asking whether a property is attractive, we should ask whether it is suitable.

    Before asking whether the location has growth potential, we should understand who will drive that growth.

    And before asking whether a development offers good investment returns, we should establish whether there is genuine demand to support those returns.

    The bigger question: Are we building enough homes, or the right homes?

    Malaysia does not simply need more property development.

    It needs developments that respond to real market requirements.

    The property overhang should not be viewed only as a developer’s sales challenge or a buyer’s affordability problem. It is also an opportunity for the entire industry to examine how properties are planned, priced, positioned and delivered.

    A home is not just a collection of concrete, facilities and attractive marketing materials.

    It is a product that must serve the needs of the people who will eventually live in it.

    And an investment property must have a realistic market that can support its rental and resale potential.

    Perhaps the property industry’s next competitive advantage will not come from building bigger projects or offering more facilities.

    It will come from understanding the market better.

    Because the real question is not whether Malaysians need homes. It is whether we are building the homes that Malaysians can afford, want and genuinely need.


    Discover Better. Decide Smarter.

    Miichael yeoh

    Property Strategist

    Disclaimer: This article is intended for general educational and property market discussion purposes only. Market conditions, property prices, financing requirements and investment outcomes may vary by location and individual circumstances. Readers should conduct their own due diligence and seek appropriate professional advice before making property-related decisions.
  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    17–23 October 2026

    🇲🇾 MALAYSIA PROPERTY MARKET

    STORY 1 — Sime Darby Property’s RM418.5 Million Kulai Land Deal: What Comes Next?

    Illustrative image of agricultural land in Kulai, Johor; not the exact acquisition parcel.

    What Happened?

    On 20 October, EdgeProp reported further details about the proposed land acquisition by Sime Darby Property Berhad, which is seeking shareholder approval for its purchase of approximately 556.96 acres of freehold land from SD Guthrie Berhad.

    The proposed transaction involves:

    • Purchase price: RM418.5 million.
    • Land area: Approximately 556.96 acres.
    • Estimated gross development value (GDV): RM3 billion.
    • Location: Kulai, within the Johor–Singapore Special Economic Zone growth corridor.
    • Planned development: A residential and commercial township.
    • First phase: Targeted for launch in 2028.
    • Development horizon: Approximately 10–15 years.

    The purchase price is approximately 4.23% below the RM437 million market valuation cited in the acquisition circular. Sime Darby Property’s extraordinary general meeting is scheduled for 3 November 2026 to seek approval from non-interested shareholders. The acquisition remains subject to the required approvals and other conditions. EdgeProp

    Sources: EdgeProp — Kulai land acquisition and shareholder approval; Sime Darby Property’s official announcement.

    Why It Matters

    This is a long-term landbank strategy, not an immediate housing launch.

    A developer acquiring a large parcel of land must consider more than the purchase price. Infrastructure, planning approvals, construction costs, future household demand and the pace of development all influence whether the investment ultimately creates value.

    The Johor–Singapore Special Economic Zone provides a potential economic growth context, but its existence does not guarantee that every development within the corridor will succeed.

    The estimated RM3 billion GDV is also not the same as profit. Development costs, financing, infrastructure obligations and the timing of sales still matter.

    Miichael’s Review

    I find this development interesting because it highlights the difference between buying land with potential and creating a successful township.

    A large landbank gives a developer flexibility to phase development according to market conditions. It can avoid bringing too many homes to market at once and adjust the product mix as the surrounding area develops.

    However, the ultimate question is whether the future township will meet genuine housing and commercial demand.

    I would examine:

    1. The employment and population growth expected in the surrounding area.
    2. Existing competing residential supply.
    3. Planned transport and infrastructure improvements.
    4. The affordability of the proposed homes.
    5. The developer’s ability to phase construction responsibly.

    My view: Land acquisition is the beginning of a property strategy, not proof of a successful investment. The real test will be how well the developer translates location potential into a sustainable community.


    STORY 2 — CapitaLand Malaysia Trust’s Distributable Income Rises 32.2%

    llustrative image of a logistics property relevant to Malaysia’s industrial and logistics real estate sector.

    What Happened?

    CapitaLand Malaysia Trust (CLMT) reported stronger third-quarter 2026 results, with distributable income increasing 32.2% year-on-year.

    For the quarter ended 30 September 2026, the trust reported:

    Financial measureQ3 2026Year-on-year change
    Distributable incomeRM46.3 million+32.2%
    Distribution per unit1.35 sen+21.6%
    RevenueRM126.5 million+9.1%
    Net property incomeRM79.4 million+14.9%
    Net profitRM47 million+35.5%

    CLMT attributed the stronger performance to contributions from industrial and logistics properties acquired in 2025, positive rental reversions, scheduled rent increases and lower financing costs.

    As at 30 September, overall portfolio occupancy stood at 94.3%, while committed retail occupancy was 93.1%. The trust’s gearing ratio was 38.3%. EdgeProp

    Sources: EdgeProp — CLMT’s third-quarter results, 22 October 2026; CLMT official website.

    Why It Matters

    This is a useful example of how a property investment trust can grow its income through a combination of acquisitions, rental performance and financing management.

    The result also demonstrates why investors should look beyond headline revenue.

    A REIT’s ability to generate distributable income depends on the performance of its properties, occupancy, operating expenses, financing costs and the capital required to maintain and expand its portfolio.

    However, one strong quarter does not establish that future distributions will grow at the same rate.

    Miichael’s Review

    For me, the important point is the relationship between property assets and the income they can sustainably generate.

    When evaluating a REIT, I would ask:

    • Are its properties attracting tenants?
    • Can rental income be maintained or improved?
    • Are acquisitions adding value after financing costs?
    • Is its debt manageable?
    • Are distributions supported by recurring property income?

    Industrial and logistics assets can also diversify a portfolio beyond conventional retail properties.

    But the quality of the underlying assets and the price paid for them remain important.

    My view: Property investment should be evaluated through both asset quality and income sustainability. A large property portfolio is valuable only when its assets can generate attractive returns relative to their costs and risks.


    STORY 3 — IHH Plans an 18-Acre Healthcare Campus in Medini, Johor

    What Happened?

    On 20 October, EdgeProp reported that IHH Healthcare Berhad was acquiring Afiniti Wellness in Iskandar Puteri, with plans to convert the property into an ambulatory care centre.

    The proposed facility will form part of an integrated healthcare campus spanning approximately 18 acres, bringing together the existing Gleneagles Hospital Johor, Afiniti Wellness and IHH’s existing landbank in Medini.

    The new centre is intended to provide consultations, diagnostic services, day surgery and other outpatient treatments.

    Retrofitting work was expected to begin shortly, with operations targeted for the second or third quarter of 2028. The purchase price for Afiniti Wellness was not disclosed. EdgeProp

    Sources: EdgeProp — IHH’s planned Medini healthcare campus, 20 October 2026; IHH Healthcare Malaysia’s official website.

    Why It Matters

    This development highlights the role that specialised facilities can play in shaping a property’s long-term use and value.

    Instead of constructing an entirely new building, IHH plans to adapt an existing property to support a wider healthcare ecosystem.

    The project also reflects how demand for healthcare services can influence commercial property use, particularly in locations where population, business activity and access to specialist services are expected to grow.

    However, the anticipated benefits will depend on actual demand, operating performance and the successful integration of the facilities.

    Miichael’s Review

    I see this as an example of property value being created through the right use, rather than simply through new construction.

    An existing building may become more useful when it is repositioned to meet a specific market need.

    For property developers and investors, the questions are:

    1. Is there sufficient demand for the intended use?
    2. Can the existing building be adapted efficiently?
    3. Will the location support the required customer or patient catchment?
    4. Does the new use create a sustainable operating model?
    5. Can the investment deliver long-term value without excessive capital expenditure?

    This is particularly relevant to commercial property owners considering how to reposition underutilised assets.

    My view: The strongest property strategies begin with understanding demand. Sometimes the opportunity is not to build more, but to make better use of what already exists.


    🌏 INTERNATIONAL PROPERTY WATCH

    🇯🇵 STORY 4 — Japan’s New Condo Market: Fewer Launches, but Prices Keep Rising

    Illustrative image of residential condominiums in Japan.

    What Happened?

    A market report published on 22 October by Japan Property Insight, based on data from the Real Estate Economic Institute, highlighted a striking contrast in the Kinki region, which includes the areas around Osaka, Kyoto and Kobe.

    For September 2026:

    • New condominium launches fell 49.6% year-on-year to 752 units.
    • The average unit price rose 37.6% to ¥70.75 million.
    • The average price per square metre increased 19.7% to ¥1.15 million.
    • The first-month contract rate was 62.6%.
    • Unsold inventory stood at 3,007 units.

    For the first half of Japan’s fiscal 2026, new launches in the region fell 8.6% to 6,557 units, while the average price rose 8.4% to ¥60.1 million. The first-month contract rate fell below 70% for the first time in four years. Japan Property Insight

    Source: Japan Property Insight — September 2026 condominium market report, published 22 October.

    Why It Matters

    The figures illustrate a situation where fewer new properties are being offered to buyers even as average prices rise.

    But an important distinction is necessary: the increase in average prices does not mean every existing property became 37.6% more valuable.

    When fewer units are launched, the mix of properties entering the market can change significantly. A smaller number of expensive projects can push up the overall average.

    At the same time, a lower contract rate suggests that sales absorption is not keeping pace with the higher price environment as comfortably as before.

    This is why property-market analysis needs to examine supply, prices and actual sales together.

    Miichael’s Review

    I find this an important lesson for buyers and investors.

    A market can report higher average prices while simultaneously experiencing weaker sales activity.

    That means we should not automatically interpret rising prices as evidence of stronger underlying demand.

    I would examine:

    • Whether the properties being launched are comparable with those launched previously.
    • Whether completed inventory is accumulating.
    • Whether buyers can afford the new price levels.
    • Whether transactions support the asking prices.
    • Whether the market is becoming increasingly divided between premium and more affordable properties.

    My view: Rising prices are only one part of the story. Understanding who can afford to buy, what is being supplied and how quickly units are selling gives us a much clearer picture of the market.


    🇺🇸 STORY 5 — US Homebuilding Weakens as Mortgage Costs Pressure Affordability

    Illustrative image of a US residential construction site.

    What Happened?

    On 20 October, Reuters reported that US single-family homebuilding fell in September as higher mortgage rates and elevated construction costs weighed on demand.

    According to the US Commerce Department’s Census Bureau:

    • Single-family housing starts fell 4.6% month-on-month to an annualised rate of 859,000 units, the lowest level since September 2025.
    • Single-family building permits fell 4.0% to an annualised rate of 845,000 units, the lowest since March 2023.
    • The average 30-year fixed mortgage rate was 7.40% in the preceding week, according to Freddie Mac data cited by Reuters.

    Separately, the National Association of Home Builders/Wells Fargo Housing Market Index fell three points to 29 in October, its lowest reading since June 2012.

    Builders were facing a combination of higher financing costs, elevated material and energy expenses, labour constraints and weak buyer demand. Reuters

    Sources: Reuters — US housing starts and permits weaken, 20 October 2026; The Wall Street Journal — US homebuilder confidence falls to a 14-year low.

    Why It Matters

    The US housing market illustrates how financing costs affect both sides of the property market.

    For buyers, higher mortgage rates reduce purchasing power and increase monthly repayments.

    For developers, weaker demand can make new projects more difficult to justify, particularly when construction costs remain elevated.

    There is also a longer-term concern: reducing new construction may ease immediate inventory pressure, but it does not automatically solve an underlying housing shortage.

    The challenge is to deliver homes at prices that buyers can afford while ensuring that developments remain financially viable.

    Miichael’s Review

    This reinforces a principle I have always considered important in property decisions: affordability is not determined by the asking price alone.

    A home may appear reasonably priced, but if financing costs push the monthly repayment beyond the buyer’s comfortable limit, demand can weaken.

    For developers, this means product planning must be connected to the actual purchasing capacity of the target market.

    For buyers, it means understanding the total cost of ownership rather than focusing only on the initial price.

    I would look at:

    1. Household income and debt commitments.
    2. Mortgage rates and repayment sensitivity.
    3. Construction costs and the supply of comparable homes.
    4. The relationship between asking prices and completed transactions.
    5. Whether a property remains affordable under less favourable conditions.

    My view: Sustainable property demand requires a realistic match between price, financing and household purchasing power. Without that balance, both buyers and developers can find themselves under pressure.


    WORTH WATCHING

    Here are the developments I would monitor over the next few weeks.

    MarketWhat to watchWhy it matters
    Malaysia — JohorShareholder approval and subsequent planning steps for the Kulai land acquisitionDetermines how the proposed township progresses from landbank strategy to implementation.
    Malaysia — REITsCLMT’s next results and distribution performanceHelps assess whether income growth is sustainable beyond one quarter.
    Malaysia — MediniProgress on the planned ambulatory care centreShows whether existing commercial property can be successfully repurposed for specialised demand.
    JapanNew condo launches, contract rates and unsold inventoryHelps distinguish price increases caused by supply composition from stronger underlying demand.
    United StatesMortgage rates, housing starts and builder confidenceIndicates whether financing pressure continues to affect homebuyers and future housing supply.

    MY TAKEAWAY THIS WEEK

    This week’s property news reinforces a common theme across different markets.

    In Malaysia, developers are positioning their landbanks for future growth, a REIT is reporting stronger income and an existing property is being repurposed for specialised healthcare use.

    In Japan, new condominium supply has contracted sharply even as average prices have risen. In the United States, higher mortgage costs are putting pressure on homebuilding and affordability.

    The circumstances differ, but the underlying questions remain similar.

    • Is there genuine demand for the property?
    • Is the asking price supported by market evidence?
    • Can the intended buyers afford the property?
    • Can the asset generate sustainable income?
    • Does the development create lasting value for its owners and surrounding community?

    A property can have a strong location, attractive design or impressive headline value and still be the wrong investment if the fundamentals do not support it.

    My approach remains simple: research first, evaluate objectively and make decisions based on the fundamentals.

    Look beyond the price. Understand the fundamentals before making the decision.

    Miichael Yeoh
    PROPERTY STRATEGIST

  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    10–16 October 2026

    LOOK BEYOND THE PRICE

    Five stories. Three Malaysian developments. Two international markets. One objective: helping buyers and investors make better-informed property decisions.

    🇲🇾 MALAYSIA PROPERTY MARKET

    STORY 1 — Why Are Malaysian Property Developers Becoming More Cautious?

    What Happened?

    A property industry survey reported by The Edge Malaysia on 15 October revealed that 63% of surveyed developers had no plans to launch residential projects in the second half of 2026.

    The survey by the Real Estate and Housing Developers’ Association Malaysia (REHDA) covered 181 respondents in Peninsular Malaysia.

    Key findings included:

    • 114 of 181 respondents had no plans for residential launches in the second half of 2026.
    • The remaining respondents planned to launch 18,696 units.
    • 77% of respondents reported financing difficulties during the first half of 2026.
    • 59% of respondents with relevant data reported unsold completed residential units as at 30 June 2026.
    • Among respondents who reported unsold completed units, 32% said some of their stock had remained unsold for more than three years.

    Developers cited market conditions, approval delays and existing unsold inventory as reasons for their cautious approach. The Edge Malaysia

    Source: The Edge Malaysia — REHDA property industry survey, 15 October 2026

    Why It Matters

    This is an important signal for Malaysia’s property market.

    A high number of new launches does not automatically mean a healthy market. What matters is whether homes are priced appropriately, buyers can obtain financing and completed units find genuine occupants.

    The financing figures are particularly noteworthy. Demand for housing may exist, but prospective buyers still need to qualify for loans and manage their financial commitments.

    Developers must also balance construction costs against what their target customers can realistically afford.

    Miichael’s Review

    I see this as a reminder that property development must follow real demand, not simply market excitement.

    When developers become more cautious, buyers should look beyond promotional campaigns and ask some practical questions:

    1. How many comparable properties are already available?
    2. Are existing developments attracting genuine buyers?
    3. Are asking prices supported by recent transactions?
    4. Can the intended buyers realistically obtain financing?
    5. Is the development designed for actual occupants or mainly for investors hoping to resell?

    The survey also suggests that different property categories are performing differently. Buyers should therefore avoid treating the entire Malaysian market as one uniform market.

    My view: A more selective market can reward careful research. Buyers need to distinguish between a property that is attractively marketed and one that is genuinely well positioned.


    STORY 2 — Malaysia Reports 1,726 Revived Housing Projects: What Does This Mean for Buyers?

    What Happened?

    On 14 October, EdgeProp Malaysia reported on the Housing and Local Government Ministry’s update that 1,726 sick or abandoned private housing projects had been revived since 2023.

    The projects involved approximately:

    • 199,643 housing units
    • RM158 billion in gross development value
    • 1,542 sick projects completed with Certificates of Completion and Compliance
    • 147 projects restored to smooth status
    • 37 abandoned projects resolved through physical completion or arrangements benefiting buyers

    The ministry also reported that, as at 31 August 2026, Kuala Lumpur still had seven projects classified as abandoned and another 12 classified as sick.

    The government has set a target of eliminating sick and abandoned housing projects by 2030. EdgeProp

    Source: EdgeProp Malaysia — Housing project rehabilitation update, 14 October 2026

    Why It Matters

    A stalled housing project can create serious financial and emotional difficulties for buyers.

    They may have paid deposits and progressive payments, committed to housing loans and continued paying rent while waiting for their homes.

    The reported rehabilitation figures are encouraging, but one distinction matters: a project being revived does not necessarily mean every unit has been completed and handed over.

    The different outcomes must be examined individually.

    For prospective buyers, this is also a reminder to assess the delivery record of a developer and the actual status of a project before committing.

    Miichael’s Review

    I welcome efforts to protect homebuyers and resolve problematic developments.

    However, I would assess a project’s progress using evidence rather than announcements alone.

    Before buying into an ongoing development, I would want to understand:

    • The developer’s financial and delivery track record.
    • The project’s construction progress.
    • Whether the required approvals and legal arrangements are in place.
    • Whether there are known disputes or rehabilitation issues.
    • The expected completion date and the evidence supporting it.

    For buyers already affected by a stalled project, the available rehabilitation route and legal position are particularly important.

    My view: The real measure of success is not simply how many projects have been declared revived. It is how many affected buyers ultimately receive the homes or appropriate resolutions they were promised.


    STORY 3 — IOI Properties Advances Its Proposed RM7.66 Billion REIT Listing

    What Happened?

    IOI Properties Group Berhad advanced its proposed Malaysian real estate investment trust (REIT) listing after signing an underwriting agreement with six financial institutions.

    According to EdgeProp Malaysia on 12 October:

    • The proposed REIT has nine initial assets.
    • The portfolio was valued at approximately RM7.66 billion as at 31 May 2026.
    • The proposed offering could involve up to 2.2 billion units.
    • The underwriting agreement covers 165 million offer units, subject to the offering’s allocation provisions.
    • The prospectus was targeted for the fourth quarter of 2026, with listing targeted by year-end.

    The initial portfolio includes IOI City Mall, six hotels and two office properties.

    These are proposed listing arrangements; the announcement did not mean the IPO had already been completed. EdgeProp

    Source: EdgeProp Malaysia — IOI Properties advances proposed REIT IPO, 12 October 2026

    Why It Matters

    A REIT provides a way for investors to gain exposure to income-generating property through a listed investment vehicle rather than purchasing an entire property themselves.

    For the property sector, a listing can provide another route for capital management and potentially broaden investor participation.

    However, a large property portfolio does not automatically make a REIT an attractive investment.

    Investors still need to examine rental income, occupancy, financing costs, debt levels, asset valuations and the proposed distribution policy.

    Miichael’s Review

    This is worth watching because it connects property ownership with capital markets.

    For individual investors, a REIT may offer a different way to participate in commercial property, hotels and retail assets without directly managing a building.

    But the decision should be based on the investment’s fundamentals.

    I would look carefully at:

    1. The quality and location of the underlying assets.
    2. The sustainability of rental income.
    3. Financing costs and gearing.
    4. The proposed distribution yield and how it is calculated.
    5. Whether the offering valuation is reasonable relative to comparable investments.

    My view: The important question is not merely how much the portfolio is worth. It is whether its assets can generate sustainable income at a valuation that makes sense for investors.


    🌏 INTERNATIONAL PROPERTY WATCH

    🇦🇪 STORY 4 — Dubai Buyers Shift Towards Completed Homes as the Market Becomes More Selective

    What Happened?

    A third-quarter 2026 residential market report from betterhomes, reported by Khaleej Times on 15 October, showed a shift towards completed homes in Dubai.

    Key findings included:

    • Sales of ready residential properties rose 16% quarter-on-quarter.
    • Secondary-market transactions reached 10,055, with a total value of Dh27.1 billion.
    • Secondary-market transactions accounted for 29% of total residential sales, up from 24% in the second quarter.
    • Overall residential sales totalled 34,615 transactions during the quarter, broadly unchanged from the previous quarter.
    • Median apartment prices declined 2.4% between June and September, while villa and townhouse prices fell 2.3%.

    Despite the quarterly price declines, prices remained higher than a year earlier. Rental enquiries also rose sharply, although median rents eased in several market segments. Khaleej Times

    Source: Khaleej Times — Dubai ready-home sales jump 16%, 15 October 2026

    Why It Matters

    The figures suggest that buyers are becoming more selective about the type of property they purchase.

    Completed homes offer advantages that off-plan properties cannot immediately provide: buyers can inspect the actual unit, assess the surrounding community and potentially receive rental income sooner.

    However, the reported shift does not mean off-plan properties have become universally unattractive. Different buyers have different financial circumstances, objectives and risk tolerances.

    The decline in quarterly prices also highlights the importance of comparing actual transactions rather than relying exclusively on advertised prices.

    Miichael’s Review

    This is an interesting development for property investors.

    A completed property may provide greater visibility into its condition, rental demand and surrounding environment. An off-plan property may offer different advantages, but it also requires buyers to assess delivery risk and future market conditions.

    I would compare both options using the same criteria:

    • Total acquisition cost.
    • Expected rental income.
    • Maintenance and other holding expenses.
    • Financing commitments.
    • Comparable transaction prices.
    • Exit options if market conditions change.

    My view: A completed property is not automatically a better investment, just as an off-plan property is not automatically a better bargain. The right choice depends on the numbers, the risks and the buyer’s objectives.


    🇨🇦 STORY 5 — Canadian Home Sales Fall Again as Mortgage Rates Weigh on Buyers

    What Happened?

    On 16 October, Reuters reported that Canadian home sales declined again in September as higher mortgage rates and expectations of a possible interest-rate increase weighed on market activity.

    According to the Canadian Real Estate Association (CREA):

    • National home sales fell 2.3% month-on-month in September, following a 0.7% decline in August.
    • Sales were down 7.7% year-on-year on an unadjusted basis.
    • The Home Price Index declined 0.4% month-on-month and 3.4% year-on-year.
    • New property listings fell 1.8% from August.
    • The seasonally adjusted sales-to-new-listings ratio slipped to 48.8%, below its long-term average of 54.7%.

    At the time of the report, financial markets were pricing in the possibility of a 25-basis-point Bank of Canada rate increase in December. This was a market expectation, not a confirmed policy decision. Reuters

    Source: Reuters — Canadian home sales fall in September as mortgage rates increase, 16 October 2026

    Why It Matters

    The Canadian market demonstrates how financing conditions can affect property transactions.

    Even when prospective buyers want to purchase homes, higher mortgage costs can reduce borrowing capacity or make buyers more cautious about committing.

    A slower market may give some buyers more time to negotiate. However, it does not automatically mean that every property is attractively priced.

    Local conditions also matter: national figures can conceal significant differences between cities, neighbourhoods and property types.

    Miichael’s Review

    For me, the main lesson is the relationship between financing and affordability.

    When interest rates rise, a buyer may qualify for a smaller loan or face a higher monthly repayment. That can change which properties are financially sensible.

    Before committing, I would ask:

    1. Can I afford the repayments if borrowing costs increase?
    2. Does the property remain affordable after taxes, insurance and maintenance?
    3. Is the asking price supported by recent comparable transactions?
    4. Can I sustain ownership if resale takes longer than expected?
    5. Am I buying because the property suits my needs, or because I expect prices to rise?

    My view: A property purchase should be financially sustainable even when market conditions become less favourable. Buyers who understand their financing limits are better placed to make measured decisions.


    WORTH WATCHING

    Here are five developments I would monitor over the coming weeks.

    AreaWhat to watchWhy it matters
    MalaysiaDeveloper launch plans and sales performanceShows whether supply is responding to genuine demand.
    MalaysiaRehabilitation of sick and abandoned housing projectsBuyers need evidence of actual progress and resolution.
    MalaysiaIOI Properties’ proposed REIT prospectusProvides details for evaluating the portfolio, pricing and distribution policy.
    UAECompleted-home prices, rents and transaction activityHelps investors assess whether market conditions support their objectives.
    CanadaMortgage rates, sales activity and home-price trendsProvides an indication of how financing conditions affect affordability and demand.

    MY TAKEAWAY THIS WEEK

    This week’s property news reinforces a principle that applies across markets:

    Property decisions should be based on fundamentals, not headlines.

    In Malaysia, developers are becoming more cautious, housing-project rehabilitation remains important, and a proposed REIT listing offers another way to participate in property investment.

    In Dubai, buyers are showing greater interest in completed homes, while prices and rents are becoming more competitive in some segments.

    In Canada, higher borrowing costs are weighing on transactions.

    These markets have different conditions, but the underlying questions are similar.

    • Is the property priced reasonably?
    • Is there genuine demand?
    • Can the buyer afford to own it comfortably?
    • Does the investment generate sustainable income?
    • Are the risks manageable if the market changes?

    A property can look attractive on paper but still be unsuitable for a particular buyer.

    Look beyond the price. Understand the fundamentals before making the decision.

    Miichael Yeoh
    PROPERTY STRATEGIST
    miichaelyeoh.com

  • New Launch vs Subsale: Which Property Should You Buy?

    New Launch vs Subsale: Which Property Should You Buy?

    Written by: Miichael Yeoh

    A new property feels safer. An existing property feels more predictable.

    But neither statement is necessarily true.

    A new launch may offer attractive incentives, modern facilities and a fresh building. A subsale property may allow you to inspect the actual unit, understand the surrounding neighbourhood and investigate existing rental demand.

    So, which should you buy?

    The answer depends on what you’re paying, what you’re getting, what risks you’re taking and what you expect the property to deliver.

    Let’s look beyond the showroom and examine the decision properly.

    1. The Malaysian Property Market Is Giving Buyers a Reason to Be Selective

    Malaysia’s property market remained active in the first half of 2026.

    The first-half property market report recorded 187,320 property transactions worth RM105.12 billion. At the same time, 33,094 completed residential units remained unsold, valued at approximately RM17.78 billion.

    Developers also launched 27,832 residential units during H1 2026, with reported sales performance of 16.6%.

    These figures don’t mean new launches are bad or that subsale properties are automatically better.

    They tell us something more useful.

    Buyers should not assume that a new launch is a good purchase simply because a developer has launched it, or that an existing property is good value simply because someone is reselling it.

    Every property needs to be evaluated on its own merits.

    And that brings us to the first important difference.

    2. New Launch vs Subsale: What Are You Actually Buying?

    Let’s start with the basic distinction.

    A new-launch property is generally purchased directly from a developer, often before construction is completed.

    A subsale property is an existing property purchased from its current owner.

    That difference affects much more than the age of the building.

    Property Condition

    New launch: The property may still be under construction, so the finished quality cannot yet be fully assessed.

    Subsale: You can inspect the actual unit and building before making your decision.

    Pricing

    New launch: The price is set by the developer, with incentives or rebates subject to the terms offered.

    Subsale: The price may be negotiable, depending on the seller and comparable market transactions.

    Rental Income

    New launch: Rental income generally begins only after completion, handover and preparation for tenants.

    Subsale: Rental income may begin sooner if the property is ready and suitable for tenants.

    Construction Risk

    New launch: An uncompleted project carries delivery and construction-related risks.

    Subsale: A completed property avoids the risk of waiting for construction completion, although other risks remain.

    Defects and Renovation

    New launch: You may need to furnish the unit and address defects identified at handover.

    Subsale: You may need to repair existing defects, renovate or replace ageing fittings.

    Facilities and Management

    New launch: The long-term quality of building management has yet to be demonstrated.

    Subsale: You can assess the existing facilities, maintenance and management standards.

    Rental Demand

    New launch: Future rental demand must be estimated using market evidence and competing supply.

    Subsale: Existing rental listings and tenancy evidence may help you assess demand, although future conditions can change.

    Main Uncertainty

    New launch: Completion, final quality, future supply and market conditions.

    Subsale: Hidden defects, maintenance costs, building condition and future resale demand.

    Neither option wins every category.

    The mistake is choosing based on the benefits of one option while ignoring its disadvantages.

    3. Is a New Launch Cheaper Than a Subsale?

    This is where many buyers need to slow down.

    Imagine two condominiums in a similar location.

    Property A: New launch

    • Developer’s selling price: RM600,000
    • Advertised rebate: 8%
    • Indicative price after the rebate: RM552,000

    Property B: Subsale

    • Seller’s asking price: RM530,000
    • Negotiated purchase price: RM515,000

    At first glance, the subsale property appears cheaper.

    But are we comparing the same thing?

    What is the actual transaction price of comparable units?

    Does the new launch include furnishing, parking or other items that would otherwise cost extra?

    Does the subsale unit require RM30,000 in renovation?

    Are the maintenance fees comparable?

    Are both properties equally attractive to future tenants?

    What are the legal, financing and other acquisition costs applicable to each transaction?

    Until you answer these questions, you don’t know which property offers better value.

    Look Beyond the Advertised Price

    Developer incentives can reduce the buyer’s effective cost, but their value depends on the actual terms and what is included.

    Similarly, a subsale seller’s asking price may not reflect the final negotiated price.

    Compare the complete acquisition cost rather than relying on the headline figure.

    And remember:

    A lower purchase price does not automatically mean a better investment.

    4. The Hidden Difference: When Can the Property Start Working for You?

    For investors, this may be one of the most important differences.

    Suppose you purchase a new-launch condominium that will take several years to complete.

    During that period, you may have construction-stage financing payments, depending on the loan structure. You also have to wait until the property is completed, handed over and ready before rental income can begin.

    Now consider a completed subsale condominium.

    If the unit is in good condition and the rental market is established, you may be able to rent it out after completing the purchase and preparing the unit.

    The difference is time.

    Let’s Use a Simple Illustration

    Assume the subsale property can generate RM2,000 per month in rent once it is ready and occupied.

    If the new launch takes three years to complete, the theoretical gross rental income forgone over those 36 months is:

    RM2,000 × 36 months = RM72,000.

    That is a significant amount.

    But don’t misunderstand the calculation.

    RM72,000 is not a guaranteed loss or a complete comparison of the two investments. It is an illustration of potential gross rental income over that period, assuming the subsale could have been rented continuously.

    Actual results would depend on vacancy, expenses, financing, tenant demand and the timing of rental readiness.

    The new launch might also appreciate during construction. The subsale might need substantial renovation or suffer from weak tenant demand.

    The lesson is not that subsale always wins. It’s that time has a financial value, and investors should calculate it.

    5. Can You Trust the Rental Demand for a New Launch?

    This is a question I would ask before purchasing either type of investment property.

    A developer might describe a project as ideal for young professionals, expatriates or students.

    That may be a reasonable target market.

    But a target market is not proof of rental demand.

    Before buying, investigate:

    • Who actually works or studies nearby?
    • What rents are comparable units achieving?
    • How many similar units are already available?
    • How long do comparable properties typically take to find tenants?
    • What facilities and transport options matter to the intended tenants?
    • How many competing developments are expected to be completed?
    • What will make your property more attractive than the alternatives?

    For a completed subsale unit, you may be able to examine existing rental listings, speak to property managers and investigate actual tenancy evidence.

    For an uncompleted new launch, you will have to make more assumptions about future conditions.

    That doesn’t make the new launch a poor investment.

    It simply means the further you are from observable evidence, the more carefully you need to test your assumptions.

    6. What About Building Quality and Defects?

    One advantage of buying a new residential property from a developer is that qualifying purchases under prescribed housing development agreements have statutory protections, including a defect liability period.

    For standard Schedule G and Schedule H agreements, the defect liability period is generally 24 months from vacant possession, subject to the applicable agreement and legal provisions.

    However, a new building is not necessarily a defect-free building.

    You still need to inspect the unit when it is handed over, document defects and follow the proper procedures for reporting them.

    A subsale property presents a different situation.

    You can inspect the actual unit before purchasing, but you may inherit problems such as:

    • Water leakage
    • Damaged flooring
    • Ageing electrical or plumbing systems
    • Poor renovation work
    • Lift or common-area maintenance issues
    • Inadequate sinking-fund reserves
    • Disputes or management problems

    Some problems are visible. Others may require professional inspection or further investigation.

    For a subsale condominium, I would want to understand the condition of both the individual unit and the overall building.

    A brand-new unit can have defects. An older unit can be well maintained. Age alone does not determine quality.

    Note: The applicable legal protections depend on the type of property, transaction and agreement. Buyers should confirm their position with a qualified property lawyer.

    7. Don’t Ignore the Building’s Management

    This is particularly important when comparing condominiums.

    A new launch may offer an impressive swimming pool, gym, landscaped garden and other facilities.

    But who will maintain them?

    Will the maintenance charges be sustainable for residents?

    Will the facilities remain attractive after several years?

    For a completed property, you have something valuable: evidence of how the building is actually being managed.

    Look at:

    • The condition of common areas
    • Lift maintenance
    • Cleanliness and security
    • Maintenance-charge collection
    • Sinking-fund position
    • Major repairs required
    • Management responsiveness
    • The overall resident experience

    A well-maintained older condominium may provide a better ownership experience than a newer building with poor management.

    Equally, an older building with serious maintenance problems may create expenses that a buyer has underestimated.

    Don’t just compare the units. Compare the buildings behind them.

    8. Which Is Better for First-Time Homebuyers?

    There is no universal answer, but the priorities are different from those of an investor.

    A first-time buyer should consider:

    Affordability: Can you comfortably manage the purchase and ongoing costs?

    Move-in timing: Do you need a home soon, or can you wait for construction to finish?

    Location: Does it work for your job, family, transport needs and daily routine?

    Condition: Are you prepared to manage renovation, repairs or defects?

    Certainty: Would you prefer to inspect an existing unit, or are you comfortable committing to a property that has not yet been completed?

    Future flexibility: If your job or family circumstances change, will the property be reasonably easy to rent out or sell?

    A new launch may suit someone who wants a new home and can wait for completion.

    A subsale may suit someone who wants to inspect the actual property and move in sooner.

    But neither option should stretch your finances to the point that a change in income becomes a crisis.

    Your first property should support your life, not make your life revolve around the mortgage.

    9. Which Is Better for Property Investors?

    For investors, I would focus less on whether the property is new or old and more on the investment case.

    Ask five questions.

    A. What Is My Total Investment?

    Include the purchase price, transaction costs, financing costs, renovation, furnishing and other relevant expenses.

    B. When Can I Realistically Earn Rental Income?

    Account for construction, completion, preparation, vacancy and tenant-finding time.

    C. What Is My Expected Net Return?

    Do not confuse gross rental yield with actual cash flow or net return. Include recurring expenses, vacancy, repairs and financing where relevant.

    D. What Competition Am I Facing?

    Consider both existing properties and future supply.

    E. How Will I Exit?

    Think about the future buyer, resale demand, likely competition and the price at which the property might realistically sell.

    A new launch could offer an attractive opportunity if the price, location, product and future demand justify the purchase.

    A subsale could be attractive if its price is supported by evidence, its condition is acceptable and its rental or owner-occupier demand is sustainable.

    Either could be a poor investment if the numbers don’t work.

    10. The PDS New Launch vs Subsale Decision Test

    Before making a decision, I would compare the two properties using the same framework.

    1. What is the true acquisition cost?

    Include the purchase price, incentives, legal costs, financing and necessary improvements.

    2. What evidence supports the price?

    Look at comparable transactions and the property’s actual features.

    3. What demand exists?

    Investigate owner-occupier demand, tenant demand and the reasons people choose the location.

    4. What are the holding costs?

    Calculate the mortgage, maintenance, repairs, insurance and other recurring expenses.

    5. What risks am I accepting?

    Consider construction, defects, renovation, vacancy, management and future supply.

    6. What is the realistic return?

    Assess net rental income, financing impact, potential capital appreciation and costs.

    7. How will I exit?

    Identify the likely future buyer, resale demand and competing properties.

    The most important point is to compare like with like.

    If the two properties are in different locations, serve different tenant markets or offer different layouts, a simple price comparison may be misleading.

    And if you’re comparing a completed property with one that won’t be ready for several years, timing needs to be part of the analysis.

    So, New Launch or Subsale?

    My answer is straightforward.

    Buy a new launch when the product, price, developer, location and future demand justify the commitment.

    Buy a subsale when the actual property, condition, market evidence and total cost make the purchase worthwhile.

    Don’t choose a new launch just because it is new.

    Don’t choose a subsale just because it appears cheaper.

    And don’t assume that developer incentives, a beautiful showroom or an existing tenant automatically make a property a good investment.

    The right decision comes from understanding what you are buying and why it should meet your needs.

    That is the difference between choosing a property and evaluating a property.

    The Final PDS Insight

    When buyers compare new launches and subsale properties, they often begin with the wrong question:

    “Which one is better?”

    I would start somewhere else.

    “Better for whom, at what price, for what purpose and over what period?”

    A property that suits a first-time homeowner may not suit a rental investor.

    A property that works for a ten-year holding period may not work for someone who needs flexibility within three years.

    And a property that looks attractive today may face very different competition tomorrow.

    There is no shortcut around the discovery process.

    There is only a better way to make the decision.

    Don’t just compare the properties. Discover the decision behind them.

    Property Discovery System™

    Discover Better. Decide Smarter.


  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    Week in Review | Saturday, 3 October – Friday, 9 October 2026

    Explore five property updates from Malaysia, Australia and the UK, covering Budget 2027 housing measures, infrastructure delivery and changing market conditions.


    🇲🇾 STORY 1 — Budget 2027: New Stamp Duty Relief for First-Time Homebuyers

    What Happened?

    On 9 October 2026, Prime Minister Anwar Ibrahim tabled Budget 2027, proposing stamp duty exemptions for eligible first-time homebuyers.

    The proposed measures are:

    • Homes priced up to RM500,000: Full stamp duty exemption on the loan agreement and instrument of transfer.
    • Homes priced up to RM750,000: Full exemption on the first RM500,000, with a 50% exemption on the remaining amount.
    • Proposed eligibility period: Sale and purchase agreements executed from 1 January 2027 to 31 December 2030.

    The government also proposed stamp duty relief for transactions involving the rehabilitation of abandoned housing projects. Prime Minister’s Office Malaysia

    Sources: Prime Minister’s Office of Malaysia — Budget 2027 speech · The Star — First-home stamp duty announcement

    Why It Matters

    Stamp duty can be a significant upfront expense for a homebuyer.

    Reducing this cost could make it easier for some first-time buyers to complete a purchase, particularly those already stretching their savings to cover the deposit, legal fees, moving expenses and basic furnishing.

    However, there is an important distinction between making a home cheaper to purchase and making it affordable to own.

    Monthly instalments, maintenance charges, insurance, repairs and emergency savings remain part of the equation.

    Miichael’s Review

    I welcome measures that reduce the barriers to homeownership.

    But I would not advise anyone to rush into buying a property simply because an incentive is available.

    Before making a decision, buyers should ask themselves three questions:

    1. Can I comfortably afford the monthly repayments?
    2. Will I still have sufficient cash reserves after completing the purchase?
    3. Is this the right property for my needs, location and long-term plans?

    The proposed exemption is useful, but the final eligibility rules and implementation details must also be checked.

    My view: A government incentive should improve a sound property decision, not become the reason for making one.


    🇲🇾 STORY 2 — RM20 Billion Housing Guarantee to Support 80,000 First-Time Buyers

    What Happened?

    Budget 2027 provides for housing financing guarantees of up to RM20 billion through the Housing Credit Guarantee Scheme (SJKP), with the aim of assisting 80,000 first-time buyers.

    The scheme particularly targets people who may struggle to obtain conventional housing financing because they are self-employed or do not receive a fixed monthly income.

    The government also announced nearly RM1 billion for housing initiatives, including Rumah Mesra Rakyat and Program Residensi Rakyat. Four new housing projects were announced for Kulai in Johor, Nilai in Negeri Sembilan, Paya Rumput in Melaka and Pertang Valley in Terengganu. Prime Minister’s Office Malaysia

    Sources: Prime Minister’s Office of Malaysia — Budget 2027 housing measures · The Star — RM20 billion SJKP guarantee

    Why It Matters

    This addresses one of the practical challenges facing Malaysian homebuyers: access to financing.

    Some self-employed individuals have sufficient income to meet repayments but find it difficult to satisfy conventional lending requirements because their earnings fluctuate or are documented differently.

    A financing guarantee can help eligible applicants access housing loans. However, it does not mean every applicant will automatically receive loan approval.

    There is also a wider issue to consider.

    Helping more people obtain financing is only part of the solution. The market must also provide homes that buyers can genuinely afford, in locations that suit their work, family needs and daily routines.

    Miichael’s Review

    This measure is particularly relevant to younger buyers, entrepreneurs and people with non-traditional income arrangements.

    However, I would like to see how the scheme works in practice.

    How accessible will it be? What are the eligibility conditions? Will the homes available to these buyers match their budgets?

    Financing access and housing affordability must work together.

    Otherwise, we may help people qualify for loans without necessarily helping them find suitable homes.


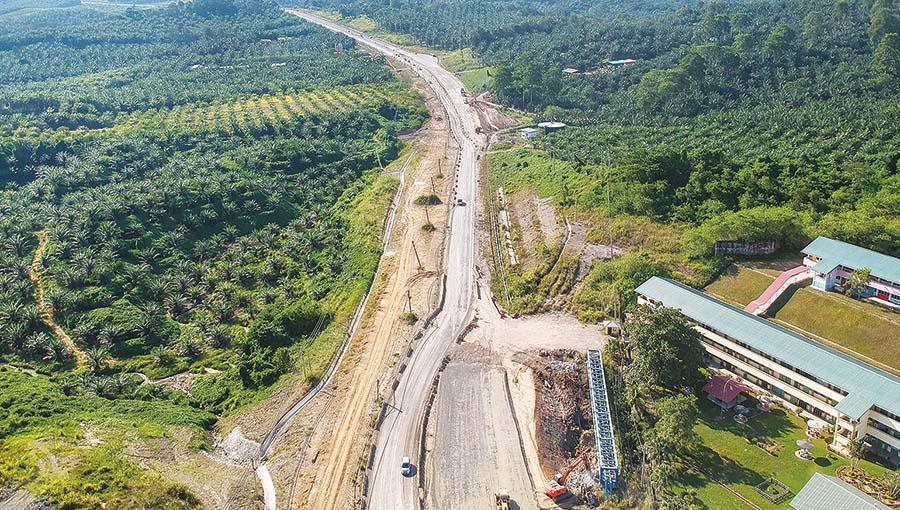
    🇲🇾 STORY 3 — Sabah Pan Borneo Highway: Infrastructure Delivery Matters More Than Announcements

    What Happened?

    The Auditor-General’s Report 2/2026, tabled on 5 October, highlighted cost increases and delivery problems affecting Sabah Pan Borneo Highway Phase 1.

    The report stated that contract costs had risen to RM18.96 billion, compared with the original RM17.91 billion.

    As at 31 March 2026, only 4 of the 35 work packages had been completed.

    The report also identified site-readiness and land-acquisition problems, RM513.99 million in variation orders approved beyond authorised limits, and RM41.37 million in delayed utility claims. These are figures reported in the audit, and the completion count relates to the position at the stated date. EdgeProp

    Source: EdgeProp Malaysia — 5 October property and infrastructure digest, reporting on the Auditor-General’s Report 2/2026.

    Why It Matters

    Infrastructure can influence property values by improving access to employment, commercial centres, tourism destinations and essential services.

    But there is a difference between a project being announced, a project being constructed and a project being completed and operational.

    Delays can postpone the economic benefits that were expected to support surrounding areas.

    For buyers and investors, this means that a property’s location should be evaluated against infrastructure that is actually available, as well as projects that remain under construction.

    Miichael’s Review

    When evaluating property near a major infrastructure project, I would not rely on a developer’s location map alone.

    I would examine:

    • Which sections of the road are already operational?
    • How much travel time will actually be saved?
    • Are employment opportunities and commercial activities growing nearby?
    • Will utilities and public services be sufficient for future development?
    • Is the property priced as though future improvements have already been delivered?

    Infrastructure creates potential, but execution determines when—and whether—that potential becomes real.

    This is an important lesson for property buyers in every state, not just Sabah.


    🌏 INTERNATIONAL PROPERTY WATCH

    🇦🇺 STORY 4 — Australia: Housing Prices Fall for a Sixth Consecutive Month

    What Happened?

    National Australia Bank’s October Housing Monitor, published on 7 October, reported that dwelling prices across Australia’s combined capital cities fell 1.2% month-on-month in September 2026.

    This marked the sixth consecutive monthly decline. Prices were 6.4% below their March 2026 peak.

    NAB also revised its forecast to an 8% decline in capital-city dwelling prices over 2026, with a possible peak-to-trough decline of 11%.

    The median time a property spent on the market increased to 41 days, the highest level since late 2020. These figures reflect NAB’s analysis and forecasts, not guaranteed future outcomes. NAB

    Source: National Australia Bank — October 2026 Housing Monitor

    Why It Matters

    The downturn has broadened beyond the markets that initially showed the greatest weakness.

    For buyers, falling prices and longer selling periods may create more room for negotiation. Sellers may need to be more realistic about pricing and the time required to secure a buyer.

    But a declining market does not automatically mean every property is a bargain.

    A property bought at a lower price can still be a poor investment if rental demand is weak, financing costs are high or the local economy deteriorates.

    Miichael’s Review

    I would not look at falling prices in isolation.

    For investors, the more important questions are:

    • Is the purchase price attractive relative to comparable properties?
    • Can rental income reasonably cover the holding costs?
    • Is the local employment base resilient?
    • Can the investment withstand a longer period of weak prices?
    • Would I still want to own this property if the market took several years to recover?

    The best buying opportunity is not necessarily when prices fall the most. It is when the price, risk and long-term fundamentals make sense together.


    🇬🇧 STORY 5 — United Kingdom: Buyer Confidence Weakens While Rental Demand Remains Firm

    What Happened?

    The Royal Institution of Chartered Surveyors (RICS) published its September UK Residential Market Survey on 6 October.

    The survey reported:

    • New buyer enquiries: Net balance of -22%, compared with -18% in August.
    • Agreed sales: Net balance of -18%, compared with -16% in August.
    • House-price sentiment: Net balance of -32%, compared with -28% in August.
    • Tenant demand: Net balance of +23%.
    • Expected rental growth: Net balance of +37% for the following three months.

    The figures suggest weaker buyer sentiment and sales activity alongside continued rental demand. RICS

    Source: RICS — UK Residential Survey, September 2026

    Why It Matters

    The sales and rental markets do not always move in the same direction.

    In the UK, buyers were becoming more cautious while rental demand remained comparatively strong.

    One important clarification: RICS net balances measure the difference between respondents reporting increases and those reporting decreases. A -32% house-price balance does not mean that actual house prices fell by 32%.

    For property investors, rental demand is only one part of the equation. Purchase price, mortgage costs, taxes, maintenance, regulation and net rental yield all matter.

    Miichael’s Review

    This is a good example of why property investors should separate capital-growth expectations from rental fundamentals.

    A market may offer rental opportunities even when transaction activity is weak. But strong rental demand alone does not guarantee a good investment.

    Investors need to understand what remains in their pocket after financing, maintenance, taxes and other expenses.

    Rental demand is a useful signal. Net returns and the ability to sustain ownership are what ultimately matter.


    WORTH WATCHING

    Over the coming weeks, I would pay particular attention to four developments.

    1. Malaysia’s Budget 2027 implementation

    The proposed stamp duty exemptions are encouraging, but the final eligibility conditions and implementation documents will be important. Buyers should not assume that every transaction automatically qualifies.

    2. Financing access for first-time buyers

    The RM20 billion SJKP guarantee is a substantial measure. The next question is how effectively it translates into approved financing and sustainable homeownership.

    3. Infrastructure execution in Malaysia

    The Pan Borneo audit highlights the importance of monitoring actual construction progress, costs and completion dates. Future property decisions should be based on realistic delivery expectations.

    4. International borrowing costs and market conditions

    Australia and the UK show why buyers and investors must continue to monitor financing costs, transaction activity, prices and rental conditions rather than relying on a single market headline.


    MY TAKEAWAY THIS WEEK

    This week reinforces a principle I have always believed in: a property decision should never be based on price alone.

    Malaysia is trying to reduce barriers to homeownership, but buyers still need sustainable financing and suitable homes.

    Australia reminds us that prices can continue falling longer than investors expect.

    The UK shows that sales and rental conditions can move in different directions.

    And the Pan Borneo audit reminds us that infrastructure announcements only create lasting value when projects are delivered.

    For buyers and investors, the questions remain the same:

    • Can I afford it comfortably?
    • Is there genuine demand?
    • Does the location have the infrastructure and economic activity to support it?
    • Do the numbers work under conservative assumptions?
    • Would this still be a sensible decision if the market did not rise as quickly as I hoped?

    Look beyond the price. Understand the fundamentals before making the decision.

    Miichael Yeoh
    PROPERTY STRATEGIST
    www.miichaelyeoh.com

    Thank you for subscribing!

    Please check your email to confirming your subscription.

  • SST Increase from 6% to 8%: How It Will Impact Malaysia’s Property Industry

    SST Increase from 6% to 8%: How It Will Impact Malaysia’s Property Industry


    Introduction

    Starting July 1, 2025, the Malaysian government officially raised the Sales and Services Tax (SST) from 6% to 8%, aiming to increase national revenue and reduce fiscal deficits. While basic necessities and certain essential services remain exempt, many sectors — including construction, legal, professional, and property-related services — are now affected. This tax adjustment is expected to have ripple effects across various industries, especially the property market, which is already facing affordability challenges.

    This article examines how the SST hike impacts the property industry, giving practical examples and offering insights into how buyers, developers, and investors might respond.


    1. Scope of SST Increase in the Property Sector

    The SST increase does not apply directly to the sale of residential properties, which are exempt from SST. However, indirect costs will go up due to increased service charges in the construction, legal, and property management sectors. These cost increments will eventually be transferred to end buyers and tenants, especially in commercial and high-rise residential developments.


    2. Areas Affected in Property Development

    Here’s a breakdown of how the 2% SST increase affects the property ecosystem:

    Service TypeBaseOld SST (6%)New SST (8%)
    Architect/Engineer FeesRM100,000RM106,000RM108,000
    Legal/Stamping ServicesRM20,000RM21,200RM21,600
    Renovation/Interior Fit-OutRM150,000RM159,000RM162,000
    Property Management ServicesRM50,000RM53,000RM54,000
    Advertising & MarketingRM30,000RM31,800RM32,400

    Example:
    A developer constructing a new serviced apartment project incurs around RM5 million in professional and management fees. Under the previous 6% SST, the tax was RM300,000. Now, it’s RM400,000 — a 33% increase in SST cost, which could result in higher launch prices to maintain developer margins.


    3. Impact on Property Developers

    • Higher Development Cost: Most developers will face a 5–8% increase in overall project costs when combined with inflation and compliance costs.
    • Price Adjustment Pressure: Developers may either absorb the cost (lowering margins) or pass it to consumers — likely raising launch prices, especially in urban areas.
    • Delay in New Launches: Some developers may delay project launches until market conditions stabilize.

    4. Impact on Homebuyers

    Although SST is not directly charged on residential property purchases, buyers may feel the pinch in several ways:

    • Higher Property Prices: Due to rising development and marketing costs.
    • Increased Renovation Expenses: Renovation and interior design are service-based industries and are now charged 8% SST.
    • Increased Maintenance Fees: Management services in condos or commercial buildings may increase, translating to higher monthly maintenance charges for owners and tenants.

    5. Impact on Real Estate Investors

    Investors will also be affected indirectly:

    • Lower Rental Yield: If property prices go up but rental rates remain stagnant, net returns will shrink.
    • Higher Operational Costs: Especially for those managing short-term rentals or Airbnb units (cleaning, advertising, renovation services all now taxed at 8%).
    • Buyer Caution: Investors may delay purchases or switch to lower-risk assets like REITs or landed residential properties outside city centers.

    6. Outlook and Strategies

    Despite the challenges, the SST increase may drive some positive changes:

    • Developers may adopt cost-efficiency technologies to maintain affordability.
    • Buyers may turn to subsale markets, which are less affected by SST-related costs.
    • Investors may focus on cash-flow-positive properties, especially those with low operating costs.

    Conclusion

    The SST increase from 6% to 8% might seem modest on paper, but its cascading effect across the property value chain is real. While residential property sales remain tax-exempt, associated services — from construction to maintenance — will become costlier. As developers adjust pricing and investors reassess risk, Malaysia’s property market may experience a short-term slowdown but could stabilize as the market adapts.


    Final Thought
    For both buyers and investors, 2024–2025 will require careful financial planning and a close eye on property pricing trends. Understanding the real costs behind the price tag is more important than ever.

    From The Desk of Miichael Yeoh