Tag: Malaysia property market 2026

  • Malaysia Property Market 2026: 33,094 Unsold Homes — Are They Really “For Sale” to Everyone?

    Malaysia Property Market 2026: 33,094 Unsold Homes — Are They Really “For Sale” to Everyone?

    33,094

    That is the number currently attracting attention in Malaysia’s property market.

    As at the first half of 2026, 33,094 completed residential units worth RM17.78 billion remained unsold.

    The figure is up from 30,471 units in the previous period.

    Naturally, the immediate question is:

    Why aren’t Malaysians buying these homes?

    The usual answers come quickly.

    Homes are too expensive.

    Buyers cannot afford them.

    Banks are rejecting loans.

    Developers are building too much.

    All of these factors may play a role.

    But I think we need to ask a more fundamental question:

    What does “unsold” actually mean?

    Because an unsold property is not necessarily a property that is simply sitting on the open market waiting for any Malaysian to buy it.

    And that distinction matters.


    The Unsold Property Paradox

    Let’s start with something that may surprise many people.

    Malaysia’s property market is still active.

    In the first half of 2026, the country recorded 187,320 property transactions worth RM105.12 billion.

    Residential property accounted for 110,998 transactions, representing 59.3% of total transactions and RM47.11 billion in transaction value.

    So this isn’t a story about Malaysians suddenly refusing to buy property.

    There are buyers.

    There are transactions.

    There is demand.

    Yet at the same time, tens of thousands of completed homes remain unsold.

    That is the paradox.

    People are buying property — but some completed properties are still not finding buyers.

    This tells us that the problem is more complicated than simply:

    “Malaysians cannot afford houses.”


    Not Every Unsold Unit Has the Same Problem

    This is where I believe we need to look at the property market differently.

    An “unsold” unit could be unsold for very different reasons.

    1. The buyer doesn’t want it.

    The location may not be attractive.

    The layout may not fit the target market.

    The facilities may not justify the price.

    The surrounding environment may not match what buyers want.


    2. The buyer wants it — but cannot get financing.

    This is a very real issue.

    The latest REHDA Property Industry Survey found that 59% of surveyed developers reported unsold completed residential units.

    Among the factors highlighted were end-financing rejection, property prices and unreleased Bumiputera units.

    The survey covered 181 REHDA members in Peninsular Malaysia.

    A buyer can therefore say:

    “I want this property.”

    But the bank may effectively say:

    “You cannot finance it.”

    Those are two completely different problems.

    3. Some units are not immediately available to the entire market

    This is another part of the conversation that deserves more attention.

    Some residential developments contain Bumiputera quota units.

    Where those units remain unsold, developers may need to go through the relevant state process before they can be released to the wider market.

    The rules are not identical across Malaysia.

    In Penang, for example, the state has a formal Bumiputera quota release process, including requirements relating to the physical progress of the development and evidence of marketing efforts to Bumiputera purchasers.

    So an important distinction needs to be made:

    A unit can be recorded as “unsold” without necessarily being immediately available to every buyer in the market.

    And depending on the state and applicable scheme, releasing such units can also involve specific conditions or financial contributions.

    This matters because we should be careful not to treat every unit in the RM17.78 billion figure as if it represents exactly the same market problem.


    4. The product may simply be wrong for today’s buyer

    This is probably one of the most overlooked questions in property development.

    A project may have been conceived several years ago.

    The developer may have studied:

    • population growth,
    • household formation,
    • income levels,
    • infrastructure,
    • competition,
    • buyer profiles,
    • pricing,
    • and future demand.

    Then the project goes through planning, approvals, construction and completion.

    By the time the keys are ready…

    The market may have changed.

    Buyers’ expectations change.

    Household sizes change.

    Working patterns change.

    Transport patterns change.

    Financing conditions change.

    Lifestyle preferences change.

    And competing developments enter the market.

    A product that looked attractive when the development was planned may not necessarily be equally attractive when it is completed.


    And this is where “affordable” becomes an interesting word

    The government has reported that properties priced RM300,000 and below accounted for 51.6% of residential transactions in H1 2026.

    At the same time, the government has acknowledged that completed unsold residential stock is not confined to high-end properties. It is also significant in affordable and mid-priced segments.

    So perhaps we need to distinguish between:

    Affordable by price

    and

    Affordable and desirable to the target buyer.

    They are not necessarily the same thing.

    A RM300,000 property may be affordable on paper.

    But if it is two hours from the buyer’s workplace…

    If public transport is poor…

    If the layout doesn’t suit the family…

    If the maintenance costs are too high…

    If financing is difficult…

    If the buyer doesn’t see future resale demand…

    Then the buyer may still decide:

    “This isn’t for me.”

    And that isn’t necessarily an affordability problem.

    It may be a product-market fit problem.


    This is where the PDS perspective comes in
    For years, much of the property industry has operated around a relatively simple sequence:

    Build → Market → Sell

    But perhaps we need to rethink the sequence.

    The PDS philosophy starts with a different question:

    Discover the buyer before you build for the buyer.

    Who exactly is the intended buyer?

    What problem are they trying to solve?

    Where do they want to live?

    What can they realistically afford?

    Can they obtain financing?

    What type of property fits their lifestyle?

    What compromises are they willing to make?

    What alternatives are available?

    What would make them choose this property over another?

    And perhaps most importantly:

    What evidence would give them confidence to make the decision?


    From “Selling Property” to “Helping Buyers Decide”

    This is a subtle but important shift.

    A traditional sales approach may ask:

    How do we sell this unit?

    A PDS approach asks:

    Why should this buyer choose this unit — and is it actually the right choice for them?

    That changes the conversation.

    Instead of starting with the brochure, we start with the buyer.

    Instead of starting with the promotion, we start with the problem.

    Instead of asking:

    “How much discount do we need to give?”

    we should also be asking:

    “Why isn’t the buyer convinced at the current value proposition?”

    Sometimes the answer may be price.

    Sometimes financing.

    Sometimes location.

    Sometimes product design.

    Sometimes timing.

    Sometimes competition.

    Sometimes eligibility.

    And sometimes the property simply isn’t solving a sufficiently important problem for the intended buyer.


    The Developer’s Question Should Change Too

    Perhaps developers should not only ask:

    “How many units can we sell?”

    They should ask:

    “How many units does this market actually need — and what type?”

    That means looking beyond headline demand.

    It means understanding:

    Demand

    → Who needs the property?

    Ability

    → Who can actually afford it?

    Eligibility

    → Who can legally or practically purchase it?

    Financing

    → Who can obtain the required loan?

    Location

    → Who wants to live there?

    Product

    → What configuration do they want?

    Value

    → Does the property justify the price?

    Confidence

    → What information does the buyer need before deciding?

    This is a much more complete view of property demand.


    The Real Property Overhang May Be an Alignment Problem
    Perhaps Malaysia doesn’t simply have a shortage of buyers.

    Perhaps we have a shortage of alignment.

    Alignment between:

    What developers build

    and

    what buyers actually want.

    Between:

    Price

    and

    purchasing power.

    Between:

    Location

    and

    daily life.

    Between:

    Product

    and

    lifestyle.

    Between:

    Eligibility

    and

    the available buyer pool.

    Between:

    financing

    and

    the buyer’s financial profile.

    And ultimately:

    what is being offered

    and

    what the buyer is prepared to decide on.


    So, What Should We Do About the 33,094?

    I don’t think the answer is simply:

    “Make property cheaper.”

    Nor is it simply:

    “Give buyers more incentives.”

    And it certainly isn’t enough to say:

    “Malaysians aren’t buying.”

    We need to understand why each segment of unsold stock remains unsold.

    Because the solution to a financing problem is different from the solution to a location problem.

    The solution to a Bumiputera quota-release issue is different from the solution to a product-market mismatch.

    And the solution to an overpriced property is different from the solution to a property that is fairly priced but poorly positioned.

    One number can hide many different problems.

    That is why we need to go beyond the headline.


    The PDS Way

    At the Property Discovery System, we believe property decisions should begin with discovery, not selling.

    For buyers:

    Discover the market.
    Understand the property.
    Test the numbers.
    Assess the risks.
    Compare the alternatives.
    Then decide.

    For developers:

    Discover the demand.
    Understand the buyer.
    Design the right product.
    Position it correctly.
    Build trust.
    Then sell.

    Because the objective shouldn’t simply be to sell more properties.

    It should be to create better alignment between property supply and real buyer demand.


    The question we should really be asking

    The headline today is:

    33,094 completed homes remain unsold.

    But perhaps the more important question is:

    Why are these particular homes still unsold?

    Until we answer that question at the unit, project, location, price, financing and buyer level, we risk treating very different problems as if they were the same problem.

    And if we keep treating the symptoms instead of understanding the buyer…

    We may simply build another 33,094 homes to replace them.

    Property is not just about selling a product.

    It is about helping people make better decisions.

    Discover Better. Decide Smarter.

    That is the PDS way.


    Sources &

    • National Property Information Centre (NAPIC), Property Market Report H1 2026. NAPIC — H1 2026 Property Market Report
    • Ministry of Finance Malaysia, launch remarks on the H1 2026 Property Market Report.
    • REHDA Property Industry Survey 1H2026, reported by EdgeProp.
    • Penang State Housing Board, Guidelines for Application for Release of Bumiputera Quota.
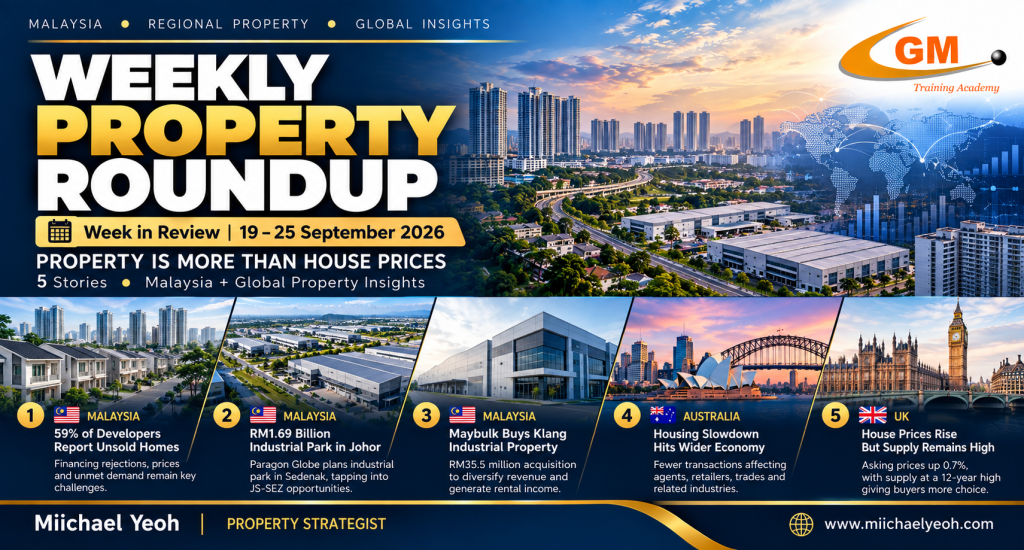
  • WEEKLY PROPERTY ROUNDUP

    WEEKLY PROPERTY ROUNDUP

    Week in Review | 19–25 September 2026

    Malaysia • Regional Property • Global Insights

    The property market is not one market. Different assets, locations and economic forces are moving in very different directions.


    🇲🇾 1. Almost 60% of Developers Report Unsold Completed Homes

    https://images.openai.com/static-rsc-4/uJ1sXQYW8YNgLMcTGhfcD4h9AlGny1gVvYl0-3Z_UUWwYtxe0L-njDRK6hbq_nQHxshYIf8luumPsz7hwaFkeeFnY-h9INrh1M3Wsc166NXJCu6itg6Pu3naU9MIZA6kT81KGWzDrYNL-2laiMsgo-gFVvv0qAxul-Ei9rdVdXRqEG6ZpH0OrMh_BYhREWGV?purpose=fullsize

    What Happened

    A new REHDA Property Industry Survey found that 59% of 181 developers surveyed had unsold completed residential units as at 30 June 2026.

    The three main reasons cited were rejected end-financing applications, property prices and unreleased Bumiputera units.

    During the survey period, 54 respondents launched 15,834 units and sold 5,260 units, giving a take-up rate of 33.2%, only slightly higher than 32.2% previously.

    REHDA also highlighted rising construction costs, financing constraints and regulatory/compliance costs as pressures on housing affordability. An average 13% increase in construction costs was reported between March and June.

    Why It Matters

    This is an important distinction:

    A home can be “affordable” on paper but still unaffordable to the buyer.

    If financing is rejected, margins are lower or credit requirements become more difficult, the advertised selling price isn’t the whole affordability equation.

    For developers, unsold completed stock also ties up capital.

    Miichael’s Review

    This is exactly why I believe buyers should look beyond the headline price.

    Before deciding whether a property is affordable, ask:

    Can I actually obtain the financing?
    What is my monthly commitment?
    What happens if interest rates or my income situation changes?

    For developers, the lesson is equally important:

    Product pricing must match real purchasing power — not just construction cost plus desired margin.

    Source: EdgeProp — REHDA survey on unsold homes and EdgeProp — REHDA on housing costs


    🇲🇾 2. Johor: Paragon Globe Plans RM1.69 Billion Industrial Park

    What Happened

    Paragon Globe is pursuing additional land in Sedenak, Johor, for a proposed industrial park with an estimated gross development value of RM1.69 billion.

    The project sits within the Kulai-Sedenak zone of the Johor-Singapore Special Economic Zone (JS-SEZ) and is planned to include industrial factories, commercial components and worker accommodation.

    The group is also taking a more strategic approach to land development, looking at anchor occupiers and the ecosystems that can form around them, rather than simply developing land in isolation.

    Why It Matters

    This is bigger than another industrial-property announcement.

    The interesting part is the “anchor occupier” strategy.

    A major manufacturer can create demand for:

    • suppliers
    • logistics
    • warehouses
    • worker accommodation
    • retail
    • supporting services

    That can turn an industrial site into an economic ecosystem.

    Miichael’s Review

    This is the kind of development strategy I find interesting.

    The best land doesn’t necessarily have the highest GDV.

    Sometimes the real question is:

    “What economic activity will this land create around itself?”

    That is a much more powerful way to assess long-term land value.

    Source: The Star — Paragon Globe eyes RM1.69bil industrial park; EdgeProp — Paragon Globe landbank strategy


    🇲🇾 3. Klang: Maybulk Moves Into Industrial Property

    What Happened

    Maybulk has proposed acquiring an 8,346 sq m freehold industrial property in Bandar Bukit Raja, Klang, for RM35.5 million.

    The property includes an industrial building, warehouse and office facilities.

    Importantly, Maybulk said the move is part of a strategy to diversify its revenue streams and reduce reliance on its existing shipping and storage businesses.

    The acquisition would also immediately provide rental income once completed.

    Why It Matters

    This is a smaller transaction than the headline billion-ringgit deals — but strategically, it is very interesting.

    We’re seeing a company from outside traditional property development use industrial real estate as an income-producing asset.

    That reflects the growing attractiveness of industrial property as an investment class.

    Miichael’s Review

    I always find these transactions worth watching because they show how corporate investors think about property differently from individual buyers.

    For a corporate investor, property can be:

    An operating asset + rental income + capital preservation + diversification.

    That is very different from buying a property simply because “the area is going up.”

    Source: The Star — Maybulk proposes RM35.5mil Klang industrial acquisition


    🌏 4. Australia: The Housing Slowdown Is Hitting More Than Property Agents

    https://images.openai.com/static-rsc-4/Brs6pRtz5kYYyfE4NHjlwNYzDeZsQhdHN8Ay_xpJgbljRtmXqHfXrQ0ZJ7iHrrLLQKWOe0izOsryIQPmdtGfKgsZshly6_Y3bJOYhnrsCRXXrUXpoyniGMpBU6UiTg5U1rpeUgc7Zw_F7zL8TwPXur-FNtdpsHx7XF08Uo8dO-6FZFqw6SGoo2PIJCj64MzF?purpose=fullsize

    What Happened

    Australia’s housing slowdown is now affecting a much wider economic ecosystem.

    Reuters reported that Australian home sales volumes have fallen sharply, with turnover 15% below a year earlier in July/August and 10.5% below the five-year average.

    Reuters estimates that the reduction in housing activity could remove around A$2.8 billion to A$5.6 billion of annual spending from businesses connected to property transactions — including removalists, conveyancers, furniture retailers, tradespeople and renovation businesses.

    The important point is that prices themselves have not collapsed: Reuters reported prices were less than 4% below the March peak and still above year-ago levels. The bigger issue is fewer transactions.

    Why It Matters

    This is a fascinating distinction:

    Property prices can remain relatively resilient while the property economy slows dramatically.

    If fewer people buy and sell, many businesses around the property ecosystem suffer.

    Miichael’s Review

    This is a useful lesson for Malaysia too.

    When we analyse a property market, we shouldn’t look only at:

    “Are prices rising?”

    We should also watch:

    transaction volume, financing, turnover, inventory and buyer confidence.

    A market can look healthy from a price chart while becoming much less active underneath.

    Source: Reuters — Australia’s housing slowdown and wider economic impact


    🌏 5. UK Housing: Prices Bounce, But Buyers Remain Selective

    https://images.openai.com/static-rsc-4/AEe5M10FcR-kJRCayCQU6MvkhNhkoA3_xw2GGp_f6LLLxiydkqrUYPQL63QZdaCxQoINy6jL0mpDitHMoiolKW5iBFZCF_fbHycfkm-eMLNzJIn4oybRTkZ_P3qO1zOmbgx6hiVX8Ce5o71Tg2Q2XS9ZjNv5XPC_Gl731cYvpOuShOgWgt_lYJuEbdKNQVeu?purpose=fullsize

    What Happened

    UK asking prices rose 0.7% in September, equivalent to about £2,441, according to Rightmove data reported by The Times.

    The average asking price reached approximately £367,440.

    But the headline increase needs context: prices remained 0.8% below a year earlier, while housing supply was reported to be at a 12-year high.

    Why It Matters

    More supply gives buyers more choice — and therefore more negotiating power.

    A seller cannot simply assume that a higher asking price will translate into a higher achieved price.

    Miichael’s Review

    This is one of my favourite property lessons:

    The asking price is not necessarily the market value.

    When supply rises and buyers become more selective, pricing strategy becomes increasingly important.

    For investors, this also reinforces the need to distinguish between:

    headline price movement and actual market liquidity.

    Source: The Times — UK house prices rise for first time since May


    📊 PROPERTY NUMBER OF THE WEEK

    59%

    The percentage of surveyed Malaysian developers reporting unsold completed residential units.

    But the more interesting number may be:

    33.2%

    The reported take-up rate during the REHDA survey period.

    The lesson: demand exists — but buyers are becoming increasingly constrained by financing, affordability and product suitability.


    👀 WORTH WATCHING

    🇲🇾 Malaysia

    1. Housing affordability
    Will financing accessibility improve enough to reduce completed unsold stock?

    2. Johor industrial property
    Watch how the JS-SEZ develops around actual occupiers and employment rather than simply land speculation.

    3. Klang industrial assets
    Will more corporates diversify into income-producing industrial property?

    🌏 International

    4. Australia
    Whether weak transaction volumes persist even if prices remain relatively resilient.

    5. UK
    Whether increased housing supply eventually translates into more realistic pricing.


    💡 MIICHAEL’S TAKEAWAY

    This week gives us five very different property stories.

    Housing affordability.
    Industrial land strategy.
    Corporate property investment.
    Australia’s transaction slowdown.
    UK supply and pricing.

    And that’s exactly why I don’t believe we should talk about “the property market” as though it is one single thing.

    Different sectors behave differently.

    Different locations behave differently.

    And most importantly, different buyers have different problems.

    For someone buying a home, financing and affordability may matter most.

    For an investor, rental income and liquidity may matter more.

    For a developer, land cost, product positioning and absorption may determine success.

    And for a corporate investor, property may simply be another asset class for diversification.

    So perhaps the better question isn’t:

    “Is property a good investment?”

    It is:

    “Which property, in which location, for what purpose — and under what market conditions?”

    That is where better property decisions begin.

    Miichael Yeoh

    Property Strategist